
 Hearing Loss Disease Treatment Market | 2026-2036
Hearing Loss Disease Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Hearing Loss Disease Treatment Market Intelligence
Pediatric audiology departments is bifurcating from general ENT practices as the primary volume channel for implantable solutions. Cochlear Limited anchors the cochlear implant segment through sustained R&D intensity in electrode array design. Sonova Holding AG dominates the premium hearing aid tier with extensive channel control across audiologist networks. GN Store Nord A/S differentiates through wireless connectivity platforms that integrate with consumer electronics ecosystems.
Hearing loss disease treatment encompasses pharmacological interventions, surgical implantation of neuroprosthetic devices, and programmable sound amplification systems calibrated to individual audiometric thresholds across frequencies from 250 Hz to 8 kHz. The primary commercial purpose is restoring functional auditory perception for sensorineural, conductive, and mixed pathologies. Hearing aids represent the mature volume base where margin pools shift toward rechargeable lithium-ion and AI-driven signal processing variants. Cochlear implants command premium positioning due to surgical infrastructure requirements and specialized follow-up protocols. Assistive listening devices gain traction in educational and occupational compliance settings where regulatory mandates for accessibility expand addressable need.
FDA premarket notification pathways and EU MDR conformity assessment shape product development cycles and market access timelines for manufacturers seeking multi-territory placement. The EPA and OSHA noise exposure standards indirectly expand the treatable population by mandating hearing conservation programs in industrial settings. Japan's PMDA and METI reimbursement frameworks determine pricing bands and adoption velocity for imported and domestic devices alike. Stakeholders must monitor evolving OTC hearing aid classification shifts and gene therapy pipeline milestones to recalibrate portfolio priorities and partnership strategies.
Market Dynamics
The Hearing Loss Disease Treatment Market is restructuring around rechargeable lithium-ion power systems and AI-driven signal processing architectures that compress replacement cycles and shift margin pools toward software-enabled service models.
Growth Catalysts
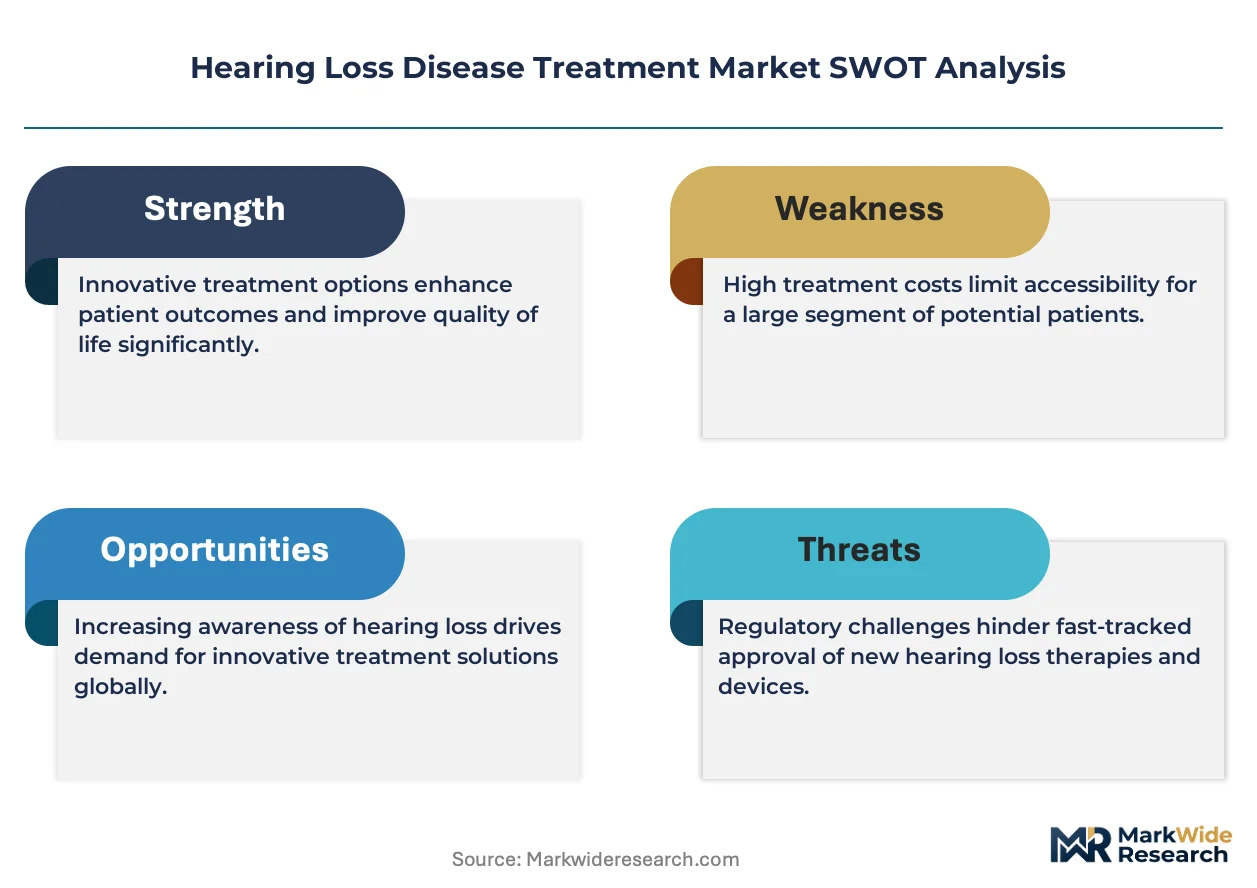
- OTC Hearing Aid Classification:The FDA's 2022 over-the-counter hearing aid final rule collapses prescription barriers for mild-to-moderate impairment, expanding addressable population through direct-to-consumer retail channels.
- Geriatric Care Network Expansion:Japan's METI reimbursement frameworks and Germany's statutory health insurance digitization mandate accelerate device procurement through integrated eldercare facilities.
- Gene Therapy Pipeline Maturation:Otoprotective biologics targeting synaptopathy and hair cell regeneration are advancing through Phase II trials, creating parallel treatment modality demand.
Market Restraints
- Electrode Array Manufacturing Concentration:Precision platinum-iridium wire drawing and silicone molding capabilities concentrate among three European suppliers, creating single-source vulnerability for cochlear implant producers.
- EU MDR Conformity Assessment Bottleneck:Extended notified body capacity constraints delay CE marking timelines by 8-14 months for novel implantable neuroprosthetics.
- Surgical Infrastructure Scarcity:Pediatric cochlear implantation requires fellowship-trained otolaryngologists concentrated in tertiary academic medical centers, limiting geographic penetration.
Strategic Opportunities
- India's PLI Scheme for Medical Devices:Production-linked incentives for domestic hearing aid manufacturing create localized supply base potential for export-oriented multinationals.
- Teleaudiology Service Integration:Remote programming and fitting protocols enabled by Bluetooth Low Energy connectivity expand rural and homebound patient access.
- Assistive Listening Device Mandates:OSHA hearing conservation program expansion and educational accessibility requirements under the Americans with Disabilities Act broaden institutional procurement volumes.
Industry Challenges
- Audiologist Training Pipeline Constraints:University-level AuD program enrollment lags device complexity growth, creating fitting and follow-up service bottlenecks.
- Cross-Platform Firmware Compatibility:Proprietary signal processing algorithms lock patients into manufacturer ecosystems, complicating upgrade pathways and second-device pairing.
- Battery Chemistry Certification Delays:UN 38.3 lithium-ion transport testing and IEC 62133 safety validation extend product launch timelines for rechargeable variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hearing Loss Disease Treatment Market |
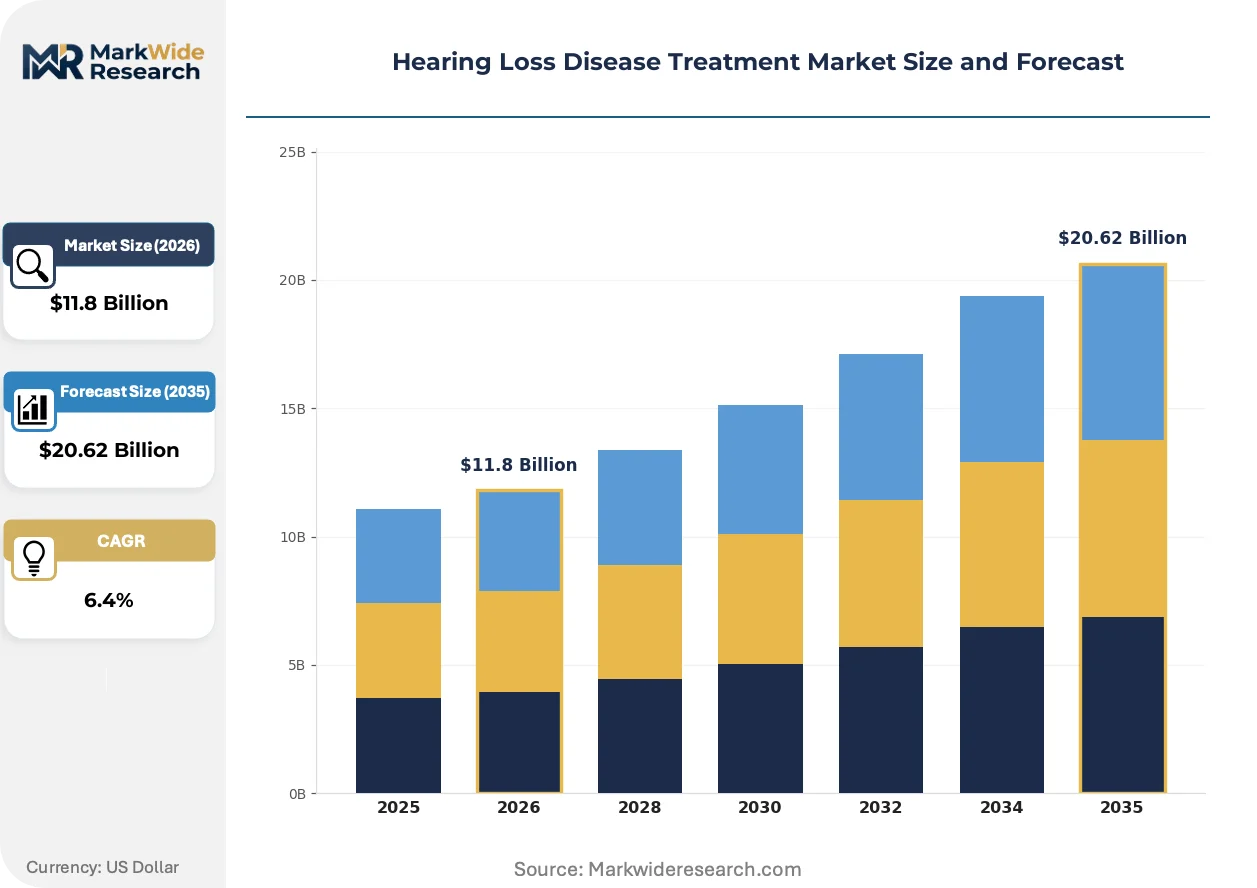
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $20.62 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hearing Aids, Cochlear Implants, Assistive Listening Devices, Bone Anchored Systems Application: Presbycusis, Noise-Induced Hearing Loss, Conductive Hearing Loss, Auditory Processing Disorder End User: Hospitals, Specialty Clinics, Home Care Settings, Rehabilitation Centers Technology: Digital, Analog, Wireless, Hybrid |
| Companies Covered | Sonova Holding AG, Cochlear Limited, GN Store Nord A/S, Demant A/S, WS Audiology A/S, Novartis AG, MED-EL Elektromedizinische Geräte GmbH, Sensorion, Starkey Laboratories Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hearing Loss Disease Treatment Market Strategic Shifts & Innovations
Deep learning architectures and edge-computing silicon are compressing the latency between acoustic capture and processed output, enabling real-time environmental classification that was previously confined to laboratory settings.
Deep neural network-based noise reduction is supplanting traditional directional microphone beamforming in premium hearing aid tiers. Audiologist networks in the United States and Germany are fitting these devices at replacement cycles shortened from five to three years. The technology is supplanting hardware-centric differentiation strategies with software-update monetization models that extend customer lifetime value.
EU MDR post-market surveillance requirements now mandate systematic implant registry data collection for cochlear devices, forcing manufacturers to rebuild quality management systems around real-world performance tracking. The regulation compresses product modification approval timelines and raises clinical evidence thresholds for design changes. Implantable neuroprosthetic segments face the steepest compliance cost escalation, with mid-tier manufacturers consolidating to share notified body audit burdens.
Direct-to-consumer online hearing tests and self-fitting applications are fragmenting the traditional audiologist-controlled distribution channel. Big-box retailers and consumer electronics chains in the United States are capturing mild-to-moderate impairment cases previously served by independent practices. This channel rotation is most visible in metropolitan markets where smartphone penetration and digital health literacy rates exceed national averages.
Hearing Loss Disease Treatment Market Segmentation
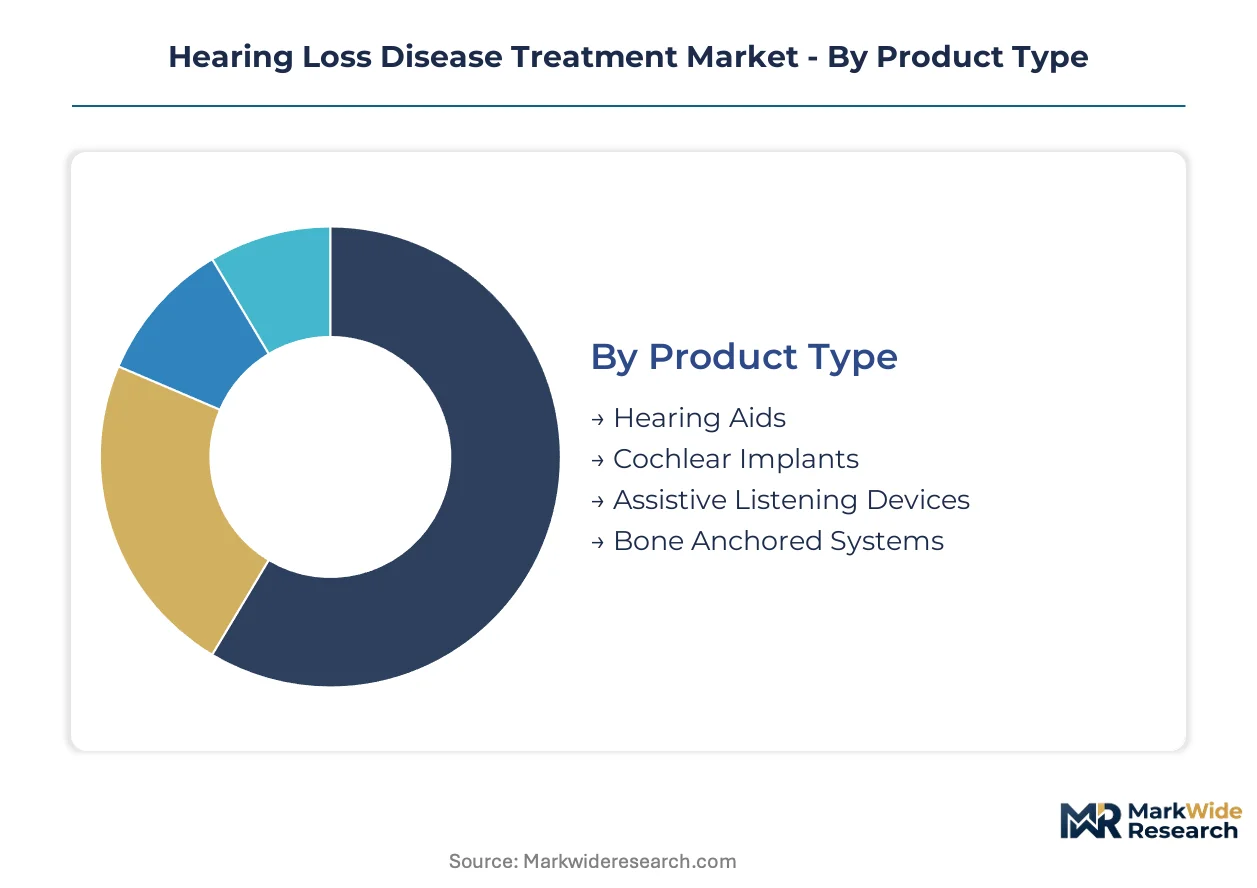
Segmentation in hearing loss treatment reveals how procurement authority, reimbursement pathways, and patient acuity determine which products flow through institutional versus retail channels. Manufacturers calibrate portfolio breadth and service intensity around these structural boundaries.
Product Type:
Hearing aids route predominantly through independent audiologist networks and direct-to-consumer retail following the FDA's OTC classification shift, while implantable systems remain captive to tertiary surgical centers with specialized fitting protocols.
- Hearing Aids:Programmable sound amplification systems calibrated to individual audiometric thresholds across frequencies from 250 Hz to 8 kHz. Demand concentrates in the United States and Germany where reimbursement frameworks favor advanced digital variants and replacement cycles compress from five to three years with AI-driven signal processing adoption.
- Cochlear Implants:Surgically implanted neuroprosthetic devices with electrode arrays that bypass damaged hair cells to directly stimulate the auditory nerve. Pediatric audiology departments in Japan's university hospitals and Germany's statutory health insurance networks drive procurement volumes for severe-to-profound sensorineural impairment.
- Assistive Listening Devices:FM systems and infrared transmitters deployed in educational and occupational compliance settings where OSHA hearing conservation programs and ADA accessibility mandates expand institutional procurement.
- Bone Anchored Systems:Osseointegrated implants for conductive or mixed hearing loss where conventional air-conduction aids provide limited benefit, fitted through ENT surgical units with craniofacial expertise.
Hearing aids dominate installed base. Cochlear implants are where expansion concentrates.
Application:
Cost tier alignment separates premium implantable solutions for congenital or traumatic pathologies from mass-market amplification for age-related decline, with reimbursement intensity scaling to impairment severity and intervention invasiveness.
- Presbycusis:Age-related sensorineural degeneration affecting high-frequency perception first. Germany's digitized statutory health insurance and Japan's METI eldercare frameworks accelerate device procurement through integrated geriatric networks.
- Noise-Induced Hearing Loss:Occupational and recreational acoustic trauma from sustained exposure above 85 dB. EPA and OSHA noise exposure standards indirectly expand treatable population through mandated hearing conservation programs in industrial settings.
- Conductive Hearing Loss:Mechanical disruption of sound transmission through external or middle ear structures. Bone anchored systems and surgical reconstruction compete with conventional amplification depending on anatomical feasibility and patient surgical candidacy.
- Auditory Processing Disorder:Central nervous system dysfunction in sound interpretation despite normal peripheral hearing thresholds. Assistive listening devices and FM systems in educational settings address classroom comprehension deficits where regulatory accessibility mandates apply.
Presbycusis commands the largest addressable population. Noise-induced hearing loss is climbing the fastest as occupational exposure litigation expands.
End User:
Customer type determines service intensity requirements, with surgical implantation demanding fellowship-trained otolaryngologist concentration that geographic penetration constraints limit.
- Hospitals:Tertiary academic medical centers with cochlear implantation programs, pediatric audiology departments, and neurotology fellowship training. Japan's university hospitals and US academic medical centers anchor surgical volume.
- Specialty Clinics:Independent audiology practices and ENT group practices controlling hearing aid fitting and follow-up protocols. Germany's statutory health insurance digitization mandate accelerates procurement through these channels.
- Home Care Settings:Direct-to-consumer and teleaudiology-enabled remote fitting for mild-to-moderate impairment following OTC classification shifts in the United States.
- Rehabilitation Centers:Post-implantation auditory training and speech therapy protocols, particularly for pediatric cochlear implant recipients requiring sustained habilitation support.
Specialty clinics capture the highest hearing aid volume. Home care settings are gaining share fastest as remote programming protocols mature.
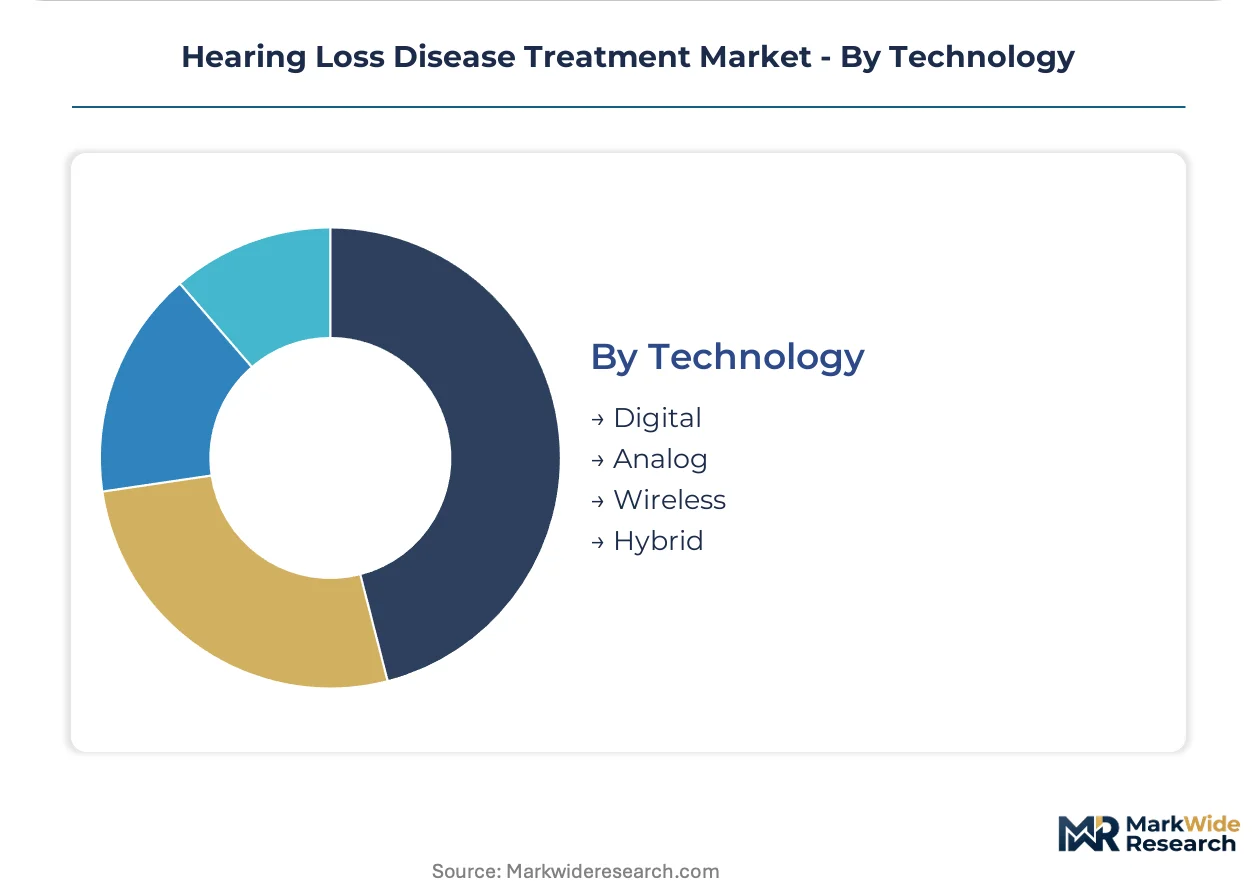
Technology:
Margin pools shift toward software-enabled architectures that compress hardware replacement cycles and enable subscription-based service monetization.
- Digital:DSP-based signal processing with multi-channel compression, noise reduction, and feedback cancellation algorithms. AI-driven environmental classification now supplants traditional directional microphone beamforming in premium tiers.
- Analog:Basic amplification with limited frequency shaping, confined to economy-tier markets and specific regulatory environments with delayed digital adoption.
- Wireless:Bluetooth Low Energy connectivity enabling direct streaming from consumer electronics and remote programming capabilities that expand rural and homebound patient access.
- Hybrid:Combined acoustic and electric stimulation for residual hearing preservation in cochlear implantation, requiring sophisticated electrode array design and surgical technique.
Digital technology dominates installed base. Wireless is where expansion concentrates as consumer electronics ecosystem integration becomes table stakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Rotterdam's pharmaceutical logistics corridors enable rapid distribution of implantable neuroprosthetics across Continental Europe, anchoring the region's procurement infrastructure for advanced auditory devices.
United States
Pediatric audiology departments at tertiary academic medical centers drive cochlear implant volumes. FDA breakthrough device designation accelerates product registration timelines for novel electrode array designs. The Boston-Cambridge corridor concentrates gene therapy research facilities targeting hair cell regeneration.
Germany
Statutory health insurance digitization mandates accelerate hearing aid procurement through integrated eldercare networks. EU MDR conformity assessment bottlenecks delay CE marking timelines for implantable systems. The Rhine-Ruhr metropolitan region hosts precision platinum-iridium wire drawing suppliers serving cochlear implant manufacturers.
Japan
METI reimbursement frameworks determine pricing bands for imported and domestic devices in university hospital networks. PMDA regulatory pathways shape adoption velocity for advanced digital hearing aids. Tokyo's Kanto region anchors pediatric cochlear implantation programs with fellowship-trained otolaryngologist concentration.
India
Production-linked incentive schemes for medical devices create localized supply base potential for export-oriented multinationals. BIS certification requirements and CDSCO regulatory pathways govern domestic manufacturing. Maharashtra's Pune-Ahmedabad industrial corridor attracts hearing aid component fabrication facilities.
United Kingdom
NHS England procurement frameworks determine volume allocation for programmable sound amplification systems. MHRA post-Brexit regulatory autonomy creates parallel conformity assessment requirements for EU-registered devices. London's Harley Street medical district concentrates private audiology practices serving premium-tier hearing aid fittings.
Hearing Loss Disease Treatment Market Key Industry Players
Concentration sits with diversified hearing technology conglomerates and specialized implant manufacturers that control electrode array design and audiologist channel networks. The market structure exhibits tiered consolidation where premium hearing aid tiers and implantable neuroprosthetics operate on distinct competitive axes. Three archetypes dominate: integrated hearing technology platforms, surgical implant specialists, and pharmaceutical-biotech hybrids pursuing otoprotective therapeutics. Capacity expansion in rechargeable lithium-ion architectures and strategic partnerships for teleaudiology service integration represent the dominant competitive moves reshaping positioning.
Among Swiss-based hearing technology platforms, Sonova Holding AG exemplifies the premium-tier device archetype through extensive channel control. Australian surgical implant specialists Cochlear Limited occupy the electrode array innovation vector. Danish wireless connectivity platforms find representation in GN Store Nord A/S, which exemplifies consumer electronics ecosystem integration strategies. These three anchors illustrate how geographic clustering around regulatory hubs and manufacturing competence centers shapes competitive differentiation.
| Leading Market Players |
|---|
| Sonova Holding AG |
| Cochlear Limited |
| GN Store Nord A/S |
| Demant A/S |
| WS Audiology A/S |
| Novartis AG |
| MED-EL Elektromedizinische Geräte GmbH |
| Sensorion |
| Starkey Laboratories Inc. |
| Others |
Cost & Logistics Intelligence
FDA breakthrough device designation and CE marking under EU MDR simultaneously gate supplier qualification and enable premium price positioning for electrode array manufacturers, compressing margin dispersion between certified and uncertified tiers while concentrating procurement authority among notified body-approved producers.
Pricing Analysis
Volume-discount tiering structures separate pediatric cochlear implant programs from adult hearing aid retail, with pricing stratifying across premium, standard, and economy tiers based on signal processing sophistication and after-sales bundling intensity. Price differentiation hinges on FDA breakthrough status and rechargeable lithium-ion certification grade, with premium tiers commanding substantial markups for AI-driven environmental classification. Cost compression in economy-tier hearing aids is intensifying because direct-to-consumer OTC channels bypass audiologist fitting fees. Institutional buyers at tertiary academic medical centers exhibit lowest price sensitivity, while independent audiology practices face margin pressure from big-box retail encroachment.
Supply Chain Analysis
Inventory lead times for precision platinum-iridium electrode arrays extend 8-14 months due to EU MDR conformity assessment bottlenecks, forcing cochlear implant manufacturers to hold strategic safety stock. Component fabrication concentrates in Germany, Switzerland, and Denmark, with silicone molding and wire drawing capabilities anchored in the Rhine-Ruhr metropolitan region. Raw material dependencies include medical-grade platinum-iridium alloys, lithium-ion cells for rechargeable variants, and specialized DSP silicon from Taiwan. Single-source vulnerability for electrode array substrates creates supply chain risk. Distribution runs through hospital procurement systems for implants and audiologist networks for hearing aids, with direct-to-consumer channels fragmenting traditional retail pathways.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive advantage in this market rests on scarce surgical infrastructure and specialized fitting expertise, with fellowship-trained otolaryngologist concentration limiting geographic penetration for implantable systems and creating defendable moats around tertiary academic medical centers.
For Market Incumbents: Secure exclusive supply agreements with precision platinum-iridium wire drawing specialists in Germany to lock in electrode array manufacturing capacity before EU MDR bottlenecks worsen. Fortify channel control through teleaudiology platform integration that embeds proprietary firmware ecosystems, raising switching costs against direct-to-consumer OTC entrants. Backward integration into rechargeable lithium-ion cell assembly reduces UN 38.3 transport testing exposure. For New Entrants and Emerging Players: Anchor in India's PLI scheme for medical devices to establish localized component fabrication for export-oriented supply base participation, bypassing European single-source vulnerabilities. Target home care settings with Bluetooth Low Energy-enabled self-fitting applications that exploit OTC classification shifts and remote programming protocol maturation. Pursue assistive listening device mandates under OSHA hearing conservation program expansion as the most penetrable institutional procurement channel. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across implantable neuroprosthetic segments due to EU MDR post-market surveillance compliance costs and systematic registry data collection requirements. Long-term viability over the projection horizon favors diversified hearing technology platforms with software-update monetization models over hardware-centric pure-plays. Acquisition target archetype: mid-tier manufacturers consolidating to share notified body audit burdens. Signal to watch: gene therapy pipeline Phase II trial readouts for otoprotective biologics targeting synaptopathy.| Strategic Initiative | Industry Significance |
|---|---|
| Teleaudiology Service Integration | Bluetooth Low Energy connectivity expands rural patient access beyond audiologist network density constraints. |
| Rechargeable Lithium-Ion Architecture | UN 38.3 certification and IEC 62133 validation compress replacement cycles toward software-enabled service models. |
| EU MDR Conformity Assessment Pathway | CE marking timelines determine market access velocity for novel electrode array designs across Continental Europe. |
| Pediatric Audiology Department Partnership | Tertiary academic medical center alliances anchor cochlear implant volume through fellowship-trained surgical concentration. |
| Gene Therapy Pipeline Positioning | Otoprotective biologics for hair cell regeneration create parallel treatment modality demand alongside device portfolios. |
Research Approach
Operator-level perspectives from cochlear implant surgeons, pediatric audiology department heads, biomedical engineers at tertiary hospitals, and GPO contracts managers anchored the qualitative base. Primary interviews with hearing aid manufacturers' regulatory affairs leads and independent audiologist practice owners combined with secondary validation from FDA 510(k) filings, EU MDR notified body documentation, CMS Medicare reimbursement databases, and hospital procurement contract repositories. Bottom-up installed base modeling and top-down epidemiological prevalence estimates triangulated volume projections.
Sensitivity analysis across the analysis window tested elasticity assumptions for OTC channel penetration rates, gene therapy pipeline maturation timelines, and EU MDR conformity assessment duration scenarios. Segmentation dimensions modeled include product type, application pathology, end-user setting, and technology architecture, with regional regulatory cluster effects layered across geographic markets. CAGRs derived from replacement cycle compression dynamics and reimbursement framework evolution. Industry-specific forecast inputs incorporated audiologist AuD program enrollment trajectories and lithium-ion battery chemistry certification pipeline status.
Decision-makers should treat outputs as directional under assumptions of sustained FDA OTC classification enforcement and stable METI reimbursement band structures; material deviation in either would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
ENT
Audiology Devices Market
ENT
Custom Hearing Aids Market
ENT
Global Sinusitis Treatment Market
ENT
Global Acute Otitis Media Treatment Market
ENT
Europe Speech Therapy Market
ENT
Global ENT Workstations Market
ENT
Nasal Sampling Lines Market
ENT
Over-The-Counter (OTC) Hearing Aids Market
ENT
Europe Hearing Aids Market
ENT
North America Hearing Aid Market
ENT
Surgical ENT Devices Market
ENT
Global Audiological Devices Market
ENT
Laryngeal Papillomatosis Treatment Market
ENT
Nasal Polyps Treatment Market
ENT
ENT Devices Market
ENT
US Hearing Aids Market