
 Pallet Labelling System Market | 2026-2036
Pallet Labelling System Market Size, Share, and Industry Trends Forecast 2026-2036
Pallet Labelling System Market Insights
Equipment leasing and managed print services are fragmenting the competitive landscape for pallet labelling systems, lowering capital barriers for mid-sized warehouses and third-party fulfillment operators. Zebra Technologies leverages its channel dominance in rugged mobile computing to bundle labelling hardware with enterprise software. SATO Holdings anchors its position through deep specialization in thermal transfer printheads and RFID inlay integration. Weber Marking Systems competes on geographic proximity, sustaining strong service density across Central European manufacturing corridors.
A pallet labelling system comprises automated print-and-apply stations, verification scanners, and enterprise software that encode GS1-compliant identifiers onto shipping units at throughput rates exceeding 120 pallets per hour. These systems enable real-time supply chain visibility by linking physical pallets to warehouse management systems through machine-readable symbologies. Thermal transfer printers occupy the mature core of the product mix, where replacement consumables generate recurring margin pools, while RFID technology represents the fastest-expanding technology segment as retailers mandate chip-based inbound receiving protocols. End user demand tilts toward logistics providers operating multi-tenant distribution networks, where standardised labelling protocols reduce cross-dock friction and accelerate order fulfillment cycle times.
GS1 standards, the EU Machinery Directive, and OSHA workplace safety regulations collectively shape equipment design, operator training requirements, and market access conditions for pallet labelling system vendors. ECHA restrictions on solvent-based inks under REACH are redirecting R&D investment toward water-based and UV-curable formulations. Stakeholders must monitor evolving interoperability mandates between national traceability databases and private fleet management platforms to anticipate compliance-driven replacement cycles.
Market Dynamics
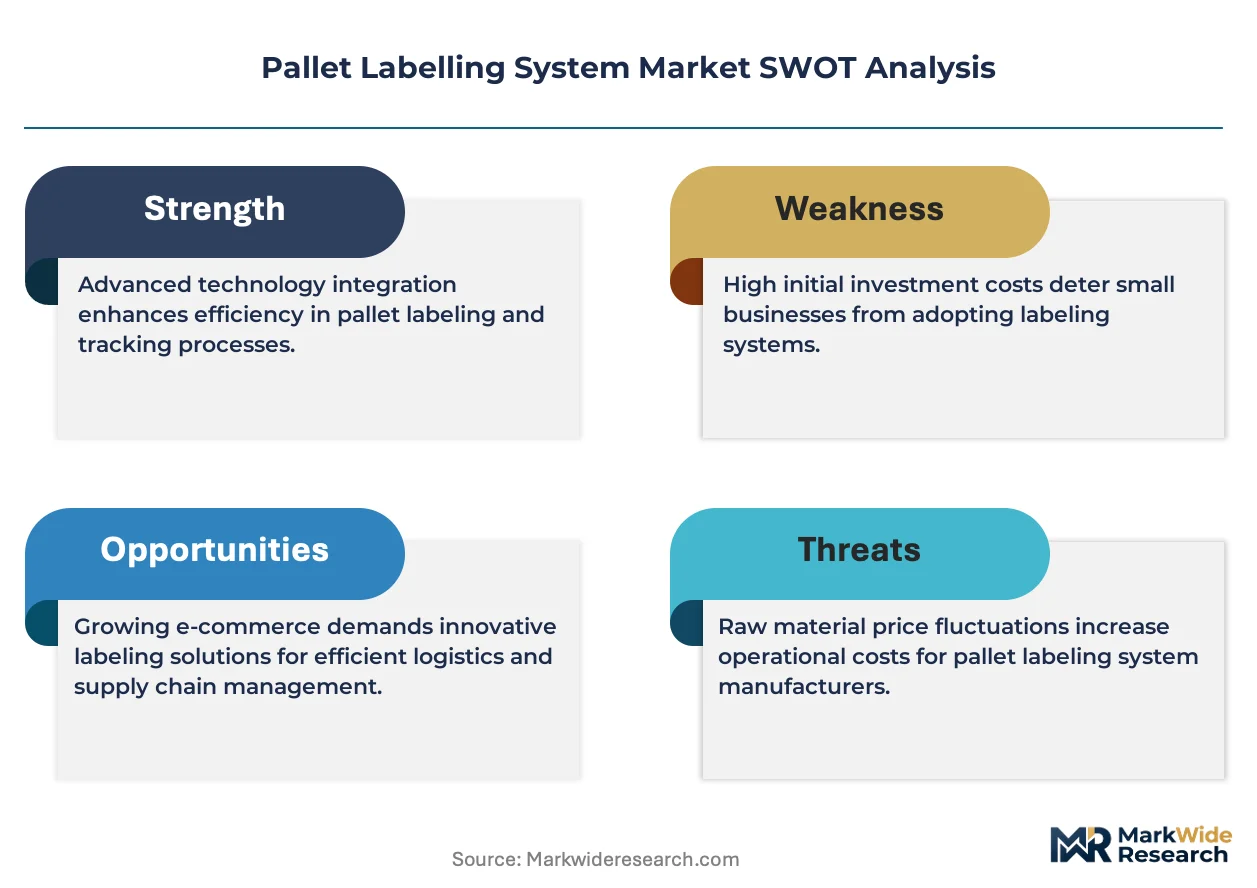
Automated pallet identification is compressing labor-dependent workflows across fulfillment networks, with RFID-enabled traceability emerging as the dominant architectural shift forcing hardware refresh cycles and software interoperability investments.
Growth Catalysts
- E-Commerce Fulfillment Density:Third-party logistics operators in Germany and the Netherlands are deploying high-throughput print-and-apply stations to meet same-day delivery SLAs. Warehouse automation budgets now prioritize pallet-level visibility as a prerequisite for cross-dock efficiency.
- F-Gas Regulation Compliance:The EU's phasedown of hydrofluorocarbon-based cooling in thermal transfer printers is accelerating equipment replacement toward solid-state heating elements. Manufacturers must certify new hardware designs before market access.
- GS1 Digital Link Adoption:Retailers including grocery and pharmaceutical chains are mandating 2D barcode formats that encode web-resolvable identifiers. This standardization reduces inbound receiving friction and enables dynamic product information updates.
Market Restraints
- Thermal Transfer Ribbon Supply Concentration:Wax-resin and full-resin ribbon production clusters in East Asia, exposing European system integrators to freight cost volatility and extended lead times for color-matched formulations.
- RFID Inlay Cost Structure:Passive UHF chip assembly remains concentrated among semiconductor packaging houses, limiting price compression for pallet-level tagging at high volumes.
- REACH Solvent Restrictions:ECHA limitations on toluene and xylene in ink formulations are forcing reformulation cycles that degrade print durability on corrugated substrates, creating warranty exposure for label applicator vendors.
Strategic Opportunities
- Pharmaceutical Cold Chain Expansion:Temperature-sensitive biologics distribution in Belgium and Switzerland is creating demand for RFID-enabled labels with integrated logging sensors. Regulatory serialization mandates in these markets require pallet-level aggregation records.
- Equipment-as-a-Service Models:Mid-sized German manufacturers are piloting subscription-based print-and-apply deployments that bundle maintenance, consumables, and software updates. This shifts capital expenditure to operational budgets and locks in multi-year vendor relationships.
- Water-Based Ink Convergence:UV-curable and water-based formulations are achieving abrasion resistance parity with solvent systems. Early adopters in Scandinavian markets are securing sustainability certifications that unlock preferential supplier status with retail consolidators.
Industry Challenges
- Multi-Protocol Integration Complexity:Warehouse management systems must simultaneously support legacy barcode symbologies, EPC Gen 2 RFID, and emerging GS1 Digital Link formats. Engineering teams face extended commissioning timelines when retrofitting existing material handling infrastructure.
- Field Service Technician Scarcity:Maintenance of high-speed applicator mechanisms requires mechatronics expertise combining pneumatic systems, precision motion control, and printhead calibration. Vocational training pipelines in Central Europe have not kept pace with deployment velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pallet Labelling System Market |
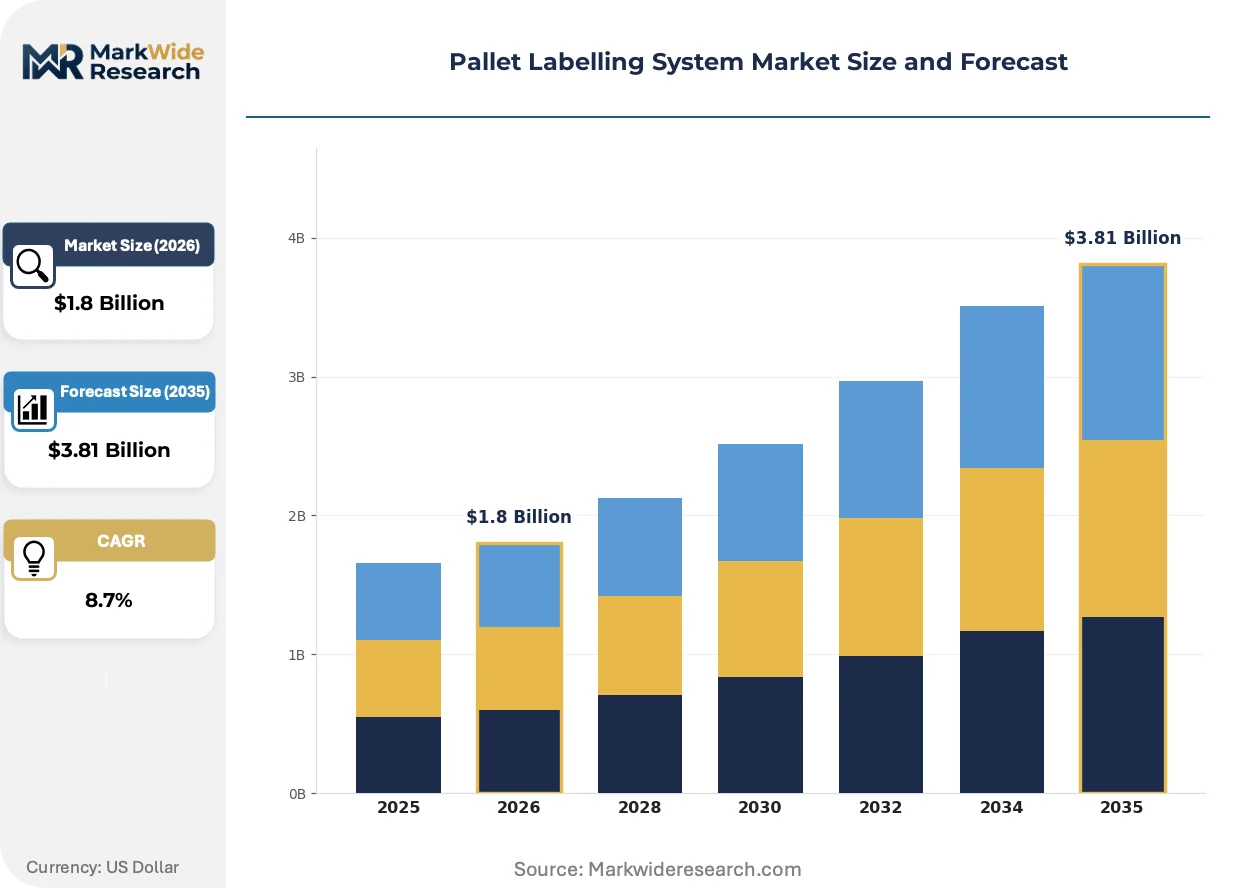
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Inkjet Printers, Thermal Transfer Printers, Laser Coders, Barcode Scanners Technology: RFID, NFC, QR Code, 2D Barcode, Optical Character Recognition Application: Warehouse Management, Inventory Tracking, Order Fulfillment, Supply Chain Monitoring End User Type: Logistics Providers, Manufacturing Plants, Retail Distribution Centers, Third-Party Fulfillment |
| Companies Covered | Avery Dennison, Zebra Technologies, SATO Holdings, Honeywell International, Markem-Imaje, Domino Printing Sciences, Weber Marking Systems, Mathews International, Diagraph, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pallet Labelling System Market Trends and Innovations
Print engine architectures are converging with industrial IoT platforms, creating real-time diagnostic capabilities that reshape service delivery models and hardware refresh cadences across automated distribution facilities.
Hybrid print-and-apply stations are hybridizing thermal transfer and direct thermal technologies within single chassis designs. Automotive parts distributors in Stuttgart and Wolfsburg are adopting these dual-mode systems to handle mixed pallet loads without changeover delays. This convergence is compressing capital deployment timelines by eliminating redundant line configurations.
REACH authorization requirements for chromium trioxide in corrosion-resistant coatings are forcing hardware manufacturers toward ceramic and plasma-deposited alternatives. The industrial consequence extends equipment lead times by eight to fourteen weeks as new surface treatments undergo qualification testing. German machine builders are responding by pre-certifying component suppliers to maintain delivery commitments.
Consolidated procurement of labelling consumables is displacing decentralized purchasing across multi-site logistics networks. Third-party fulfillment operators in Rotterdam and Hamburg are centralizing ribbon and label stock contracts to secure volume-tier pricing and standardize quality specifications. This concentration is most visible in pharmaceutical distribution, where batch traceability requirements favor single-source supply relationships.
Pallet Labelling System Market Segmentation
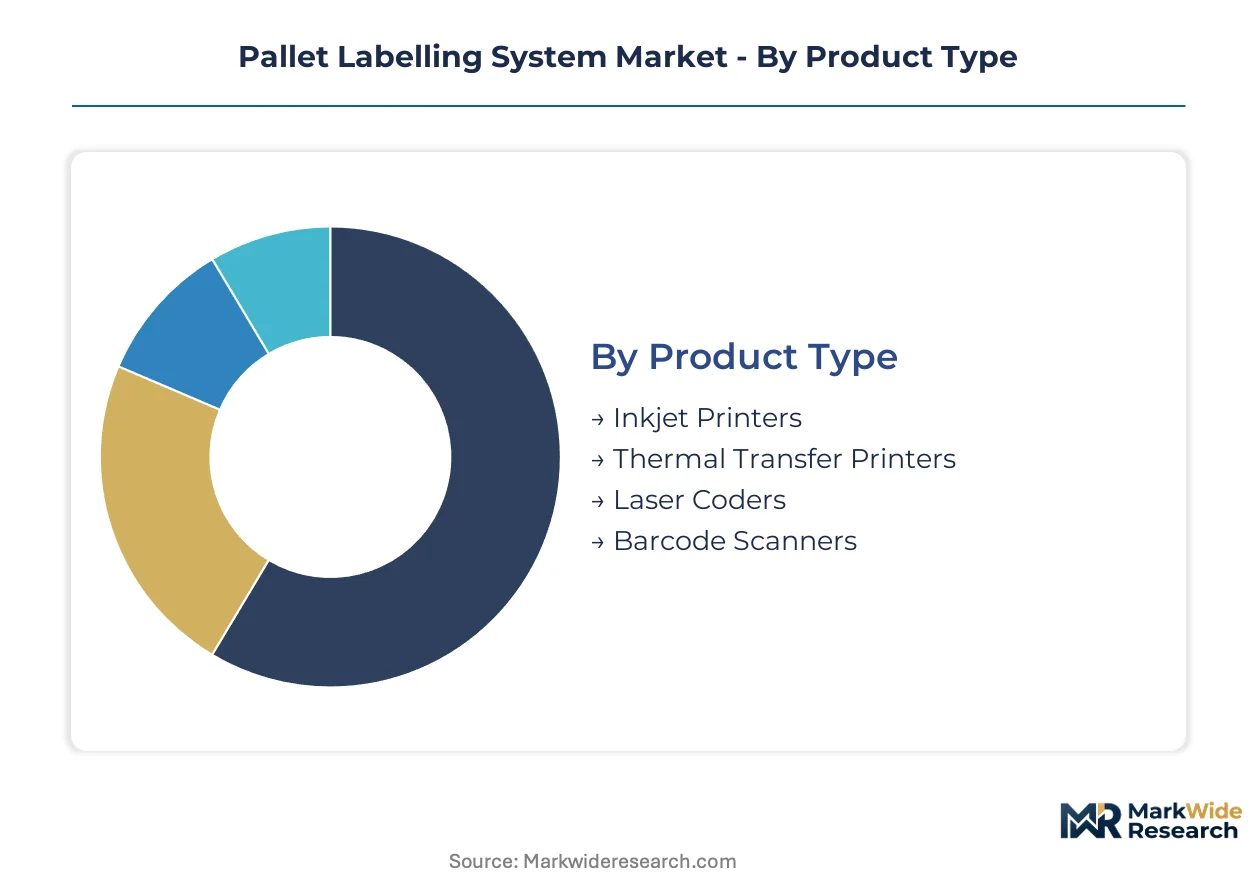
Pallet labelling system segmentation reveals distinct technology maturity curves and application-specific performance requirements. Equipment buyers prioritize throughput reliability, regulatory compliance, and integration depth with existing warehouse management infrastructure.
Product Type:
Thermal transfer technology occupies the mature core of the product portfolio, while inkjet and laser systems represent emerging alternatives with distinct total-cost-of-ownership profiles.
- Thermal Transfer Printers:Wax-resin and full-resin ribbon systems deliver abrasion-resistant labels at 120+ pallets per hour in high-throughput German automotive distribution centers. Replacement consumables generate recurring revenue streams that sustain vendor margins across multi-year deployment cycles.
- Inkjet Printers:Piezoelectric drop-on-demand systems enable variable data printing without consumable ribbons, attracting pharmaceutical serialization mandates in Belgium and Switzerland where lot-code flexibility reduces changeover downtime.
- Laser Coders:CO2 and fiber laser systems etch permanent marks directly onto pallet surfaces, eliminating label substrate costs for closed-loop container pools in Scandinavian retail networks.
- Barcode Scanners:Linear imager and area-array verification stations confirm GS1-compliant symbology readability before pallet release from print-and-apply stations.
Thermal transfer printers retain volume leadership; laser coders hold the steepest expansion curve among non-contact marking alternatives.
Technology:
Identification protocols span optical machine-readable formats and radio-frequency data carriers, each imposing distinct infrastructure requirements on warehouse operators.
- RFID:Passive UHF inlays enable bulk reading of palletized goods without line-of-sight positioning, satisfying retailer inbound receiving mandates in Rotterdam and Hamburg distribution corridors. Chip assembly concentration among semiconductor packagers limits near-term price compression at pallet-level volumes.
- 2D Barcode:Data Matrix and QR formats encode web-resolvable GS1 Digital Link identifiers, bridging physical pallets to dynamic product information portals demanded by grocery and pharmaceutical retail chains.
- QR Code:Consumer-facing square matrix symbologies extend traceability visibility beyond supply chain operators to end-customer verification applications.
- NFC:Near-field communication tags support tap-to-read authentication for high-value pharmaceutical and luxury goods pallets requiring anti-counterfeiting verification.
- Optical Character Recognition:Vision-based alphanumeric reading supplements barcode decoding for legacy pallet markings and damaged label recovery scenarios.
2D barcode deployments dominate current installation bases; RFID-enabled traceability is gaining share fastest as retail consolidation mandates chip-based receiving protocols.
Application:
Functional use cases align with discrete workflow stages across automated distribution facilities, each demanding specific print speed and verification reliability thresholds.
- Order Fulfillment:Print-and-apply stations encode customer-specific routing information at cross-dock velocity, enabling same-day delivery SLAs for third-party logistics operators in the Netherlands.
- Warehouse Management:Pallet-level identifiers synchronize physical inventory positions with WMS location records, reducing put-away errors in multi-tenant German distribution hubs.
- Supply Chain Monitoring:Aggregation records link individual cases to pallet identifiers, supporting regulatory serialization track-and-trace requirements for temperature-sensitive biologics.
- Inventory Tracking:Cycle-count verification through handheld or fixed-position scanners maintains stock accuracy between physical audits.
Order fulfillment applications command the largest equipment procurement budgets; supply chain monitoring exhibits the most rapid technology refresh cycles driven by regulatory mandates.
End User Type:
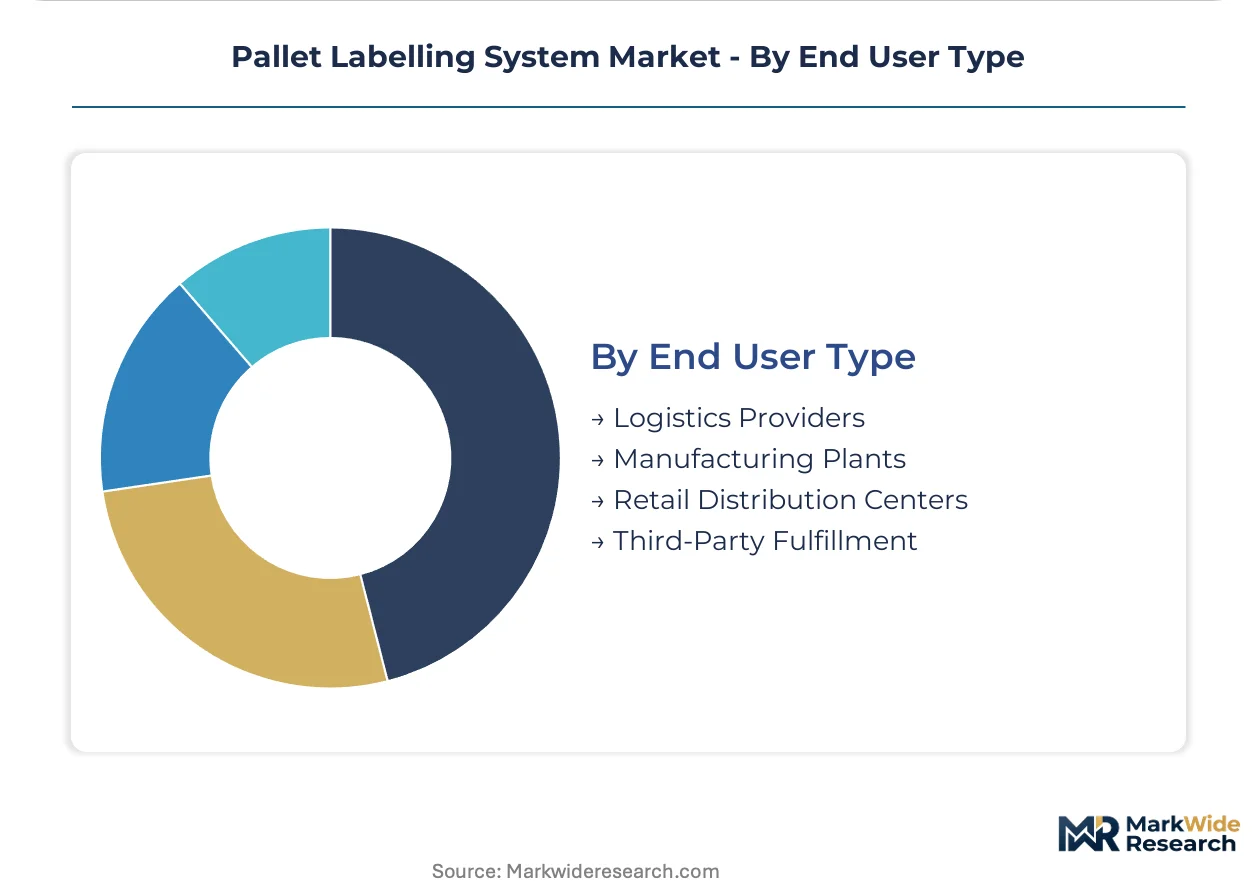
Buyer sophistication and capital deployment scale vary sharply across operational contexts, from asset-light fulfillment specialists to vertically integrated manufacturing networks.
- Logistics Providers:DHL, Kuehne+Nagel, and comparable operators standardize labelling protocols across multi-tenant networks to minimize cross-dock friction, centralizing ribbon and label procurement for volume-tier pricing.
- Third-Party Fulfillment:E-commerce specialist warehouses in Rotterdam and Hamburg prioritize rapid deployment of subscription-based print-and-apply services that convert capital expenditure to operational budgets.
- Manufacturing Plants:Automotive and pharmaceutical production facilities require pallet-level aggregation records linking finished goods to component batch traceability.
- Retail Distribution Centers:Grocery and mass-merchant consolidation hubs mandate inbound receiving compatibility with downstream store delivery requirements.
Logistics providers represent the deepest installed base; third-party fulfillment operators are expanding equipment demand most aggressively through as-a-service consumption models.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-oriented manufacturing economies generate disproportionate equipment demand as inbound raw material tracking and outbound finished goods compliance converge on standardized pallet identification protocols. Import-dependent distribution hubs in Northern Europe and East Asia are accelerating deployment of automated print-and-apply stations to compress customs clearance cycles and reduce demurrage exposure at container terminals.
Germany
Automotive logistics corridors in Stuttgart and Wolfsburg drive high-throughput thermal transfer installations exceeding 120 pallets per hour. The EU Machinery Directive and F-Gas Regulation mandate equipment recertification cycles that compress hardware replacement timelines. Bavarian pharmaceutical distribution centers in Munich are deploying RFID-enabled traceability systems to satisfy serialization mandates for temperature-sensitive biologics exports.
United States
Third-party fulfillment operators in Chicago and Dallas-Fort Worth are centralizing ribbon and label procurement across multi-site networks to secure volume-tier pricing. OSHA workplace safety regulations govern operator training requirements for high-speed applicator mechanisms. West Coast port logistics clusters in Los Angeles and Long Beach are retrofitting existing material handling infrastructure to support GS1 Digital Link 2D barcode formats for retail inbound receiving compatibility.
China
E-commerce fulfillment density in the Yangtze River Delta is forcing warehouse automation budgets toward pallet-level visibility as a prerequisite for same-day delivery service level agreements. GB standards and MIIT interoperability mandates shape equipment design for domestic traceability databases. Shenzhen-based system integrators are piloting hybrid thermal transfer and direct thermal architectures to handle mixed pallet loads without changeover delays.
Netherlands
Rotterdam and Hamburg distribution corridors standardize labelling protocols across multi-tenant logistics networks to minimize cross-dock friction and accelerate order fulfillment cycle times. REACH solvent restrictions on toluene and xylene in ink formulations are redirecting R&D investment toward water-based and UV-curable alternatives. Dutch pharmaceutical cold chain operators are adopting RFID-enabled labels with integrated temperature logging sensors for regulatory serialization compliance.
Japan
Precision manufacturing supply chains in the Nagoya-Chubu corridor require pallet-level aggregation records linking finished automotive components to batch traceability systems. METI industrial standards and JIS certification requirements create equipment qualification barriers for foreign vendors. Tokyo-area retail consolidation hubs are mandating chip-based inbound receiving protocols that accelerate RFID adoption fastest among non-contact identification technologies.
Pallet Labelling System Market Competitive Landscape
On the supply side, the industry is consolidating around equipment manufacturers with captive consumables businesses and enterprise software integration capabilities. The vendor base stratifies into three tiers: diversified industrial technology conglomerates with broad identification portfolios, specialized labelling equipment fabricators with deep thermal transfer expertise, and regional system integrators with dense service networks. Dominant competitive moves include strategic partnerships between hardware vendors and warehouse management software providers, plus geographic expansion through distributor channel development in underpenetrated logistics corridors.
Within the diversified technology tier, Zebra Technologies and Honeywell International exemplify players leveraging channel dominance in rugged mobile computing to bundle labelling hardware with enterprise software platforms. SATO Holdings occupies a specialist position anchored in thermal transfer printhead engineering and RFID inlay integration. These three companies represent distinct strategic archetypes: Zebra Technologies and Honeywell International sit within the scale-driven conglomerate segment, while SATO Holdings exemplifies deep vertical specialization in consumables and identification substrates.
| Leading Market Players |
|---|
| Avery Dennison |
| Zebra Technologies |
| SATO Holdings |
| Honeywell International |
| Markem-Imaje |
| Domino Printing Sciences |
| Weber Marking Systems |
| Mathews International |
| Diagraph |
| Others |
Pricing and Supply Chain Analysis
Thermal transfer ribbon supply concentration in East Asia determines both pricing tier spreads and supply chain shape, compressing margins for European system integrators while forcing procurement centralization among multi-site logistics operators seeking volume-tier insulation from freight cost volatility.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels, with differentiation driven by throughput certification and after-sales service bundling. Cost compression in the economy tier is intensifying because REACH-compliant ink reformulations degrade print durability on corrugated substrates, creating warranty exposure. Third-party fulfillment operators exhibit highest price sensitivity due to asset-light operating models, while pharmaceutical cold chain distributors accept premium positioning for integrated sensor-enabled traceability.
Supply Chain Analysis
Upstream wax-resin and full-resin ribbon feedstock production clusters in Japan, South Korea, and Taiwan, with passive UHF chip assembly for RFID inlays drawing from semiconductor packaging houses in the same corridor. Single-source vulnerability in color-matched ribbon formulations exposes European integrators to extended lead times. Distribution runs through centralized procurement contracts at Rotterdam and Hamburg logistics hubs, displacing decentralized purchasing across multi-tenant networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
GS1 Digital Link interoperability mandates are transforming pallet identification into a platform-economics inflection, where hardware vendors must embed web-resolvable identifier capabilities or face displacement by software-native competitors.
For Market Incumbents: Harden defensible positions through captive consumables businesses and enterprise software integration capabilities. Deepen thermal transfer printhead specialization to resist substitution by inkjet alternatives in pharmaceutical serialization. Prioritize pre-certification of component suppliers under EU Machinery Directive and F-Gas Regulation recertification cycles to compress equipment lead times.
For New Entrants and Emerging Players: Pursue equipment-as-a-service deployment models targeting mid-sized German manufacturers piloting subscription-based print-and-apply systems. Scandinavian markets offer penetrable white space for water-based and UV-curable ink formulations achieving sustainability certifications. Lead with interoperability consulting to reduce multi-protocol integration complexity during WMS retrofit commissioning.
For Investors and Strategic Acquirers: ECHA solvent restrictions under REACH reshape the acquisition landscape toward vendors with qualified water-based ink formulations. Long-term viability centers on RFID-enabled traceability capabilities as retail consolidation mandates chip-based receiving protocols. Watch for field service technician scarcity forcing consolidation among regional system integrators with dense Central European service networks.
| Strategic Initiative | Industry Significance |
|---|---|
| RFID Inlay Integration Partnership | Passive UHF chip sourcing agreements with semiconductor packagers lock in pallet-level tagging supply for pharmaceutical cold chain expansion. |
| Water-Based Ink Formulation Certification | REACH-compliant alternatives achieving abrasion resistance parity unlock preferential supplier status with Scandinavian retail consolidators. |
| Equipment-as-a-Service Platform Launch | Subscription-based print-and-apply deployments convert capital expenditure to operational budgets for mid-sized German manufacturers. |
| GS1 Digital Link Software Companion | Web-resolvable identifier encoding bridges physical pallets to dynamic product information portals demanded by grocery retail chains. |
| Central European Service Network Expansion | Dense technician coverage addresses mechatronics expertise scarcity in high-speed applicator maintenance across Stuttgart and Wolfsburg corridors. |
Research Methodology
Initial hypotheses were tested against primary input from warehouse automation directors, thermal transfer printhead engineers, pharmaceutical serialization compliance officers, and third-party logistics procurement leads and refined through secondary validation against customs trade data, ECHA REACH authorization filings, SEC equipment manufacturer disclosures, and GS1 standards documentation. Bottom-up equipment shipment tallies were triangulated against top-down warehouse automation budget surveys across the analysis window.
Demand-supply balance modeling segmented volume and value outputs by print technology maturity, identification protocol adoption curve, application workflow stage, and end-user capital deployment scale throughout the forecast period. CAGRs were derived from equipment replacement cycle compression under F-Gas Regulation phasedown timelines and RFID mandate propagation through retail consolidation networks. Industry-specific inputs included thermal transfer ribbon consumption rates per pallet hour and pharmaceutical serialization aggregation record requirements.
Sensitivities concentrate around REACH solvent restriction enforcement timelines and semiconductor packaging capacity allocation for passive UHF inlays. Forecasts reflect assumptions regarding GS1 Digital Link retailer mandate adoption velocity and mechatronics technician training pipeline expansion in Central Europe. Cross-checking against ECHA pre-registration volumes and EU customs equipment import declarations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Pallets Packaging
Pallet Packaging Market
Pallets Packaging
Disposable Plastic Pallet Market
Pallets Packaging
China Pallets Market
Pallets Packaging
Canada Pallets Market
Pallets Packaging
Pallet Collar Market
Pallets Packaging
North America Lumber Pallet Market
Pallets Packaging
Pallet Corner Boards Market
Pallets Packaging
Pallet Displays Market
Pallets Packaging
Pallet Wrappers Market
Pallets Packaging
India Pallets Market
Pallets Packaging
Stringer Pallets Market
Pallets Packaging
Foldable Plastic Pallet Boxes Market
Pallets Packaging
Wire Cage Pallet Collar Market
Pallets Packaging
Pallet Slip Sheets Market
Pallets Packaging
Pallet Boxes Market
Pallets Packaging
Pallet Labeler Market