
 Fiber Optic Labels Market | 2026-2036
Fiber Optic Labels Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber Optic Labels Market Foresight
Polypropylene is broadening its addressable share in fiber optic labels as converters substitute away from legacy vinyl formulations to meet halogen-free mandates. Brady Corporation leverages in-house thermal transfer printing expertise to sustain premium positioning in data center applications. Panduit Corporation anchors its portfolio through integrated cable management systems that bundle labels with physical pathway hardware.
Fiber optic labels are pressure-sensitive identification tags engineered to withstand temperatures from minus forty to plus one hundred fifty degrees Celsius while maintaining legibility under abrasion and chemical exposure; they serve primarily to trace individual strands within dense cable bundles across telecommunications and computing infrastructure. Patch cord labels command the largest volume share due to universal deployment in structured cabling, while ribbon labels represent the fastest-expanding category as multi-fiber push-on connectors proliferate in hyperscale environments. Adhesive labels carry the weakest margin pool because commodity-grade polyester substrates face pricing pressure from unbranded Asian suppliers.
The EPA regulates perfluorinated compounds in adhesive coatings, while TIA-606 standards mandate uniform labeling schemes for telecommunications infrastructure in the United States. CE marking under the EU Construction Products Regulation governs flame propagation characteristics for labels installed in European public networks. Stakeholders must monitor evolving halogen-free material certifications and pre-printed serialization capabilities as fiber density per rack unit continues to escalate.
Market Dynamics
Hyperscale data center buildouts are compressing fiber density per rack unit, forcing identification systems to manage 10,000-plus strand counts within constrained physical footprints while maintaining traceability across complex cable hierarchies.
Growth Catalysts
- Multi-fiber push-on (MPO) connector proliferation:Ribbon label formats capture accelerating demand as 8-fiber and 16-fiber MPO configurations replace discrete patch cords in cloud computing facilities.
- REACH and RoHS mandates:European halogen-free substrate requirements are accelerating converter migration from legacy vinyl to polypropylene formulations.
- United States hyperscale concentration:Serialized cable identification procurement at scale concentrates in Virginia, Texas, and Oregon data center clusters.
Market Restraints
- Commodity polyester pricing pressure:Unbranded Asian suppliers erode margins on adhesive label substrates through volume-based cost undercutting.
- Fluorinated compound regulation:EPA restrictions on perfluorinated adhesive coatings constrain formulation flexibility and extend qualification timelines.
- Legacy vinyl substitution costs:Converters face capital expenditure burdens retooling thermal transfer lines for halogen-free polypropylene processing.
Strategic Opportunities
- India data center expansion:Greenfield cloud infrastructure under the country's PLI scheme creates first-mover positioning for serialized identification systems.
- Pre-printed serialization services:Value-added printing capabilities bypass buyer in-house thermal transfer investments while capturing recurring revenue streams.
- Integrated cable management bundling:Label-to-pathway hardware packaging addresses procurement consolidation trends among facility operators.
Industry Challenges
- TIA-606 compliance complexity:Uniform labeling scheme enforcement across multi-vendor installations demands cross-functional coordination between contractors and facility managers.
- Temperature-rated adhesive qualification:Minus forty to plus one hundred fifty degrees Celsius performance validation extends product development cycles and testing expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber Optic Labels Market |
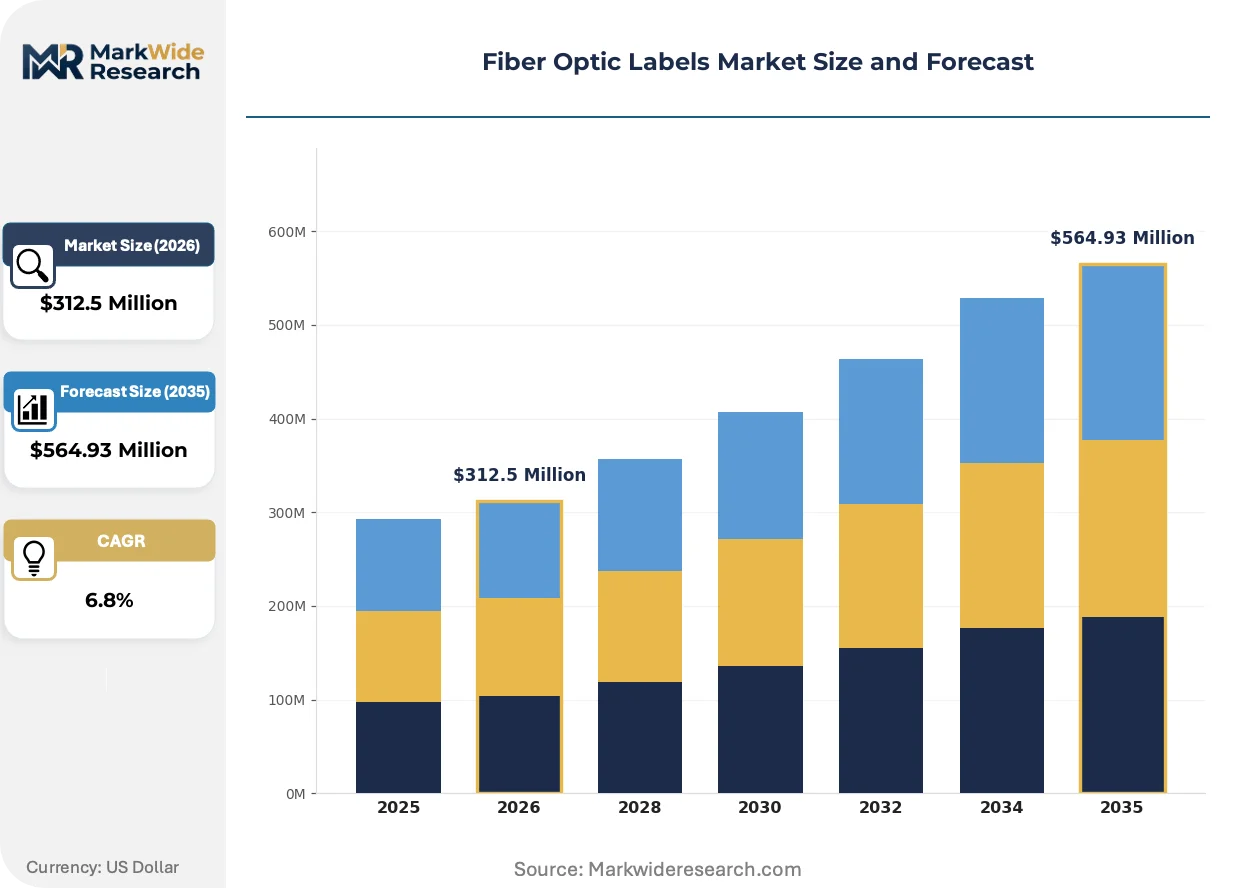
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $564.93 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ribbon Labels, Pigtail Labels, Patch Cord Labels, Adhesive Labels Material: Polyester, Nylon, Vinyl, Polypropylene Application: Data Centers, Telecommunication Networks, Medical Devices, Industrial Automation End User: Telecom Providers, System Integrators, IT Departments, Facility Managers |
| Companies Covered | 3M Company, Brady Corporation, Panduit Corporation, HellermannTyton Group PLC, Avery Dennison Corporation, TE Connectivity Ltd., Sumitomo Electric Lightwave Corporation, Fujikura Ltd., Leviton Manufacturing Co., Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber Optic Labels Market Shifts & Advancements
Laser-etched serialization and automated cable identification systems are compressing manual traceability workflows. Material science advances in halogen-free substrates intersect with procurement model evolution toward pre-printed service contracts.
RFID-embedded fiber optic labels is automating inventory reconciliation and fault isolation in dense cable environments. Hyperscale operators in the United States are deploying these tags at rack-scale density. The technology is automating what previously required technician-led visual inspection, compressing mean-time-to-repair metrics.
REACH substance restriction amendments are tightening halogen-free certification requirements for substrates entering European public networks. Converter qualification costs are rising as ECHA documentation burdens expand. Ribbon label categories face the steepest compliance escalation given their deployment in mission-critical telecommunications infrastructure.
Buyer consolidation toward integrated procurement platforms is disintermediating traditional distributor channels. Large facility operators now contract directly with label converters for serialized pre-printed volumes. This pattern concentrates most visibly in United States hyperscale markets where procurement standardization across multi-site portfolios reduces vendor management overhead.
Fiber Optic Labels Market Segmentation
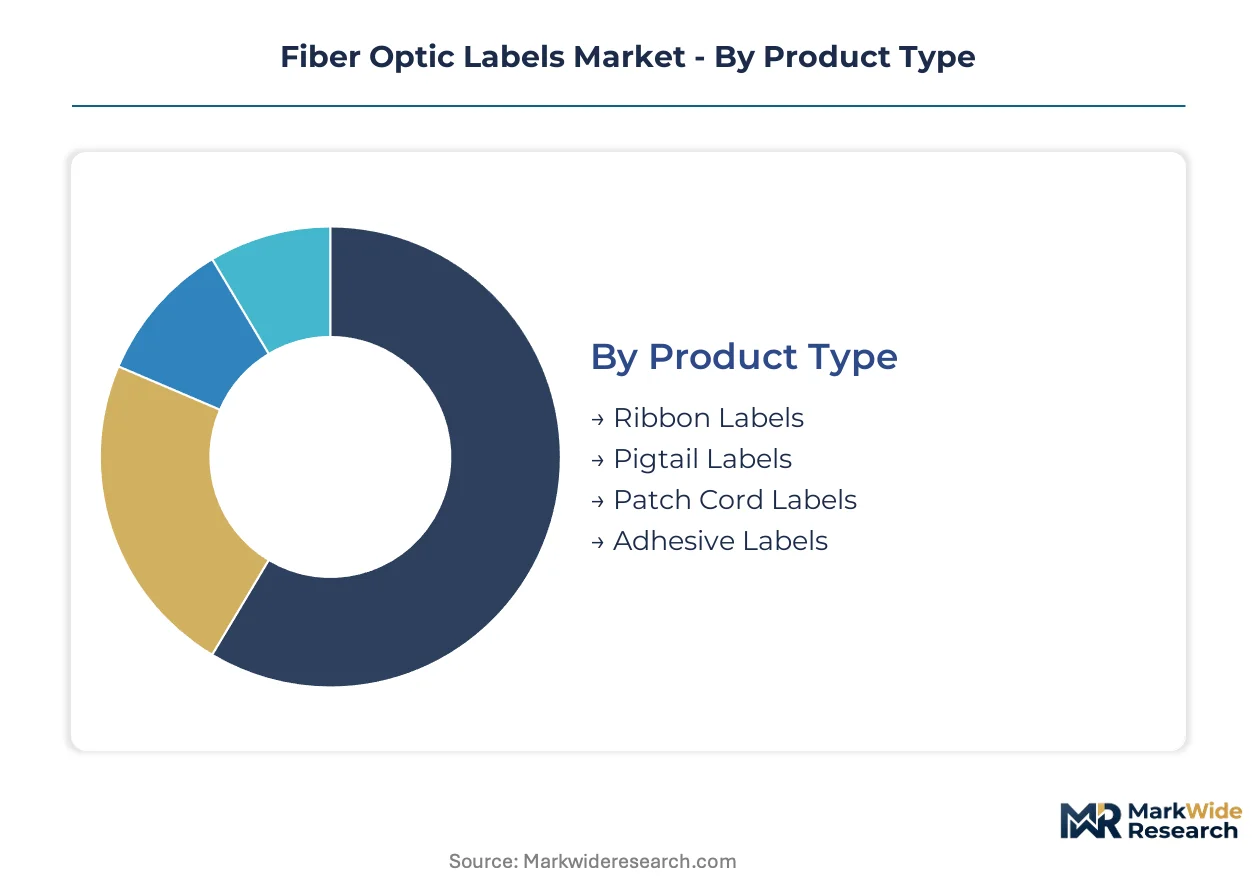
Fiber optic label procurement varies sharply by deployment environment, with hyperscale data centers demanding serialized traceability while industrial settings prioritize temperature-rated durability. Material specifications and adhesive formulations must align with jurisdiction-specific halogen-free mandates, creating divergent qualification burdens across segments.
Product Type:
REACH substance restrictions and TIA-606 compliance timelines diverge sharply across formats, with ribbon labels facing the steepest ECHA documentation burdens due to their concentration in European public telecommunications infrastructure.
- Ribbon Labels:Multi-fiber identification tags engineered for 8-fiber and 16-fiber MPO connector configurations. Demand concentrates in Virginia and Texas hyperscale clusters where rack-scale fiber density exceeds 10,000 strands. REACH amendments are accelerating converter migration from legacy substrates.
- Patch Cord Labels:Discrete single-fiber tags deployed universally in structured cabling systems. Volume leadership stems from universal deployment across telecom and enterprise networks, though margin pressure intensifies from unbranded Asian polyester suppliers.
- Pigtail Labels:Splice-point identification for fiber termination assemblies.
- Adhesive Labels:General-purpose pressure-sensitive formats facing commodity pricing dynamics.
Leading the category by volume: Patch Cord Labels. Growing fastest: Ribbon Labels.
Material:
Cost tiers stratify around certification grade, with halogen-free polypropylene commanding premium positioning against legacy vinyl formulations facing regulatory obsolescence.
- Polypropylene:Halogen-free substrate gaining share as converters substitute away from vinyl to satisfy REACH and RoHS mandates. European public network deployments are driving qualification investments among thermal transfer converters.
- Polyester:Commodity-grade substrate dominating adhesive label production. Unbranded Asian suppliers are eroding margins through volume-based cost undercutting in standard-temperature applications.
- Vinyl:Legacy formulation facing substitution costs from retooling requirements.
- Nylon:High-abrasion substrate for industrial automation environments.
Dominant by procurement value: Polypropylene. Steepest volume decline: Vinyl.
Application:
Customer type determines specification intensity, with hyperscale operators contracting directly for serialized pre-printed volumes while medical device manufacturers navigate FDA device labeling overlays.
- Data Centers:Hyperscale facilities in Oregon and Texas are compressing fiber density per rack unit, forcing identification systems to manage complex cable hierarchies. Pre-printed serialization services are capturing recurring revenue from operators bypassing in-house thermal transfer investments.
- Telecommunication Networks:TIA-606 standards mandate uniform labeling schemes across multi-vendor installations. Cross-functional coordination between contractors and facility managers drives compliance complexity.
- Industrial Automation:Temperature-rated adhesive validation from minus forty to plus one hundred fifty degrees Celsius extends product development cycles.
- Medical Devices:FDA device labeling requirements overlay fiber traceability specifications.
Highest specification intensity: Data Centers. Longest qualification timelines: Medical Devices.
End User:
Procurement consolidation patterns favor direct converter relationships among large facility operators, disintermediating traditional distributor channels across user types.
- Telecom Providers:European operators under CE marking and EU Construction Products Regulation are tightening flame propagation requirements for labels entering public networks. ECHA documentation burdens are expanding qualification costs.
- System Integrators:Multi-vendor installation coordination demands TIA-606 compliance enforcement across contractor ecosystems. Label-to-pathway hardware bundling addresses procurement consolidation trends.
- IT Departments:Enterprise data center operators with standardized multi-site portfolios.
- Facility Managers:Building infrastructure operators with integrated cable management requirements.
Most concentrated buying power: Telecom Providers. Fastest procurement model evolution: System Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale facility construction concentrates procurement power in specific metropolitan clusters, with serialized cable identification demand tracking data center buildout intensity across three continents. Regulatory divergence on halogen-free substrates and flame propagation standards fragments material qualification requirements by jurisdiction.
United States
Virginia, Texas, and Oregon data center clusters drive ribbon label procurement for 10,000-plus strand density environments. EPA restrictions on perfluorinated adhesive coatings constrain formulation flexibility for domestic converters. Northern Virginia's Ashburn-Loudoun corridor anchors the highest concentration of hyperscale cable identification contracts.
Germany
REACH substance restriction amendments accelerate converter migration from legacy vinyl to polypropylene substrates. ECHA documentation burdens expand qualification costs for labels entering European public telecommunications networks. Frankfurt's financial data center ecosystem demands CE-marked flame-resistant identification under EU Construction Products Regulation.
China
Domestic cloud infrastructure expansion creates procurement scale for serialized pre-printed volumes. MIIT standards govern telecommunications labeling schemes across multi-province networks. Yangtze River Delta data center zones in Shanghai and Jiangsu province concentrate domestic hyperscale buildout activity.
India
Greenfield cloud infrastructure under the PLI scheme generates first-mover positioning for serialized identification systems. TRAI mandates uniform cable labeling across multi-operator fiber deployments. Mumbai and Bengaluru metropolitan clusters anchor initial hyperscale facility construction.
Japan
METI efficiency standards drive automated cable identification adoption in dense telecommunications infrastructure. JIS flame propagation requirements govern substrate selection for public network installations. Tokyo-Osaka corridor data centers prioritize RFID-embedded traceability systems.
Fiber Optic Labels Market Competitive Landscape
Strategic partnerships dominate the current landscape as converters align with pathway hardware manufacturers to capture bundled procurement contracts. The vendor base stratifies around three tiers: integrated cable management specialists, thermal transfer printing experts, and commodity substrate suppliers. Archetypes include full-system integrators bundling labels with physical infrastructure, premium converters leveraging in-house serialization capabilities, and cost-focused Asian manufacturers. M&A activity and geographic expansion represent the two primary competitive vectors as firms seek scale and regulatory proximity.
Within the integrated-systems tier, Panduit Corporation and HellermannTyton Group PLC exemplify pathway-hardware bundling strategies, while Brady Corporation occupies a position among thermal-transfer specialists. Minnesota-based 3M Company anchors the materials-science archetype with substrate formulation capabilities. These three entities represent divergent approaches to value capture: physical infrastructure packaging, printing expertise monetization, and upstream material control.
| Leading Market Players |
|---|
| 3M Company |
| Brady Corporation |
| Panduit Corporation |
| HellermannTyton Group PLC |
| Avery Dennison Corporation |
| TE Connectivity Ltd. |
| Sumitomo Electric Lightwave Corporation |
| Fujikura Ltd. |
| Leviton Manufacturing Co., Inc. |
| Others |
Supply & Pricing Matrix
Backward integration into halogen-free substrate production anchors both supply security and margin protection for converters serving European public networks under REACH mandates. This upstream control separates qualified suppliers from commodity competitors facing polyester pricing erosion.
Pricing Analysis
Volume leadership in patch cord labels generates thin margins from commodity polyester substrates, while ribbon labels capture premium positioning through halogen-free polypropylene certification. Price differentiation rests on REACH compliance tier and serialization capability depth. Cost compression in adhesive labels is intensifying because unbranded Asian suppliers undercut branded converters. Enterprise IT departments demonstrate highest price sensitivity; hyperscale operators show lowest sensitivity due to traceability-critical procurement.
Supply Chain Analysis
Direct-to-hyperscale channels handle serialized pre-printed volumes, bypassing traditional distributor intermediaries. Raw material sourcing draws from China for commodity polyester, Germany for specialty polypropylene formulations, and Japan for high-temperature adhesive polymers. Supply chain risk centers on single-source vulnerability for halogen-free substrate certification documentation. Distribution runs through integrated cable management bundling with pathway hardware manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH substance restriction amendments have erected a cost-of-compliance moat that favors incumbent converters with existing ECHA documentation infrastructure over prospective entrants lacking qualification capital.
For Market Incumbents: Lock in hyperscale direct contracting relationships before procurement consolidation completes. Extend thermal transfer serialization capabilities into pre-printed service contracts. Brady Corporation's premium positioning demonstrates defensibility against unbranded Asian polyester erosion through in-house printing expertise. For New Entrants and Emerging Players: System integrators represent the most penetrable channel partner type for bundled label-to-pathway hardware offerings. Target India's PLI-backed data center greenfield expansion where first-mover serialization contracts remain unclaimed. Pursue white-label pre-printed partnerships to bypass capital-intensive thermal transfer line investments. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by integrated cable management specialists seeking label capabilities. Long-term viability favors converters with halogen-free substrate qualification depth and hyperscale direct relationships. Monitor ECHA documentation burden expansion as inflection indicator for regulatory-driven consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Halogen-Free Substrate Qualification | ECHA documentation investment separates REACH-compliant suppliers from vinyl legacy converters facing obsolescence. |
| Pre-Printed Serialization Service Launch | Recurring revenue capture from hyperscale operators bypassing in-house thermal transfer capital expenditure. |
| Integrated Cable Management Bundling | Panduit Corporation's pathway-hardware packaging demonstrates procurement consolidation capture among facility operators. |
| India Data Center Market Entry | PLI scheme greenfield construction creates first-mover positioning for serialized identification system contracts. |
| RFID-Embedded Label Development | Automated inventory reconciliation addresses 10,000-plus strand density traceability in hyperscale rack environments. |
Research Methodology
SEC filings, ECHA substance restriction databases, and hyperscaler capital expenditure disclosures formed the secondary backbone for this analysis. Primary interviews with data center procurement directors, thermal transfer converter operations managers, cable pathway hardware manufacturers, and telecommunications infrastructure contractors validated demand assumptions. Bottom-up fiber strand count modeling and top-down facility construction pipeline analysis were triangulated against TIA-606 compliance requirement timelines.
Historical trendline analysis of adhesive substrate pricing and ribbon label adoption curves informed projection mechanics across the analysis window. Segmentation dimensions modeled include product format, material certification tier, application environment, and end-user procurement consolidation pattern. CAGRs were derived from facility buildout intensity correlations with serialized identification procurement scaling. Forecast inputs incorporated REACH amendment implementation schedules and MPO connector deployment trajectories in hyperscale clusters.
Caveats apply where EPA perfluorinated compound restrictions or ECHA substance list expansions could materially shift the outlook for adhesive formulation availability. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Labels
Hang Tags Market
Labels
Foil Labels Market
Labels
Ripeness Indicator Labels Market
Labels
Kraft Labels Market
Labels
Holographic Labels Market
Labels
Foam Labels Market
Labels
GCC Labels and Release Liners Market
Labels
Industrial Label Printers Market
Labels
Self-Adhesive Labels Market
Labels
Glue-Applied Labels Market
Labels
Sleeve Label Market
Labels
HAZMAT Labels Market
Labels
In-Mold Labeling (IML) Market
Labels
Wrap Around Labels Market
Labels
Ampoule Sticker Labeling Machine Market
Labels
Wire Marking Labels Market