
 Global CMP Slurry Market | 2026-2036
Global CMP Slurry Market Size, Share, and Industry Trends Forecast 2026-2036
Global CMP Slurry Market Intelligence
The European Union's REACH regulation, governing chemical substance use, is realigning demand towards more environmentally benign CMP slurry formulations. Cabot Corporation leverages its deep expertise in particle manufacturing to supply critical abrasive materials for these products. DuPont specializes in developing advanced polymer-based slurries for next-generation semiconductor nodes, while Fujimi Corporation sustains its market position through a broad portfolio catering to both silicon and compound semiconductor substrates.
Chemical Mechanical Planarization (CMP) slurry is a chemical dispersion used to achieve nanometer-level surface flatness. These formulations contain abrasive nanoparticles, such as silica or ceria, suspended in a chemically reactive liquid solution to polish semiconductor wafers. Ceria-based slurries are gaining prominence for advanced dielectric planarization, a critical step in semiconductor fabrication. Demand from leading-edge foundries for slurries compatible with sub-5nm logic devices represents the fastest-growing application segment.
Regulations from bodies like the US EPA and the EU's ECHA dictate permissible chemical compositions and impose stringent wastewater treatment requirements on semiconductor fabs. In China, MEE directives on industrial pollutants influence slurry selection and disposal practices. Future investment decisions will hinge on developing slurries that balance higher planarization efficiency with reduced environmental impact and lower defectivity rates.
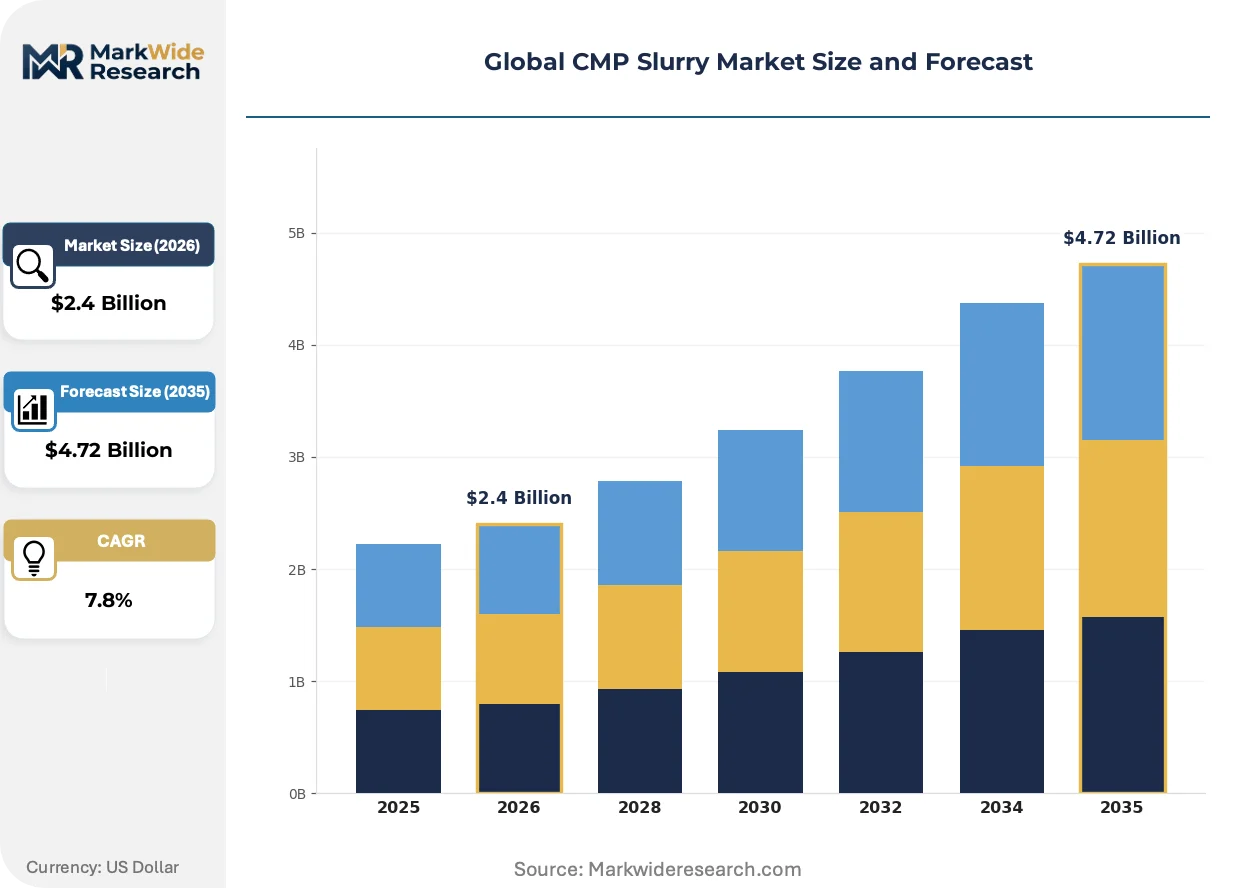
Market Dynamics
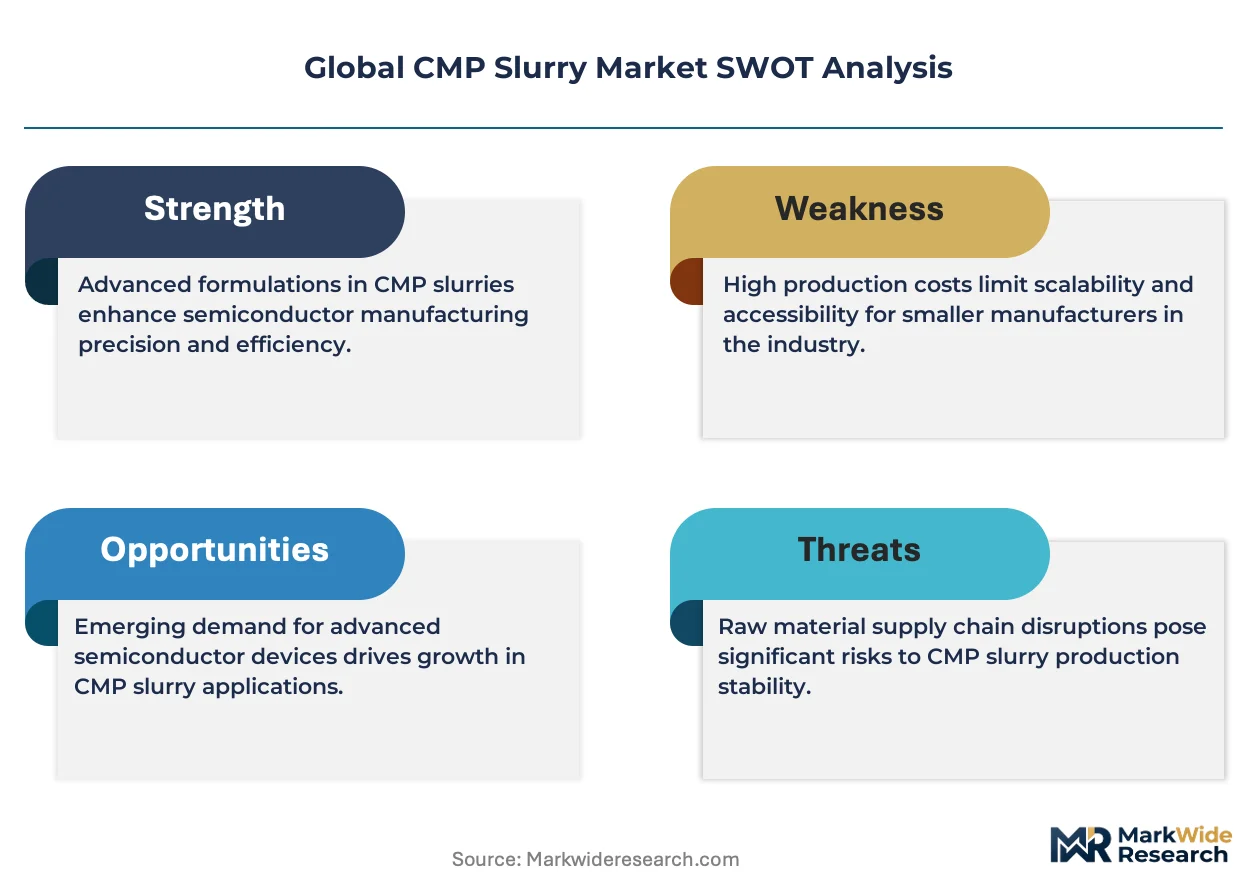
The central dynamic in the CMP slurry market is the technological imperative for atomic-scale precision in semiconductor manufacturing. This pressure, driven by the transition to sub-3nm process nodes, requires slurry formulations with unprecedented purity and material-specific selectivity.
Growth Catalysts
- Advanced Logic and Memory Nodes:Demand from foundries in Taiwan and South Korea for slurries that support Gate-All-Around (GAA) transistors and high-stack 3D NAND memory represents a primary growth vector for specialized formulations.
- Compound Semiconductor Adoption:The expanding use of silicon carbide (SiC) and gallium nitride (GaN) substrates for power electronics and 5G radio frequency components requires new slurry chemistries, broadening the market beyond traditional silicon wafers.
- Automotive Semiconductor Demand:Proliferation of ADAS and in-vehicle infotainment systems necessitates high-reliability chips, driving demand for CMP slurries that deliver superior surface quality and low defectivity to ensure long-term device performance.
Market Restraints
- Raw Material Concentration:The supply of high-purity abrasive particles, particularly ceria and colloidal silica, is concentrated among a few suppliers, creating price volatility and potential supply chain bottlenecks for slurry manufacturers.
- Environmental Compliance Costs:Regulations like the EU's REACH and directives from the US EPA impose stringent wastewater treatment requirements, increasing operational costs for both slurry producers and the semiconductor fabs that use them.
- Technical Hurdles in Defect Control:Achieving near-zero defectivity at advanced nodes is a significant technical barrier, slowing the qualification and adoption of new slurry formulations and limiting the number of capable suppliers.
Strategic Opportunities
- Environmentally Benign Formulations:Developing biodegradable or recyclable slurries that align with corporate ESG mandates and regulatory frameworks like the EU Green Deal creates a premium market segment for sustainable products.
- Advanced Packaging Applications:Adapting CMP slurries for panel-level packaging and other heterogeneous integration techniques provides a new high-volume application outside of front-end-of-line wafer fabrication.
- AI-Driven Process Optimization:The development of AI models and digital twins to predict slurry performance and optimize recipes in real-time offers a path to create high-value, service-based revenue streams for suppliers.
Industry Challenges
- Process Integration Complexity:Ensuring new slurry formulations are compatible with a fab's existing toolset and chemical processes is a complex and time-consuming challenge that can significantly delay qualification cycles for new materials.
- Wastewater Management Investment:The high capital expenditure needed for semiconductor fabs to build and operate advanced wastewater treatment systems capable of handling complex slurry chemistries presents a significant operational burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global CMP Slurry Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $4.72 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica-Based, Alumina-Based, Ceria-Based, Composite, Resin, Others Particle Size: Nanoparticles, Submicron, Micron, Ultrafine, Coarse Application: Semiconductor Fabrication, Photovoltaic Cells, Optical Components, Data Storage Devices, MEMS, LEDs End User: Foundries, Chipmakers, Electronics Manufacturers, R&D Laboratories, Assembly Units, Testing Facilities |
| Companies Covered | Entegris, Fujimi Corporation, DuPont, Cabot Corporation, FUJIFILM Corporation, BASF, Dow Chemicals, Saint-Gobain, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global CMP Slurry Market Strategic Shifts & Innovations
The market's trajectory is shaped by a dual pursuit of atomic-level surface precision and enhanced environmental sustainability. This inherent tension accelerates innovation in material science and process control, compelling a re-evaluation of legacy slurry chemistries and disposal methods.
Selective slurries provide highly differentiated polishing rates between dissimilar materials, such as silicon nitride and silicon oxide, which is essential for creating complex 3D device structures. Leading-edge logic and memory fabs are rapidly adopting these advanced formulations for their most critical process steps. This high-selectivity approach is overtaking traditional non-selective, bulk-removal slurries for intricate planarization tasks in sub-5nm device manufacturing.
China's MEE directives on industrial pollutants are tightening restrictions on chemical waste discharge from semiconductor facilities. This regulatory pressure compels fabs in manufacturing centers like Shanghai and Wuxi to invest in more sophisticated slurry recycling and water treatment infrastructure. The copper and tungsten slurry segments are particularly affected, with suppliers now engineering formulations that feature lower metal content and easier-to-treat chemical compositions.
A shift toward collaborative, in-fab process development is altering supplier-customer dynamics. Instead of purchasing standardized products, leading foundries are increasingly co-developing custom slurry formulations directly with suppliers to meet unique device performance and yield targets. This deep integration is most prominent in Taiwan and South Korea, where competitive pressures demand proprietary solutions for the most advanced technology nodes.
Global CMP Slurry Market Segmentation
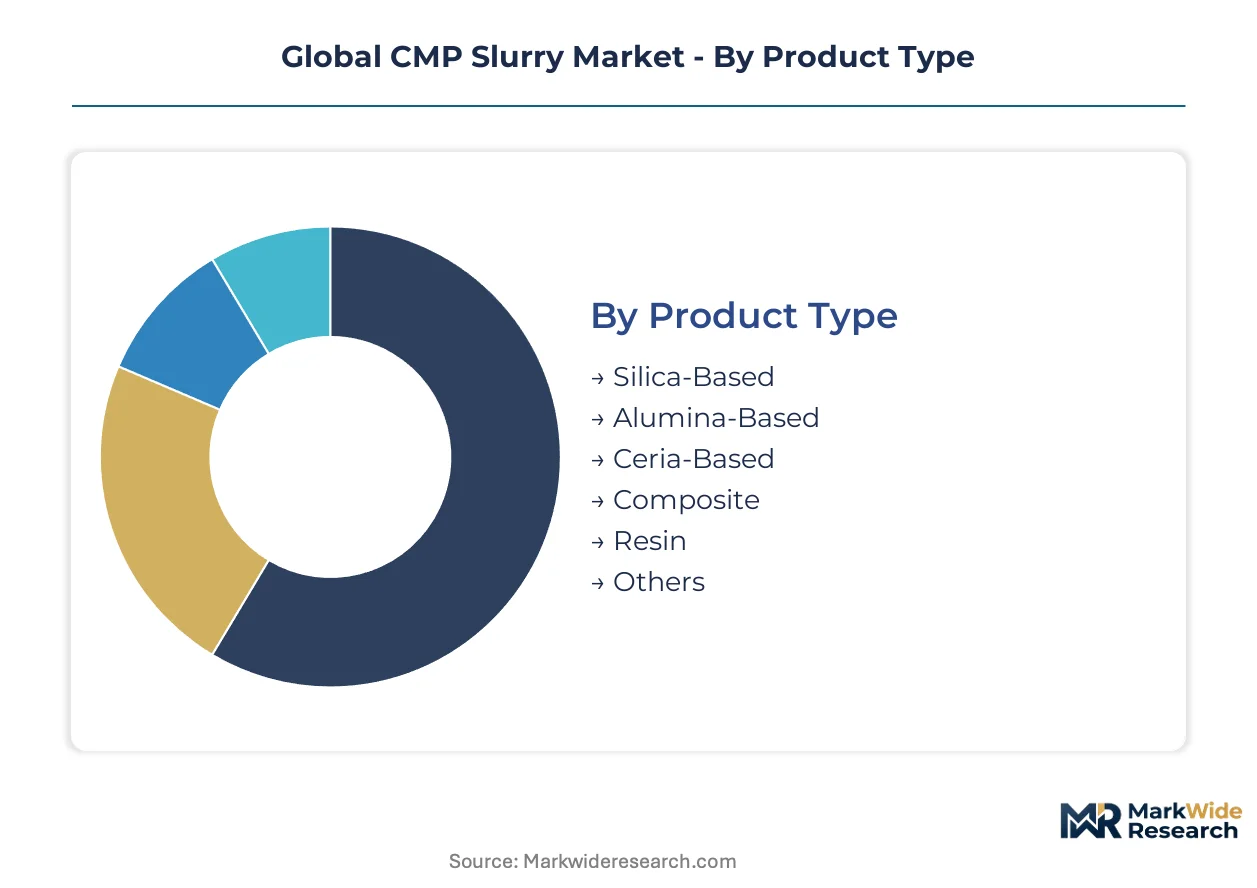
The CMP slurry market segments reflect the intricate demands of advanced manufacturing processes. Understanding these distinct categories provides clarity on material science innovations and shifts in end-use applications. This granular analysis illuminates the varied performance requirements across semiconductor production and other precision-intensive industries.
Product Type:
The continuous upgrade cycle in semiconductor manufacturing drives the evolution of CMP slurry product types, demanding formulations with superior performance and purity.
- Ceria-Based:Ceria oxide nanoparticles offer high selectivity for dielectric planarization. Demand concentrates in advanced logic and memory foundries in Taiwan, where sub-5nm fabrication requires precise material removal.
- Silica-Based:Silicon dioxide particles are widely used for planarization, offering good material compatibility and surface finish. Foundries in South Korea rely on these for front-end-of-line processes, balancing cost with performance.
- Alumina-Based:Aluminum oxide particles provide aggressive polishing for harder materials.
- Composite:These combine multiple abrasives for tailored selectivity.
- Resin:Polymer-based slurries designed for delicate material layers.
- Others:Niche formulations, including diamond or silicon carbide abrasives.
Silica-Based slurries sit at the top of the volume ranking, with Ceria-Based formulations climbing the fastest.
Particle Size:
Particle size directly influences the planarization mechanism and defectivity, with specific applications dictating the required abrasive dimensions.
- Nanoparticles:Particles below 100 nm are critical for atomic-scale flatness and defect reduction at advanced nodes. Demand is highest from leading-edge foundries developing sub-3nm logic devices.
- Submicron:Particles from 100 nm to 1000 nm balance removal rate and surface quality for broad planarization tasks. Semiconductor fabs in China utilize these for growing process technologies.
- Micron:Larger particles, 1-10 micrometers, for bulk material removal.
- Ultrafine:Bridging nanoparticles and submicron for intermediate planarization.
- Coarse:Used for initial grinding or aggressive material removal.
The shift towards smaller device geometries ensures that Nanoparticles are gaining share fastest, driven by advanced semiconductor manufacturing.
Application:
The volume contribution of CMP slurries varies significantly across diverse application areas, reflecting differing material requirements and process complexities.
- Semiconductor Fabrication:This primary application uses CMP slurries to create flat surfaces for lithography. The transition to Gate-All-Around transistors in Taiwan amplifies the need for highly selective slurries.
- Photovoltaic Cells:Slurries achieve optimal surface quality for enhanced light absorption and efficiency in solar cell production. Expanding renewable energy initiatives in Europe drive demand for cost-effective formulations.
- Optical Components:Precision polishing of lenses and mirrors relies on specialized CMP slurries.
- Data Storage Devices:Hard disk manufacturing utilizes CMP for surface planarization.
- MEMS:CMP achieves precise geometries for miniature Micro-Electro-Mechanical Systems.
- LEDs:LEDs require CMP for substrate preparation to improve light extraction.
Semiconductor Fabrication remains the largest application, while Photovoltaic Cells demonstrate a steepest expansion trajectory.
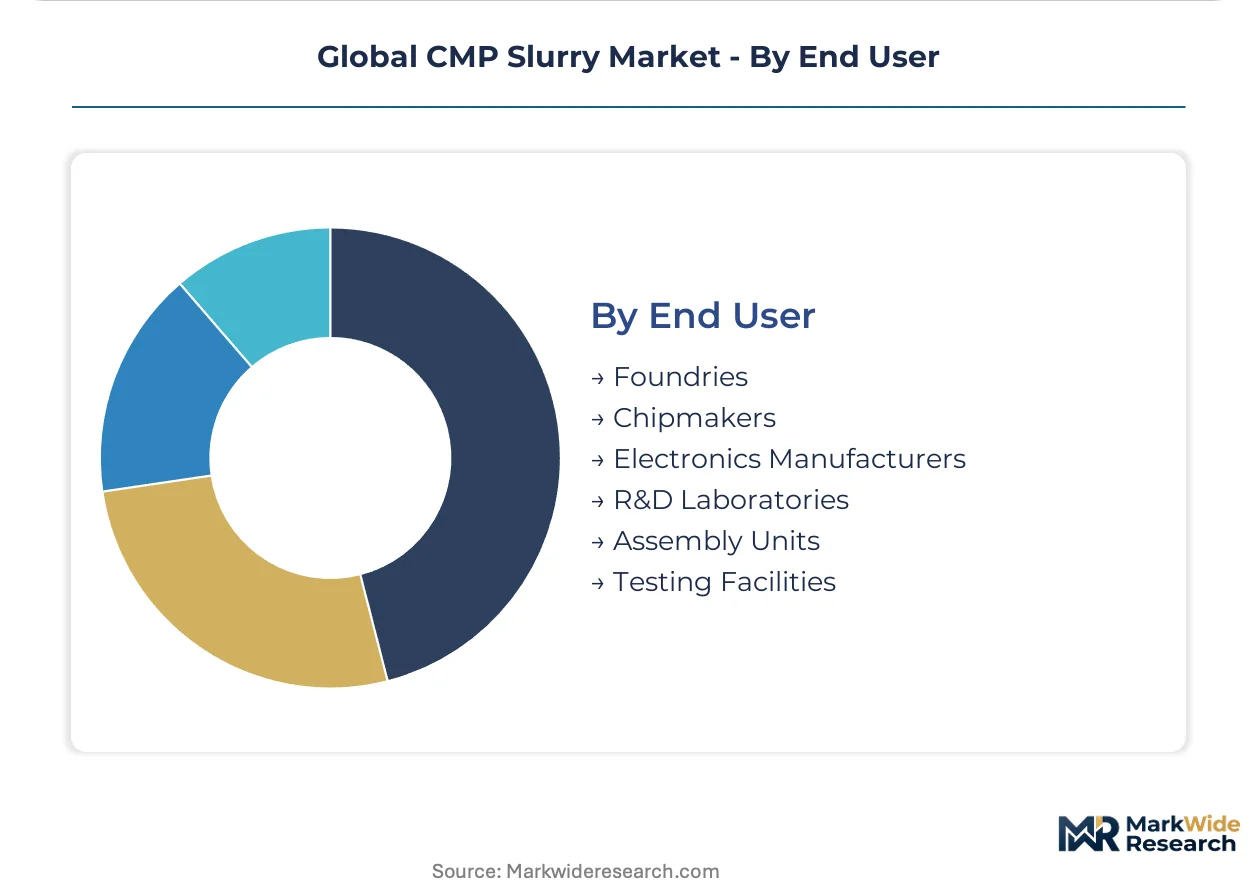
End User:
The maturity of end-user operations influences their specific slurry procurement strategies, ranging from standardized products to custom co-development.
- Foundries:These specialized manufacturers drive demand for high-volume, advanced CMP slurries. Foundries in South Korea prioritize custom co-development to meet stringent yield targets.
- Chipmakers:Integrated Device Manufacturers (IDMs) need diverse CMP slurries for varied product lines. US-based chipmakers focus on slurries ensuring high reliability for automotive applications.
- Electronics Manufacturers:Indirectly influence demand for reliable upstream CMP processes.
- R&D Laboratories:Require small batches of specialized slurries for experimentation.
- Assembly Units:Quality requirements influence upstream wafer processing and slurry selection.
- Testing Facilities:Evaluate chip performance, validating CMP effectiveness.
Foundries account for the largest share of consumption, with R&D Laboratories representing a segment with specialized, growing needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global CMP slurry market initially scaled alongside the semiconductor industry's expansion in the United States and Japan. Advancements in microelectronics fabrication drove the early demand for precise planarization. Today, the market's center of gravity has shifted towards Asian manufacturing powerhouses.
Taiwan
Demand for advanced CMP slurries in Taiwan stems from its world-leading foundry capacity. The transition to Gate-All-Around transistors amplifies the need for highly selective formulations. Hsinchu Science Park remains a critical hub for semiconductor manufacturing and slurry co-development.
South Korea
South Korea's robust memory and logic semiconductor industry drives significant slurry consumption. Foundries prioritize custom co-development to meet stringent yield targets for high-stack 3D NAND memory. The Gyeonggi Province hosts major semiconductor fabrication plants requiring specialized slurries.
United States
The United States market sees demand from chipmakers focusing on high-reliability automotive applications. Regulations from the US EPA influence slurry selection and disposal practices. Silicon Valley and Austin serve as key centers for semiconductor R&D and advanced device manufacturing.
China
China's expanding semiconductor industry, driven by national self-sufficiency goals, fuels demand for a broad range of CMP slurries. MEE directives on industrial pollutants shape slurry selection and wastewater treatment investments. Manufacturing centers like Shanghai and Wuxi are increasing their advanced semiconductor production.
Germany
European Union's REACH regulation is realigning demand towards more environmentally benign CMP slurry formulations. German research institutions and advanced manufacturing facilities contribute to the development of specialized chemistries. Dresden's Silicon Saxony cluster represents a significant European semiconductor manufacturing region.
Global CMP Slurry Market Key Industry Players
Capital-heavy producers compete with asset-light designers for market influence in the CMP slurry sector. The market exhibits a tiered structure, with a few large integrated chemical companies alongside specialized material science firms. Strategic archetypes include diversified chemical giants offering broad portfolios and niche particle manufacturing experts providing critical abrasive components. Companies primarily engage in strategic partnerships and technology licensing to maintain their competitive edge and accelerate product qualification.
Among the diversified chemical giants, DuPont exemplifies a focus on advanced polymer-based slurries essential for next-generation semiconductor nodes. Cabot Corporation, a US-based entity, anchors the market through its deep expertise in particle manufacturing, supplying critical abrasive materials for these products. Japan's Fujimi Corporation sustains its market position through a broad portfolio catering to both traditional silicon and emerging compound semiconductor substrates. These companies represent the blend of material science innovation and broad market coverage required to address the intricate demands of advanced semiconductor fabrication.
| Leading Market Players |
|---|
| Entegris |
| Fujimi Corporation |
| DuPont |
| Cabot Corporation |
| FUJIFILM Corporation |
| BASF |
| Dow Chemicals |
| Saint-Gobain |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Leading-edge foundry demand for specialized CMP slurries, particularly from Taiwan and South Korea, compels suppliers to invest heavily in R&D and co-development, driving premium pricing for advanced formulations. This dynamic shapes the supply chain, prioritizing reliability and technical partnership over pure cost efficiency for critical materials.
Pricing Analysis
Value-based pricing structures characterize the CMP slurry market, reflecting the high customization required for sub-3nm nodes. Price differentiation stems from formulation purity, material selectivity, and the depth of co-development support provided to leading foundries. Pricing softness affects conventional silica-based slurries, driven by broad market competition and increasing supply from China. Foundries prioritize performance over cost for advanced applications, while photovoltaic cell manufacturers exhibit higher price sensitivity.
Supply Chain Analysis
Semiconductor fabs frequently mandate dual-sourcing for critical CMP slurry components to mitigate risk and ensure supply continuity. Supply of high-purity abrasive particles, particularly ceria and colloidal silica, concentrates in China and Japan, creating potential single-source vulnerabilities. The supply chain relies on specialized chemical manufacturers in the United States and Germany for advanced polymer additives. Distribution runs through direct sales channels to major foundries in Taiwan and South Korea, alongside specialized chemical distributors for smaller fabs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CMP slurry market presents a geographic arbitrage opportunity, driven by lower production costs in emerging Asian economies versus stringent environmental compliance requirements imposed by the EU's REACH regulation. This differential influences manufacturing footprint and product development strategies.
For Market Incumbents:Acquire specialized material science firms possessing proprietary environmentally benign formulations to counter regulatory shifts like the EU Green Deal. Expand in-fab co-development partnerships with leading foundries in Taiwan, leveraging existing relationships to secure next-generation node qualifications. This defends against margin pressure from new entrants offering sustainable alternatives and reinforces competitive positioning through advanced technology access.
For New Entrants and Emerging Players:Begin with targeted entry into the compound semiconductor segment, specifically developing specialized slurries for silicon carbide and gallium nitride substrates. This market, driven by 5G and power electronics, offers higher margins and less entrenched competition than traditional silicon. Focus on value proposition through superior material selectivity and defectivity control for these emerging applications. Partner with smaller, innovative fabs in less saturated regions to establish initial market presence.
For Investors and Strategic Acquirers:Asymmetric upside sits with niche material science firms possessing proprietary environmentally benign CMP slurry formulations. This market remains critical for semiconductor scaling across the next decade, ensuring sustained demand for advanced polishing solutions. Target companies with strong intellectual property in ceria-based or advanced polymer slurries compatible with sub-3nm process nodes. The signal to watch is a significant increase in strategic partnerships between large chemical companies and smaller, innovative material developers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion for Ceria Production | Ensures stable supply of critical abrasive material for advanced dielectric planarization. |
| Joint Development of Biodegradable Slurries | Aligns with EU Green Deal and MEE directives, creating a premium segment for sustainable products. |
| AI-Driven Process Optimization Platform | Offers high-value, service-based revenue streams by enhancing slurry performance and fab efficiency. |
| Geographic Expansion into Southeast Asian Foundries | Captures emerging demand from new semiconductor manufacturing hubs outside traditional regions. |
| Advanced Packaging Slurry Formulation | Addresses new high-volume applications in panel-level packaging and heterogeneous integration. |
Research Approach
Multiple input streams — primary interviews, extensive secondary research, and proprietary industry databases — were reconciled to construct a robust market view. This involved conversations with R&D directors, procurement managers, and process engineers across leading semiconductor fabs and slurry suppliers. Secondary validation drew from company annual reports, SEMI industry publications, and regulatory filings from the US EPA and EU's ECHA. Bottom-up data aggregation and top-down market sizing ensured comprehensive triangulation.
The reconciled data streams fed into an integrated analytical framework, modeling market dynamics across the analysis window. Segmentation dimensions included product type, particle size, application, end-user, and regional manufacturing clusters. Compound Annual Growth Rates were derived from historical trends, identified growth catalysts, and expert projections. Key forecast inputs included announced semiconductor fab expansion plans and evolving global chemical regulatory landscapes.
Several conditions sit outside the modeled scope, including sudden geopolitical shifts impacting trade routes or unforeseen breakthroughs in alternative planarization technologies. Forecasts reflect documented assumptions, but rapid changes in semiconductor manufacturing processes or raw material supply disruptions could alter market trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Chemicals
1-Octanol Market
Industrial Chemicals
High Viscosity Mixer Market
Industrial Chemicals
Global Neopentyl Glycol Market
Industrial Chemicals
Chemical Process Mixers Market
Industrial Chemicals
Chrome Plating Market
Industrial Chemicals
Volatile Organic Compounds (VOC) Concentrator Market
Industrial Chemicals
Cockroach Gel Baits Market
Industrial Chemicals
Northern Europe Calcium Sulphate Market
Industrial Chemicals
1, 6 Hexanediol Market
Industrial Chemicals
Welding Electrodes Market
Industrial Chemicals
Global Industrial Oils Market
Industrial Chemicals
Industrial Grade Urea Market
Industrial Chemicals
Organophosphate Insecticides Market
Industrial Chemicals
Ethoxy Propanol Market
Industrial Chemicals
Foam Market
Industrial Chemicals
Caustic Calcined Magnesia Market