

Activated Carbon for Sugar Decolorization Market Size, Share, and Industry Trends Forecast 2026-2036
Activated Carbon for Sugar Decolorization Market Insights
Specialty organic sugar refineries are redrawing procurement patterns across the activated carbon supply base, displacing commodity bulk buyers that historically anchored volume contracts. Kuraray leverages its coconut-shell carbon technology leadership to dominate premium regenerable grades for European beet processors. Cabot Corporation anchors North American supply through integrated carbon reactivation infrastructure serving cane refineries along the Gulf Coast. Jacobi Group competes on granular product breadth, sustaining geographic coverage across Latin American and Asian sugar hubs.
Activated carbon for sugar decolorization comprises thermally or chemically activated carbonaceous materials with high mesopore surface area, typically 900–1,500 m²/g, engineered to adsorb color precursors, caramels, and polyphenolic compounds from raw sugar liquors and syrups. Steam-activated coconut shell and coal-based variants predominate in cane and beet applications where pH tolerance and ash content determine regeneration cycles and syrup throughput economics. Powdered activated carbon leads in beet sugar processing where rapid dispersion and high dosing rates address seasonal campaign intensity, while granular activated carbon captures expanding share in cane refineries seeking lower labor costs through fixed-bed column systems. Extruded activated carbon remains a niche but growing format in corn syrup purification, where pressure-drop requirements in continuous flow reactors favor pelletized geometries.
EFSA food-contact regulations and EU Green Deal sustainability criteria are tightening permissible ash and heavy-metal thresholds in carbon used for edible products, directly shaping supplier qualification and reactivation service economics. FDA food additive rules under 21 CFR 173 and EPA spent carbon disposal guidelines add compliance layers for U.S. refiners operating integrated reactivation kilns. ISO 9001 and FSSC 22000 certifications increasingly gate market access among multinational food and beverage producers. Stakeholders must weigh captive reactivation investments against third-party service models as regulatory scrutiny of carbon lifecycle impacts intensifies.
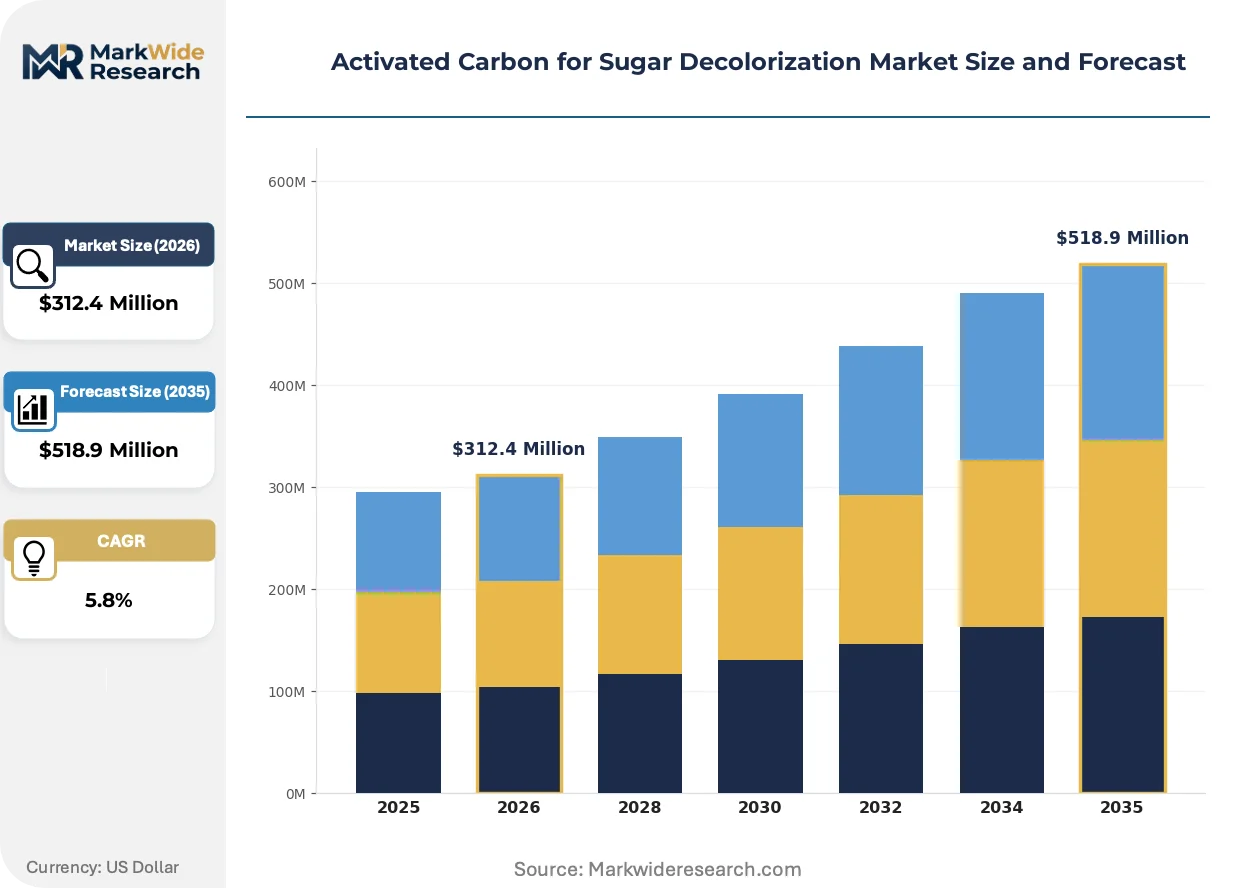
Market Dynamics
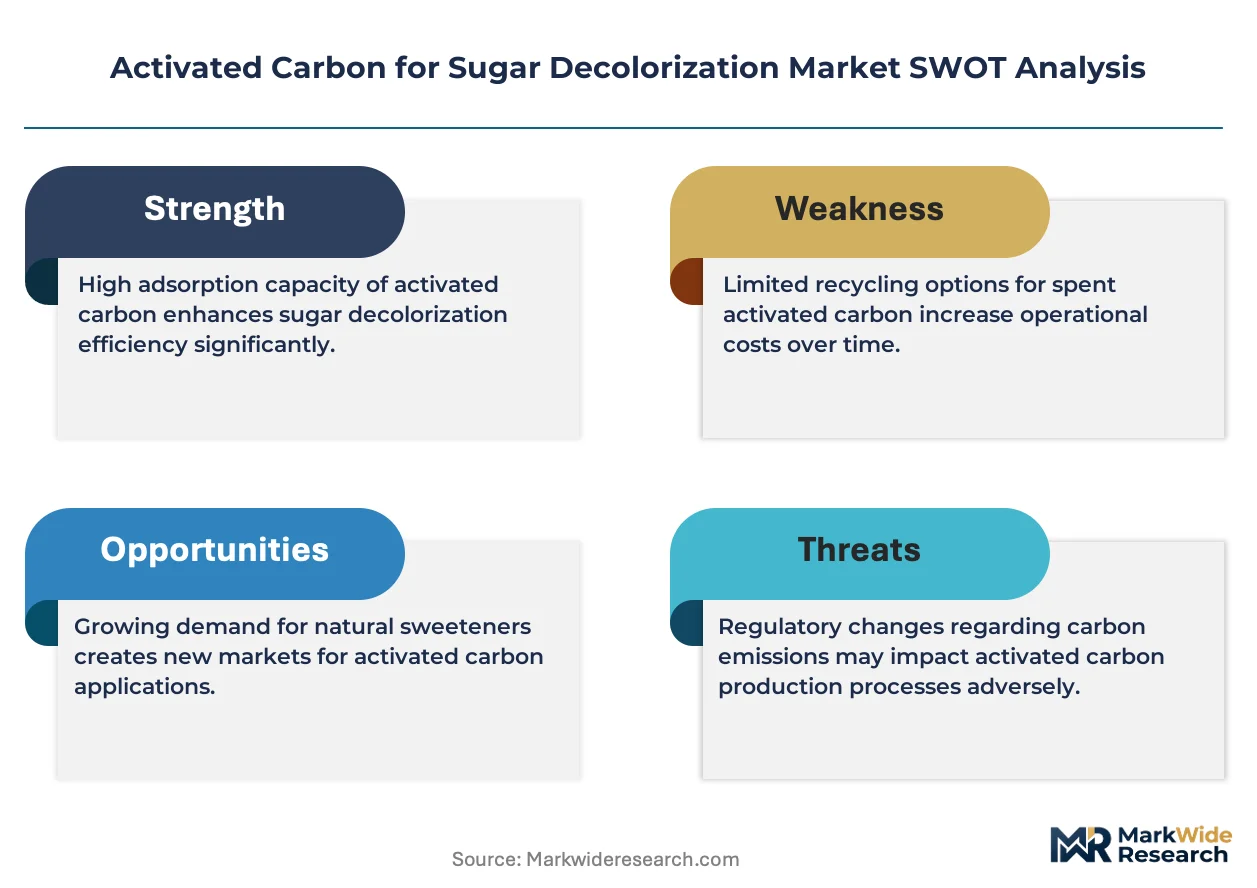
EU Green Deal sustainability mandates and EFSA food-contact material regulations are forcing sugar refineries to abandon older decolorization chemistries, redirecting capital toward regenerable carbon systems with certified reactivation loops.
Growth Catalysts
- EFSA Heavy-Metal Thresholds:Tightened permissible ash and heavy-metal limits under EU food-contact regulations are disqualifying conventional carbon suppliers and creating qualified-supplier premiums for compliant producers.
- Ethanol-Sugar Flex Plants:Brazil's Center-South cane belt is requiring higher-purity outputs for simultaneous crystal sugar and anhydrous biofuel production, expanding granular activated carbon deployment in fixed-bed column systems.
- Organic Food Additive Certification:Specialty sugar refineries seeking FSSC 22000 and organic certifications are specifying coconut-shell-based powdered grades with documented renewable sourcing.
Market Restraints
- Coconut Shell Feedstock Volatility:Supply concentration in Southeast Asian coconut-processing regions exposes producers to weather-driven raw material shortages and price spikes.
- Reactivation Infrastructure Concentration:North American and Western European reactivation kiln capacity is controlled by a limited set of integrated service providers, creating bottleneck risks for refineries without captive facilities.
- Technical Regeneration Limits:Thermal reactivation degrades mesopore structure over successive cycles, eventually requiring virgin carbon replacement and eroding lifetime cost advantages.
Strategic Opportunities
- Indian Beet Sugar Expansion:Uttar Pradesh and Maharashtra processing cooperatives are modernizing filtration infrastructure, creating first-mover advantage for granular system suppliers offering integrated reactivation partnerships.
- Corn Syrup Purification:Extruded pellet geometries are penetrating high-fructose corn syrup continuous flow reactors where pressure-drop specifications previously excluded activated carbon.
- EU Carbon Border Adjustment:CBAM implementation is penalizing imported sugar processed with non-regenerable decolorization chemistries, advantaging European carbon reactivation service networks.
Industry Challenges
- Reactivation Technician Shortage:Specialized kiln operation and spent carbon handling certification programs are failing to produce sufficient qualified personnel for expanding reactivation facility networks.
- Legacy System Integration:Cane refineries with decades-old powder-dosing infrastructure face significant mechanical and control-system retrofit costs to transition to fixed-bed granular column operations.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Activated Carbon for Sugar Decolorization Market Trends and Innovations
Activated carbon technology is converging with precision agriculture and biofuel quality standards, compressing acceptable color-body thresholds while extending carbon regeneration economics through digital monitoring.
Mesopore-engineered coconut-shell carbon is miniaturizing color-precursor adsorption kinetics, enabling Brazilian ethanol-sugar flex plants to achieve simultaneous crystal sugar and fuel-grade purity without parallel filtration trains. Specialty organic refineries in Germany and France are adopting these grades for beet campaigns despite 15-20% virgin carbon premiums. The structural consequence is compressing acceptable performance thresholds for commodity coal-based alternatives.
EFSA's updated food-contact material regulations under the EU Green Deal are mandating lifecycle documentation for carbon used in edible products, forcing suppliers to establish chain-of-custody certification from raw material through reactivation. Beet processors in northern France and eastern Germany are disqualifying suppliers lacking ISO 9001 and FSSC 22000 dual certification. This regulatory pressure is accelerating consolidation among reactivation service providers capable of audit-ready documentation.
Refinery procurement departments are unbundling carbon supply from reactivation services, issuing separate contracts for virgin material and spent-carbon processing to optimize unit economics. Gulf Coast cane refineries in Louisiana and Texas are piloting this model through third-party logistics providers offering kiln-to-kiln tracking. Brazil's Center-South mills are resisting this shift, maintaining integrated contracts with suppliers offering guaranteed regeneration-cycle minimums.
Activated Carbon for Sugar Decolorization Market Segmentation
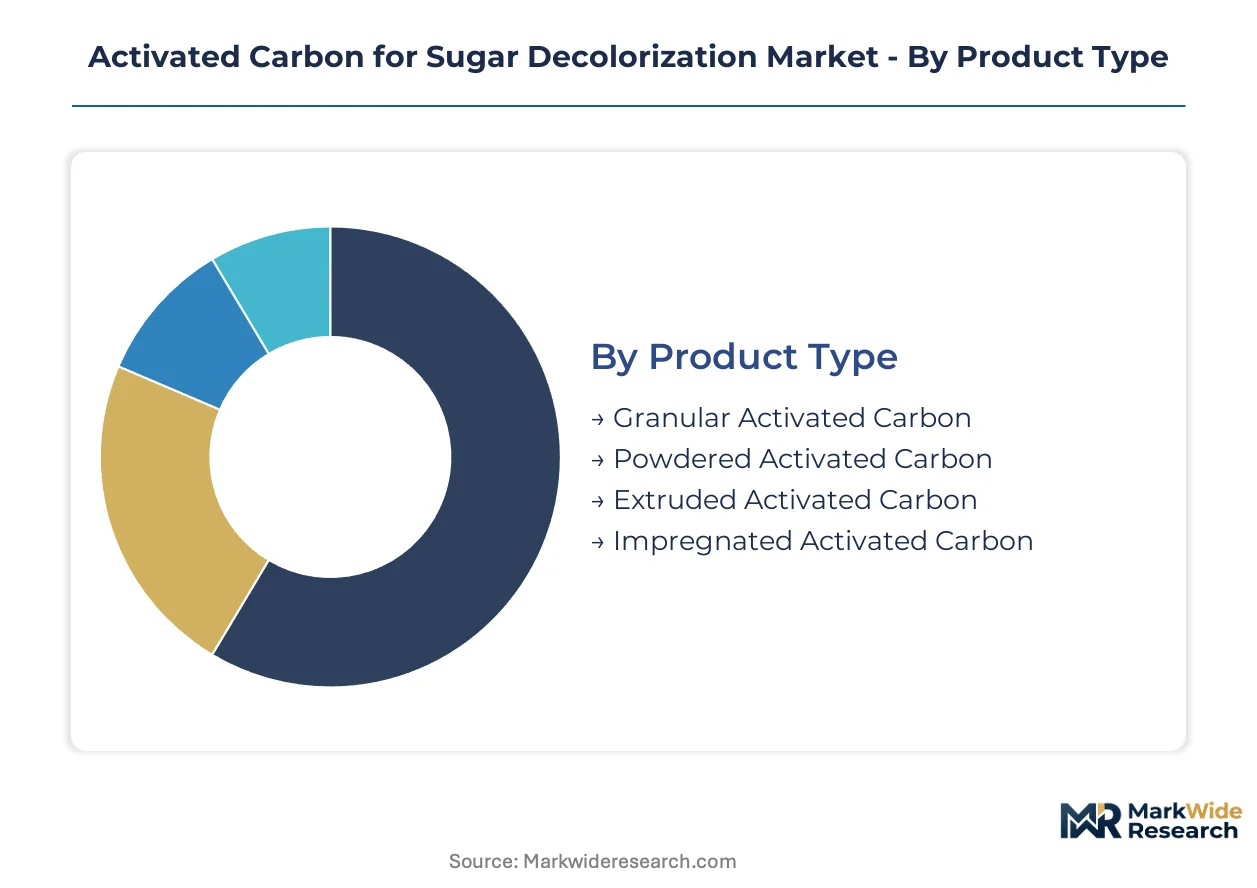
Segmentation in the activated carbon for sugar decolorization market reflects divergent procurement economics between commodity bulk buyers and specialty refineries seeking certified regenerable grades. Understanding these divides clarifies why coconut-shell granular carbon commands premium pricing in European beet processing while coal-based powdered variants dominate Brazilian cane operations.
Product Type:
Domestic consumption patterns favor granular and powdered formats in established refining markets, while extruded and impregnated grades see stronger export-led demand from specialty food additive suppliers seeking differentiated performance profiles.
- Powdered Activated Carbon:Rapid-dispersion thermally activated carbon with high surface area-to-mass ratios, typically dosed at 0.5-2.0 kg per ton of raw sugar. Beet processors in northern France and eastern Germany deploy this format during intensive seasonal campaigns where throughput velocity outweighs labor costs. EFSA food-contact certification requirements are disqualifying non-compliant suppliers and consolidating procurement among dual-ISO-certified vendors.
- Granular Activated Carbon:Fixed-bed column carbon with engineered particle size distributions (0.4-2.5 mm) enabling multiple thermal regeneration cycles. Brazil's Center-South ethanol-sugar flex plants are installing granular systems to achieve simultaneous crystal sugar and anhydrous biofuel purity without parallel filtration infrastructure. Higher virgin carbon capex is offset by reduced labor and extended regeneration economics.
- Extruded Activated Carbon:Pelletized geometries optimized for pressure-drop specifications in continuous flow reactors, penetrating corn syrup purification applications where previous carbon formats failed.
- Impregnated Activated Carbon:Surface-modified variants with enhanced selectivity for specific color precursors, serving niche organic certification requirements in specialty sugar segments.
Powdered activated carbon holds the largest share; momentum sits with granular formats as fixed-bed automation spreads beyond Brazilian cane refineries into Indian and Thai operations.
Application:
Cost tier stratification separates high-volume commodity processing from premium certification-driven segments, with beet and cane applications anchoring mid-tier economics while corn syrup and bioethanol purification command specialized pricing.
- Cane Sugar Refining:Year-round processing of tropical raw sugars with higher initial color loads and invert sugar content, demanding pH-tolerant carbon with low soluble ash. Gulf Coast refineries in Louisiana and Texas operate integrated reactivation kilns to manage spent carbon volumes, while Brazilian flex plants prioritize granular systems with guaranteed regeneration-cycle contracts.
- Beet Sugar Processing:Seasonal campaigns (90-120 days) processing temperate-climate root sugars with lower color precursors but higher seasonal throughput intensity. European processors face EU Green Deal pressure to document carbon lifecycle impacts from raw material through reactivation, favoring coconut-shell suppliers with chain-of-custody certification.
- Corn Syrup Purification:Continuous-flow high-fructose processing where extruded pellet geometries address pressure-drop constraints previously excluding activated carbon from this application.
- Bioethanol Production:Anhydrous fuel-grade purity requirements in Brazilian flex plants driving granular carbon deployment for simultaneous sugar and ethanol output streams.
- Brewing Industry:Adjacent fermentation-derived color removal applications with lower volume scale but higher specification variability.
Cane sugar refining commands the largest application share; bioethanol production is climbing the fastest as Brazilian flex-plant capacity expands.
End User:
Customer type fragmentation separates integrated multinational refiners with captive reactivation infrastructure from regional processors dependent on third-party service networks.
- Sugar Refining Plants:Large-scale beet and cane operations with annual carbon consumption exceeding 500 tons, typically operating under FSSC 22000 certification requirements. These facilities are unbundling virgin carbon supply from reactivation services to optimize unit economics.
- Food & Beverage Producers:Downstream users specifying certified carbon grades for ingredient supply chains, exerting upstream pressure on refinery procurement decisions through audit requirements.
- Biofuel Manufacturers:Brazilian ethanol-sugar flex plants and standalone anhydrous fuel producers requiring higher-purity outputs than traditional sugar operations.
- Ethanol Distilleries:Fermentation-based producers with distinct color-body profiles from cane juice versus molasses feedstocks.
- Food Additive Suppliers:Specialty organic and natural sweetener producers driving coconut-shell carbon premiums through renewable sourcing documentation requirements.
Sugar refining plants represent the dominant end-user category; food additive suppliers are expanding most quickly as organic certification requirements proliferate.
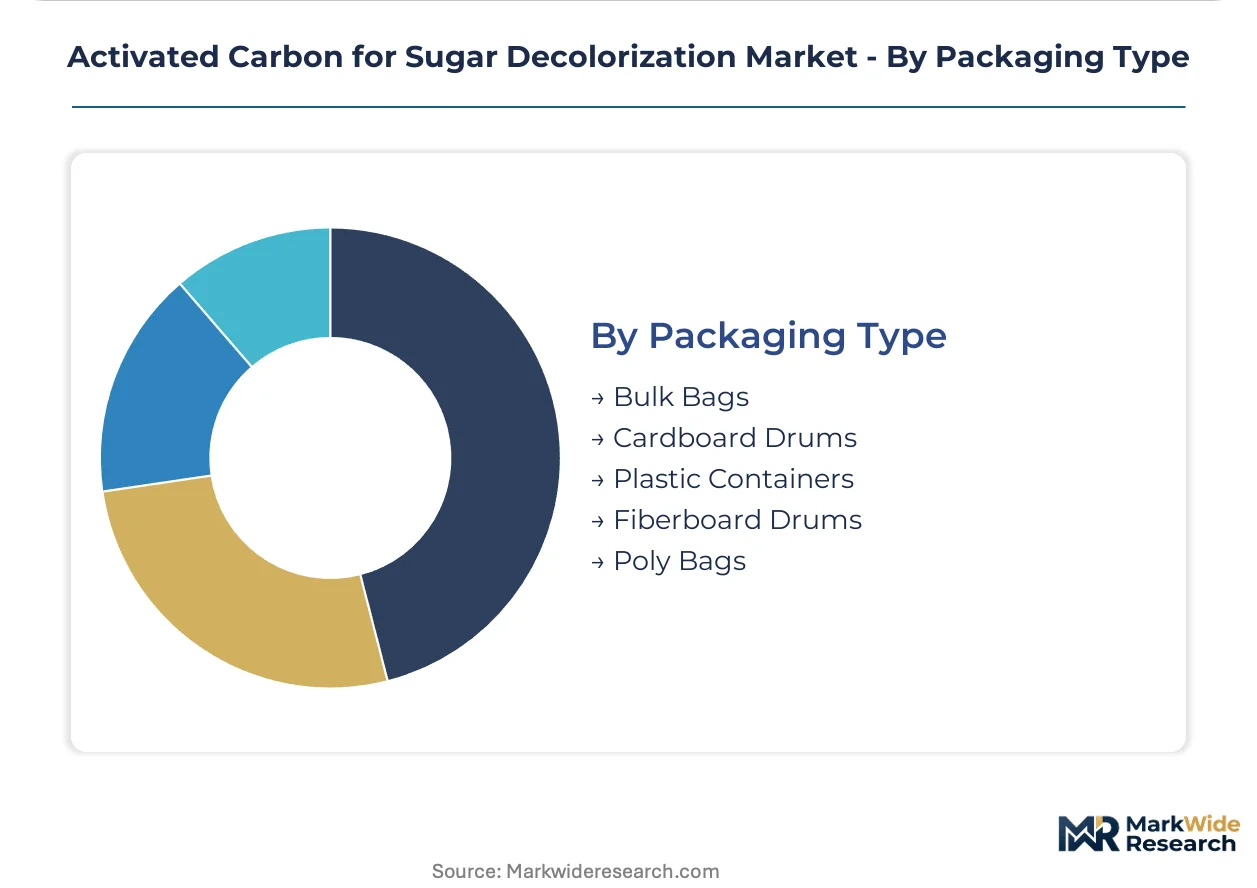
Packaging Type:
Supply concentration in bulk logistics favors regional packaging configurations aligned with reactivation facility proximity and refinery materials-handling infrastructure.
- Bulk Bags:One-ton flexible intermediate bulk containers dominating high-volume cane refinery deliveries along the US Gulf Coast and Brazilian Center-South corridor.
- Cardboard Drums:Standard 25-50 kg packaging for beet campaign seasonal deliveries where moisture protection and stacking stability matter.
- Fiberboard Drums:Enhanced structural integrity for export shipments to Indian and Southeast Asian processing cooperatives.
- Plastic Containers:Moisture-barrier protection for specialty impregnated grades with humidity-sensitive surface modifications.
- Poly Bags:Lowest-cost option for captive reactivation facilities receiving spent carbon returns in non-critical handling environments.
Bulk bags hold the largest share; fiberboard drums are gaining share fastest as Indian beet sugar infrastructure modernization accelerates import-dependent procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Santos container terminals underwrite Brazil's dominance in sugar decolorization carbon logistics, handling over 70% of activated carbon imports for the Center-South cane belt. This maritime infrastructure connects Southeast Asian coconut-shell suppliers to the world's largest ethanol-sugar flex plant cluster.
Brazil
Center-South flex plants in São Paulo state deploy granular carbon in fixed-bed columns to achieve simultaneous crystal sugar and anhydrous biofuel purity. ANVISA food-contact regulations align with EFSA heavy-metal thresholds, pressuring mills toward certified regenerable systems. The Ribeirão Preto industrial corridor hosts the densest concentration of integrated carbon reactivation partnerships.
Germany
Beet processors in Lower Saxony and Saxony-Anhalt face EU Green Deal mandates to document carbon lifecycle impacts from raw material through reactivation. EFSA tightened permissible ash thresholds disqualify conventional suppliers, consolidating procurement among FSSC 22000-certified vendors. The Magdeburg sugar refining cluster leads adoption of coconut-shell granular grades despite virgin carbon premiums.
United States
Gulf Coast cane refineries in Louisiana operate captive reactivation kilns to manage spent carbon volumes under EPA disposal guidelines. FDA 21 CFR 173 food additive rules add compliance layers for integrated facilities. The St. James Parish industrial corridor anchors North American supply through third-party logistics providers offering kiln-to-kiln tracking.
India
Uttar Pradesh and Maharashtra processing cooperatives modernize filtration infrastructure, creating first-mover advantage for granular system suppliers. FSSAI food safety standards increasingly gate market access among multinational food producers. The Muzaffarnagar sugar belt drives import-dependent procurement of fiberboard-drum packaged carbon for seasonal campaign intensity.
France
Northern beet processors in Picardy face EU Carbon Border Adjustment penalties for imported sugar processed with non-regenerable chemistries. EFSA chain-of-custody requirements favor suppliers with ISO 9001 dual certification. The Amiens refining cluster accelerates consolidation among reactivation service providers capable of audit-ready documentation.
Activated Carbon for Sugar Decolorization Market Competitive Landscape
Listed leaders compete with private specialists across reactivation infrastructure ownership, creating a tiered structure where scale advantages clash with service flexibility. The vendor base concentrates among integrated carbon manufacturers with captive kiln networks and regional distributors dependent on third-party reactivation partnerships. Three archetypes dominate: multinational chemical conglomerates with backward integration into coconut-shell feedstock, mid-cap carbon specialists with geographic coverage across sugar hubs, and reactivation service providers unbundling spent-carbon processing from virgin supply. Capacity expansion and strategic partnerships represent the dominant competitive moves, as mills seek guaranteed regeneration-cycle minimums.
Among Japanese chemical conglomerates, Kuraray and Osaka Gas Chemicals occupy positions in premium regenerable grades, while U.S.-based Cabot Corporation anchors North American supply through integrated reactivation infrastructure. These three exemplify the split between feedstock-integrated manufacturers and service-network operators competing for refinery procurement contracts.
| Leading Market Players |
|---|
| Kuraray |
| Cabot Corporation |
| Jacobi Group |
| Haycarb |
| Chemviron |
| Calgon Carbon Corporation |
| Ingevity Corporation |
| Osaka Gas Chemicals |
| Norit |
| Others |
Pricing and Supply Chain Analysis
Coconut-shell carbon displacement of coal-based alternatives simultaneously redraws procurement geography toward Southeast Asian feedstock clusters and compresses pricing premiums for certified regenerable grades. EFSA heavy-metal thresholds and EU Green Deal lifecycle mandates force European beet processors to absorb 15-20% virgin carbon premiums while Brazilian cane refineries exploit volume-scale contracts to offset fixed-bed granular system capex.
Pricing Analysis
Volume-discount tiering structures separate multinational refiners consuming 500+ tons annually from regional processors dependent on spot-market procurement. Three-tier pricing stratification across FSSC 22000-certified premium grades, ISO 9001-compliant standard tiers, and economy coal-based alternatives reflects certification investment and regeneration-cycle guarantees. Pricing pressure stems from coconut-shell feedstock volatility in Southeast Asian sourcing regions. Regional beet cooperatives exhibit highest price sensitivity due to seasonal campaign intensity, while Brazilian flex-plant operators prioritize guaranteed regeneration minimums over unit cost.
Supply Chain Analysis
Inventory buffers and extended lead times characterize procurement planning for Southeast Asian coconut-shell feedstock exposed to monsoon-driven supply interruptions. Raw material sourcing concentrates in Indonesia, Philippines, and Sri Lanka, while reactivation kiln capacity clusters in Germany, United States, and Brazil. The supply chain rests on single-source vulnerability for specialty mesopore-engineered grades and steam-activated coconut-shell variants. Distribution runs through integrated service providers offering kiln-to-kiln tracking for spent carbon returns, with bulk bag logistics dominating high-volume cane refinery deliveries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as Brazilian ethanol-sugar flex plant capacity expansion drives granular carbon system deployment and regeneration service demand. EFSA regulatory tightening and EU Carbon Border Adjustment implementation create sustained procurement momentum for certified regenerable grades.
For Market Incumbents: Fortify reactivation infrastructure ownership through captive kiln additions in Ribeirão Preto and Magdeburg industrial corridors to defend against third-party service unbundling. Accelerate FSSC 22000 dual certification investments to disqualify non-compliant suppliers from European beet procurement. Secure long-term coconut-shell feedstock offtake agreements to mitigate Southeast Asian supply volatility.
For New Entrants and Emerging Players: Reactivation technician training and certification program gaps present white-space opportunities where incumbents under-serve expanding facility networks. Target Indian Uttar Pradesh and Maharashtra processing cooperatives modernizing filtration infrastructure with granular system partnerships. Penetrate corn syrup purification applications through extruded pellet geometries optimized for pressure-drop specifications in continuous flow reactors.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed reactivation service providers lacking chain-of-custody documentation capabilities for EFSA compliance. Five-to-ten year viability hinges on EU Green Deal enforcement trajectory and Brazilian flex-plant capacity expansion sustainability. Monitor ANVISA alignment with EFSA heavy-metal thresholds as inflection indicator for South American certification-driven procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Reactivation Infrastructure Expansion | Captive kiln additions in São Paulo and Lower Saxony secure regeneration-cycle guarantees for flex-plant and beet processor contracts. |
| Feedstock Backward Integration | Direct coconut-shell sourcing partnerships in Indonesian processing regions mitigate Southeast Asian supply concentration risk. |
| Certification Program Investment | FSSC 22000 and ISO 9001 dual certification gates European procurement among EFSA-compliant supplier pools. |
| Service Unbundling Partnership | Separate virgin carbon supply and spent-carbon processing contracts optimize unit economics for Gulf Coast refineries. |
| Application Expansion into Corn Syrup | Extruded pellet geometries penetrate high-fructose continuous flow reactors previously excluding activated carbon formats. |
Research Methodology
A spread of perspectives from sugar refinery procurement directors, carbon reactivation kiln operators, EFSA regulatory affairs consultants, and coconut-shell feedstock traders converged on the working assumptions. Primary interviews with FSSC 22000 certification auditors and beet campaign operations managers combined with secondary validation through EU Green Deal implementation documents, ANVISA food-contact regulations, and Brazilian Center-South crushing statistics. Bottom-up granular carbon consumption estimates and top-down sugar processing capacity analysis triangulated market sizing.
Segmentation dimensions modeled include product format (powdered, granular, extruded, impregnated), application (cane refining, beet processing, corn syrup purification, bioethanol production), and end-user scale (integrated multinational, regional cooperative, specialty organic). CAGRs were derived from regression analysis of historical procurement patterns and forward projection of regulatory compliance timelines. Forecast inputs incorporated EFSA heavy-metal threshold enforcement schedules and Brazilian flex-plant capacity expansion announcements.
Material uncertainties — coconut-shell feedstock weather disruptions, reactivation technician certification program expansion rates, EU Carbon Border Adjustment implementation scope — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory alignment trajectories and refinery infrastructure modernization cadence. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.