
 Test Rig Market | 2026-2036
Test Rig Market Size, Share, and Industry Trends Forecast 2026-2036
Test Rig Market Outlook
Modular test rig configurations is shifting buyer choice across aerospace and automotive programs. AVL dominates engine and powertrain testing systems through its integrated platform approach. ETA Technology specializes in custom pneumatic and hydraulic rigs for Indian defense and research institutions. Dynaspede anchors southern India's automation test rig supply with servo-controlled dynamometer systems.
A test rig comprises a purpose-built mechanical, hydraulic, pneumatic, or electrical assembly designed to apply controlled loads, pressures, torques, or environmental conditions to a component or complete product under repeatable test protocols, typically incorporating load cells rated to specific force ranges, multi-channel data acquisition sampling at kilohertz frequencies, and programmable logic controllers for test sequence automation. Hydraulic test rigs occupy the largest product segment due to their capacity for high-force structural and fatigue testing in aerospace and energy applications, while data acquisition systems represent the fastest-growing technology segment as manufacturers integrate real-time analytics and cloud-connected diagnostics into legacy mechanical platforms. Automation technology is displacing manual test sequences in quality assurance labs, compressing cycle times and reducing operator-dependent variability in pass-fail determinations.
The EPA enforces emissions verification protocols that mandate specific test cell configurations and calibration traceability for automotive certification, while ISO publishes load cell and force measurement standards that define accuracy classes and environmental performance envelopes. Germany's KBA references UN ECE regulations requiring documented test rig capability for type approval of vehicle components. Stakeholders must monitor how AI-driven predictive maintenance integration reshapes capital allocation between new rig purchases and retrofit automation upgrades.
Market Dynamics
Automation technology is compressing test cycle times across quality assurance labs while displacing manual sequences that introduced operator-dependent variability in pass-fail determinations. This structural shift is redrawing capital allocation between new rig purchases and retrofit automation upgrades.
Growth Catalysts
- EPA emissions verification protocols:The EPA mandates specific test cell configurations and calibration traceability for automotive certification, forcing manufacturers to upgrade rig capabilities.
- China's industrial equipment testing sector:Domestic manufacturers are upgrading quality assurance capabilities, concentrating demand for advanced test rig systems.
- Modular test rig configurations:Aerospace and automotive programs are shifting buyer preference toward reconfigurable platforms that accommodate evolving test protocols.
Market Restraints
- High-force hydraulic component costs:Structural and fatigue testing applications require specialized hydraulic systems where input material volatility constrains margin flexibility.
- German automotive testing concentration:Procurement expansion by Germany's KBA-referenced programs creates geographic demand concentration risk for suppliers.
- ISO load cell calibration complexity:Tightening accuracy classes and environmental performance envelopes extend certification timelines and technical qualification requirements.
Strategic Opportunities
- Indian defense and research institutions:Custom pneumatic and hydraulic rig demand from this underpenetrated buyer segment offers white space for specialized suppliers.
- Cloud-connected diagnostics convergence:Real-time analytics integration with legacy mechanical platforms is opening retrofit revenue streams.
- PLI scheme incentives:India's production-linked incentive framework supports domestic testing infrastructure investment for industrial equipment validation.
Industry Challenges
- Kilohertz-frequency data acquisition expertise:Multi-channel sampling specialists remain scarce, constraining rig commissioning speed.
- UN ECE type approval documentation:Component manufacturers face extended timelines to demonstrate documented test rig capability for vehicle certification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Test Rig Market |
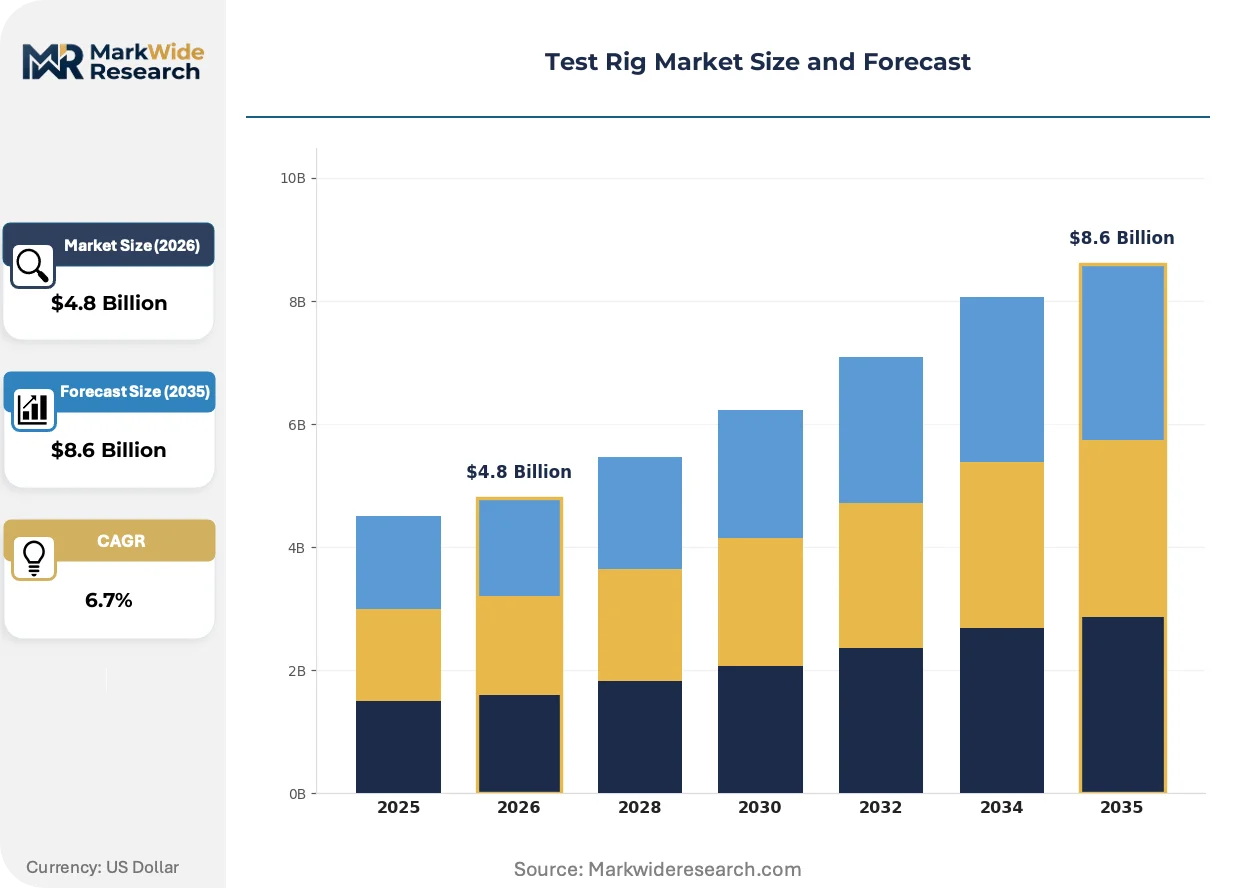
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Hydraulic Test Rigs, Pneumatic Test Rigs, Electrical Test Rigs, Mechanical Test Rigs Application: Aerospace Engineering, Automotive Testing, Energy Sector Testing, Industrial Equipment Testing Technology: Load Cell Technology, Data Acquisition Systems, Automation Technology, Simulator Technology End User: Manufacturers, Research Institutions, Quality Assurance Labs, Military |
| Companies Covered | Formrite Precision, Dynaspede, Averna, Servo Enterprises, Eltecon Engineering Services, ETA Technology, Technomech, Mechanica Systems, AVL, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Test Rig Market Strategic Shifts
Real-time analytics and predictive maintenance integration are rewriting how test rig operators extract value from capital equipment. These capabilities are shifting competitive advantage from hardware specifications to software-enabled uptime guarantees.
Cloud-connected diagnostics is rewriting the economics of legacy platform lifecycle management. Automotive and aerospace quality labs are adopting these retrofit modules faster than full rig replacement cycles. This technology is rewriting supplier relationships by embedding continuous service revenue into one-time equipment sales.
The EPA's tightening emissions verification protocols are mandating documented calibration traceability chains that extend back to NIST-recognized standards. Test cell operators must now maintain audit-ready documentation packages. Heavy-duty engine certification programs in the United States are responding by consolidating supplier relationships around vendors with embedded compliance architecture.
Buyer preference is pivoting toward integrated platform approaches that bundle hardware, software, and ongoing calibration services. Traditional equipment-only vendors are losing share to suppliers offering outcome-based uptime contracts. This shift is most visible in German automotive testing programs where procurement teams now evaluate total cost of validation rather than capital expenditure alone.
Test Rig Market Segmentation
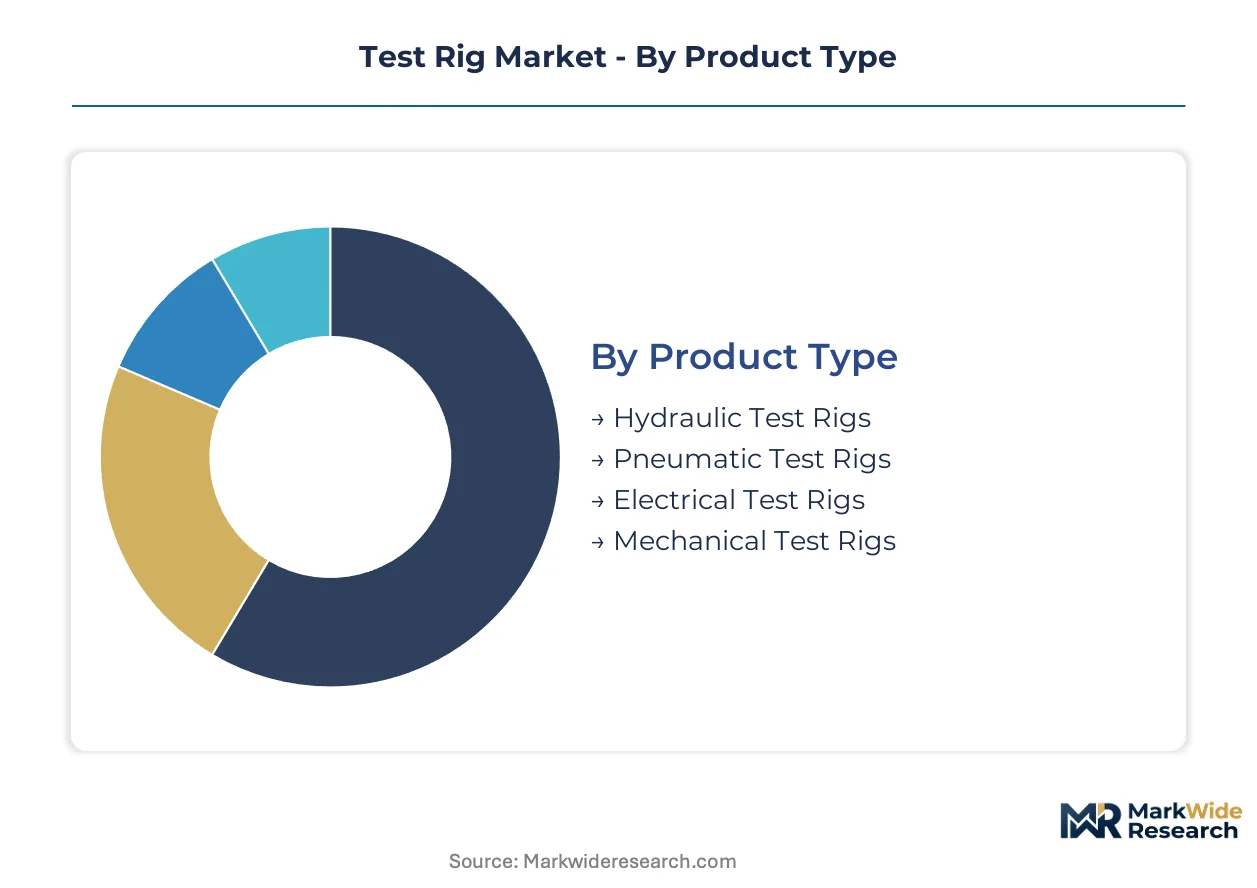
Test rig procurement patterns diverge sharply between high-force structural validation and precision component testing. Understanding these splits enables suppliers to align R&D investment with where buyers actually commit capital.
Product Type:
Hydraulic systems command premium pricing due to force capacity requirements, while electrical rigs scale through volume deployment in electronics manufacturing.
- Hydraulic Test Rigs:These assemblies deploy high-pressure fluid circuits to generate controlled forces exceeding 500 kN for structural fatigue and load-bearing validation. Aerospace wing box testing in Germany and wind turbine blade certification in Denmark concentrate demand where ISO 7500-1 force calibration mandates apply. Material input volatility for specialized hydraulic cylinders constrains supplier margin flexibility.
- Data Acquisition Systems:Multi-channel sampling architectures operating at kilohertz frequencies capture transient phenomena during dynamic load applications. China's industrial equipment upgrading programs and US automotive emissions verification protocols are driving replacement of legacy analog recording systems with digital platforms. Cloud-connected diagnostics integration is accelerating retrofit demand faster than new rig attachment rates.
- Pneumatic Test Rigs:Compressed air systems deliver rapid cycle testing for seals, valves, and pressure vessels where cleanliness requirements exclude hydraulic fluids.
- Electrical Test Rigs:Servo-electric actuators provide precision positioning for electronics and medical device validation with lower maintenance overhead than fluid power alternatives.
- Mechanical Test Rigs:Screw-driven and cam-based systems persist in educational settings and simple pass-fail applications where capital constraints override automation priorities.
Mature deployment sits with hydraulic test rigs in established aerospace and energy certification programs. Newer deployment is concentrated in data acquisition system retrofits upgrading legacy mechanical platforms.
Application:
End-use concentration follows regulatory intensity, with emissions compliance and flight safety mandates creating non-discretionary procurement.
- Automotive Testing:Powertrain durability, brake validation, and chassis fatigue programs require rigs capable of reproducing road load spectra across millions of cycles. EPA emissions verification protocols and UN ECE type approval requirements in Germany are consolidating supplier relationships around vendors with embedded compliance documentation. The shift toward electric powertrains is reshaping test protocols away from engine dynamometers toward battery pack and e-axle validation systems.
- Aerospace Engineering:Full-scale structural testing of fuselage sections and control surfaces demands hydraulic rigs with multi-actuator coordination and real-time load control. FAA certification requirements and EASA CS-25 airworthiness standards mandate documented calibration traceability that extends equipment replacement cycles.
- Energy Sector Testing:Wind turbine blade fatigue, oil wellhead pressure validation, and nuclear component qualification require specialized environmental chambers combined with mechanical loading.
- Industrial Equipment Testing:Construction machinery, agricultural implements, and material handling systems undergo structural validation against ISO and national standards.
Capital intensity peaks in aerospace engineering where single test campaigns span months. Fastest volume expansion is occurring in automotive testing as electrification forces protocol redevelopment.
Technology:
Hardware-software integration depth separates premium suppliers from commodity equipment vendors.
- Automation Technology:Programmable logic controllers and robotic handling systems eliminate operator-dependent variability in quality assurance sequences. German automotive testing programs and Japanese precision manufacturing facilities are deploying lights-out validation cells that compress cycle times.
- Load Cell Technology:Strain gauge and piezoelectric force transducers rated to specific accuracy classes per ISO 376 provide the measurement foundation for all quantitative testing. Aerospace and metrology laboratories drive demand for the highest accuracy tiers.
- Simulator Technology:Hardware-in-the-loop systems combine physical rigs with real-time computational models to test components against virtual operating environments.
Proven deployment concentrates in load cell technology where calibration infrastructure amortizes over decades. Emerging deployment clusters around automation technology as labor cost arbitrage loses effectiveness against quality consistency requirements.
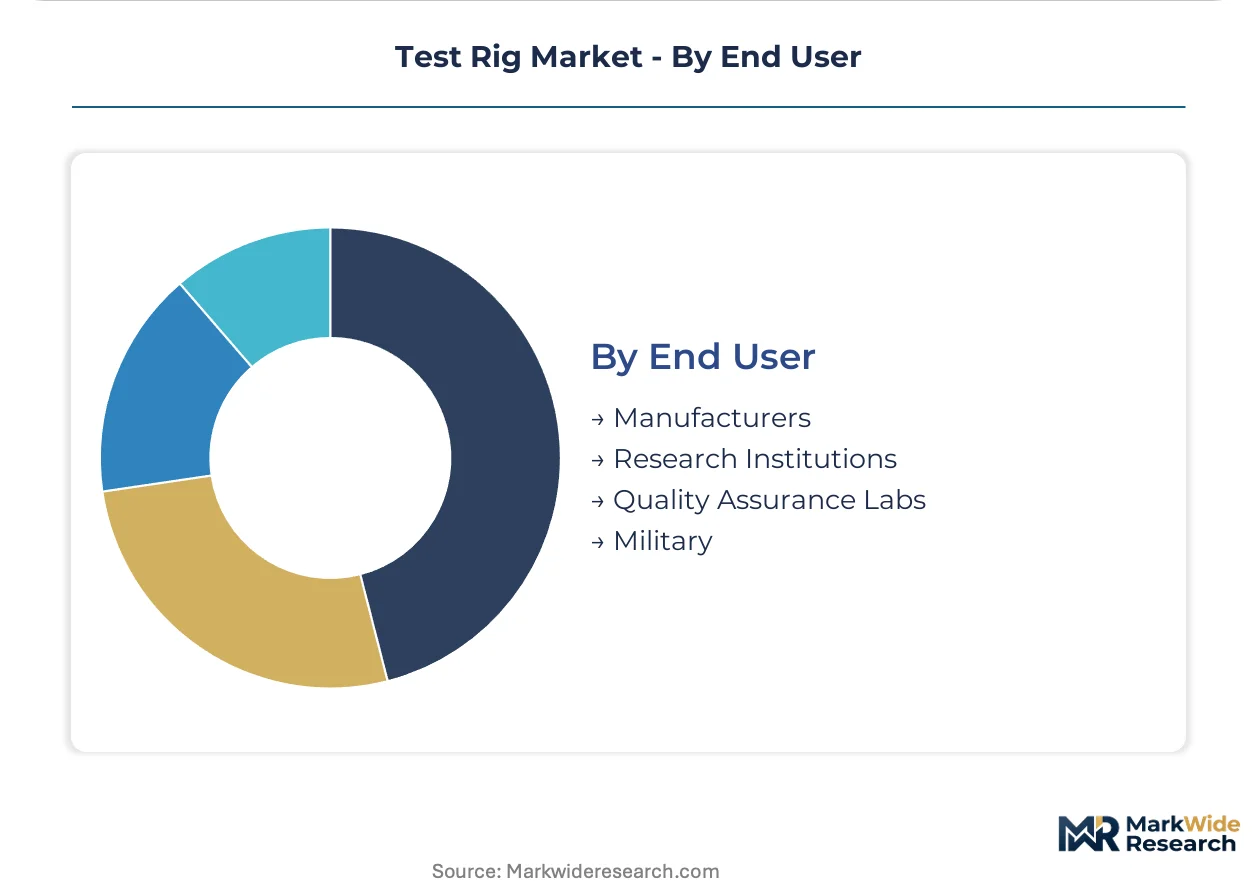
End User:
Procurement authority splits between production-integrated validation and independent third-party certification.
- Quality Assurance Labs:Independent testing facilities serving multiple industrial clients require modular rig configurations that reconfigure across contract portfolios. ISO 17025 accreditation requirements drive investment in documented measurement uncertainty and inter-laboratory comparison programs.
- Manufacturers:In-house validation departments at automotive OEMs and tier suppliers prioritize throughput and integration with production scheduling systems.
- Research Institutions:Universities and national laboratories pursue novel testing methodologies with less emphasis on cycle time optimization.
- Military:Defense procurement specifications emphasize ruggedization and security compliance over commercial performance metrics.
Established procurement volume rests with manufacturers integrating testing into production workflows. Fastest contract value growth is appearing in quality assurance labs as outsourcing of validation functions accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive testing programs consume substantial hydraulic rig capacity, while China's industrial upgrading drives fastest procurement expansion. Production concentrates among German precision fabricators and US aerospace suppliers, with India emerging as a cost-optimized assembly location.
United States
The EPA enforces emissions verification protocols mandating specific test cell configurations for heavy-duty engine certification. NHTSA references UN ECE regulations requiring documented rig capability for vehicle component type approval. Detroit's automotive engineering clusters and Wichita's aerospace testing facilities anchor domestic demand for structural fatigue and powertrain validation systems.
Germany
KBA-administered type approval programs require test rig documentation extending calibration traceability to NIST-recognized standards. The country's national automotive regulator tightens certification timelines for emissions compliance equipment. Stuttgart's powertrain engineering corridor and Hamburg's maritime testing institutes concentrate procurement of multi-actuator hydraulic systems.
China
Domestic manufacturers upgrade quality assurance capabilities across industrial equipment and automotive component sectors. MIIT enforces GB standards for force measurement equipment used in machinery certification. Shanghai's robotics validation labs and Shenzhen's electronics testing facilities drive data acquisition system retrofit demand.
India
Defense procurement specifications and research institution budgets concentrate demand for custom pneumatic and hydraulic configurations. The PLI scheme incentivizes domestic testing infrastructure investment for industrial equipment validation. Bangalore's aerospace research complexes and Pune's automotive component clusters anchor regional procurement.
Japan
Precision manufacturing facilities deploy lights-out validation cells compressing quality assurance cycle times. METI promotes JIS standards adoption for load cell calibration in automotive and electronics testing. Nagoya's automotive engineering belt and Osaka's industrial machinery districts sustain demand for servo-controlled dynamometer systems.
Test Rig Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across the test rig market structure. The vendor base stratifies into three tiers: integrated platform providers bundling hardware-software-service offerings, component specialists supplying load cells and data acquisition modules, and regional fabricators serving localized certification requirements. Consolidation pressures favor vendors with embedded compliance documentation capabilities. Dominant competitive moves include strategic partnerships with cloud diagnostics providers and geographic expansion into underpenetrated defense procurement markets.
Within the integrated platform tier, AVL anchors European engine and powertrain testing systems through its bundled service approach. ETA Technology occupies a position among Indian specialists serving defense and research institution demand for custom configurations. Dynaspede exemplifies the regional fabrication archetype, anchoring southern India's automation test rig supply with servo-controlled systems. These three represent distinct strategic postures: global platform integration, national specialization, and regional manufacturing scale.
| Leading Market Players |
|---|
| Formrite Precision |
| Dynaspede |
| Averna |
| Servo Enterprises |
| Eltecon Engineering Services |
| ETA Technology |
| Technomech |
| Mechanica Systems |
| AVL |
| Others |
Value Chain & Pricing Dynamics
Family-owned mid-cap fabricators across Germany and Japan anchor precision component supply, translating concentrated engineering heritage into pricing discipline that resists commoditization despite input cost volatility. Their long-tenured relationships with aerospace certification bodies create switching costs that insulate margin structures from aggressive Asian competition.
Pricing Analysis
Margin tightening in hydraulic system tiers reflects specialized cylinder material volatility and extended ISO 7500-1 calibration timelines. Three-tier pricing structure across premium, standard, and economy levels separates AVL-integrated platforms from regional fabricators like Dynaspede, with certification grade and after-sales service bundling as primary differentiation drivers. Cost-down pressure accelerates as Chinese industrial buyers consolidate procurement around documented traceability chains. Quality assurance labs exhibit highest price sensitivity due to ISO 17025 accreditation compliance costs, while military procurement demonstrates lowest sensitivity given ruggedization mandates.
Supply Chain Analysis
Regional distribution centers in Stuttgart, Detroit, and Shanghai coordinate hub-and-spoke patterns for multi-actuator hydraulic systems and kilohertz-frequency data acquisition modules. Manufacturing concentrates in Germany, the United States, and China, with India emerging as cost-optimized assembly location under PLI scheme incentives. Specialized hydraulic cylinders, strain gauge load cells, and servo-electric actuators feed from concentrated precision metalworking clusters. Single-source vulnerability in high-force hydraulic component supply creates structural risk. Distribution runs through OEM-direct channels for integrated platforms and specialized distributors for modular retrofit components.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
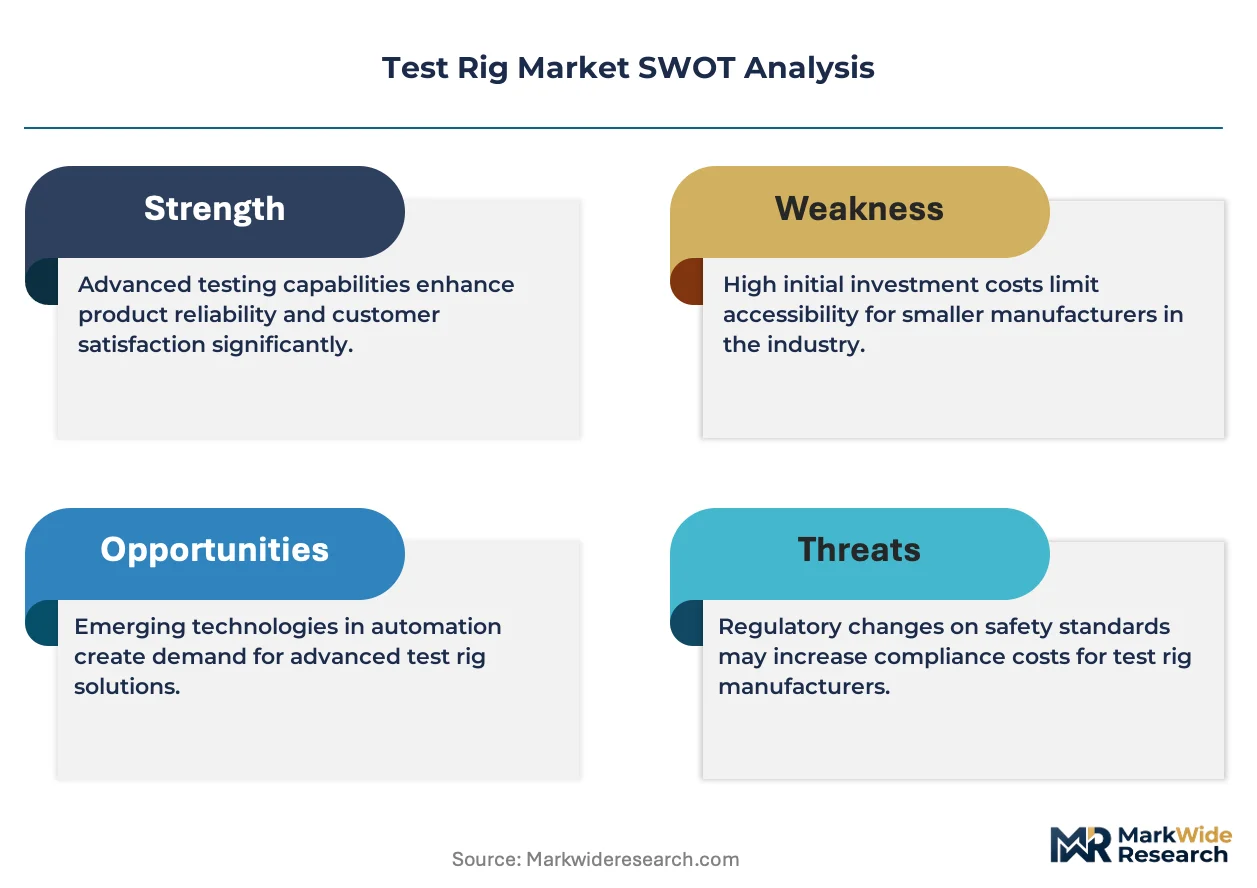
This market functions as a cost-of-compliance story where EPA emissions verification protocols and UN ECE type approval requirements erect barrier-to-entry moats favoring vendors with embedded documentation architecture.
For Market Incumbents: Hedge against cloud-connected diagnostics disruption by acquiring real-time analytics specialists before retrofit revenue streams consolidate around platform-integrated competitors. Deepen backward integration into load cell calibration infrastructure to defend margin position against ISO 376 accuracy class tightening. Capacity expansion in India's defense procurement corridor captures PLI-supported infrastructure investment. For New Entrants and Emerging Players: Launch via modular data acquisition retrofit partnerships with established hydraulic rig operators seeking kilohertz-frequency sampling upgrades without full platform replacement. Target quality assurance labs in China's industrial equipment upgrading programs as most penetrable segment, where ISO 17025 accreditation drives documented measurement uncertainty investment. Pursue white-space in Indian research institution custom pneumatic configurations where ETA Technology's specialization leaves price-competitive gaps. For Investors and Strategic Acquirers: Consolidation of supplier relationships around EPA-compliant vendors with embedded calibration traceability is the leading indicator that platform-integrated players will capture disproportionate value expansion. Five-to-ten year viability favors vendors bundling hardware-software-service offerings over equipment-only specialists. Acquisition target archetype: regional fabricators with proven servo-controlled dynamometer systems and latent cloud diagnostics integration capability. Signal to monitor: AI-driven predictive maintenance contract penetration rates in German automotive testing programs.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Diagnostics Integration | Retrofit revenue streams rewrite legacy platform economics for AVL and ETA Technology customers. |
| Backward Integration into Load Cells | Captive supply of ISO 376-calibrated force transducers defends margin against certification complexity. |
| Defense Procurement Specialization | Custom pneumatic and hydraulic configurations for Indian military specifications open underpenetrated demand. |
| PLI-Aligned Capacity Expansion | Domestic testing infrastructure investment in India accelerates under production-linked incentive frameworks. |
| Predictive Maintenance Platform Launch | AI-enabled uptime guarantees shift competitive advantage from hardware specifications to software outcomes. |
Study Parameters
SEC 10-K filings, EPA certification documentation, and ISO standard revision records formed the secondary backbone, cross-referenced with customs data on hydraulic component trade flows. Primary interviews with test rig procurement managers at automotive OEMs, quality assurance lab directors, calibration service technicians, and defense procurement officers validated demand assumptions. Bottom-up rig deployment counts triangulated against top-down industrial equipment capital expenditure patterns.
Bottom-up modeling aggregated individual rig configurations by force capacity, channel count, and automation tier across the projection horizon. Segmentation dimensions included product type, application intensity, technology integration depth, and end-user procurement authority. CAGRs derived from regression analysis of historical replacement cycles against regulatory compliance deadline clustering. Industry-specific inputs encompassed EPA emissions verification protocol revision schedules and MIIT GB standards enforcement timelines.
Regulatory deadline delays, raw material input volatility in specialized hydraulic cylinders, and cloud diagnostics adoption rate variance are the dominant revision risks to modeled outputs. Forecasts reflect documented assumption sets regarding compliance timeline adherence and technology substitution elasticities. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Metrology Services Market
Test and Measurement
Asia-Pacific Laser Interferometer Market
Test and Measurement
Pump Testers Market
Test and Measurement
Ohm Meter Market
Test and Measurement
Industrial X-Ray Inspection System Market
Test and Measurement
Digital Height Gauges Market
Test and Measurement
Optical Wafer Inspection Systems Market
Test and Measurement
Duct Integrity Tester (DIT) Market
Test and Measurement
Test and Measurement Sensors Market
Test and Measurement
Gigabit Ethernet Test Equipment Market
Test and Measurement
Hardware-Assisted Verification Market
Test and Measurement
Shape Measuring Devices Market
Test and Measurement
Micro Ohmmeter Market
Test and Measurement
Shock Test Machines Market
Test and Measurement
One-Box Testers Market
Test and Measurement
Non-Destructive Testing Market