

Cooling Laser Power Measurement Sphere Market Size, Share, and Industry Trends Forecast 2026-2036
Cooling Laser Power Measurement Sphere Market Insights
Modular sensor-head architecture is pivoting buyer choice away from monolithic sphere systems toward field-swappable detector configurations. Gentec-EO leverages this shift by offering calibrated thermal modules that integrate across multiple sphere diameters. Labsphere anchors its position through in-house production of high-reflectance coatings that control spectral uniformity. Ophir Optronics Solution competes on software-defined measurement workflows that reduce calibration cycle times.
A cooling laser power measurement sphere is a hollow, thermally stabilized optical enclosure lined with diffuse reflecting material, typically Spectralon or barium sulfate, designed to capture and homogenize high-power laser beams for accurate total power determination; liquid cooling channels machined into the sphere wall maintain thermal equilibrium during continuous-wave measurements exceeding kilowatt levels, preventing detector saturation and ensuring traceability to NIST or PTB standards. Integrating sphere configurations dominate installed base revenue due to their universality across wavelengths, while photodiode sensors represent the fastest-expanding product category driven by pulsed laser diagnostics in medical device calibration. Thermal sensor technology leads in absolute accuracy for materials processing applications, whereas semiconductor sensors capture margin pools in compact OEM-embedded designs.
FDA 21 CFR Part 1040 laser performance standards and the EU Machinery Directive's EN 60825 safety classifications shape product design by mandating verified power measurement protocols before commercial laser system deployment. China's GB 7247.1 laser safety standard, administered by SAMR, requires domestic manufacturers to use traceable power measurement equipment for factory acceptance testing. Stakeholders must monitor how IEC 60825-14's forthcoming revisions address cooled-sphere calibration intervals for ultrafast lasers.
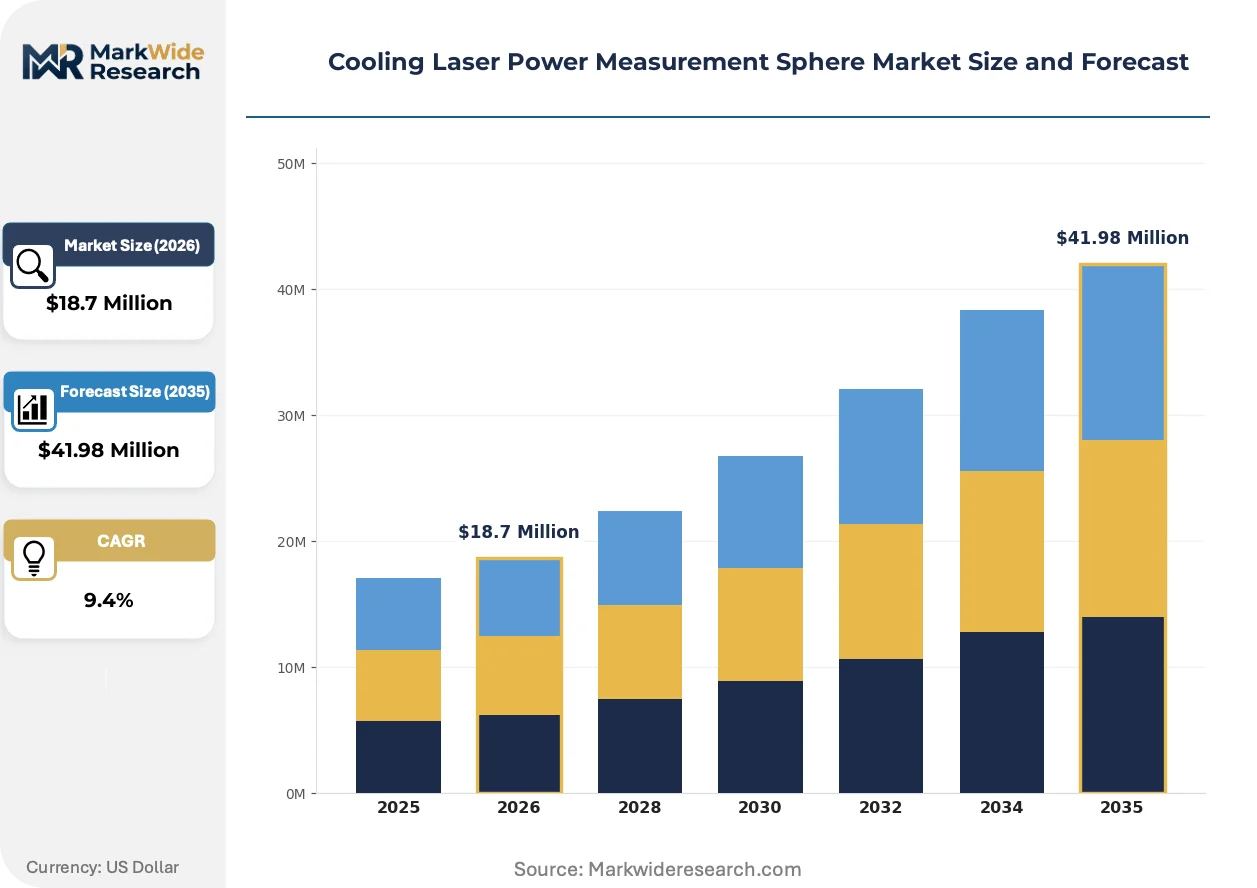
Market Dynamics
Semiconductor fabs are expanding metrology budgets as EUV lithography systems demand tighter thermal stability in power verification, redirecting procurement toward liquid-cooled measurement architectures.
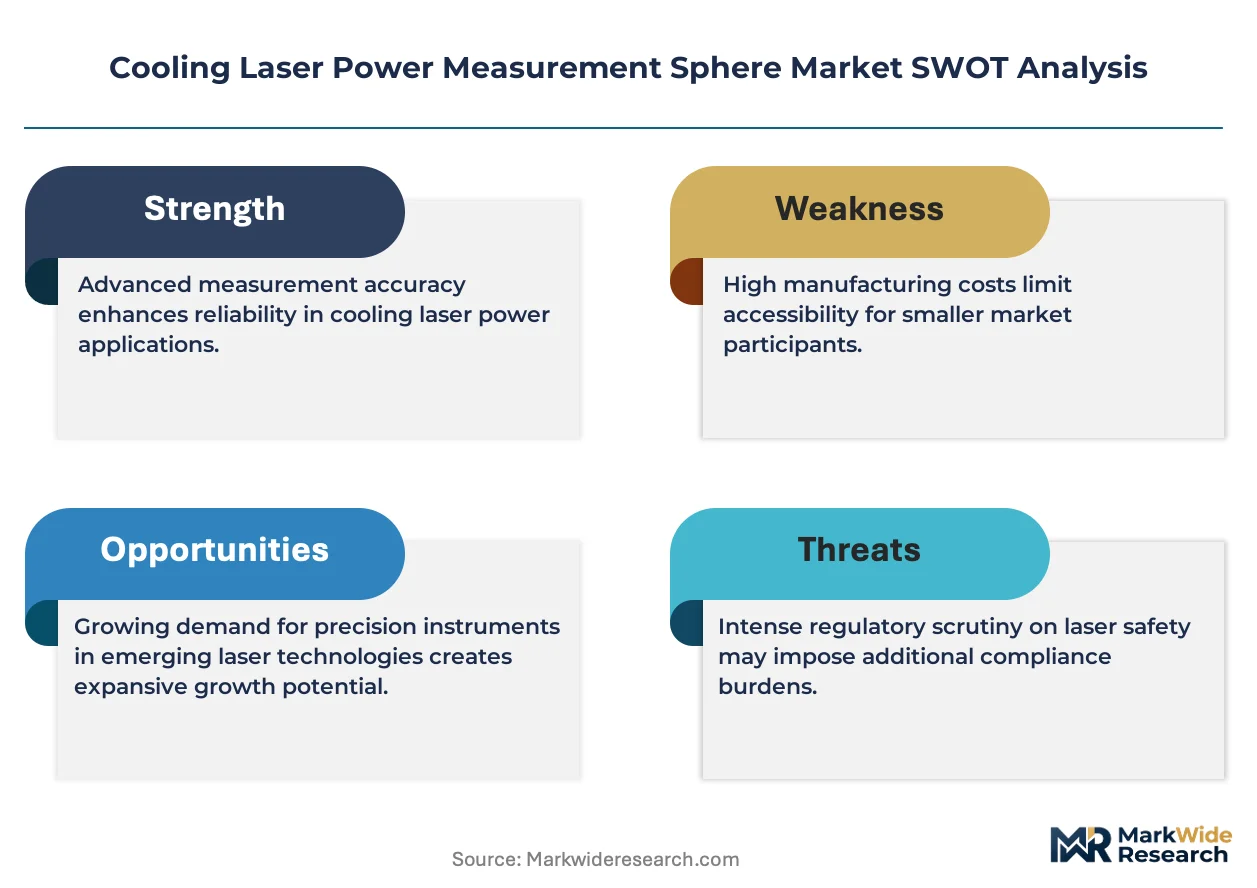
Growth Catalysts
- EUV Lithography Metrology:Semiconductor fabrication facilities require calibrated spheres for high-power fiber laser qualification as node sizes shrink below 3nm.
- China's Dual Carbon Goals:Industrial laser efficiency mandates under MEE directives redirect state procurement toward liquid-cooled measurement architectures.
- Spectralon Coating Advances:High-reflectance diffuse materials now maintain uniformity across ultraviolet to infrared wavelengths, expanding addressable applications.
Market Restraints
- Barium Sulfate Supply Concentration:Coating precursor production clusters in select German and Chinese chemical hubs create input vulnerability.
- NIST Traceability Costs:Calibration protocols for ultrafast lasers under IEC 60825-14 revisions extend certification timelines and laboratory overhead.
- Photodiode Substitution:Compact semiconductor sensors capture margin pools in OEM-embedded designs below 500W measurement thresholds.
Strategic Opportunities
- Medical Device Calibration:Pulsed laser diagnostics in surgical equipment manufacturing creates demand for field-swappable detector configurations.
- Software-Defined Workflows:Automated calibration cycle reduction through integrated measurement software opens service revenue streams.
- India's PLI Scheme:Domestic laser system manufacturing incentives under the production-linked initiative build local metrology infrastructure demand.
Industry Challenges
- Thermal Modeling Expertise:Computational fluid dynamics simulation for liquid cooling channel design requires scarce cross-trained optical and mechanical engineers.
- Legacy Sphere Integration:Retrofitting field-swappable thermal modules into installed monolithic systems demands custom mechanical adapters.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooling Laser Power Measurement Sphere Market Trends and Innovations
Modular sensor-head architecture is pivoting buyer choice away from monolithic systems, compressing replacement cycles and enabling vendor-agnostic component sourcing across sphere diameters.
Integrating sphere configurations dominate installed base revenue due to their universality across wavelengths. Photodiode sensors represent the fastest-expanding product category driven by pulsed laser diagnostics requirements. Thermal sensor technology leads in absolute accuracy for materials processing applications.
FDA 21 CFR Part 1040 laser performance standards and the EU Machinery Directive's EN 60825 safety classifications shape product design by mandating verified power measurement protocols. China's GB 7247.1 standard administered by SAMR requires domestic manufacturers to use traceable power measurement equipment. Stakeholders must monitor IEC 60825-14's forthcoming revisions addressing cooled-sphere calibration intervals.
Buyers in Germany's precision optics cluster around Jena and Oberkochen increasingly specify calibrated spheres with software-defined measurement workflows. OEM procurement teams compress vendor qualification timelines by demanding pre-certified thermal modules compatible across multiple sphere diameters. This pattern concentrates most acutely in fiber laser qualification programs for automotive welding applications.
Cooling Laser Power Measurement Sphere Market Segmentation
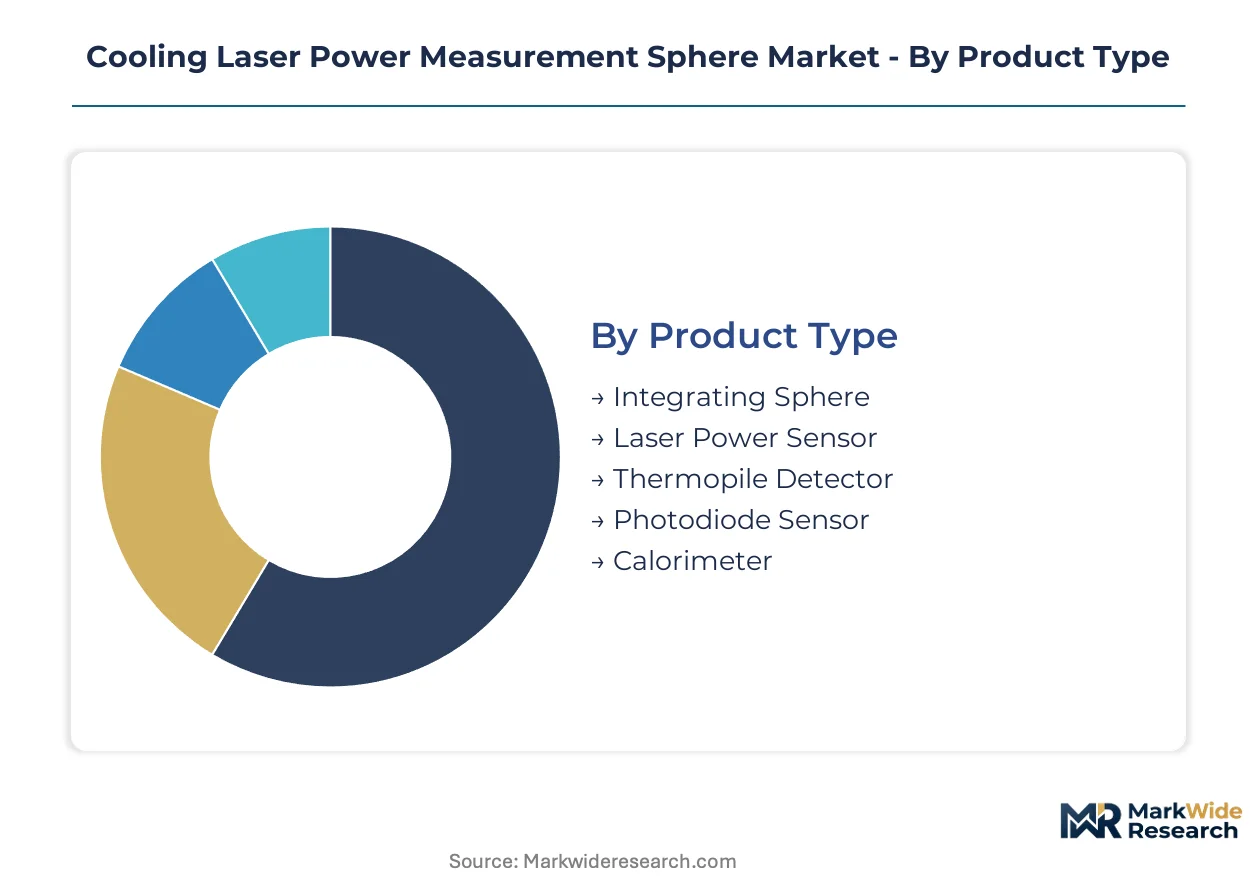
Segmentation in the cooling laser power measurement sphere market reveals distinct upgrade cycles across hardware categories. Procurement teams prioritize field-swappable architectures that extend equipment lifespan without full system replacement.
Product Type:
Replacement cycles accelerate where modular designs allow sensor-head upgrades without sphere replacement, compressing refresh timelines for high-throughput facilities.
- Integrating Sphere:Hollow optical enclosures lined with Spectralon or barium sulfate diffuse reflecting material maintain thermal equilibrium through liquid-cooled wall channels. Semiconductor fabs in Germany's precision optics cluster specify these for EUV lithography power verification as node sizes shrink below 3nm.
- Laser Power Sensor:Modular detector units designed for field-swappable integration across multiple sphere diameters. OEM procurement teams in China's laser manufacturing bases demand pre-certified thermal modules compatible with existing installations under MEE efficiency mandates.
- Thermopile Detector:Thermal conversion elements measuring radiant power through temperature differential across junction arrays.
- Photodiode Sensor:Semiconductor-based detection for pulsed laser diagnostics in medical device manufacturing.
- Calorimeter:Absolute power measurement through thermal mass temperature rise, preferred for NIST-traceable certification protocols.
Integrating Sphere configurations sit at the top of the volume ranking, with Photodiode Sensor climbing the fastest.
Technology:
Cost tiers separate absolute-accuracy thermal platforms from compact semiconductor alternatives serving embedded OEM designs below 500W thresholds.
- Thermal Sensor:Thermoelectric or thermopile elements delivering NIST-traceable absolute accuracy for materials processing applications. Automotive welding qualification programs in Germany's Jena-Oberkochen corridor specify these for fiber laser power verification requiring continuous-wave stability.
- Semiconductor Sensor:Silicon or InGaAs photodiode arrays capturing margin pools in compact OEM-embedded designs. Electronics manufacturers in China's domestic laser system supply chain integrate these under SAMR-administered GB 7247.1 factory acceptance testing requirements.
- Optical Sensor:Beam position and power monitoring through position-sensitive detector arrays.
- Pyroelectric Sensor:Ferroelectric crystal elements for pulsed energy measurement in surgical equipment calibration.
- Beam Splitter System:Partial reflection sampling for high-power beam attenuation before detector exposure.
Thermal Sensor commands the premium tier by accuracy specification, while Semiconductor Sensor expands most quickly through OEM embedded integration.
Application:
Application concentration follows capital expenditure patterns in precision manufacturing and regulated medical device production.
- Laser Welding:Power verification for automotive and aerospace joining operations requiring thermal stability in multi-kilowatt continuous-wave measurement. German OEMs specify liquid-cooled spheres with software-defined workflows to compress vendor qualification timelines.
- Medical Device Calibration:Pulsed laser diagnostics for surgical equipment manufacturing under FDA 21 CFR Part 1040 performance standards. Field-swappable detector configurations reduce calibration cycle times in contract manufacturing facilities.
- Optical Testing:Spectral power distribution measurement across ultraviolet to infrared wavelengths.
- Communications Equipment Testing:Fiber laser power verification for telecom infrastructure deployment.
- Research & Development:Experimental power measurement in academic and government laboratory settings.
Laser Welding anchors application volume through automotive capital expenditure, with Medical Device Calibration gaining share fastest from regulatory compliance expansion.
End User:
Customer type determines procurement authority and specification complexity, from centralized metrology laboratories to distributed manufacturing quality stations.
- Calibration Laboratories:Accredited facilities performing NIST or PTB-traceable power certification under IEC 60825-14 protocols. Extended certification timelines for ultrafast laser cooled-sphere calibration intervals drive demand for automated software-defined measurement workflows.
- Manufacturing Facilities:In-line power verification stations in semiconductor and industrial laser production environments. China's dual carbon goals redirect state procurement toward liquid-cooled measurement architectures with higher thermal efficiency.
- Research Institutes:Academic and government laboratories requiring universal wavelength coverage.
- Electronics OEMs:Integrated power monitoring in laser system original equipment manufacturing.
- Quality Assurance Centers:Final acceptance testing stations for laser system deployment.
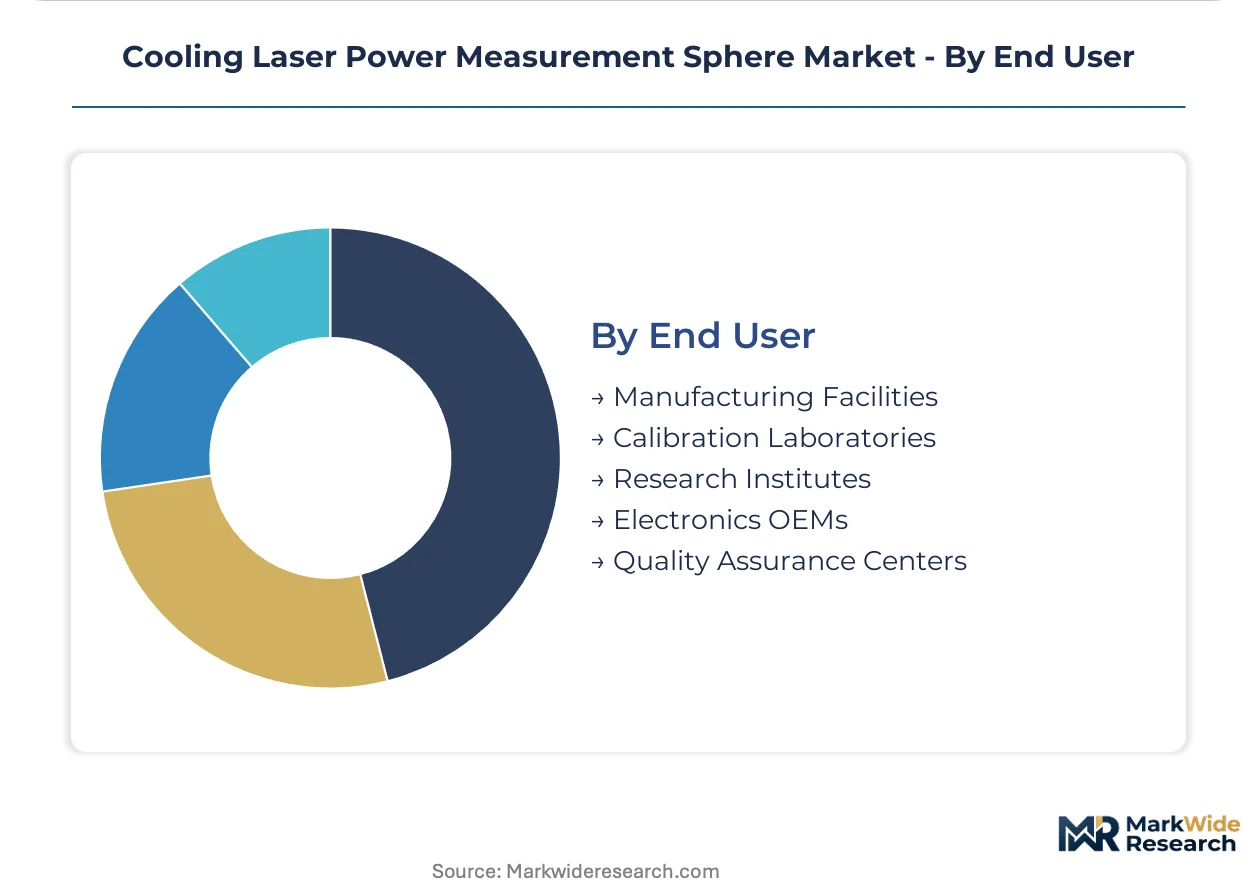
Calibration Laboratories lead end-user volume through regulatory mandate, with Manufacturing Facilities expanding most quickly from industrial laser efficiency requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision optics workshops pioneered integrating sphere metrology during the fiber laser scaling of the 1990s, establishing thermal stabilization protocols that now propagate through EUV lithography supply chains worldwide.
Germany
Automotive fiber laser welding programs and semiconductor metrology drive procurement of liquid-cooled spheres with software-defined workflows. The EU Machinery Directive's EN 60825 safety classifications mandate verified power measurement protocols before commercial deployment. The Jena-Oberkochen precision optics cluster concentrates OEM specification activity for high-power laser qualification systems.
United States
FDA 21 CFR Part 1040 laser performance standards shape medical device calibration demand, while semiconductor fabs expand EUV lithography metrology budgets. The FDA requires verified power measurement protocols for surgical equipment commercialization. Greater Boston and Silicon Valley host concentrated procurement from photonics startups and defense contractors.
China
Industrial laser efficiency mandates under MEE directives redirect state procurement toward liquid-cooled architectures. SAMR-administered GB 7247.1 standards require traceable power measurement equipment for factory acceptance testing. The Yangtze River Delta manufacturing bases concentrate domestic laser system production and metrology infrastructure buildout.
Japan
METI industrial efficiency programs and semiconductor materials processing sustain demand for thermal sensor accuracy. JIS standards govern laser safety equipment certification timelines. The Chubu-Nagoya automotive welding corridor specifies calibrated spheres for multi-kilowatt continuous-wave measurement in production lines.
Cooling Laser Power Measurement Sphere Market Competitive Landscape
The competitive structure tilts toward coating-specialist incumbents with captive diffuse-reflectance material production. Three archetypes populate the vendor map: Spectralon-coating houses controlling spectral uniformity, modular thermal module integrators enabling field-swappable configurations, and software-defined workflow providers compressing calibration cycles. Dominant competitive moves include backward integration into high-reflectance material production and strategic partnerships with semiconductor fab equipment OEMs.
Among North American precision optics houses, Edmund Optics and MKS Instruments exemplify the coating-to-system integration archetype, while Gentec-EO occupies a position within the modular thermal module tier. Labsphere anchors the specialist segment through in-house Spectralon production capabilities. These three represent divergent strategic postures: captive material control, field-configurable hardware platforms, and diffuse-reflectance coating mastery.
| Leading Market Players |
|---|
| Edmund Optics |
| Avantes |
| Shimadzu |
| Labsphere |
| MKS Instruments |
| HORIBA |
| Ophir Optronics Solution |
| Gentec-EO |
| Laser Components |
| Others |
Pricing and Supply Chain Analysis
Semiconductor fab metrology procurement teams in Germany's Jena-Oberkochen corridor anchor pricing power through multi-year framework agreements that lock in thermal module specifications. Their concentration around EUV lithography qualification programs forces vendors into performance-based contracting with liquid-cooled sphere architectures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates NIST-traceable thermal sensor systems from compact semiconductor alternatives. Price differentiation hinges on certification grade (IEC 60825-14 compliance tier) and volume scale (single-unit lab procurement versus fleet purchases by automotive OEMs). Cost compression in the economy tier is intensifying because photodiode substitution below 500W thresholds erodes margin pools. Calibration laboratories exhibit the lowest price sensitivity due to regulatory mandate, while electronics OEMs embedded in China's domestic laser supply chain drive the hardest bargaining.
Supply Chain Analysis
Regional distribution centers in Germany, China, and the United States maintain hub-and-spoke patterns for high-reflectance coating materials and pre-certified thermal modules. Geographic supply concentration rests on Germany's chemical hubs for barium sulfate precursor production, China's Yangtze River Delta manufacturing bases for semiconductor sensor assembly, and US precision optics houses for Spectralon substrate finishing. Raw material dependencies draw from specialized diffuse-reflectance coatings, liquid-cooling channel machining capacity, and detector element foundry output. Single-source vulnerability in barium sulfate supply creates structural exposure. Distribution runs through direct OEM qualification programs and accredited calibration laboratory channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a late-cycle quality story. Demand is pivoting toward premium specifications as EUV lithography node shrinkage below 3nm mandates tighter thermal stability protocols.
For Market Incumbents: Hedge against photodiode substitution by deepening captive control over high-reflectance coating production. Secure backward integration into Spectralon or barium sulfate substrate supply to defend margin position against modular thermal module competitors. Expand capacity addition in Germany's precision optics cluster to anchor automotive fiber laser welding qualification programs.
For New Entrants and Emerging Players: Capture white-space in India's PLI scheme-driven domestic laser system manufacturing, where metrology infrastructure buildout lags production capacity expansion. Target medical device calibration facilities seeking field-swappable detector configurations to reduce FDA 21 CFR Part 1040 compliance cycle times. Lead with software-defined measurement workflow integration as the go-to-market angle.
For Investors and Strategic Acquirers: Semiconductor fab equipment OEMs are the most active acquirer in this space, seeking to bundle metrology capabilities with lithography system sales. Long-term viability rests on coating-specialist positioning with captive diffuse-reflectance material production. Monitor IEC 60825-14 revision timing as the inflection signal for ultrafast laser calibration interval standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Coating Materials | Captive Spectralon production secures spectral uniformity control against German chemical hub concentration. |
| Software-Defined Workflow Development | Automated calibration cycle reduction opens service revenue streams for FDA and EU Machinery Directive compliance. |
| Modular Thermal Module Platform Expansion | Field-swappable configurations across sphere diameters compress replacement cycles for high-throughput facilities. |
| Regional Distribution Hub Establishment | Proximity to China's Yangtze River Delta manufacturing bases reduces logistics exposure for domestic laser system supply chains. |
| Certification Investment for IEC 60825-14 | Pre-positioning for ultrafast laser calibration interval standards captures early-mover advantage in semiconductor metrology. |
Research Methodology
Multiple input streams — technical discussions with semiconductor fab metrology directors, calibration laboratory accreditation officers, and precision optics procurement leads; alongside thermal sensor OEM product managers and industrial laser system integrators — were reconciled against secondary validation. Secondary sources encompassed IEC 60825-14 draft documentation, SAMR-administered GB 7247.1 compliance filings, EU Machinery Directive EN 60825 implementation guidance, and trade data through customs records for high-reflectance coating material flows. Bottom-up equipment installation tracking and top-down metrology budget allocation analysis were triangulated to establish market sizing.
Data-stream reconciliation across the projection horizon applied segment-specific modeling for integrating sphere configurations, laser power sensors, thermopile detectors, photodiode sensors, and calorimeters by technology tier (thermal, semiconductor, optical, pyroelectric, beam splitter). Application dimensions spanned laser welding, medical device calibration, optical testing, communications equipment testing, and research and development. CAGRs were derived from equipment replacement cycle compression rates and capital expenditure patterns in precision manufacturing. Industry-specific forecast inputs incorporated EUV lithography node roadmap acceleration and China's MEE industrial laser efficiency mandate implementation pacing.
Underlying measurement precision varies by segment; integrating sphere and thermal sensor categories carry tighter precision than photodiode sensor estimates due to established NIST-traceable certification protocols. Forecasts reflect documented assumptions around regulatory revision timing and raw material supply concentration. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.