
 Megohmmeters Market | 2026-2036
Megohmmeters Market Size, Share, and Industry Trends Forecast 2026-2036
Megohmmeters Market Outlook
Skilled electrical technician shortages across North American utility fleets is redrawing how megohmmeter vendors structure training and distribution. Fluke Corporation leverages its extensive field service network to embed certification programs directly with contractor fleets. Hioki E.E. Corporation anchors its position in Japanese industrial manufacturing through deep calibration expertise and localized technical support.
A megohmmeter measures electrical insulation resistance by applying a calibrated DC voltage and quantifying leakage current, typically ranging from 250V to 15kV test outputs depending on application requirements. Digital megohmmeters now dominate commercial procurement due to automated data logging and Bluetooth connectivity for asset management integration. Microprocessor controlled technology commands the fastest expansion as utilities demand programmable test sequences and pass-fail automation for compliance testing workflows.
FCC equipment authorization governs wireless-enabled diagnostic tools in the United States, while IEC 61543 shapes insulation tester safety and accuracy benchmarks across European markets. Japan's METI enforces JIS standards that restrict market access for non-compliant instruments. Stakeholders must weigh calibration traceability investments against the shift toward cloud-integrated predictive maintenance platforms.
Market Dynamics
Microprocessor-controlled test automation is compressing replacement cycles across utility and industrial maintenance programs, forcing instrument vendors to embed programmable logic and cloud connectivity as standard features rather than premium add-ons.
Growth Catalysts
- Preventive maintenance mandates:State utilities in India are expanding rural electrification network testing protocols under CEA guidelines, requiring systematic insulation resistance verification at distribution transformers.
- Bluetooth-enabled asset management:Digital megohmmeters with wireless data logging are displacing analog units in Southeast Asian grid infrastructure programs.
- IEC 61543 compliance deadlines:German and Japanese regulators are accelerating instrument replacement cycles through stricter safety and accuracy benchmarks for high-voltage insulation testers.
Market Restraints
- Calibration infrastructure concentration:Traceable calibration services cluster in Japan and Germany, creating service access gaps for utilities in secondary markets.
- Skilled technician scarcity:North American electrical contractor fleets face persistent shortages of certified insulation testing specialists, slowing field deployment of advanced instruments.
- Silicon component volatility:Microprocessor and ADC supply constraints from concentrated Asian semiconductor fabrication are extending lead times for digital unit production.
Strategic Opportunities
- Cloud-integrated predictive maintenance:Utilities in the United States are piloting megohmmeter data streams into FERC-mandated asset health monitoring systems.
- Remote industrial monitoring:Mining and oil & gas operators in Australia are adopting wireless-enabled insulation testers for hazardous environment worker safety.
- Training certification bundling:Field service networks are embedding technician certification programs directly with contractor procurement contracts.
Industry Challenges
- Legacy system integration friction:Microprocessor-controlled units face protocol compatibility barriers with existing utility asset management databases.
- Multi-standard certification timelines:Manufacturers must sequence FCC authorization, IEC 61543 testing, and METI JIS compliance in parallel to avoid market access delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Megohmmeters Market |
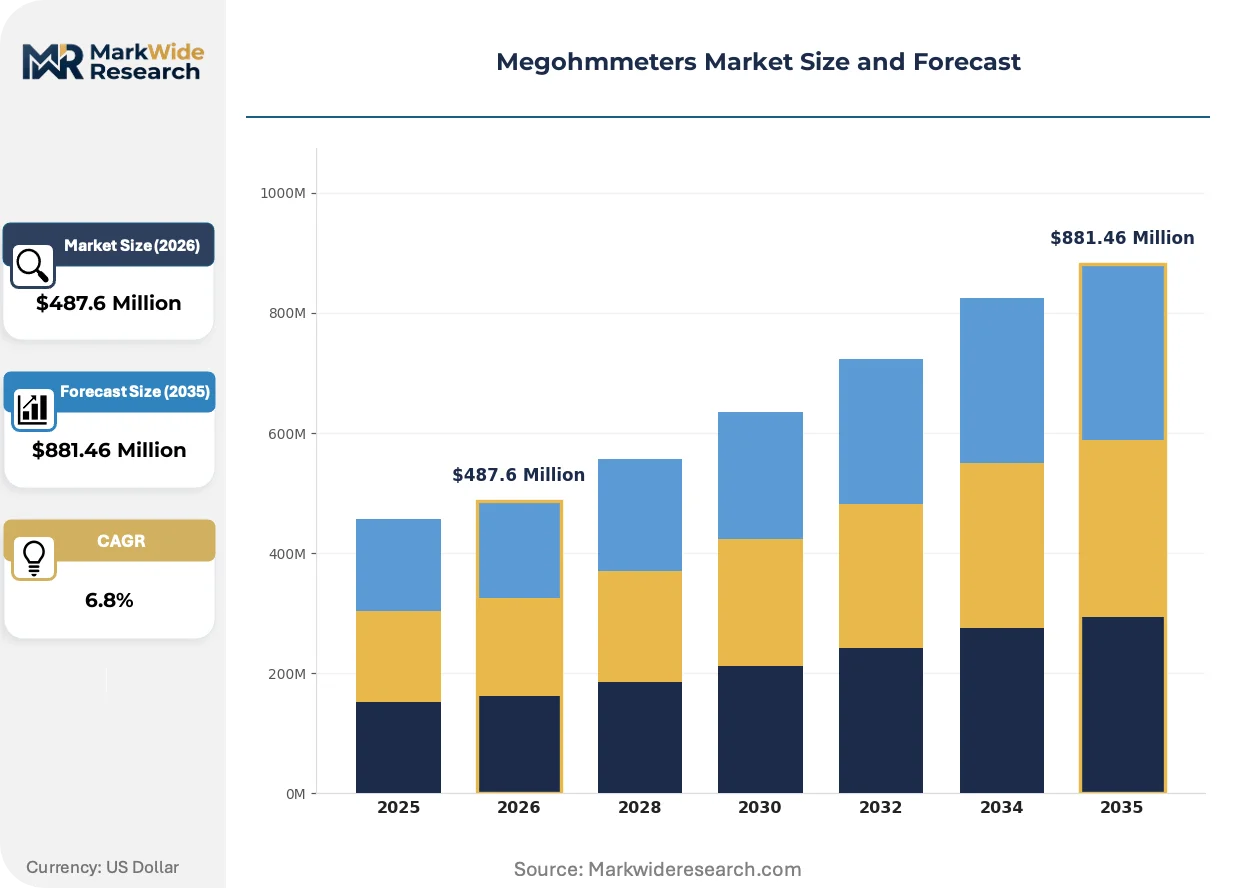
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Digital Megohmmeters, Analog Megohmmeters, Insulation Resistance Testers, High Voltage Megohmmeters Technology: Microprocessor Controlled, Manual, Automatic, RF Technology End User: Electrical Utilities, Industrial Manufacturing, Telecommunications, Aerospace Application: Maintenance Testing, Quality Control, Research & Development, Compliance Testing |
| Companies Covered | Megger Group Limited, Fluke Corporation, Hioki E.E. Corporation, Chauvin Arnoux Group, Kyoritsu Electrical Instruments Works Ltd, Yokogawa Electric Corporation, AEMC Instruments, Extech Instruments, B&K Precision Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Megohmmeters Market Strategic Shifts
Test instrument architecture is converging around embedded connectivity and automated compliance workflows, compressing the gap between field measurement and centralized asset decision-making.
Handheld digital megohmmeters with integrated microprocessors and solid-state voltage generation are miniaturizing traditional bench-top insulation testing capabilities into field-portable formats. Transmission utilities in Germany and Japan are adopting these compact units for substation maintenance where space and weight constraints previously limited test equipment selection. The form factor reduction is miniaturizing procurement criteria, enabling single-technician deployment models that reduce crew costs and accelerate testing frequency.
Japan's METI enforcement of updated JIS standards for electrical safety testing equipment is restricting market access for instruments lacking localized certification documentation. Industrial manufacturing facilities in Osaka and Nagoya industrial clusters are responding by demanding supplier-provided JIS compliance packages as standard procurement terms. This regulatory tightening is fragmenting vendor qualification pools and elevating technical support capabilities as a competitive differentiator.
Electrical contractor procurement patterns are compressing toward bundled instrument-certification-service contracts rather than discrete equipment purchases. Large utility fleets in the United States are consolidating vendor relationships through multi-year maintenance agreements that embed training and calibration traceability. This contract structure shift is visible most acutely in California and Texas transmission markets where contractor consolidation has concentrated buying power among regional electrical services conglomerates.
Megohmmeters Market Segmentation
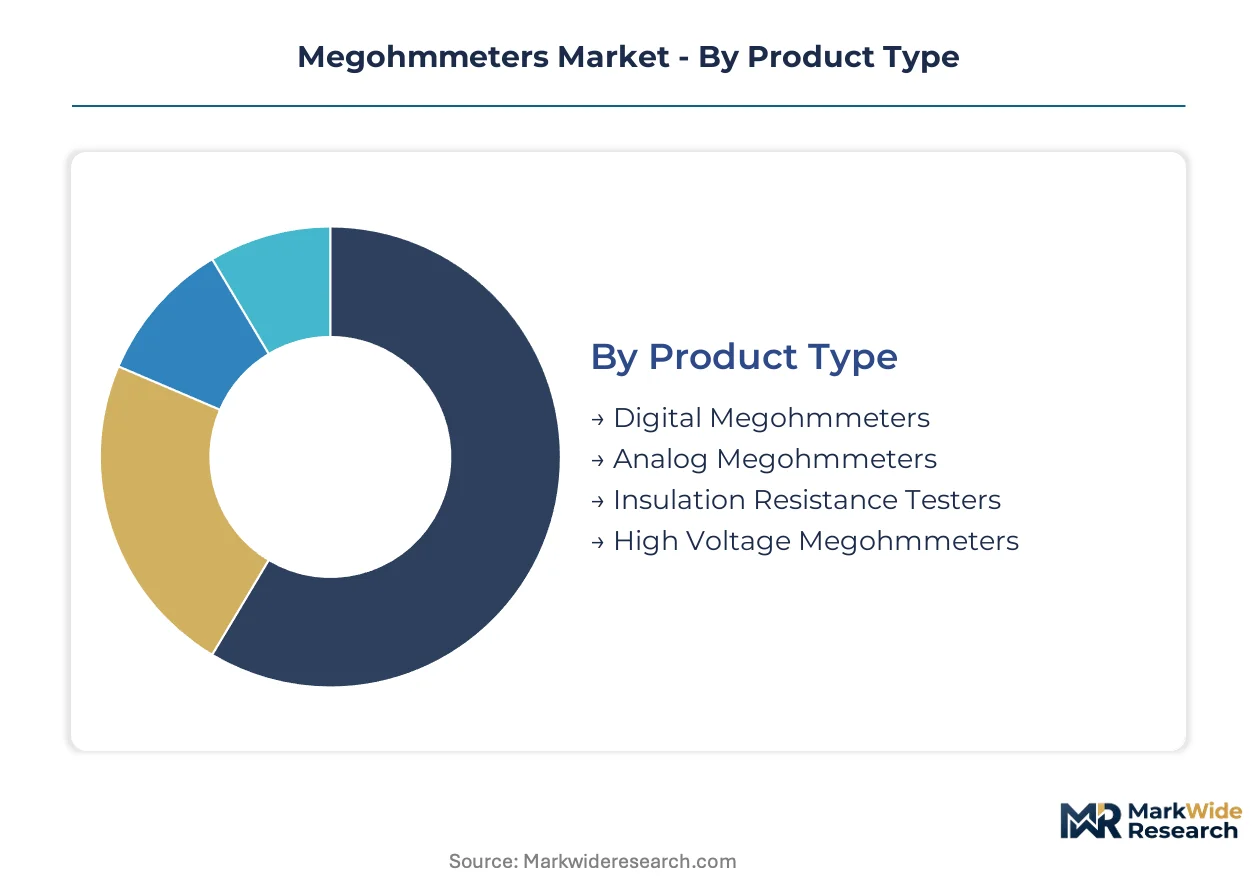
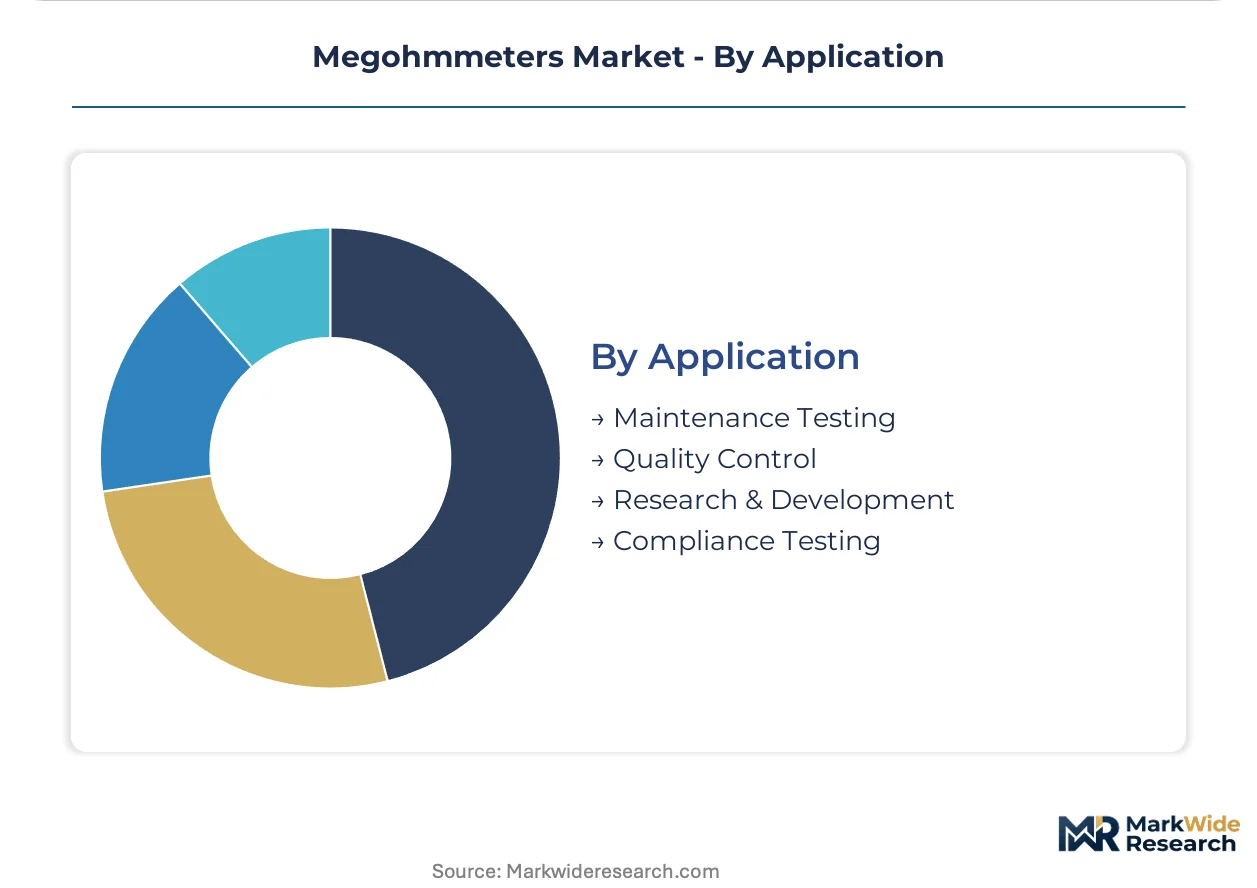
Megohmmeter procurement splits sharply between utility fleets demanding ruggedized field units and industrial buyers prioritizing calibration traceability. Channel strategy must align with these divergent technical requirements and replacement cycle patterns.
Product Type:
Digital units flow through authorized distributor networks to utility contractors, while analog models persist in secondary markets through independent electrical supply houses.
- Digital Megohmmeters:Microprocessor-based instruments with automated data logging and Bluetooth connectivity. Electrical utilities in India and Southeast Asia concentrate procurement here under CEA-mandated rural electrification testing protocols.
- Analog Megohmmeters:Electromechanical movement-based units with direct needle readout. Maintenance programs in legacy industrial facilities across Japan's Osaka industrial cluster continue specified procurement for technician familiarity.
- Insulation Resistance Testers:Combined-function instruments integrating continuity and voltage measurement capabilities.
- High Voltage Megohmmeters:5kV to 15kV output units for transmission infrastructure.
By volume, Digital Megohmmeters leads. By growth pace, High Voltage Megohmmeters is ahead.
Technology:
Cost tiering separates premium microprocessor platforms from manual units, with automatic systems capturing mid-market migration.
- Microprocessor Controlled:Programmable test sequences with pass-fail automation and cloud data streaming. German transmission operators under IEC 61543 compliance deadlines are accelerating replacement toward these platforms.
- Manual:Technician-operated voltage selection and timing without automation. Small electrical contractors in India's secondary cities maintain procurement for capital-constrained deployment.
- Automatic:Fixed-test-sequence units with simplified operator interfaces.
- RF Technology:Wireless-enabled diagnostic transmission for remote monitoring integration.
Microprocessor Controlled commands the dominant revenue share. RF Technology is climbing the fastest as FERC-mandated asset health monitoring expands.
End User:
Customer type determines calibration service bundling, with utilities demanding traceable documentation and manufacturing prioritizing throughput speed.
- Electrical Utilities:Grid infrastructure maintenance fleets requiring IEC 61543-compliant documentation. State utilities in India and transmission operators in Germany anchor procurement volume through centralized tender programs.
- Industrial Manufacturing:Plant maintenance departments with scheduled shutdown testing windows. Japanese automotive and electronics clusters in Nagoya specify JIS-certified instruments with localized technical support.
- Telecommunications:Network infrastructure operators testing cable insulation integrity.
- Aerospace:MRO facilities and OEM production lines with MIL-spec traceability requirements.
Electrical Utilities generates the largest absolute demand. Aerospace shows the steepest expansion trajectory driven by fleet modernization programs.
Application:
Margin structure varies by application, with compliance testing commanding premium pricing and maintenance testing competing on total cost of ownership.
- Maintenance Testing:Scheduled preventive inspection of energized equipment. Mining and oil & gas operators in Australia are adopting wireless-enabled units for hazardous environment worker safety protocols.
- Quality Control:Production-line insulation verification for electrical equipment manufacturing. Japanese industrial clusters integrate these into automated test stations with JIS documentation.
- Research & Development:Laboratory characterization of insulation materials and prototypes.
- Compliance Testing:Regulatory-mandated verification with auditable documentation trails.
Maintenance Testing leads in unit volume. Compliance Testing is gaining share fastest as IEC 61543 enforcement tightens across European markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power in Japan commands substantial premiums over equivalent procurement in India, reflecting calibration infrastructure concentration and regulatory certification depth versus volume-driven cost optimization.
United States
Electrical contractor fleets in California and Texas are consolidating vendor relationships through multi-year maintenance agreements that embed training and calibration traceability. FERC-mandated asset health monitoring systems are piloting megohmmeter data streams for predictive maintenance workflows. Field service networks in the Southeast are embedding technician certification programs directly with procurement contracts.
Germany
Transmission operators under IEC 61543 compliance deadlines are accelerating replacement toward microprocessor-controlled platforms with programmable test sequences. Stricter safety and accuracy benchmarks are compressing instrument replacement cycles across utility maintenance programs. Industrial clusters in Bavaria and North Rhine-Westphalia are demanding supplier-provided compliance documentation as standard procurement terms.
Japan
METI enforcement of updated JIS standards is restricting market access for instruments lacking localized certification documentation. Automotive and electronics clusters in Nagoya and Osaka are specifying JIS-certified instruments with localized technical support. Calibration traceability investments are elevating technical support capabilities as a competitive differentiator among domestic suppliers.
India
State utilities are expanding rural electrification network testing protocols under CEA guidelines, requiring systematic insulation resistance verification at distribution transformers. Digital megohmmeters with wireless data logging are displacing analog units in grid infrastructure programs. Secondary cities maintain procurement of manual units for capital-constrained deployment among small electrical contractors.
Australia
Mining and oil and gas operators are adopting wireless-enabled insulation testers for hazardous environment worker safety protocols. Maintenance testing programs in Western Australia are prioritizing field-portable formats that enable single-technician deployment models. Remote industrial monitoring applications are driving demand for Bluetooth-enabled asset management integration.
Megohmmeters Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium positioning depends on calibration expertise and regulatory certification depth. The vendor base spans consolidated multinational instrument manufacturers alongside specialized regional fabricators serving price-sensitive procurement channels. Three archetypes dominate: microprocessor platform specialists, calibration service integrators, and volume-oriented standard unit suppliers. Competitive moves center on embedding cloud connectivity as standard features and bundling training certification with instrument procurement.
Among established multinational instrument manufacturers, Megger Group Limited and Fluke Corporation exemplify the calibration-integrated archetype, while Hioki E.E. Corporation occupies a position within the Japan-centric technical support tier. These three companies anchor the premium segment through differentiated service capabilities rather than hardware specifications alone.
| Leading Market Players |
|---|
| Megger Group Limited |
| Fluke Corporation |
| Hioki E.E. Corporation |
| Chauvin Arnoux Group |
| Kyoritsu Electrical Instruments Works Ltd |
| Yokogawa Electric Corporation |
| AEMC Instruments |
| Extech Instruments |
| B&K Precision Corporation |
| Others |
Value Chain & Pricing Dynamics
Solid-state voltage generation replacing electromechanical movement-based designs is redrawing supply geography toward semiconductor fabrication hubs while compressing pricing premiums for field-portable units. This substitution dynamic simultaneously elevates calibration service bundling as a pricing differentiator and concentrates component sourcing in Asian microprocessor supply chains.
Pricing Analysis
The customization-premium spread separates configured-to-order microprocessor platforms with JIS documentation from standard digital units. Three-tier pricing structure across premium, standard, and economy levels tracks certification depth and after-sales service bundling. Cost compression in manual units is intensifying because small contractors in India's secondary cities prioritize capital-constrained deployment. State utilities in Germany and Japan show least price sensitivity due to IEC 61543 compliance mandates.
Supply Chain Analysis
Just-in-time inventory strategies dominate among Japanese and German manufacturers serving premium segments, while strategic stockpiling characterizes Indian and Southeast Asian procurement responding to silicon component volatility. Microprocessor and ADC sourcing draws from Taiwan, South Korea, and Japan. Calibration traceability investments rest on concentrated service infrastructure in Germany and Japan. Single-source vulnerability in semiconductor fabrication creates supply chain risk. Distribution runs through authorized distributor networks to utility contractors and independent electrical supply houses to secondary markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among regional electrical services conglomerates in California and Texas, compressing vendor relationships toward multi-year bundled contracts that embed training and calibration traceability.
For Market Incumbents: Fortify calibration service infrastructure as a defensive moat against emerging platform competitors offering cloud-integrated predictive maintenance. Deepen JIS and IEC 61543 certification investments to maintain premium positioning as METI enforcement tightens. Anchor channel control through embedded technician certification programs that raise switching costs for consolidated utility fleets. For New Entrants and Emerging Players: Differentiate on hazardous environment wireless connectivity for mining and oil and gas operators in Australia where incumbent coverage remains thin. Target secondary cities in India for manual unit penetration where capital constraints persist among small electrical contractors. Pursue direct procurement relationships with state utilities bypassing traditional distributor markups. For Investors and Strategic Acquirers: The market sits at a compliance-driven replacement phase that favors calibration-integrated specialists over pure hardware manufacturers. Long-term viability hinges on cloud data platform ownership rather than instrument production scale. Acquisition targets should demonstrate embedded service revenue streams and multi-standard certification capabilities. Watch FERC-mandated asset health monitoring adoption rates as the inflection signal for predictive maintenance platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Calibration Service Network Expansion | Captures recurring revenue from German transmission operators under IEC 61543 deadlines. |
| Cloud Platform Integration | Enables FERC-mandated asset health monitoring data streams for US utility pilots. |
| JIS Certification Acceleration | Unlocks METI-compliant market access for automotive clusters in Nagoya and Osaka. |
| Technician Certification Bundling | Secures multi-year maintenance agreements with California and Texas electrical conglomerates. |
| Hazardous Environment Wireless Development | Addresses worker safety protocols for Australian mining and oil and gas operators. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with instrument manufacturers, calibration service providers, utility maintenance directors, and electrical contractor procurement managers; and secondary validation through IEC 61543 documentation, METI JIS standard filings, CEA rural electrification guidelines, and FERC asset health monitoring directives. Bottom-up unit shipment estimates triangulated against top-down market value reconstructions across product type, technology, end user, and application dimensions.
Across the projection horizon, the analytical framework modeled volume and value outputs through segmented growth rate derivation. Segmentation dimensions included product architecture, control technology sophistication, customer type calibration requirements, and application compliance intensity. CAGRs were computed from replacement cycle analysis, regulatory deadline sequencing, and wireless connectivity adoption curves specific to utility asset management integration.
The analysis sits within stated boundaries; outcomes outside sustained semiconductor supply stability or accelerated IEC 61543 enforcement timelines would require recalibration. Forecasts reflect assumptions regarding technician certification program penetration and cloud platform interoperability standards. Revision becomes warranted when silicon component lead time volatility crosses thresholds that compress digital unit production schedules.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Test and Measurement
Bit Error Rate Tester Market
Test and Measurement
Hybrid Supercapacitor Lifetime and Safety Test Equipment Market
Test and Measurement
Pump Testers Market
Test and Measurement
Destructive Testing Market
Test and Measurement
Continuous Friction Tester Market
Test and Measurement
Voltage Tester Market
Test and Measurement
North America Electrical Testing Services Market
Test and Measurement
Advanced Probe Card and Wafer Probing Test Systems Market
Test and Measurement
Compression Testers Market
Test and Measurement
Noise Dosimeter Market
Test and Measurement
Eddy Current Testing Market
Test and Measurement
Flying Probe Testing for PCB Assembly Market
Test and Measurement
Electric Vehicle Edrive Test System Market
Test and Measurement
Microwave Power Meters Market
Test and Measurement
In-Situ Layer-by-Layer AM Defect Monitoring Test Equipment Market
Test and Measurement
Electrical and Electronic Test Equipment Market