
 Forging Press Market | 2026-2036
Forging Press Market Size, Share, and Industry Trends Forecast 2026-2036
Forging Press Market Foresight
Qualified press operator availability is collapsing across mature manufacturing economies, forcing fabricators to automate batch setups and reduce changeover times. SMS Group leverages its German engineering base to sustain turnkey automation packages for automotive stampers. Yangli Group anchors Asian supply through cost-optimized mechanical press lines for construction equipment makers. ANDRITZ Schuler competes on servo-electric retrofit intelligence that extends legacy hydraulic frames into precision aerospace work.
A forging press is a mechanically or hydraulically powered machine that delivers controlled compressive force to shape heated metal billets into desired forms, typically generating forces from several hundred to over 100,000 metric tons depending on application scale. Its primary purpose is to produce high-strength, defect-minimized components for industries where fatigue resistance and structural integrity are non-negotiable. Hydraulic presses dominate heavy forging for shipbuilding and construction equipment due to their force flexibility and dwell control, while servo-electric systems capture margin-rich aerospace component work through energy recovery and programmable slide motion. Drop forging retains volume leadership in automotive and general metal forming, though press forging gains share where near-net-shape requirements reduce downstream machining costs.
OSHA lockout/tagout standards and EPA foundry emissions rules shape US equipment specifications, pressuring domestic fabricators toward enclosed press designs and fume capture integration. China's MIIT enforces GB energy-efficiency grades that accelerate hydraulic system replacement cycles. ISO 16092 safety standards for mechanical presses create market access barriers for non-certified Asian exporters into European metal forming supply chains. Stakeholders must weigh captive retrofit investment against third-party forging service consolidation as labor scarcity and regulatory compliance costs escalate simultaneously.
Market Dynamics
Qualified press operator availability is collapsing across mature manufacturing economies, forcing fabricators to automate batch setups and reduce changeover times. This labor scarcity is compressing equipment procurement cycles and reshaping supplier relationships as buyers prioritize turnkey automation over standalone machinery.
Growth Catalysts
- GB Energy-Efficiency Grades:China's MIIT enforcement is accelerating hydraulic system replacement cycles across foundries, creating sustained equipment refresh demand.
- Aerospace OEM Backlogs:Commercial aircraft manufacturers are expanding forging press capacity to meet multi-year order commitments, concentrating procurement in precision-capable equipment.
- Ruhr Industrial Cluster:Germany's heavy machinery fabricators anchor European procurement, generating regional demand concentration for high-tonnage presses.
Market Restraints
- Specialized Labor Scarcity:Certified press operators and maintenance technicians command premium wages, inflating total cost of ownership beyond equipment purchase price.
- Raw Material Volatility:Forged die steel and high-grade hydraulic fluid prices fluctuate with energy markets, destabilizing fabricator margins.
- ISO 16092 Certification Barriers:European safety standards create market access friction for non-certified Asian exporters, limiting supply-side competition.
Strategic Opportunities
- Servo-Electric Retrofit Intelligence:Converting legacy hydraulic frames with programmable motion control opens precision aerospace work without full replacement capex.
- Construction Equipment Makers:Asian infrastructure investment is driving demand for cost-optimized mechanical press lines in heavy component forming.
- EPA Foundry Emissions Rules:US fabricators must integrate fume capture and enclosed press designs, creating aftermarket service and upgrade revenue streams.
Industry Challenges
- Automation Integration Complexity:Legacy press lines require extensive sensor retrofitting and control system harmonization to achieve lights-out operation.
- OSHA Lockout/Tagout Compliance:Fabricators face extended certification timelines and documentation burdens when modifying existing equipment safety systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Forging Press Market |
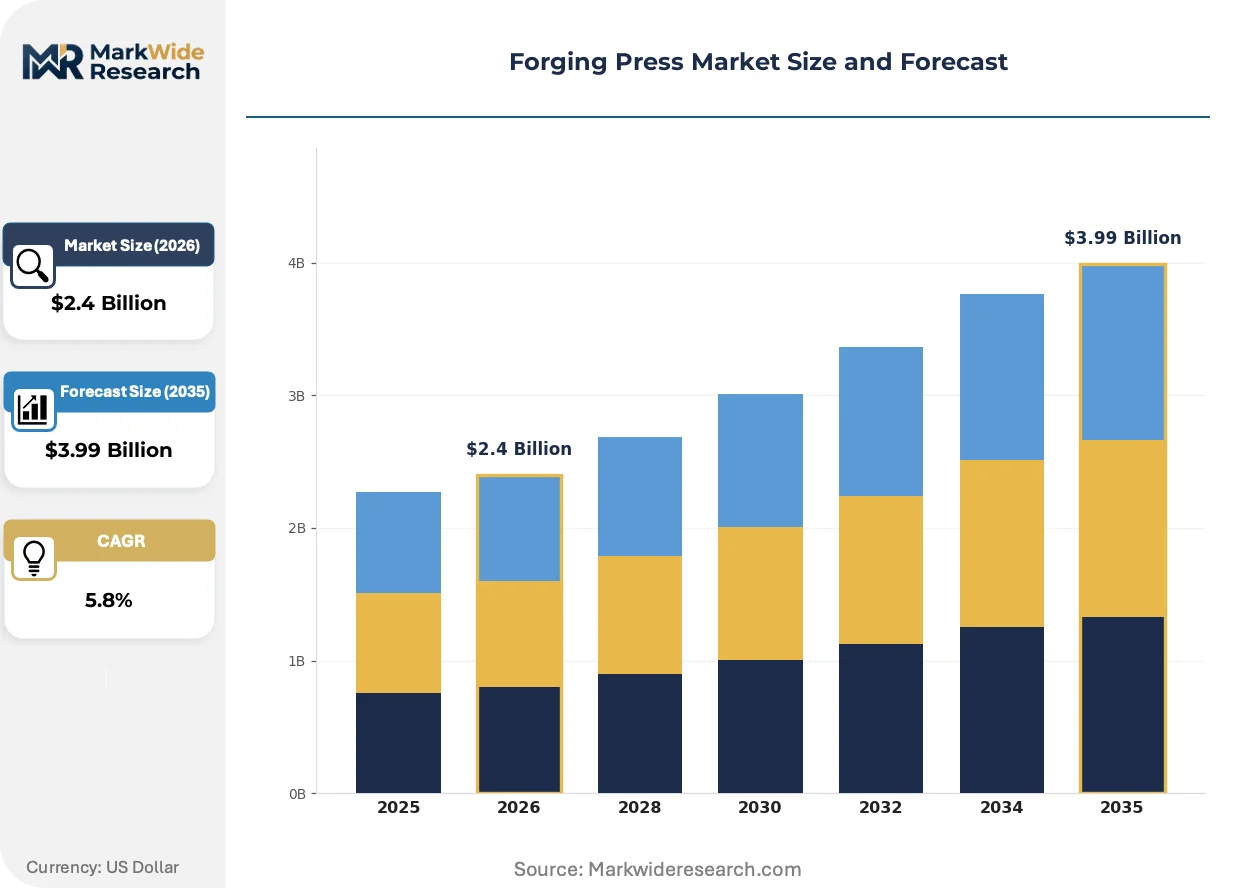
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.99 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Hydraulic, Mechanical, Pneumatic, Screw, Servo Electric Technology: Drop Forging, Press Forging, Upset Forging, Roll Forging, Roll Forming Application: Aerospace Components, Construction Equipment, Heavy Machinery, Shipbuilding, Electrical Devices End User: Fabricators, Equipment Manufacturers, Metal Formers, Custom Manufacturers |
| Companies Covered | Siempelkamp, ANDRITZ Schuler, Schuler, Stamtec, Sumitomo, SMS Group, Yangli Group, TMP, Aida, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Forging Press Market Shifts & Advancements
Digital motion control and energy recovery systems are redefining press performance benchmarks. Equipment buyers now prioritize programmable slide motion and real-time force feedback over raw tonnage ratings.
Servo-electric drive technology is fragmenting the traditional hydraulic-dominated market. Aerospace component manufacturers are adopting these systems for near-net-shape titanium forming. The technology is fragmenting supplier hierarchies as electrical engineering firms enter territory once held by fluid power specialists.
China's GB standards on industrial equipment efficiency are forcing foundry modernization. MIIT enforcement creates compliance deadlines that compress procurement decisions. Domestic fabricators face accelerated replacement cycles while foreign suppliers must certify to local efficiency grades.
Buyer preference is migrating toward performance-based equipment contracts. Automotive stampers now negotiate uptime guarantees and output-per-hour metrics rather than capital purchase terms. This shift is most pronounced in Germany's automotive supply chain, where tier-one stampers demand vendor accountability for production throughput.
Forging Press Market Segmentation
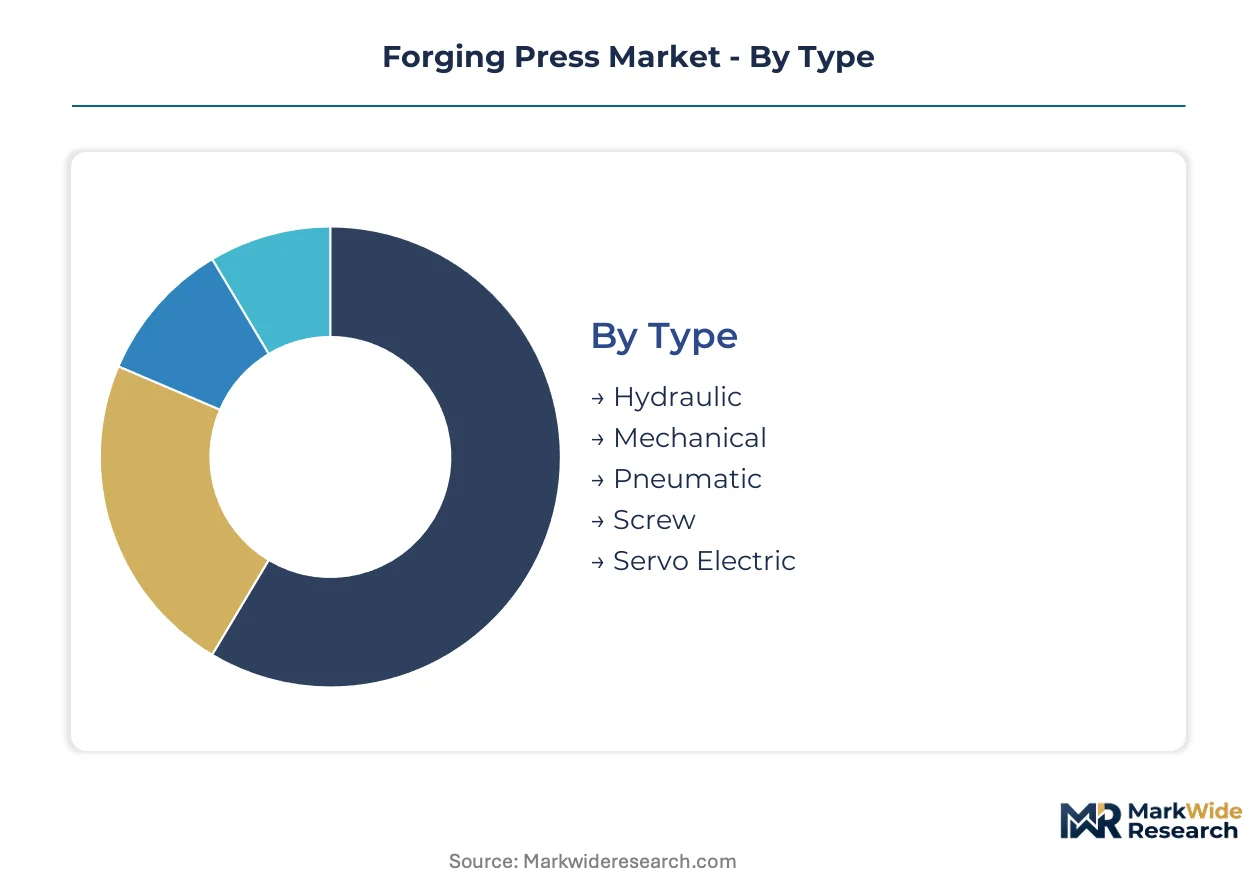
Equipment buyers segment procurement by force delivery mechanism and forming physics, with margin concentration shifting toward precision-controlled systems. Technology selection determines which end-use verticals a fabricator can serve, creating rigid capability boundaries between commodity and specialty producers.
Type:
Hydraulic systems command the largest installed base while servo-electric architectures capture expanding margin pools in precision applications.
- Hydraulic:Fluid-powered force generation with dwell control and variable stroke length enables heavy-section forming. Shipbuilders in Germany's Ruhr cluster specify these for crankshaft and propeller shaft production where force flexibility outweighs energy efficiency concerns.
- Servo Electric:Programmable ball-screw or direct-drive mechanisms recover braking energy and deliver slide motion accuracy within 0.01mm. Aerospace component manufacturers in China's eastern seaboard are standardizing these for titanium near-net-shape work.
- Mechanical:Crankshaft or eccentric drive systems deliver high-speed repetitive strokes for volume automotive stamping.
- Pneumatic:Compressed-air actuation serves light-gauge blanking and coining operations with limited tonnage requirements.
- Screw:Friction or electric screw mechanisms generate sustained pressure for open-die forging of large ingots.
Hydraulic holds installed capacity. Servo Electric is rotating up the share rankings.
Technology:
Process physics separate high-volume commodity production from defect-sensitive structural component work.
- Drop Forging:Impact forming via falling ram weight shapes heated billets in closed dies. Automotive stampers across India's Maharashtra industrial corridor deploy these for connecting rod and gear blank production where cycle speed dominates unit economics.
- Press Forging:Controlled compressive force application produces near-net shapes with minimal internal stress. US aerospace tier-one suppliers specify these for landing gear and structural fitting manufacture under FAA material traceability requirements.
- Upset Forging:Localized compression increases cross-sectional area of bar stock for bolt head and fastener formation.
- Roll Forging:Rotating dies progressively reduce and shape long workpieces for shaft and axle production.
- Roll Forming:Continuous bending through successive roll stands produces long structural sections from coil stock.
Press Forging commands the steepest expansion trajectory as machining cost reduction becomes a procurement priority.
Application:
End-use specifications dictate force range, die material, and certification requirements with aerospace work carrying the most stringent qualification barriers.
- Aerospace Components:Titanium and nickel superalloy forming demands vacuum or inert-atmosphere heating, isothermal die conditions, and NDT-validated microstructure. OEM backlogs for narrowbody and widebody programs are concentrating procurement in Germany, France, and China's certified supplier bases.
- Construction Equipment:High-tonnage structural member forming for excavator booms and crane components prioritizes equipment uptime over energy efficiency. South Korean and Japanese fabricators anchor regional demand for 10,000-ton-plus press capacity.
- Heavy Machinery:General industrial forging for mining and agricultural equipment serves price-sensitive procurement cycles.
- Shipbuilding:Marine shaft and rudder stock forming requires specialized open-die capabilities at extreme tonnage ratings.
- Electrical Devices:Precision copper and aluminum conductor forming for switchgear and transformer components operates at lower force ranges.
Construction Equipment anchors current volume. Aerospace Components is climbing the fastest as commercial aircraft production rates escalate.
End User:
Customer type determines procurement sophistication, with captive fabrication operations investing deeper in automation than job-shop metal formers.
- Equipment Manufacturers:OEM-integrated forging operations for construction and mining machinery specify turnkey automated cells with robotic billet handling. China's state-owned heavy equipment producers are consolidating press capacity at three mega-facilities in Shandong, Jiangsu, and Hunan provinces.
- Fabricators:Independent for-hire operations serving multiple industrial verticals prioritize equipment flexibility and rapid die changeover. Labor scarcity across mature economies is forcing these operators toward automated batch setup systems.
- Metal Formers:Dedicated stamping and forming specialists concentrate on high-volume automotive and appliance component production.
- Custom Manufacturers:Low-volume specialty work for prototype and aftermarket applications sustains manual press operations in niche segments.
Equipment Manufacturers dominate capital deployment. Fabricators are expanding fastest as outsourcing displaces captive forging investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT enforcement of GB energy-efficiency grades anchors China's regulatory pressure on foundry modernization. Equipment refresh cycles compress procurement timelines across Asia's largest installed press base. Fabricators in mature economies face parallel labor scarcity constraints.
China
Eastern seaboard aerospace component manufacturers standardize servo-electric systems for titanium forming. MIIT's GB standards accelerate hydraulic replacement cycles with compliance deadlines. Shandong, Jiangsu, and Hunan provinces consolidate state-owned heavy equipment press capacity at three mega-facilities.
Germany
Ruhr industrial cluster heavy machinery fabricators anchor European procurement for high-tonnage presses. ISO 16092 safety standards for mechanical presses create certification barriers for non-compliant imports. Stuttgart and Munich aerospace tier-one suppliers demand precision-capable equipment under FAA and EASA material traceability requirements.
United States
OSHA lockout/tagout standards and EPA foundry emissions rules shape domestic equipment specifications. Automotive stampers negotiate performance-based contracts with uptime guarantees rather than capital purchase terms. Detroit and Chicago metal forming corridors drive automated batch setup adoption amid collapsing operator availability.
Japan
METI industrial efficiency guidelines press shipbuilders toward energy-recovery press architectures. Construction equipment makers in Osaka and Nagoya industrial zones prioritize 10,000-ton-plus capacity for excavator boom forming. JIS standards harmonize with ISO certifications for export market access.
South Korea
Busan-Ulsan shipbuilding cluster sustains open-die hydraulic demand for marine shaft production. MFDS-aligned industrial safety protocols extend equipment certification timelines. Daegu-Gyeongbuk machinery builders anchor regional demand concentration for heavy-section forming capability.
Forging Press Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in forging press supply. Hydraulic system builders with captive automation capabilities command premium positioning in heavy industrial segments. Servo-electric entrants fragment precision aerospace supply as electrical engineering competencies displace fluid power heritage. Capacity expansion and strategic technology licensing represent the dominant competitive moves as fabricators seek turnkey solutions over standalone machinery procurement.
Among Germany-based engineering groups, SMS Group and ANDRITZ Schuler exemplify the integrated automation tier, while Yangli Group anchors Chinese supply for cost-optimized mechanical lines. These three occupy positions spanning premium turnkey packages through volume-optimized regional supply, representing the structural diversity of press manufacturing capability.
| Leading Market Players |
|---|
| Siempelkamp |
| ANDRITZ Schuler |
| Schuler |
| Stamtec |
| Sumitomo |
| SMS Group |
| Yangli Group |
| TMP |
| Aida |
| Others |
Supply & Pricing Matrix
Capacity utilization at Germany's Ruhr industrial cluster and China's Shandong mega-facilities creates asymmetric pricing power between heavy-tonnage hydraulic specialists and precision servo-electric entrants. Scale economies in forged die steel procurement and high-grade hydraulic fluid sourcing compress margin floors for mid-tier fabricators while insulating integrated leaders.
Pricing Analysis
German-engineered turnkey automation packages command 40-60% premiums over Asian mechanical press lines, with price stratification across premium servo-electric, standard hydraulic, and economy mechanical tiers. Price differentiation rests on ISO 16092 certification status and after-sales service bundling. Cost compression in economy-tier mechanical presses is intensifying as Yangli Group expands Shandong capacity. Automotive stampers exhibit highest price sensitivity; aerospace tier-one suppliers prioritize uptime guarantees over capital expenditure minimization.
Supply Chain Analysis
Germany, China, and Japan anchor global forging press manufacturing, with the Ruhr cluster and Shandong province concentrating heavy-tonnage hydraulic capacity while Japan's Osaka-Nagoya zone specializes in precision servo-electric architectures. Forged die steel supply draws from Swedish and Austrian specialty mills; high-grade hydraulic fluid sourcing hinges on German and US petrochemical complexes. Single-source vulnerability in aerospace-grade titanium billet supply creates procurement risk for precision press operators. Distribution runs through OEM-direct contracts for equipment manufacturers and regional distributor networks for independent fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating as China's state-owned heavy equipment producers consolidate press procurement at three mega-facilities, fragmenting negotiating leverage across smaller independent fabricators in mature economies.
For Market Incumbents: Shield installed base relationships through captive aftermarket service contracts and ISO 16092 certification investments that block non-compliant Asian entrants. SMS Group and ANDRITZ Schuler should deepen backward integration into forged die steel sourcing to offset raw material volatility. Automation integration capabilities represent the critical defensive lever as labor scarcity accelerates retrofit demand. For New Entrants and Emerging Players: Lead with servo-electric retrofit intelligence targeting US aerospace tier-one suppliers under EPA emissions compliance pressure. The most penetrable white space sits in precision titanium forming for narrowbody OEM backlogs, where electrical engineering competencies displace fluid power heritage. A go-to-market angle through performance-based contracts with uptime guarantees bypasses capital purchase barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors servo-electric specialists with aerospace certification pathways over legacy hydraulic incumbents. Long-term viability over a 5-10 year window rests on programmable motion control IP and energy recovery system integration. Acquisition targets should demonstrate MIIT GB standards compliance for China market access. The signal to watch is OEM backlog duration for commercial aircraft programs.| Strategic Initiative | Industry Significance |
|---|---|
| Servo-Electric Retrofit Intelligence | Converts legacy hydraulic frames into precision aerospace-capable equipment without full replacement capex. |
| ISO 16092 Certification Investment | Creates European market access barriers protecting German incumbents from non-compliant Asian competition. |
| Backward Integration into Forged Die Steel | Stabilizes input cost exposure from Swedish and Austrian specialty mill supply volatility. |
| Performance-Based Contract Structuring | Aligns vendor accountability with automotive stamper throughput metrics rather than capital purchase terms. |
| MIIT GB Standards Compliance | Unlocks equipment refresh cycles across China's foundry modernization mandates. |
Research Methodology
A spread of perspectives from plant engineers at German Ruhr cluster fabricators, OEM procurement teams at Chinese state-owned heavy equipment producers, aftermarket service heads at Japanese precision press specialists, and regulatory affairs leads navigating MIIT enforcement converged on the working assumptions. Primary fieldwork combined with secondary validation from customs trade data, SEC filings of listed industrial equipment manufacturers, and MIIT GB standards documentation enabled bottom-up and top-down triangulation.
Segmentation dimensions modeled span force delivery mechanism, forming physics, end-use application, and customer type across the projection horizon. CAGRs derived from equipment shipment tracking, capacity utilization surveys, and OEM backlog analysis. Industry-specific forecast inputs include aerospace production rate schedules and foundry modernization compliance deadlines under MIIT enforcement.
Forecasts assume regulatory continuity in MIIT GB energy-efficiency enforcement and OSHA lockout/tagout standards; material policy shifts would require re-modeling. Specific risks that could revise projections include raw material volatility in forged die steel markets and abrupt aerospace OEM order cancellations. Recalibration cycles align with material shifts in labor scarcity severity and regulatory compliance deadline adjustments.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Tension Tester Market
Tools
Tape Measure Market
Tools
Ratchet Wringer Market
Tools
Saw Blades Market
Tools
Spray Painting Machine Market
Tools
Allen Key Market
Tools
Mold Racks Market
Tools
Thread Milling Machine Market
Tools
Spray Gun Market
Tools
Hand Tools and Woodworking Tools Market
Tools
Automotive Torque Tools Market
Tools
MIG Guns Market
Tools
Nut Runner Market
Tools
Level Floats Market
Tools
Portable Pressure Washer Market
Tools
Laser Engraving Machine Market