
 United States Machine Tools Market | 2026-2036
United States Machine Tools Market Size, Share, and Industry Trends Forecast 2026-2036
United States Machine Tools Market Intelligence
Software-defined machining is rewriting how US fabricators orchestrate tool paths, spindle speeds, and quality feedback in real time. Haas Automation leverages its Oxnard, California manufacturing base to sustain price-competitive vertical machining centers for job shops nationwide. Makino, Inc. differentiates through advanced die-mold and aerospace solutions, while DMG MORI USA anchors its position with integrated turning-milling centers and digital twin capabilities.
Machine tools encompass powered mechanical devices that shape metal or other rigid materials through cutting, grinding, drilling, or abrading operations, typically achieving tolerances within micrometers for precision components. These systems serve as foundational capital equipment across discrete manufacturing, enabling dimensional accuracy in everything from turbine blades to surgical implants. Milling machines occupy the largest installed base among product types, reflecting sustained replacement cycles in general fabrication. Computer Numerical Control technology commands premium positioning as shops retire manual equipment, while additive manufacturing hybrid systems represent the fastest-growing technology segment for complex geometries. Aerospace end users generate the highest margin pools due to superalloy machining requirements and stringent traceability standards.
FAA airworthiness directives and NIST measurement standards shape equipment specifications for defense and aerospace suppliers, while OSHA machine guarding regulations influence retrofit demand across legacy shop floors. The SEC climate disclosure rules are beginning to flow through to capital allocation, pushing manufacturers toward energy-efficient spindle systems and coolant recycling. Stakeholders must weigh reshoring momentum against interest rate sensitivity when timing capacity investments.
Market Dynamics
The CHIPS Act and NIST precision manufacturing standards are forcing domestic machine tool buyers to replace legacy equipment with traceable, digitally integrated systems capable of micrometer tolerances for defense and semiconductor supply chains.
Growth Catalysts
- CHIPS Act capital allocation:Semiconductor fabrication facility construction across Arizona, Texas, and Ohio is pulling multi-axis machining centers and ultra-precision grinding systems into active procurement cycles.
- FAA airworthiness directives:Defense aerospace suppliers in the US Southeast must upgrade to five-axis simultaneous machining capability to machine titanium and Inconel superalloys under stricter traceability protocols.
- Software-defined toolpath optimization:Real-time spindle load monitoring and adaptive feedrate control are compressing cycle times in Michigan automotive transmission plants.
Market Restraints
- Ball screw and linear guide import concentration:Japanese and German precision motion component suppliers dominate critical feed drive subsystems, exposing US builders to yen-euro volatility and extended lead times.
- High-purity cast iron supply constraints:Domestic foundry capacity for machine tool beds and columns has contracted, forcing reliance on Chinese and Indian gray iron imports subject to Section 301 tariff exposure.
- Skilled CNC programmer scarcity:Community college machining programs graduate insufficient operators capable of G-code optimization and macro programming for complex five-axis work.
Strategic Opportunities
- Texas energy-equipment cluster expansion:Oilfield services manufacturers in Houston and Midland are retrofitting horizontal boring mills for geothermal turbine housing production.
- Hybrid additive-subtractive systems:Directed energy deposition heads integrated onto vertical machining centers enable repair of aerospace blisks and impellers without thermal distortion.
- SEC climate disclosure rules:Publicly held manufacturers must document Scope 1 and 2 emissions, creating pull for energy-efficient spindle motors and closed-loop coolant systems with consumption monitoring.
Industry Challenges
- IT/OT cybersecurity integration:Connected machine tools with MTConnect or OPC-UA interfaces expose shop floors to ransomware targeting production continuity.
- AS9100D certification timeline compression:Aerospace tier suppliers face 18-month audit backlogs for quality management system updates, delaying qualification for new defense contracts.
- Retrofit controller compatibility:Legacy analog servo systems resist integration with modern digital twin platforms, forcing costly full-machine replacement versus incremental upgrade paths.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Machine Tools Market |
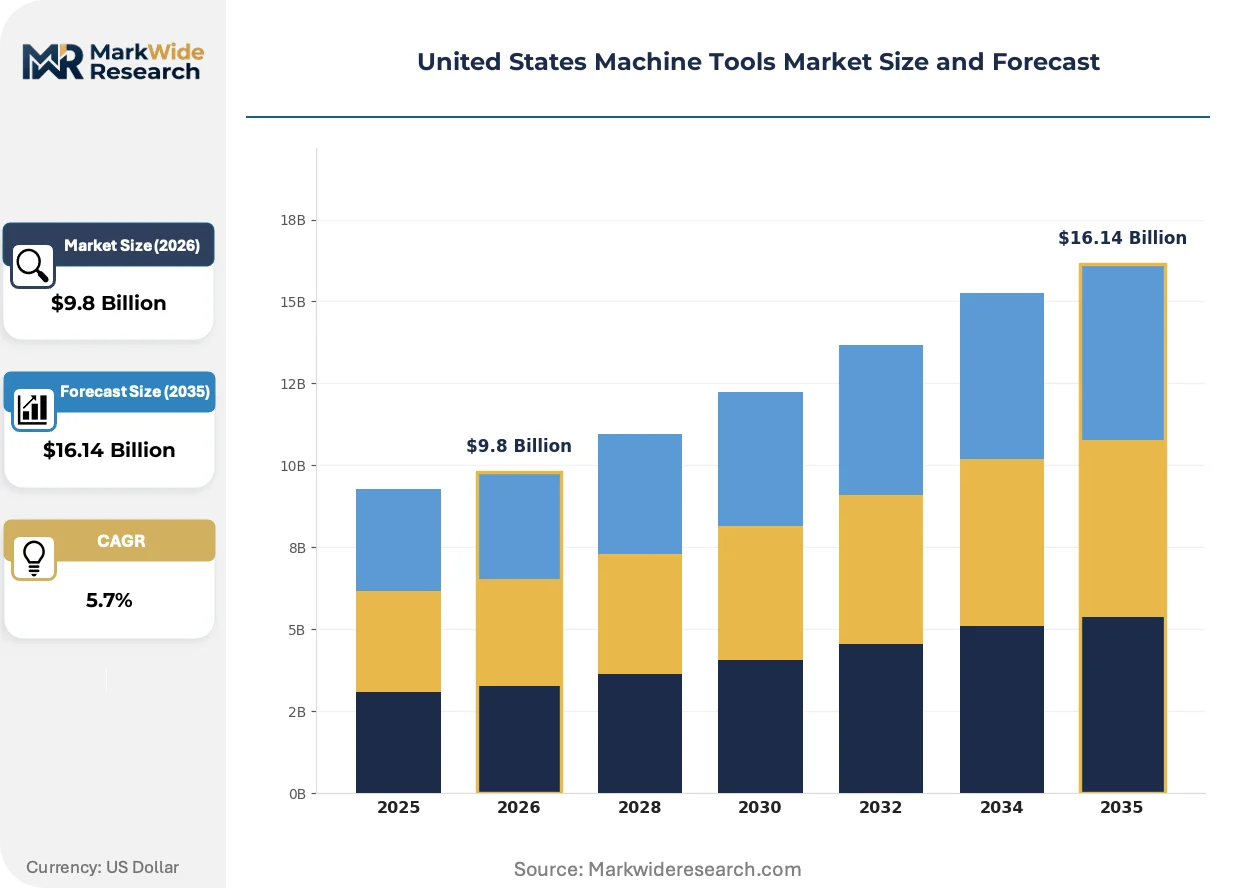
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $16.14 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lathe Machines, Milling Machines, Grinding Machines, Drilling Machines End User: Aerospace, Automotive OEMs, Heavy Machinery, Electronics Technology: Computer Numerical Control, Manual, Hybrid, Additive Manufacturing Application: Industrial Manufacturing, Component Production, Tooling, Prototyping |
| Companies Covered | Okuma America, Makino, Inc., Haas Automation, Hardinge Inc., Hurco Companies, Inc., Mazak Corporation, TRUMPF Inc., Doosan Machine Tools, DMG MORI USA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Machine Tools Market Strategic Shifts & Innovations
Digital thread integration from CAD through CAM to spindle feedback is collapsing quality assurance loops and enabling unattended machining in high-mix, low-volume production environments previously dominated by manual intervention.
Edge computing nodes deployed directly at the machine control are digitizing vibration signature analysis and thermal drift compensation without latency-prone cloud roundtrips. Medical implant manufacturers in Massachusetts and Minnesota are deploying these systems to maintain ISO 13485-compliant process validation across titanium hip stem production. The compression of inspection cycles from post-process to in-process is eliminating downstream rework and reducing work-in-process inventory buffers.
OSHA machine guarding regulations updated in response to collaborative robot integration are mandating light curtain and area scanner configurations that protect human-robot interaction zones without sacrificing spindle access. Job shops across the US Midwest are reconfiguring cell layouts to accommodate these safety envelopes while maintaining throughput. The regulatory friction is accelerating adoption of fully enclosed five-axis machining centers with integrated automation over retrofitted open-architecture machines.
Original equipment manufacturers are unbundling traditional turnkey installation and training packages into modular service tiers priced by machine complexity and geographic distance from factory service centers. Buyers in secondary US manufacturing markets—Appalachian metalworking corridors, Pacific Northwest marine equipment suppliers—are selecting remote commissioning with video-guided rigging over premium white-glove installation. The disintermediation of field service engineers is compressing vendor margins while expanding addressable market reach into previously uneconomic territories.
United States Machine Tools Market Segmentation
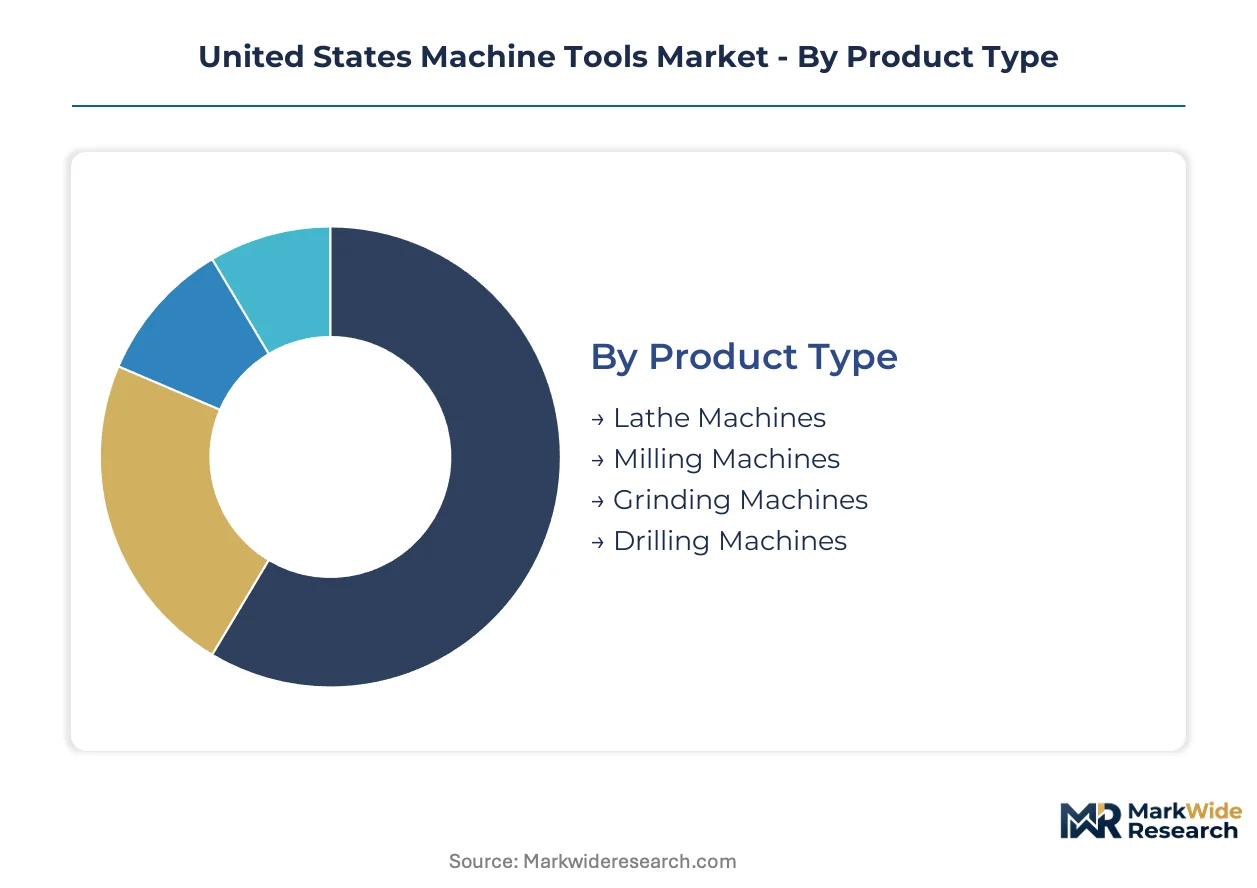
Machine tool segmentation reveals how capital equipment flows align with manufacturing density, regulatory pressure, and technology refresh cycles across US industrial corridors. Distinct buyer profiles emerge from defense aerospace traceability mandates, automotive volume economics, and semiconductor capital intensity.
Product Type:
Machining centers span subtractive, abrasive, and holemaking operations with tolerances scaling from general fabrication to micrometer-precision defense work.
- Milling Machines:Vertical and horizontal machining centers dominate US installed base through sustained replacement cycles in general fabrication. Michigan automotive transmission plants and Texas oilfield equipment manufacturers drive demand for four-axis pallet-changing systems with 40-taper spindles.
- Lathe Machines:Turning centers with live tooling and Y-axis capability enable complete machining of shaft-type components in single setups. Heavy machinery producers in Illinois and Ohio specify these for large-diameter bearing housings and hydraulic cylinder production.
- Grinding Machines:Surface, cylindrical, and centerless configurations achieve sub-micron finishes for aerospace landing gear and medical implant applications.
- Drilling Machines:Deep-hole drilling systems serve gun barrel manufacturers and energy-sector downhole tool producers with length-to-diameter ratios exceeding 20:1.
Established volume favors milling platforms; emerging adoption favors grinding systems for superalloy finishing.
End User:
Capital allocation intensity varies sharply across customer verticals, with defense-linked sectors commanding premium specifications and extended qualification timelines.
- Aerospace:Tier suppliers machine titanium and Inconel superalloys under FAA airworthiness directives requiring full digital thread traceability. Five-axis simultaneous capability is becoming baseline for Southeast defense corridor contract eligibility.
- Automotive OEMs:Powertrain plants in Michigan and Tennessee deploy high-volume horizontal machining centers with robotic pallet pools for engine block and transmission case production.
- Heavy Machinery:Construction and mining equipment manufacturers specify large-format boring mills and gantry machines for weldment machining.
- Electronics:Semiconductor capital equipment builders and PCB fixture producers demand micromachining centers with thermal stability control.
Margin concentration sits with aerospace qualification barriers; volume scale concentrates in automotive OEM procurement.
Technology:
Control architecture determines workforce requirements, throughput consistency, and integration depth with digital manufacturing platforms.
- Computer Numerical Control:Closed-loop servo systems with macro programming capability and MTConnect data interfaces command dominant share as manual shops retire legacy equipment. NIST manufacturing standards and CHIPS Act traceability requirements accelerate displacement of non-programmable machines.
- Manual:Levers and handwheels persist in maintenance departments, vocational training facilities, and specialty repair operations where part complexity remains low.
- Hybrid:Subtractive platforms with integrated directed energy deposition heads enable repair of blisks and impellers without thermal distortion.
- Additive Manufacturing:Powder-bed fusion and binder jet systems for metal 3D printing represent the steepest expansion trajectory in complex geometry applications where conventional machining reaches physical limits.
Displacement momentum favors CNC retrofit cycles; frontier investment favors hybrid repair systems.
Application:
Production mode shapes machine specification, with high-mix environments demanding flexibility that continuous-flow operations trade for dedicated automation.
- Industrial Manufacturing:General fabrication shops across the US Midwest run three-shift operations on vertical machining centers with quick-change fixturing for job shop economics.
- Component Production:Dedicated cells for automotive and aerospace suppliers achieve six-sigma capability through statistical process control and automated gauging integration.
- Tooling:Die and mold manufacturers specify high-speed machining centers with 30,000+ RPM spindles and precision thermal compensation for hardened steel and aluminum electrode work.
- Prototyping:R&D departments and product development centers prioritize five-axis universal machines with broad work envelopes over specialized production equipment.
Capacity utilization peaks in component production; flexibility premiums concentrate in prototyping workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German and Japanese machine tool builders export precision motion systems to US aerospace and semiconductor fabricators, creating trans-Pacific and trans-Atlantic supply corridors that shape domestic capital equipment availability.
Southeast
Defense aerospace suppliers in Georgia and South Carolina drive five-axis machining center procurement for titanium superalloy work. FAA airworthiness directives mandate full digital thread traceability for tier-one contractors. The Charleston-North Charleston corridor hosts expanding Boeing and Lockheed Martin supply chains requiring simultaneous multi-axis capability.
Texas
Energy-equipment manufacturers in Houston and Midland retrofit horizontal boring mills for geothermal turbine housings and oilfield downhole tools. NIST precision manufacturing standards govern equipment specifications for defense-linked suppliers. The Gulf Coast petrochemical corridor sustains demand for large-format gantry machines in weldment machining.
Michigan
Automotive powertrain plants in Detroit, Flint, and Lansing deploy high-volume horizontal machining centers with robotic pallet pools. EPA emissions regulations accelerate investment in energy-efficient spindle systems for transmission case production. The I-75 manufacturing corridor concentrates CNC retrofit cycles as manual shops retire legacy equipment.
California
Haas Automation's Oxnard manufacturing base supplies price-competitive vertical machining centers to job shops nationwide. SEC climate disclosure rules push semiconductor capital equipment builders toward closed-loop coolant systems. The Bay Area-Silicon Valley corridor demands micromachining centers with thermal stability control for wafer handling components.
Arizona
CHIPS Act-funded semiconductor fabrication facilities in Phoenix and Chandler pull multi-axis machining centers into active procurement cycles. OSHA machine guarding regulations influence retrofit demand for collaborative robot integration. The Phoenix-Tucson technology corridor concentrates ultra-precision grinding system deployment for chip manufacturing equipment.
United States Machine Tools Market Key Industry Players
Channel-controlling players compete with product-specialist players across tiered price-performance bands. The vendor base fragments between volume-oriented domestic builders, precision-focused Japanese and German transplants, and emerging Korean challengers. Two strategic archetypes dominate: vertically integrated manufacturers with captive component production, and assembly-focused integrators sourcing precision motion systems externally. M&A activity concentrates in digital twin software capabilities, while geographic expansion targets secondary US manufacturing markets previously served through distributor networks.
Among Japanese transplants, Okuma America and Makino, Inc. occupy positions emphasizing precision aerospace and die-mold solutions. Haas Automation anchors the domestic volume tier from its California manufacturing base. These three exemplify how geographic origin and organizational structure map to distinct competitive vectors—transplant precision specialists versus domestic scale players—without overlapping positioning.
| Leading Market Players |
|---|
| Okuma America |
| Makino, Inc. |
| Haas Automation |
| Hardinge Inc. |
| Hurco Companies, Inc. |
| Mazak Corporation |
| TRUMPF Inc. |
| Doosan Machine Tools |
| DMG MORI USA |
| Others |
Cost & Logistics Intelligence
Japanese and German precision motion component suppliers dominate critical feed drive subsystems, concentrating margin pools with aerospace tier-one contractors demanding five-axis simultaneous capability under FAA traceability mandates. Ball screw and linear guide import dependency exposes US machine tool builders to yen-euro volatility while defense-linked buyers absorb premium pricing for micrometer-tolerance qualification.
Pricing Analysis
Next-generation hybrid additive-subtractive systems command substantial premiums over legacy three-axis CNC platforms and retiring manual equipment. Three-tier pricing structure across premium, standard, and economy levels separates aerospace-qualified five-axis centers from automotive pallet-changing systems and price-competitive job shop vertical machines. Pricing pressure stems from skilled CNC programmer scarcity compressing utilization rates at standard-tier shops. Automotive OEMs exhibit highest price sensitivity through volume procurement leverage, while defense aerospace suppliers accept premium positioning for AS9100D-compliant digital thread integration.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk for high-purity cast iron machine tool beds and columns. Domestic foundry capacity draws from Chinese and Indian gray iron imports subject to Section 301 tariff exposure, while Japanese and Taiwanese suppliers anchor precision motion subsystem sourcing. Single-source vulnerability concentrates in ball screw and linear guide procurement channels. Distribution runs through OEM direct sales for large-format systems and regional distributor networks serving secondary manufacturing markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Qualified five-axis CNC programmers and AS9100D-certified quality engineers represent the scarcest capabilities constraining defense aerospace supplier expansion. This talent gap limits tier-one contract eligibility regardless of capital equipment availability.
For Market Incumbents: Insulate aerospace margin pools through captive training partnerships with community college machining programs, locking in programmer pipelines before competitors qualify. Prioritize backward integration into precision motion component production to reduce yen-euro exposure on feed drive subsystems. Defend against Korean challengers by accelerating digital twin software acquisition timelines. For New Entrants and Emerging Players: Secondary US manufacturing markets—Appalachian metalworking corridors and Pacific Northwest marine equipment suppliers—represent the most penetrable entry point for remote-commissioning service tiers. Target Texas energy-equipment retrofit demand for geothermal turbine housing production with video-guided rigging protocols. Pursue semiconductor capital equipment builders in Arizona through NIST precision manufacturing compliance positioning. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed machine tool service integrators lacking digital twin software capabilities. Five-to-ten year viability hinges on hybrid additive-subtractive technology adoption curves among aerospace repair operations. Monitor CHIPS Act capital allocation velocity as inflection indicator for multi-axis machining center procurement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Software Acquisition | Enables real-time spindle feedback integration for FAA traceability compliance. |
| Community College Training Partnerships | Secures CNC programmer pipelines for five-axis aerospace work. |
| Hybrid Additive-Subtractive System Launch | Captures aerospace blisk repair demand without thermal distortion risk. |
| Remote Commissioning Service Tier | Expands addressable reach into Appalachian and Pacific Northwest markets. |
| Backward Integration into Motion Components | Reduces yen-euro exposure on ball screw and linear guide sourcing. |
Research Approach
The analysis maps machining centers, turning centers, grinding systems, and hybrid additive platforms, each validated through plant engineers, OEM procurement teams, aftermarket service directors, and distributor account managers. Primary fieldwork combined with SEC 10-K filings, NIST manufacturing standard documentation, FAA airworthiness directive records, and customs import data enabled bottom-up and top-down triangulation.
Assumptions held CHIPS Act capital allocation and NIST precision standards fixed while varying interest rate sensitivity and skilled labor availability across the projection horizon. Segmentation dimensions modeled include product type, end-user vertical, control technology, and application mode throughout the forecast period. CAGRs derived from equipment replacement cycle analysis and semiconductor fabrication facility construction pipelines.
Practitioners should monitor yen-euro exchange volatility, Section 301 tariff adjustments, and AS9100D certification backlog duration for early signals requiring forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Tool Pliers Market
Tools
North America Power Tools Market
Tools
Rivet Gun Market
Tools
Dumpy Level Market
Tools
Hydraulic Torque Wrench Market
Tools
Shredder Blades Market
Tools
Cordless Bandsaw Sander Market
Tools
Wood Floor Grinding Machine Market
Tools
Nut Runner Market
Tools
Bandsaw Market
Tools
Technical Drawing Tools Market
Tools
Wood-Sanding Machine Market
Tools
Europe Stump Cutter/Grinder Market
Tools
Industrial Cleaning Equipment Market
Tools
Multi Wire Cutting Machine Market
Tools
Thread Milling Machine Market