
 Lip Scrub Market | 2026-2036
Lip Scrub Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Scrub Market Foresight
Bundle configurations pairing lip scrubs with complementary balms or masks is shifting how consumers evaluate value per purchase. L'Oréal S.A. leverages its scale to anchor premium positioning across multi-product skincare sets. Unilever N.V./PLC competes through mass-market accessibility and broad retail penetration. Fresh specializes in sensorial, ingredient-forward formulations that differentiate its scrubs within prestige channels.
A lip scrub is a topical exfoliating preparation, typically containing abrasive particles such as sugar, salt, or ground coffee suspended in emollient bases like natural oils or butters, designed to remove dead skin cells and smooth the lip surface for improved product adherence and hydration retention. Organic scrubs lead ingredient-positioned segments as clean beauty standards tighten formulation transparency requirements. Sugar-based variants occupy the largest share of the ingredient type category due to consumer familiarity and gentler exfoliation profiles. Jar packaging dominates the premium tier, while squeeze tubes sustain convenience-driven sales in travel and on-the-go contexts.
The U.S. Food and Drug Administration oversees cosmetic labeling and safety substantiation for lip scrubs sold domestically, while the European Chemicals Agency enforces REACH compliance on exfoliating micro-ingredients and fragrance allergens. These frameworks elevate compliance costs for entrants but simultaneously protect established brands with dedicated regulatory affairs infrastructure. Stakeholders must monitor evolving state-level packaging mandates and ingredient disclosure rules that could reshape competitive barriers faster than federal harmonization efforts.
Market Dynamics
Clean beauty certification requirements are compressing formulation timelines as brands race to meet tightening EU Cosmetics Regulation standards before competitors secure shelf space at specialty retailers.
Growth Catalysts
- REACH micro-ingredient disclosure mandates:ECHA enforcement is elevating transparency standards that premium brands leverage to justify price positioning against mass-market alternatives.
- Pre-makeup lip preparation rituals:Professional makeup artists and social media tutorials normalize exfoliation as a non-negotiable step, expanding the addressable user base beyond traditional skincare enthusiasts.
- Sugar-based exfoliation technology:Biodegradable particle systems resolve microplastic concerns while delivering gentler abrasion profiles suitable for sensitive skin segments.
Market Restraints
- Shea butter and coconut oil price volatility:Emollient base costs fluctuate with West African and Southeast Asian agricultural yields, compressing margin predictability for fixed-price retail contracts.
- Single-source fragrance allergen suppliers:Concentrated European producers of compliant natural scents create bottleneck risks during reformulation cycles.
- Preservative-free stability limitations:Water-free anhydrous formulations restrict texture innovation and shelf-life extension compared to conventional emulsions.
Strategic Opportunities
- Indian urban premium beauty channels:Specialty retailers in Mumbai and Delhi under-index on lip scrub SKU density relative to facial exfoliants, presenting first-mover whitespace.
- Biodegradable pod single-use formats:Travel and hospitality sectors seek portion-controlled, plastic-free alternatives to jar packaging for amenity programs.
- EU Green Deal packaging mandates:Refillable aluminum vessel requirements scheduled through 2030 favor brands with existing circular infrastructure investments.
Industry Challenges
- Cosmetic chemist specialization gaps:Formulation expertise bridging natural ingredient stability with abrasive particle suspension remains scarce in emerging production hubs.
- Multi-jurisdiction label harmonization:Divergent FDA, ECHA, and state-level disclosure rules force SKU proliferation or lowest-common-denominator labeling that undermines premium positioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Scrub Market |
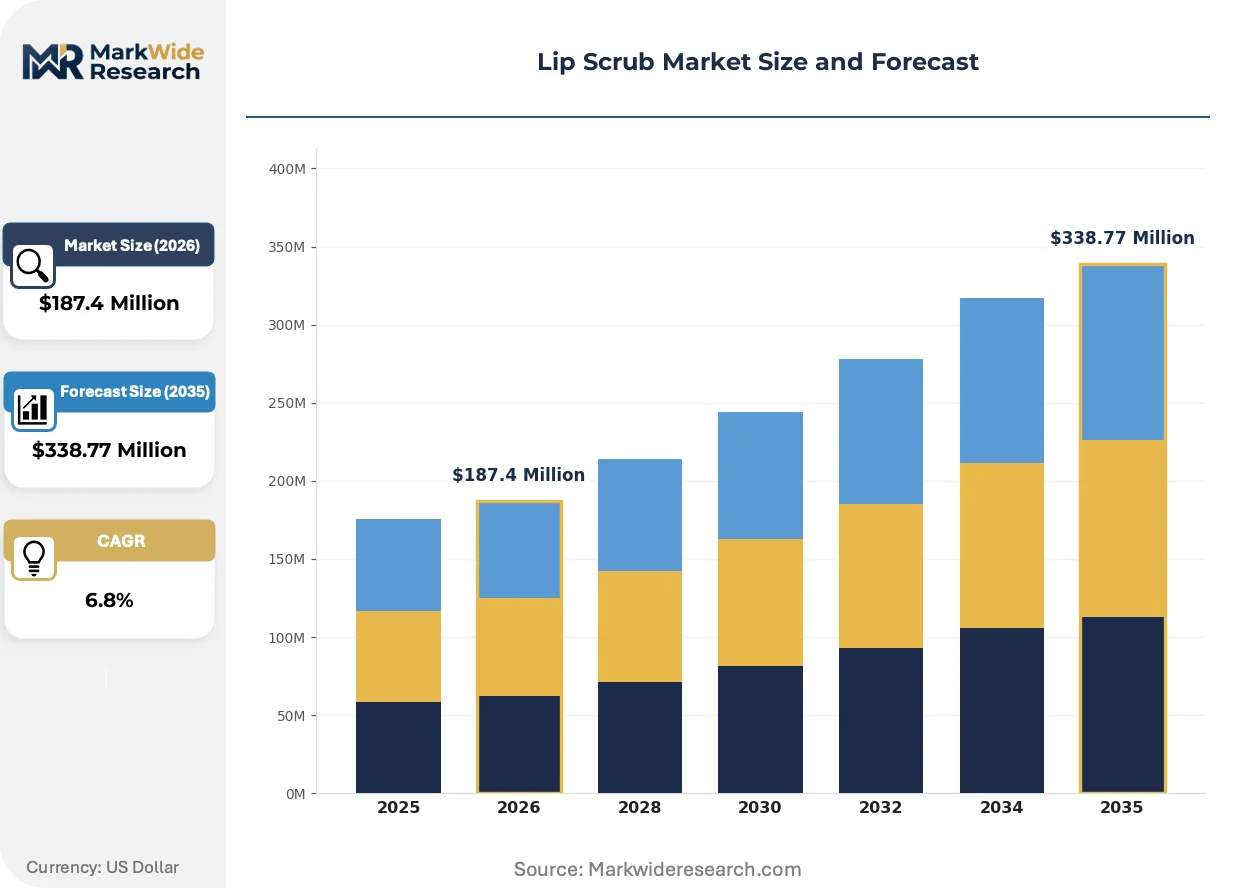
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Exfoliating Scrub, Hydrating Scrub, Flavored Scrub, Organic Scrub Ingredient Type: Sugar, Salt, Coffee, Natural Oils Packaging Type: Tub, Squeeze Tube, Stick, Jar Sales Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Revlon, Inc., Unilever N.V./PLC, L'Oréal S.A., Dr.PAWPAW, Carma Labs, Inc., Kao Corporation, The Clorox Company, Fresh, Beiersdorf AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Scrub Market Shifts & Advancements
Biotechnology-derived emollients and waterless formulation science are displacing conventional petroleum-based bases, while regulatory pressure on microplastics accelerates particle innovation cycles across all price tiers.
Encapsulated enzyme exfoliation is integrating mild proteolytic activity from fruit-derived sources to supplement or replace mechanical abrasion, reducing dependency on physical particles. Prestige dermatology brands and clean beauty specialists are adopting this hybrid approach fastest, typically launching dual-action products within twelve-month development windows. The technology is integrating chemical and mechanical modalities into single-step applications that command premium positioning while simplifying consumer routines.
REACH Annex XVII restrictions on synthetic polymer microbeads have forced complete particle system redesigns for any scrub targeting European distribution. Manufacturers now validate biodegradability through OECD 301 testing protocols, adding six to nine months to qualification timelines. Color cosmetics brands with existing EU regulatory affairs infrastructure capture shelf space faster than entrants facing first-time compliance costs.
Subscription box curation is displacing traditional trial-size sampling as the primary discovery mechanism for niche and indie lip scrub brands. Beauty box services in the United States and United Kingdom now specify clean ingredient profiles and sustainable packaging as mandatory inclusion criteria, filtering which formulations reach engaged early adopters. Direct-to-consumer brands with flexible small-batch production respond faster than mass-market houses with rigid annual planning cycles.
Lip Scrub Market Segmentation
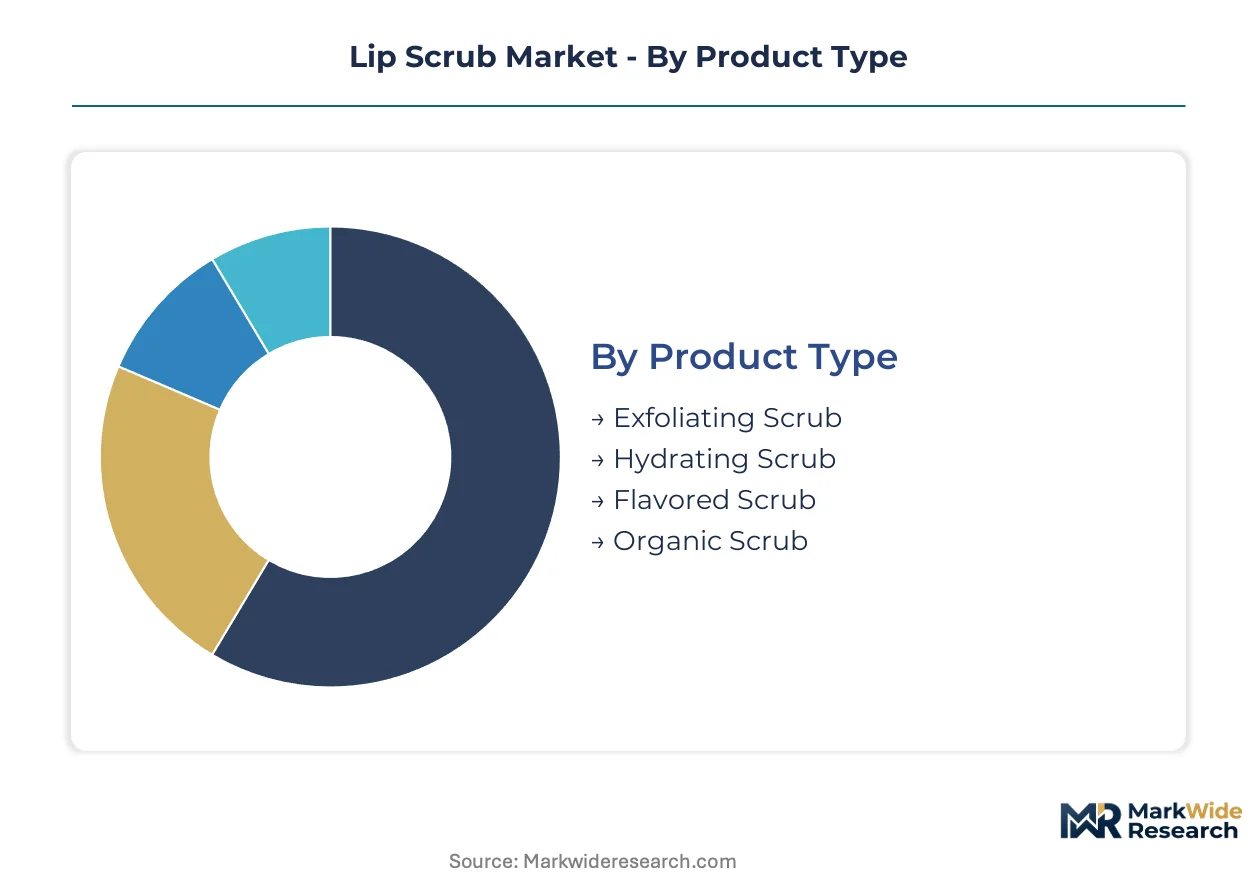
Lip scrub segmentation reveals how formulation technology, packaging engineering, and channel economics partition commercial opportunity. Brands configure product architecture across these dimensions to capture distinct willingness-to-pay thresholds and usage contexts.
Product Type:
Formulation science determines performance positioning and regulatory complexity across the exfoliation-hydration spectrum.
- Exfoliating Scrub:Mechanical abrasion systems utilizing crystalline or granular particles suspended in emollient bases. Demand concentrates among pre-makeup preparation users in the United States, where professional artist tutorials normalize exfoliation as a non-negotiable step.
- Organic Scrub:Certified botanical ingredient systems excluding synthetic preservatives and petroleum derivatives. Clean beauty certification requirements in the European Union compress formulation timelines as brands race to meet tightening EU Cosmetics Regulation standards before competitors secure specialty retail placement.
- Hydrating Scrub:Dual-function formulations combining mild exfoliation with intensive moisture deposition. Post-treatment comfort positioning targets consumers with sensitivity concerns or climate-induced dryness.
- Flavored Scrub:Sensorial-enhanced variants utilizing food-grade aromatic compounds. Gifting and impulse purchase contexts drive volume, with seasonal limited releases sustaining engagement.
Mature deployment sits with Exfoliating Scrub. Newer deployment is concentrated in Organic Scrub.
Ingredient Type:
Raw material sourcing geography and biodegradability credentials partition cost structures and regulatory risk profiles.
- Sugar:Crystalline sucrose particles offering controlled dissolution rates and gentler abrasion profiles suitable for sensitive lip tissue. Biodegradable particle systems resolve microplastic concerns while commanding premium positioning against synthetic alternatives.
- Natural Oils:Plant-derived emollient bases including shea butter, coconut oil, and jojoba esters. West African and Southeast Asian agricultural yield volatility compresses margin predictability for fixed-price retail contracts.
- Salt:Mineral crystalline abrasives with antimicrobial properties. Coarser particle sizes limit frequency of use but target specific callus or severe dryness conditions.
- Coffee:Up-cycled ground bean particles with antioxidant content and distinctive sensorial profile. Niche positioning within clean beauty and sustainability-focused segments.
Volume leadership resides with Sugar. Steepest expansion trajectory is visible in Natural Oils.
Packaging Type:
Primary packaging format determines usage occasion accessibility, preservation requirements, and circular economy compliance exposure.
- Jar:Wide-mouth rigid containers dominating premium tier presentation. Refillable aluminum vessel requirements scheduled through EU Green Deal mandates favor brands with existing circular infrastructure investments.
- Squeeze Tube:Flexible barrier systems sustaining convenience-driven sales in travel and on-the-go contexts. Portion control and hygiene concerns limit multi-user sharing.
- Tub:Shallow-profile containers optimized for fingertip access and visual product display. Amenity program specifications in hospitality sectors favor this format for back-bar professional use.
- Stick:Solid formulation delivery systems eliminating finger contact and leakage risk. Format constraints limit particle size and exfoliation intensity.
Premium positioning clusters around Jar. Mass accessibility concentrates in Squeeze Tube.
Sales Channel:
Channel selection dictates margin structure, customer acquisition economics, and speed of trend responsiveness.
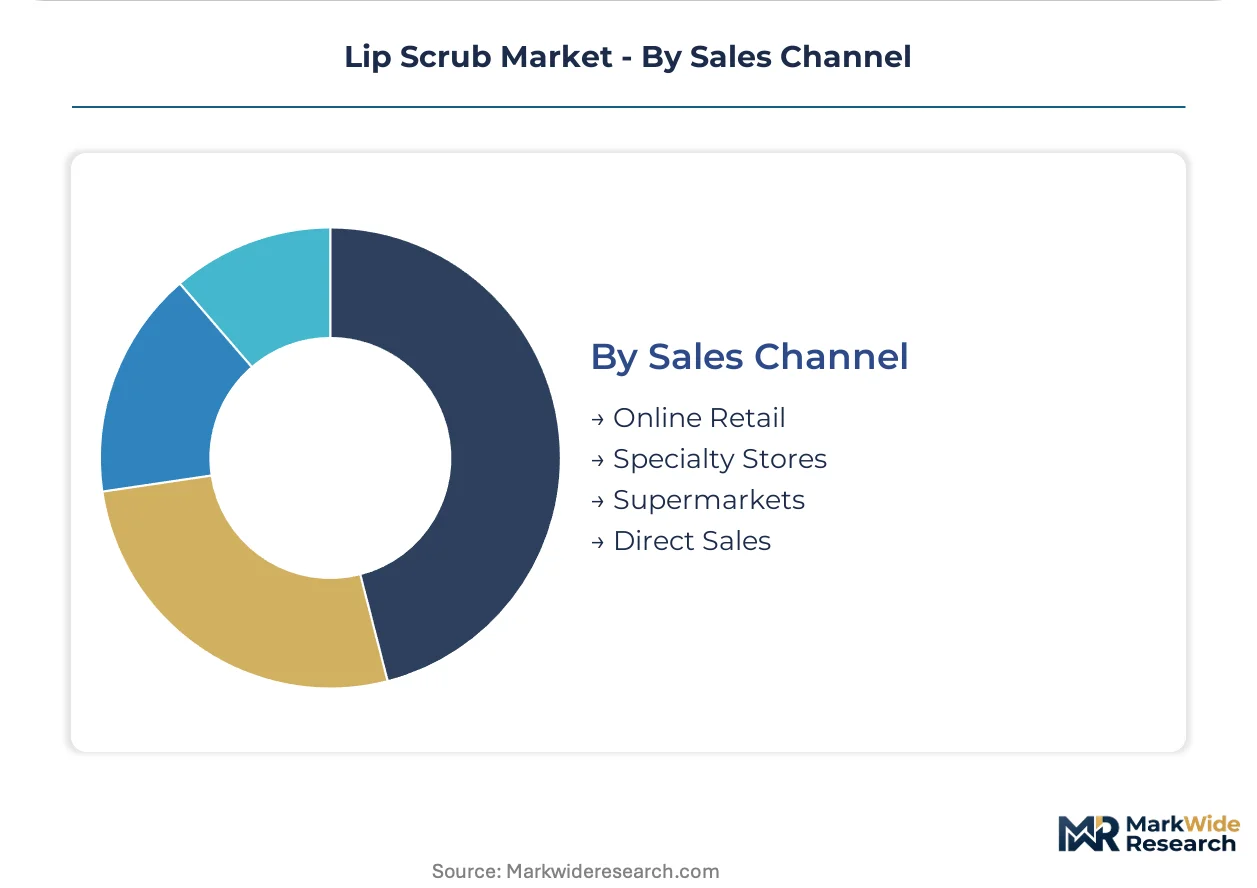
- Online Retail:Direct-to-consumer and marketplace platforms enabling flexible small-batch production response. Subscription box curation now specifies clean ingredient profiles and sustainable packaging as mandatory inclusion criteria.
- Specialty Stores:Prestige beauty retailers expanding shelf space for lip scrubs as consumers prioritize pre-makeup lip preparation. First-mover whitespace exists in Indian urban premium channels where lip scrub SKU density under-indexes relative to facial exfoliants.
- Supermarkets:Mass-market accessibility with broad retail penetration. Fixed annual planning cycles constrain responsiveness compared to agile direct-to-consumer competitors.
- Direct Sales:Consultant-mediated distribution with personalized education and sampling. Social commerce integration is modernizing this historically relationship-dependent channel.
Established volume flows through Specialty Stores. Gaining share fastest is Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty beauty corridors in Seoul's Gangnam district and Dubai's Jumeirah Lakes Towers concentrate premium lip scrub distribution, with tax-advantaged free zones accelerating brand entry into adjacent markets.
United States
Direct-to-consumer subscription services and Sephora flagship locations in New York and Los Angeles drive pre-makeup exfoliation rituals. FDA cosmetic labeling requirements elevate compliance costs for entrants lacking dedicated regulatory infrastructure. Greater Boston hosts biotechnology firms developing encapsulated enzyme systems for hybrid exfoliation formats.
Germany
Clean beauty certification demand from Hamburg and Munich specialty retailers compresses formulation timelines for EU Cosmetics Regulation compliance. ECHA REACH enforcement on micro-ingredient disclosure protects established brands with existing regulatory affairs teams. The Rhine-Ruhr industrial corridor supplies biodegradable particle systems tested to OECD 301 protocols.
United Kingdom
Beauty box subscription curation in London specifies sustainable packaging and clean ingredient profiles as mandatory inclusion criteria. The UK Cosmetics Regulation maintains alignment with EU standards post-Brexit, preserving dual-market formulation efficiency. Manchester-based indie brands leverage flexible small-batch production to respond faster than mass-market competitors.
India
Specialty retailers in Mumbai and Delhi under-index on lip scrub SKU density relative to facial exfoliants, presenting first-mover whitespace for premium positioning. BIS cosmetic standards and DGFT import regulations shape ingredient sourcing strategies. Bangalore's direct-to-consumer startups exploit agile supply chains to test formulations before national rollout.
Japan
Department store beauty halls in Tokyo's Ginza district prioritize sensorial, ingredient-forward formulations with minimalist packaging aesthetics. METI guidelines on sustainable packaging and PMDA cosmetic safety substantiation elevate entry barriers. Osaka-based formulators specialize in waterless anhydrous systems that extend shelf life without synthetic preservatives.
Lip Scrub Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered price positioning. L'Oréal S.A. and Unilever N.V./PLC anchor mass-market and premium segments through scale advantages and retail penetration. The market exhibits moderate consolidation with three strategic archetypes: multinational beauty houses, clean beauty specialists, and agile direct-to-consumer startups. Dominant competitive moves include portfolio diversification into complementary lip care formats and geographic expansion through specialty retail partnerships.
Within the multinational tier, L'Oréal S.A., Unilever N.V./PLC, and Fresh exemplify divergent positioning strategies. The Paris-based L'Oréal S.A. occupies a scale-driven position leveraging multi-product skincare set architecture. London-anchored Unilever N.V./PLC represents mass-market accessibility through broad retail channel presence. Fresh, operating as a prestige-focused specialist, anchors sensorial formulation differentiation within clean beauty channels.
| Leading Market Players |
|---|
| Revlon, Inc. |
| Unilever N.V./PLC |
| L'Oréal S.A. |
| Dr.PAWPAW |
| Carma Labs, Inc. |
| Kao Corporation |
| The Clorox Company |
| Fresh |
| Beiersdorf AG |
| Others |
Supply & Pricing Matrix
Premium jar-packaged formulations versus mass-market squeeze tubes bifurcate pricing architectures and sourcing strategies across the lip scrub category. REACH-compliant sugar particle systems and certified organic emollient bases command procurement premiums from West African and Southeast Asian suppliers, while anhydrous waterless formulations reduce preservative costs but constrain texture innovation pipelines.
Pricing Analysis
Short lead-time premiums attach to small-batch organic certifications that bypass conventional six-to-nine-month OECD 301 biodegradability validation cycles. Three-tier pricing structure across premium, standard, and economy levels separates EU Cosmetics Regulation-certified specialty retail placement from mass-market supermarket accessibility. Price differentiation stems from clean beauty certification tier and volume scale commitments. Pricing pressure stems from shea butter and coconut oil agricultural yield volatility compressing fixed-price retail contract margins. Direct-to-consumer subscription buyers exhibit lowest price sensitivity; supermarket mass-market segments show highest elasticity.
Supply Chain Analysis
Direct-to-specialty-retail channels handle premium positioning demand through Sephora flagship locations and dedicated clean beauty distributors. Raw material sourcing concentrates in Ghana and Nigeria for shea butter, Indonesia and the Philippines for coconut oil, and Brazil for up-cycled coffee particles. Formulation depends on crystalline sucrose from European beet sugar processors and biodegradable particle system innovators in the Rhine-Ruhr industrial corridor. Single-source fragrance allergen suppliers in Southern Europe create bottleneck exposure during reformulation cycles. Distribution runs through direct-to-consumer platforms, specialty beauty retailers, and mass-market supermarket networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lip scrub category functions as a vertical-integration race where control over certified organic emollient sourcing and REACH-compliant particle innovation determines margin capture. Players are pursuing backward integration into West African shea butter cooperatives and Southeast Asian coconut oil estates to secure supply predictability.
For Market Incumbents: Hedge against clean beauty certification compression by locking multi-year organic supply agreements with Ghanaian and Nigerian agricultural cooperatives before competitor offtake tightens availability. Defend shelf space at Sephora and specialty retailers through exclusive encapsulated enzyme exfoliation technology partnerships with Greater Boston biotechnology firms. Prioritize circular infrastructure investments in refillable aluminum jar formats ahead of EU Green Deal mandates.
For New Entrants and Emerging Players: The mid-tier price-point gap between L'Oréal S.A. premium positioning and Unilever N.V./PLC mass-market accessibility offers white-space capture opportunity. Target Mumbai and Delhi specialty retail channels where lip scrub SKU density under-indexes facial exfoliants by significant margins. Exploit agile small-batch production to satisfy subscription box curation requirements for clean ingredient profiles and sustainable packaging faster than mass-market annual planning cycles permit.
For Investors and Strategic Acquirers: Re-rating potential sits with direct-to-consumer startups possessing flexible supply chains and existing EU regulatory affairs infrastructure given REACH Annex XVII enforcement acceleration. Acquisition targets should demonstrate validated OECD 301 biodegradable particle systems and established specialty retail placement in at least two of the United States, Germany, or United Kingdom. Monitor ECHA micro-ingredient disclosure mandate expansion as signal for compliance cost barriers favoring scaled incumbents over capital-constrained entrants.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emollient Supply | Captive shea butter and coconut oil sourcing from West African and Southeast Asian estates reduces agricultural yield volatility exposure. |
| EU Green Deal Circular Infrastructure Investment | Refillable aluminum vessel capabilities position brands ahead of 2030 packaging mandate compliance deadlines. |
| Encapsulated Enzyme Technology Partnership | Hybrid exfoliation formats with Greater Boston biotechnology firms command premium positioning in prestige dermatology channels. |
| Specialty Retail Expansion in Indian Urban Corridors | First-mover SKU density capture in Mumbai and Delhi exploits under-indexed lip scrub placement relative to facial exfoliants. |
| Subscription Box Curation Compliance | Clean ingredient profile and sustainable packaging certification unlocks United States and United Kingdom beauty box discovery mechanisms. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this lip scrub market analysis. Primary interviews with cosmetic chemists, specialty beauty retail buyers, clean beauty brand founders, EU regulatory affairs consultants, and West African agricultural cooperative managers combined with secondary validation from FDA cosmetic labeling guidance, ECHA REACH enforcement documentation, EU Cosmetics Regulation amendment tracking, and OECD 301 biodegradability testing protocols. Nielsen retail audit data and Circana point-of-sale tracking supplied volume benchmarking. Bottom-up SKU-level modeling and top-down category sizing triangulated market estimates.
Data-stream reconciliation across formulation technology adoption curves, packaging format shipment volumes, and channel-specific price positioning generated consistent trajectory outputs. Segmentation dimensions modeled include exfoliation modality, ingredient certification tier, packaging format, and sales channel economics across the projection horizon. CAGRs derived from historical growth pattern analysis adjusted for regulatory catalyst timing and clean beauty certification penetration curves. Forecast inputs incorporated biodegradable particle system qualification timelines and specialty retail shelf space expansion rates.
Inputs from ECHA enforcement databases, FDA cosmetic registration filings, and Indian BIS cosmetic standards were available through the study window; gaps in real-time West African agricultural yield data and fragrance allergen supplier capacity introduce uncertainty bands around emollient cost assumptions. Forecasts reflect documented base assumptions regarding REACH Annex XVII expansion scope and EU Green Deal implementation pacing. Periodic stress-testing of base assumptions against regulatory announcement calendars and commodity price volatility indices is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Waterproof Temporary Tattoo Sticker Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Global Cosmetic Applicator Foam Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Foundation Cream Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Canada Cosmetic Products Market
Cosmetics & Skincare
Face Bronzer Market
Cosmetics & Skincare
China Cosmetic Products Market