
 Kuwait Perfume Market | 2026-2036
Kuwait Perfume Market Size, Share, and Industry Trends Forecast 2026-2036
Kuwait Perfume Market Intelligence
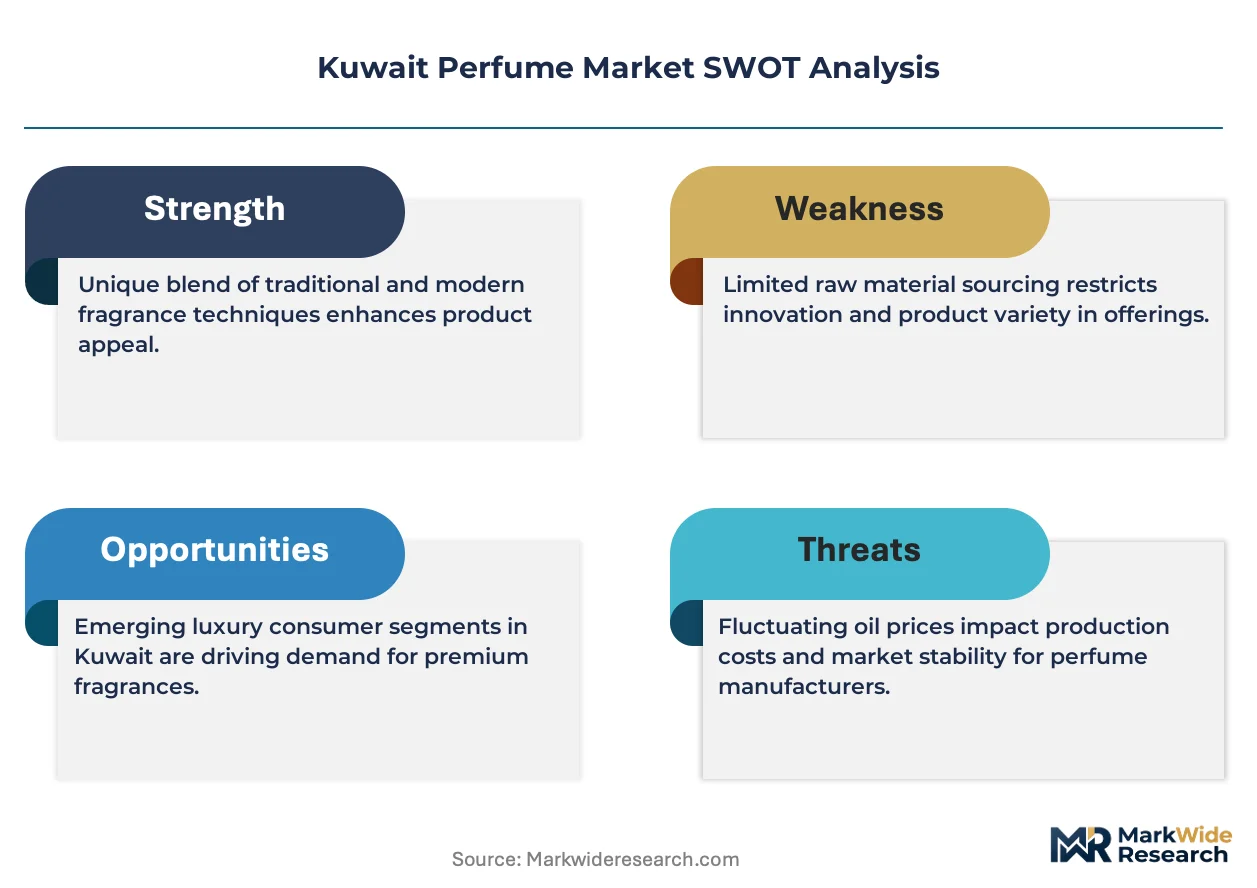
Premium attar concentration tiers are bifurcating the Kuwait perfume landscape into artisanal oud houses and mass-market Western labels. Swiss Arabian Perfumes leverages its captive distillation facilities in Jebel Ali to secure raw oud supply chains. Arabian Oud anchors the domestic retail footprint with flagship boutiques across Kuwait City's luxury corridors. Abdul Samad Al Qurashi differentiates through single-origin agarwood sourcing and bespoke blending services.
Kuwait perfume denotes alcohol-based and oil-based fragrance formulations with concentration levels spanning parfum extrait to eau fraîche, typically incorporating oud, amber, musk, or synthetic aromachemicals for personal scent application. Manufacturing involves maceration, enfleurage, or molecular distillation to achieve desired sillage and longevity profiles. The product type dimension shows Arabian perfumes commanding margin pools through oud scarcity premiums, while eau de parfum competes on volume turnover in department store placements. Gender segmentation reveals unisex formulations outpacing traditional masculine and feminine lines among under-35 buyers.
Kuwait's Ministry of Commerce and Industry enforces labeling standards aligned with Gulf Standardization Organization cosmetic directives, while the Public Authority for Industry administers import licensing for fragrance raw materials. These frameworks elevate compliance costs for new entrants but reinforce quality signaling for established houses with in-house regulatory teams. Stakeholders must monitor potential GCC tariff harmonization and evolving halal certification requirements for alcohol content disclosure.
Market Dynamics
The Ministry of Commerce and Industry's stricter labeling requirements for imported cosmetics are forcing fragrance houses to reconfigure compliance infrastructure and localize documentation workflows. This regulatory tightening concentrates advantage among established players with captive regulatory teams while elevating barriers for new import entrants.
Growth Catalysts
- Gulf Standardization Organization cosmetic directives:Harmonized labeling standards across GCC member states enable economies of scale in packaging design and reduce per-market adaptation costs for regional fragrance distributors.
- Unisex formulation demand:Under-35 consumers in Kuwait City and Salmiya are rejecting traditional gender-segmented scent marketing, expanding addressable SKU efficiency for houses with flexible blending capabilities.
- Specialty retail channel expansion:Flagship boutique clusters in The Avenues mall district and luxury corridors concentrate high-margin foot traffic, reducing customer acquisition costs for premium attar houses.
Market Restraints
- Agarwood supply concentration:Raw oud sourcing depends on Southeast Asian plantation networks and wild harvest quotas, exposing Kuwaiti blenders to price volatility and authenticity verification costs.
- Import licensing friction:The Public Authority for Industry administers fragrance raw material permits through case-by-case review, extending procurement lead times for non-captive supply chains.
- Synthetic aromachemical substitution:Mass-market Western labels leverage molecular distillation outputs to undercut natural oud scarcity premiums, compressing margin pools in mid-tier concentration tiers.
Strategic Opportunities
- Halal certification evolution:Emerging alcohol content disclosure mandates from Gulf religious authorities create first-mover advantage for oil-based parfum extrait specialists with transparent formulation documentation.
- Bespoke blending services:Single-origin agarwood sourcing combined with in-house maceration capabilities enables premium tier expansion through personalized scent commissioning.
- Governorate-level retail penetration:Specialty fragrance presence remains underdeveloped in Jahra and Farwaniya compared to Kuwait City, offering whitespace for mall-based boutique expansion.
Industry Challenges
- Regulatory documentation complexity:The Ministry of Commerce and Industry's ingredient disclosure requirements demand Arabic-English bilingual labeling with batch traceability, straining smaller importers without dedicated compliance personnel.
- Enfleurage craft scarcity:Traditional oil extraction techniques requiring skilled labor face generational knowledge gaps, limiting artisanal production scaling for heritage Kuwaiti perfume houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Kuwait Perfume Market |
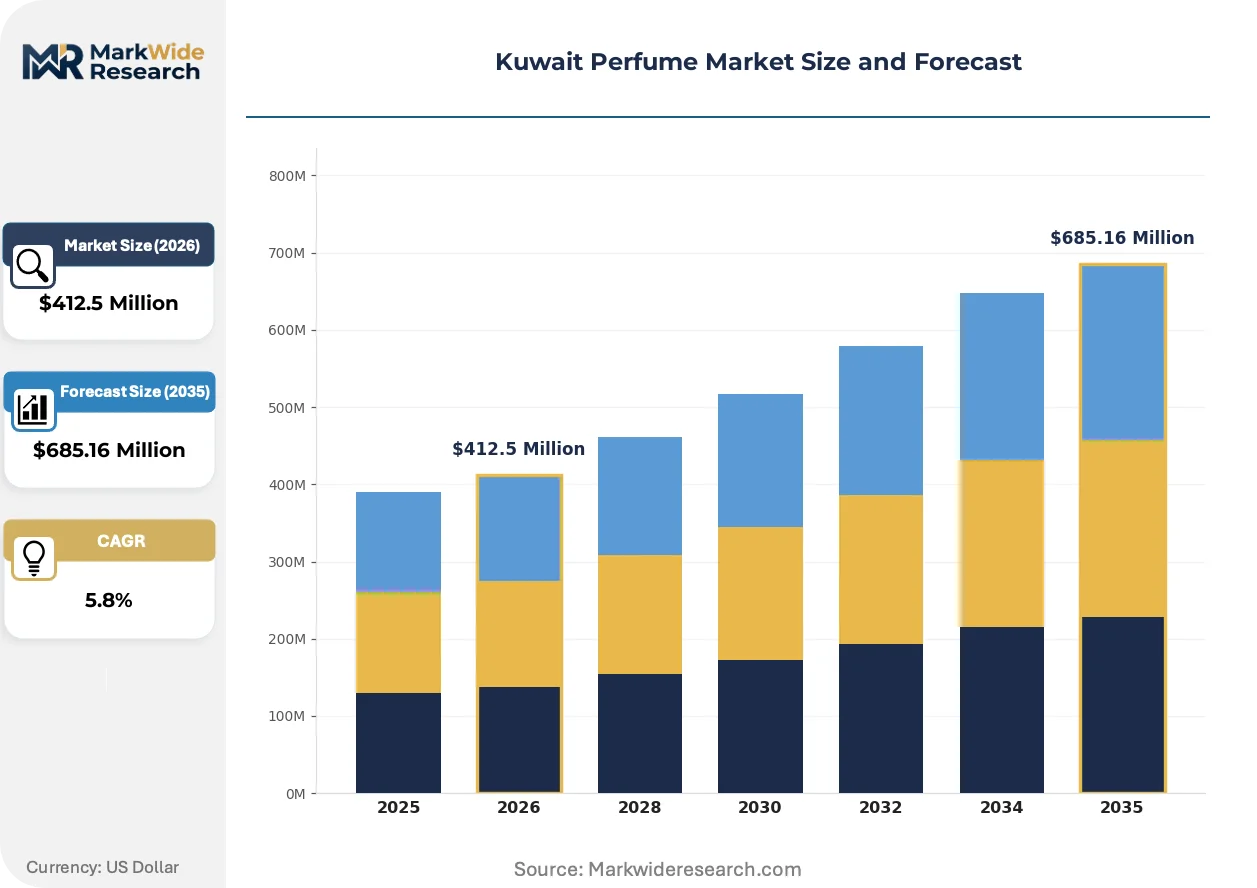
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $685.16 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Arabian Perfumes, Western Perfumes, Attars, Eau de Parfum Gender: Men, Women, Unisex, Children Occasion: Daily Wear, Formal Events, Special Occasions, Gifting Distribution Channel: Online Retail, Specialty Stores, Department Stores, Supermarkets |
| Companies Covered | Swiss Arabian Perfumes, Arabian Oud, Al Haramain Perfumes, Dior, Chanel, Ajmal Perfumes, Abdul Samad Al Qurashi, Tom Ford, Rasasi Perfumes, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Kuwait Perfume Market Strategic Shifts & Innovations
Molecular distillation technology is fragmenting traditional extraction economics while consumer preference data from specialty retail channels enables dynamic SKU optimization. These forces are compressing product development cycles and reconfiguring competitive moats around formulation transparency rather than supply chain opacity.
Supercritical CO2 extraction is decomposing conventional solvent-based methods for oud and amber resin recovery. Premium houses in Salmiya are adopting this technology to preserve volatile top notes and reduce residual solvent detection. The shift is decomposing historical quality differentiation based on extraction heritage, enabling newer entrants to match organoleptic profiles with lower batch-to-batch variation.
The Ministry of Commerce and Industry's alignment with Gulf Standardization Organization cosmetic directives is mandating ingredient percentage disclosure and allergen flagging on all imported fragrance packaging. This policy compression forces reformulation of legacy Western eau de parfum lines and elevates documentation costs. Oil-based Arabian perfume segments with simpler ingredient matrices are adapting faster than alcohol-heavy import portfolios.
Specialty retail foot traffic patterns are shifting toward experience-driven purchasing in Kuwait City's luxury corridors. Consumers now expect on-site blending consultation and sample customization before committing to full-bottle purchases. This behavioral pivot is most visible in The Avenues mall district, where flagship boutiques with captive maceration facilities capture higher conversion rates than traditional department store counter placements.
Kuwait Perfume Market Segmentation
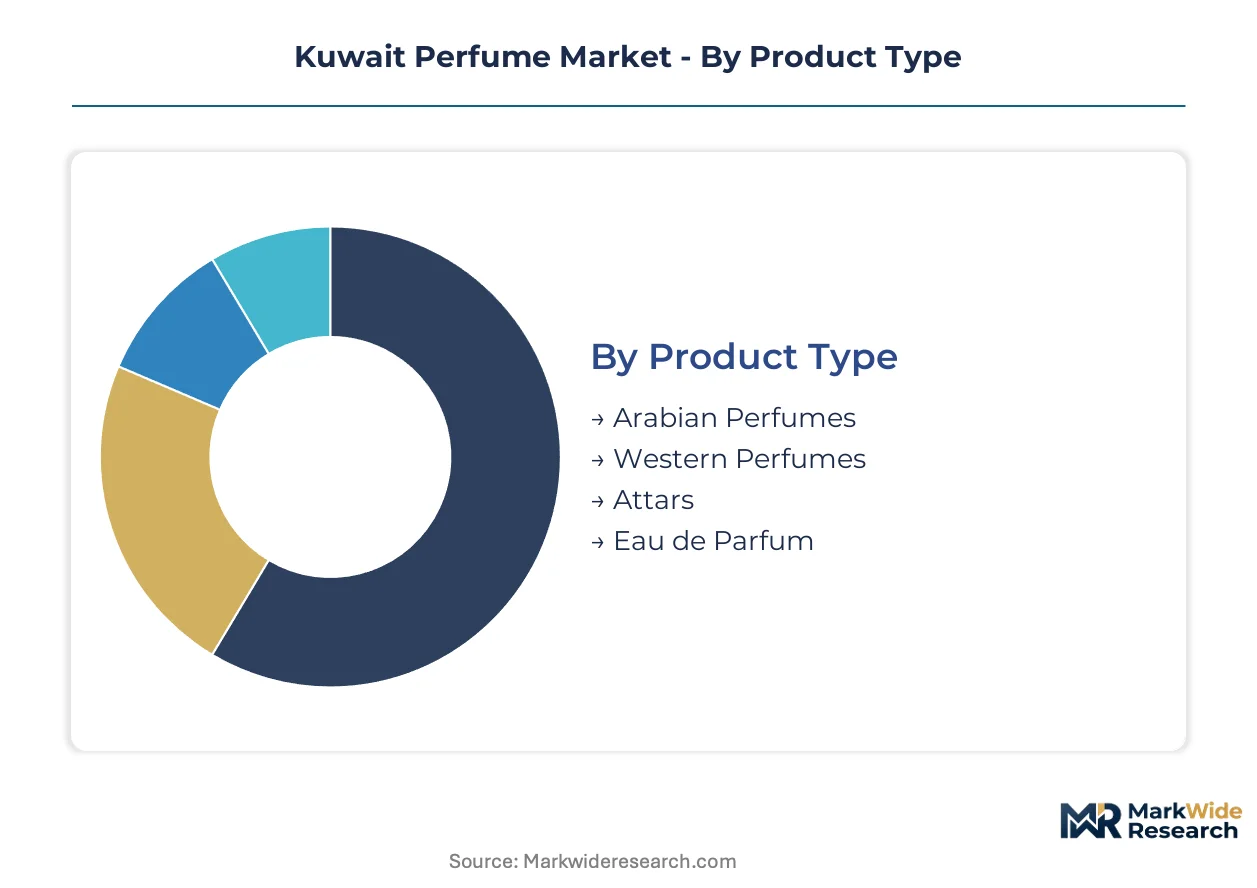
Kuwait's perfume segmentation reveals distinct channel affinities that shape margin capture and inventory velocity. Specialty retail corridors in Salmiya and The Avenues concentrate high-value transactions, while digital penetration accelerates among younger cohorts seeking discovery-driven purchasing.
Product Type:
Channel placement diverges sharply between oil-based heritage formats and alcohol-heavy Western imports, with regulatory compliance costs driving portfolio reconfiguration.
- Arabian Perfumes:Oil-based formulations featuring oud, amber, and musk dominate specialty boutique footprints in Kuwait City's luxury corridors. Concentrated parfum extrait formats command scarcity premiums through single-origin agarwood sourcing, with flagship locations in The Avenues capturing conversion rates above department store placements.
- Western Perfumes:Alcohol-based eau de parfum and eau de toilette lines distribute primarily through department store counters and duty-free channels. The Ministry of Commerce and Industry's bilingual labeling mandates impose heavier documentation burdens on these imports, extending time-to-shelf for new launches.
- Attars:Traditional concentrated oil perfumes with regional distillation heritage.
- Eau de Parfum:Mid-concentration alcohol-based sprays competing on volume turnover in mass retail.
By volume, Eau de Parfum leads through broad retail distribution. By growth pace, Arabian Perfumes are expanding most quickly on unisex demand and experience-driven flagship expansion.
Gender:
Marketing architectures are fragmenting as demographic cohorts reject traditional segmentation, forcing SKU rationalization and flexible blending investments.
- Men:Woody and oud-forward compositions retain strength in formal occasion purchasing through specialty channels in Salmiya.
- Women:Floral-oriental hybrids maintain department store presence but face share pressure from gender-neutral alternatives.
- Unisex:Formulations eschewing traditional gender coding now dominate under-35 purchasing in Kuwait City and Jahra governorates. Houses with captive maceration facilities capture this shift through on-site customization services that drive premium tier conversion.
- Children:Alcohol-free and hypoallergenic variants distributed through pharmacy and supermarket channels.
Unisex claims the steepest expansion trajectory as generational preferences reshape scent marketing. Men retains the largest absolute transaction base through established gift-giving patterns.
Occasion:
Purchase triggers map to distinct retail environments, with gifting occasions concentrating in mall-based flagship experiences and daily wear fragmenting across channels.
- Daily Wear:Lower-concentration formats with replenishment-driven purchasing through supermarket and online channels. Price sensitivity elevates here, compressing margin pools for premium houses without accessible tier offerings.
- Formal Events:Signature scents with extended longevity requirements concentrate in specialty store consultations. The Avenues mall district captures this occasion through experiential blending services that justify full-bottle commitment.
- Special Occasions:Limited editions and bespoke commissions with highest per-unit margins.
- Gifting:Seasonally concentrated demand with packaging and presentation premiums.
Gifting generates peak seasonal revenue concentration. Daily Wear shows the most channel fragmentation as digital penetration disrupts traditional replenishment patterns.
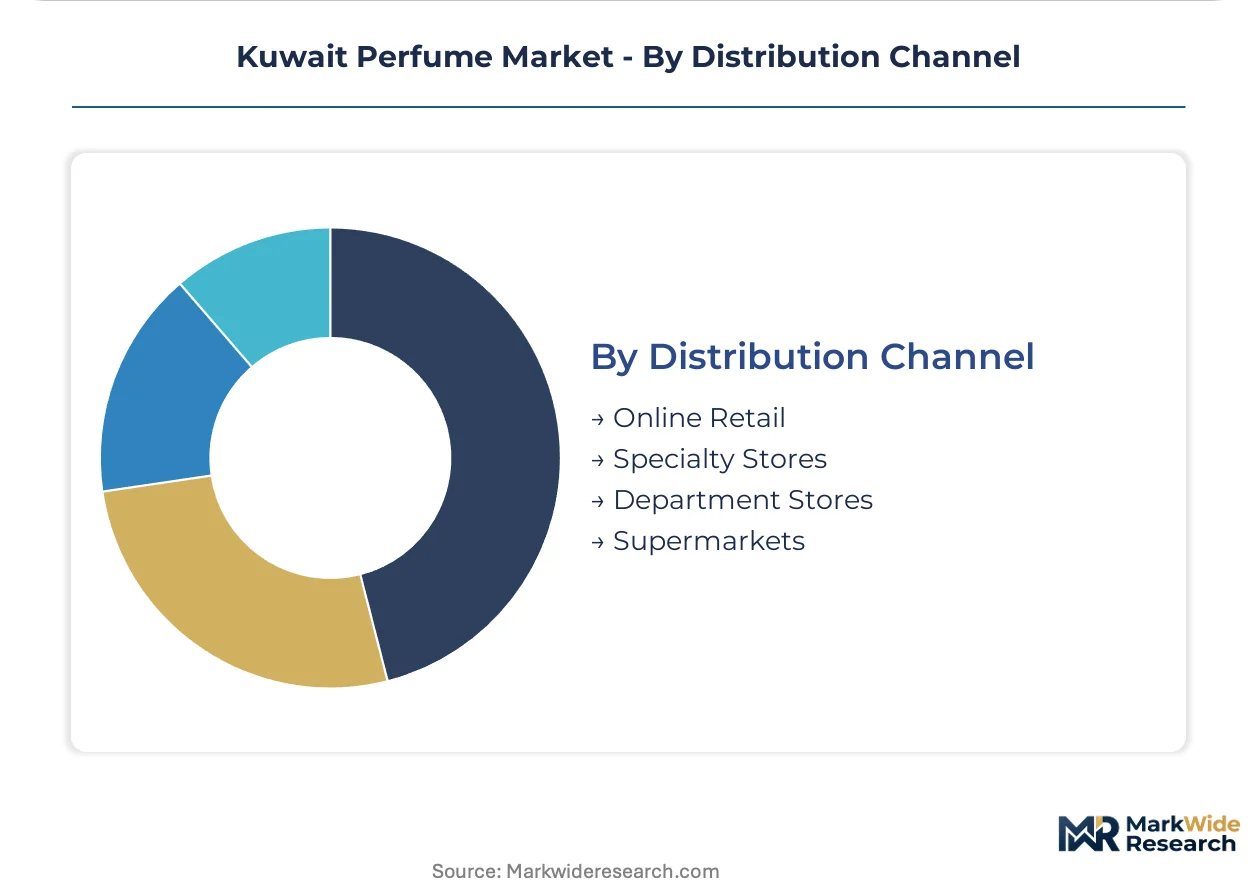
Distribution Channel:
Physical retail retains experiential dominance for discovery and commitment, while logistics infrastructure investments unlock geographic penetration beyond Kuwait City.
- Specialty Stores:Flagship boutiques with captive maceration and blending consultation in Salmiya and The Avenues. These locations capture the highest margin per square meter through personalized service and exclusive house releases unavailable in broader retail.
- Department Stores:Multi-brand counters with traffic volume advantages but declining conversion rates as consumers shift toward experience-driven specialty formats.
- Online Retail:Digital channels accelerating in Farwaniya and Jahra governorates where specialty retail penetration remains underdeveloped. Sample-to-full-bottle subscription models reduce customer acquisition costs for emerging houses.
- Supermarkets:Mass-market accessibility for replenishment purchasing with compressed margins.
Specialty Stores command the highest revenue per transaction. Online Retail is gaining share fastest on governorates beyond Kuwait City's retail core.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fragrance trade corridors from Southeast Asian agarwood plantations feed Kuwait's blending houses, while European luxury houses route alcohol-based formulations through Gulf distribution hubs. Domestic demand concentrates in Kuwait City and surrounding governorates, with regulatory frameworks from the Ministry of Commerce and Industry shaping cross-border flow patterns.
Kuwait City
Specialty retail corridors in Salmiya and The Avenues mall district anchor premium attar consumption among under-35 buyers seeking unisex formulations. The Ministry of Commerce and Industry's bilingual labeling mandates impose heavier documentation burdens on imported Western lines than on oil-based heritage formats. Flagship boutiques with captive maceration facilities capture conversion rates above traditional department store placements through experiential blending services.
Jahra Governorate
Digital channels accelerate fragrance penetration where specialty retail presence remains underdeveloped, with sample-to-full-bottle subscription models reducing customer acquisition costs. The Public Authority for Industry's case-by-case import licensing for raw materials extends procurement lead times for non-captive supply chains. Mall-based boutique expansion offers whitespace for premium houses targeting gifting occasions and formal event purchasing.
Farwaniya Governorate
Online retail gains share fastest among younger cohorts seeking discovery-driven purchasing beyond Kuwait City's retail core. Gulf Standardization Organization cosmetic directives enable economies of scale in packaging design for regional distributors serving this perimeter market. Logistics infrastructure investments unlock geographic penetration for emerging houses with flexible SKU portfolios.
Hawalli Governorate
Replenishment-driven daily wear purchasing fragments across supermarket and digital channels, compressing margin pools for premium houses without accessible tier offerings. Stricter ingredient disclosure requirements from the Ministry of Commerce and Industry force reformulation of legacy import lines with complex alcohol-based matrices. Industrial clustering around Salmiya concentrates blending consultation and bespoke commissioning services.
Ahmadi Governorate
Formal occasion and gifting demand concentrates in mall-based flagship experiences, with seasonal revenue peaks tied to religious and social calendars. Halal certification evolution around alcohol content disclosure creates positioning advantage for oil-based parfum extrait specialists. The governorate's residential density supports neighborhood-scale distribution for mass-market accessibility tiers.
Kuwait Perfume Market Key Industry Players
Listed luxury conglomerates compete with private heritage houses across formulation philosophy and channel strategy. The market structure bifurcates between alcohol-based Western imports subject to heavier regulatory documentation and oil-based Arabian formats with simpler compliance matrices. Three archetypes dominate: European luxury houses leveraging brand equity, Gulf-based heritage blenders controlling agarwood supply chains, and regional specialists offering bespoke services. Competitive moves concentrate on flagship boutique expansion and captive distillation investments.
Within the heritage blending tier, Swiss Arabian Perfumes and Arabian Oud exemplify scale-driven regional positioning, while Abdul Samad Al Qurashi occupies a specialist niche emphasizing single-origin sourcing. These entities anchor the competitive landscape through distinct supply chain configurations and retail footprint strategies.
| Leading Market Players |
|---|
| Swiss Arabian Perfumes |
| Arabian Oud |
| Al Haramain Perfumes |
| Dior |
| Chanel |
| Ajmal Perfumes |
| Abdul Samad Al Qurashi |
| Tom Ford |
| Rasasi Perfumes |
| Others |
Cost & Logistics Intelligence
Synthetic aromachemical substitution for natural agarwood is redrawing sourcing maps from Southeast Asian plantations to European molecular distillation facilities while collapsing scarcity premiums that once anchored Kuwaiti attar pricing tiers. This displacement simultaneously compresses mid-market margins and forces heritage houses to recalibrate around single-origin provenance claims.
Pricing Analysis
Extraction-methodology pricing gaps separate supercritical CO2 outputs from traditional enfleurage batches and emerging solvent-free molecular distillation lines. Three-tier pricing structure across artisanal parfum extrait, blended house signatures, and mass-market eau de parfum reflects concentration purity and origin documentation depth. Cost compression in synthetic-substitute tiers is intensifying because molecular aromachemical production scales without agarwood harvest quotas. Daily wear purchasers in supermarket channels exhibit highest price sensitivity, while bespoke commissioning clients in Salmiya specialty boutiques accept substantial premiums for batch-traceable single-origin sourcing.
Supply Chain Analysis
Port congestion at Jebel Ali and container availability constraints on Southeast Asia-Gulf trade lanes are extending replenishment cycles for raw oud shipments. Agarwood supply concentrates in Cambodian plantation networks, Thai wild harvest zones, and Indian Assam reserves, with Kuwaiti blenders drawing from these nodes through Dubai consolidation hubs. Feedstock rests on distillation-grade resin quality, sustainable harvest certification, and Gulf Standardization Organization import clearance documentation. Single-source vulnerability from Cambodian export quota restrictions threatens inventory continuity for non-captive supply chains. Distribution runs through specialty boutique flagships in The Avenues and Salmiya, with online channels penetrating Jahra and Farwaniya governorates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Kuwait's perfume sector sits in early-cycle expansion as under-35 unisex adoption penetrates governorates beyond traditional Kuwait City retail corridors, with regulatory harmonization across GCC states enabling regional packaging economies of scale.
For Market Incumbents: Secure captive agarwood supply through backward integration into Southeast Asian plantation equity or long-term offtake agreements with Cambodian and Thai harvest cooperatives. Defend margin position by accelerating halal certification documentation ahead of evolving alcohol disclosure mandates from Gulf religious authorities, converting compliance lead time into specialty channel exclusivity. For New Entrants and Emerging Players: Gulf Standardization Organization cosmetic directive pre-certification creates expedited market access versus legacy Western import portfolios requiring reformulation. Target Farwaniya and Jahra governorates where specialty retail penetration lags Kuwait City and digital discovery-to-purchase funnels reduce customer acquisition costs. Launch sample-to-full-bottle subscription models with localized Arabic-English packaging to bypass department store counter saturation. For Investors and Strategic Acquirers: Capital is best deployed toward heritage houses with in-house maceration capabilities and single-origin sourcing relationships that resist synthetic substitution erosion. Long-term viability hinges on formulation transparency credentials and experiential retail footprints in high-traffic mall districts. Watch for inflection in Ministry of Commerce and Industry enforcement intensity around ingredient percentage disclosure as signal for compliance-cost barrier elevation.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Agarwood Sourcing | Backward integration into Cambodian plantation networks secures raw material continuity against harvest quota volatility. |
| Halal Certification Acceleration | Transparent oil-based formulation documentation from Gulf religious authorities creates first-mover positioning advantage. |
| Specialty Boutique Expansion | Flagship presence in Jahra and Farwaniya malls captures whitespace before competitor saturation. |
| Supercritical CO2 Technology Adoption | Advanced extraction preserves volatile top notes and reduces batch-to-batch organoleptic variation for premium tiers. |
| Bespoke Blending Service Launch | On-site customization in Salmiya and The Avenues drives conversion rates above traditional department store placements. |
Research Approach
A standing panel of fragrance house blending directors, specialty retail boutique managers, Ministry of Commerce and Industry compliance officers, and agarwood import brokers provided ongoing calibration across the analysis window. Primary interviews with these stakeholders combined with secondary validation from Gulf Standardization Organization directive filings, Kuwait Public Authority for Industry licensing records, and regional customs trade data. Bottom-up SKU-level demand modeling and top-down macroeconomic triangulation anchored volume and value estimates.
Consistency checks against external benchmarks validated projection outputs across the modeling period. The analytical framework segmented demand by product type, gender orientation, occasion-based purchasing trigger, and distribution channel intensity, with additional disaggregation by governorate-level retail penetration. CAGRs were derived from trend extrapolation of unisex formulation adoption curves and specialty channel expansion rates, incorporating agarwood price volatility indices and synthetic aromachemical substitution elasticities as key inputs.
Decision-makers should treat outputs as directional under assumptions of continued GCC regulatory harmonization and stable Southeast Asian agarwood export flows; material deviation in either vector would warrant model refresh. Specific risks include abrupt Ministry of Commerce and Industry labeling enforcement spikes, Cambodian wild harvest moratoriums, or accelerated molecular distillation cost parity breakthroughs. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fragrances & Perfumes
Gourmand Fragrance Market
Fragrances & Perfumes
Cosmetic and Fragrance Retail Chain Market
Fragrances & Perfumes
Mini Refillable Perfume Bottles Market
Fragrances & Perfumes
Perfume Vials Market
Fragrances & Perfumes
Global Scented Candle Market
Fragrances & Perfumes
GCC Perfume Market
Fragrances & Perfumes
Global Fragrances and Perfumes Market
Fragrances & Perfumes
Middle East Fragrances Market
Fragrances & Perfumes
North America Perfume Market
Fragrances & Perfumes
Global Fragrance Market
Fragrances & Perfumes
Fragrance Diffuser Market
Fragrances & Perfumes
Gulf Cooperation Council Fragrance and Perfumes Market
Fragrances & Perfumes
Home Fragrance Market
Fragrances & Perfumes
Home Fragrance Diffusers Market
Fragrances & Perfumes
Global Luxury Perfumes Market
Fragrances & Perfumes
Saudi Arabia E-Commerce Cosmetics and Fragrances Market