
 Cold Pressed Soap Market | 2026-2036
Cold Pressed Soap Market Size, Share, and Industry Trends Forecast 2026-2036
Cold Pressed Soap Market Outlook
Direct-to-consumer subscription channels is reshaping how cold pressed soap brands build recurring revenue and capture customer lifetime value. Dr. Squatch leverages aggressive digital marketing and lifestyle branding to dominate male-oriented grooming subscriptions. Poleview Biotech Co., Ltd anchors its position through OEM manufacturing scale and private-label partnerships across Asia-Pacific markets. Chagrin Valley Soap & Salve differentiates through certified organic supply chains and transparent ingredient sourcing that commands premium shelf placement.
Cold pressed soap denotes cleansing bars manufactured without external heat application, typically saponified below 49 degrees Celsius using alkali and vegetable oils such as olive, coconut, or shea butter to preserve heat-sensitive vitamins and glycerin content. The process yields superfatted bars with retained emollient properties suited for sensitive skin and dermatological applications. Organic formulations within the Product Type segment command margin premiums due to certification costs and limited ingredient pools, while Exfoliating variants capture fastest-growing interest from spa and salon procurement channels. Online distribution within the Distribution Channel segment shows structural acceleration as algorithm-driven discovery replaces traditional health store foot traffic for artisan and scented product trials.
EPA oversight of cosmetic ingredient safety and FTC enforcement against unsubstantiated natural claims shape product labeling and marketing compliance burdens for US-based manufacturers. ECHA REACH registration requirements for essential oil imports and colorant additives restrict European market access for uncertified producers. ISO 16128 guidelines on natural and organic cosmetic content provide harmonized technical benchmarks that multinational formulators increasingly adopt to streamline cross-border certification. Stakeholders must monitor evolving state-level clean beauty legislation in California and New York alongside EU Green Deal chemical restriction timelines to anticipate reformulation mandates and compliance cost shifts.
Market Dynamics
Direct-to-consumer subscription channels are compressing traditional wholesale margins while algorithm-driven discovery replaces health store foot traffic for artisan soap trials. REACH compliance in the European Union and EPA oversight in the United States are forcing simultaneous reformulation investments across export-oriented manufacturers.
Growth Catalysts
- REACH transparency mandates:ECHA registration requirements for essential oil imports push uncertified producers out of European distribution, consolidating shelf access for compliant formulators.
- Specialty spa procurement:Premium treatment menus in Germany and France now specify cold pressed formulations, creating institutional demand anchors for certified organic supply chains.
- Shea butter and olive oil superfatting:Heat-sensitive vitamin retention in below-49-degree-Celsius saponification enables dermatological positioning that commands margin premiums in sensitive-skin segments.
Market Restraints
- Organic certification cost structure:Limited ingredient pools and third-party audit expenses compress margins for small-batch producers seeking premium positioning.
- Plant-derived colorant supply concentration:Dependency on specific geographic harvests for natural pigments creates batch-to-batch inconsistency that challenges brand standardization.
- FTC enforcement friction:Unsubstantiated natural claims trigger compliance investigations that delay product launches and require legal review of all marketing collateral.
Strategic Opportunities
- Exfoliating variant white space:Spa and salon procurement channels show fastest-growing interest in textured formulations that command treatment-menu premiums.
- Australian direct-to-consumer expansion:Artisan markets in Sydney and Melbourne demonstrate underpenetrated demand for transparent ingredient sourcing and certified organic positioning.
- ISO 16128 harmonization:Multinational formulators adopting unified natural-content benchmarks can streamline cross-border certification and reduce duplicate testing costs.
Industry Challenges
- Cold-process chemistry skill scarcity:Superfatting precision and trace alkali neutralization require trained artisans that artisan-scale producers struggle to retain against corporate cosmetic formulators.
- California clean beauty timeline compression:State-level chemical restriction mandates force reformulation cycles that outpace existing certification renewal schedules.
- Legacy retail inventory reconfiguration:Health store foot traffic decline leaves excess shelf commitments that constrain working capital for digital channel investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cold Pressed Soap Market |
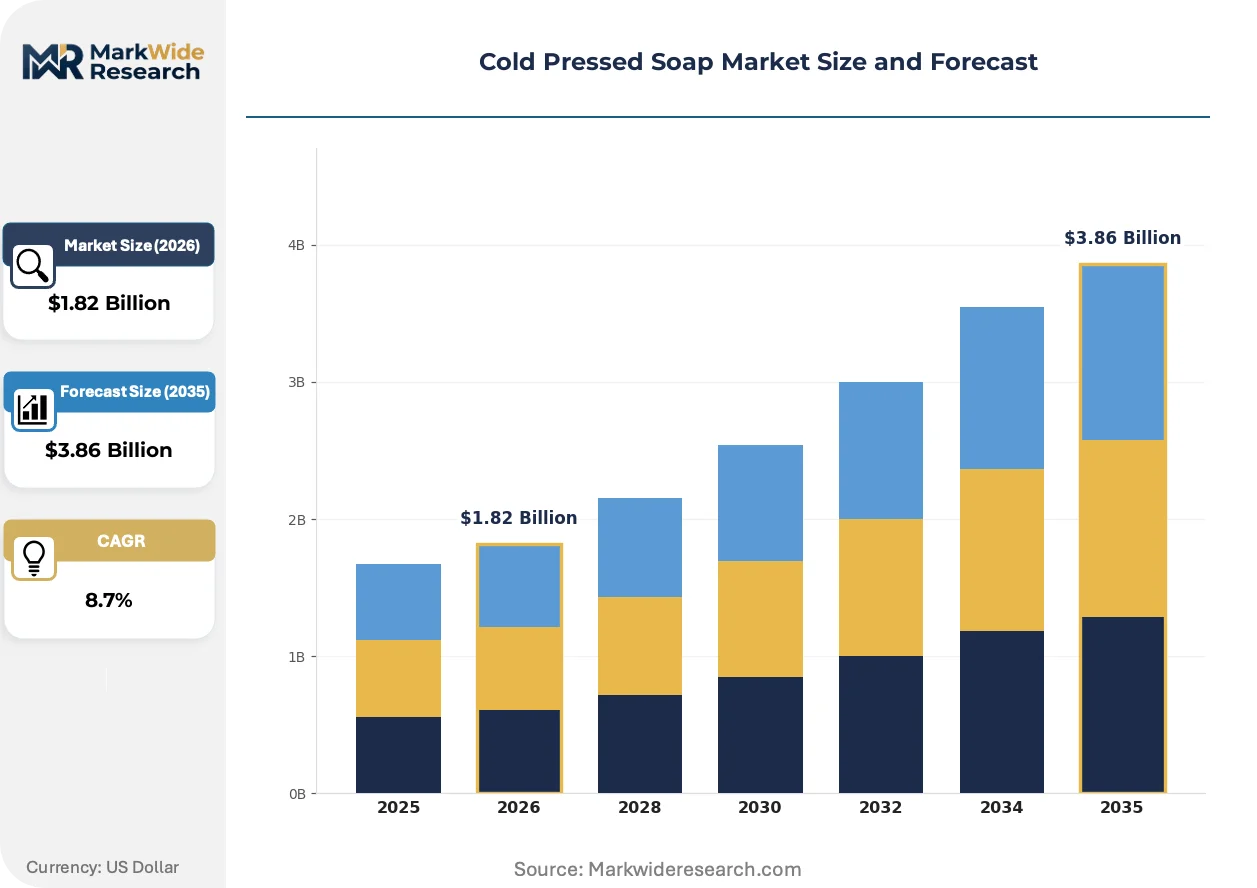
| Market Size in 2026 | $1.82 Billion |
| Market Size in 2035 | $3.86 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural, Organic, Scented, Exfoliating End User: Households, Salons, Spa Centers, Retailers Material: Vegetable Oils, Essential Oils, Additives, Colorants Distribution Channel: Online, Supermarkets, Health Stores, Artisan Markets |
| Companies Covered | Zhejiang Anji Green Daily Products Co., Ltd, Dove (Unilever), Poleview Biotech Co., Ltd, Dr. Squatch, Irish Spring (Colgate-Palmolive), Shenzhen Yefon Cosmetics Co., Ltd, Jiangsu SOHO Int'l Group – H&B Division, Chagrin Valley Soap & Salve, Guangzhou OEM Cosmetics Co., Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cold Pressed Soap Market Strategic Shifts
Algorithmic personalization and regulatory transparency requirements are simultaneously elevating ingredient traceability and compressing traditional discovery channels. Formulators must now embed compliance documentation into consumer-facing narratives.
Supercritical CO2 extraction for botanical infusions preserves heat-sensitive compounds without thermal degradation. Premium spa formulators in France are adopting this cold-compatible concentration method at pilot scale. The technology is rendering obsolete traditional heat-assisted maceration that degrades antioxidant profiles in final bar formulations.
ECHA REACH registration requirements for essential oil imports now mandate full supply chain disclosure down to harvest origin. This industrial consequence forces reformulation around pre-registered botanical sources or synthetic alternatives. Organic-certified producers with documented farm partnerships capture preferential European market access while uncertified competitors face import blockages.
Subscription-based replenishment models now dominate discovery for male-oriented grooming segments. Digital-native brands bypass wholesale margin stacking through direct fulfillment. This channel displacement concentrates customer lifetime value capture in algorithm-optimized acquisition funnels rather than retail shelf placement, with the United States and Australia showing the most pronounced behavioral adoption curves.
Cold Pressed Soap Market Segmentation
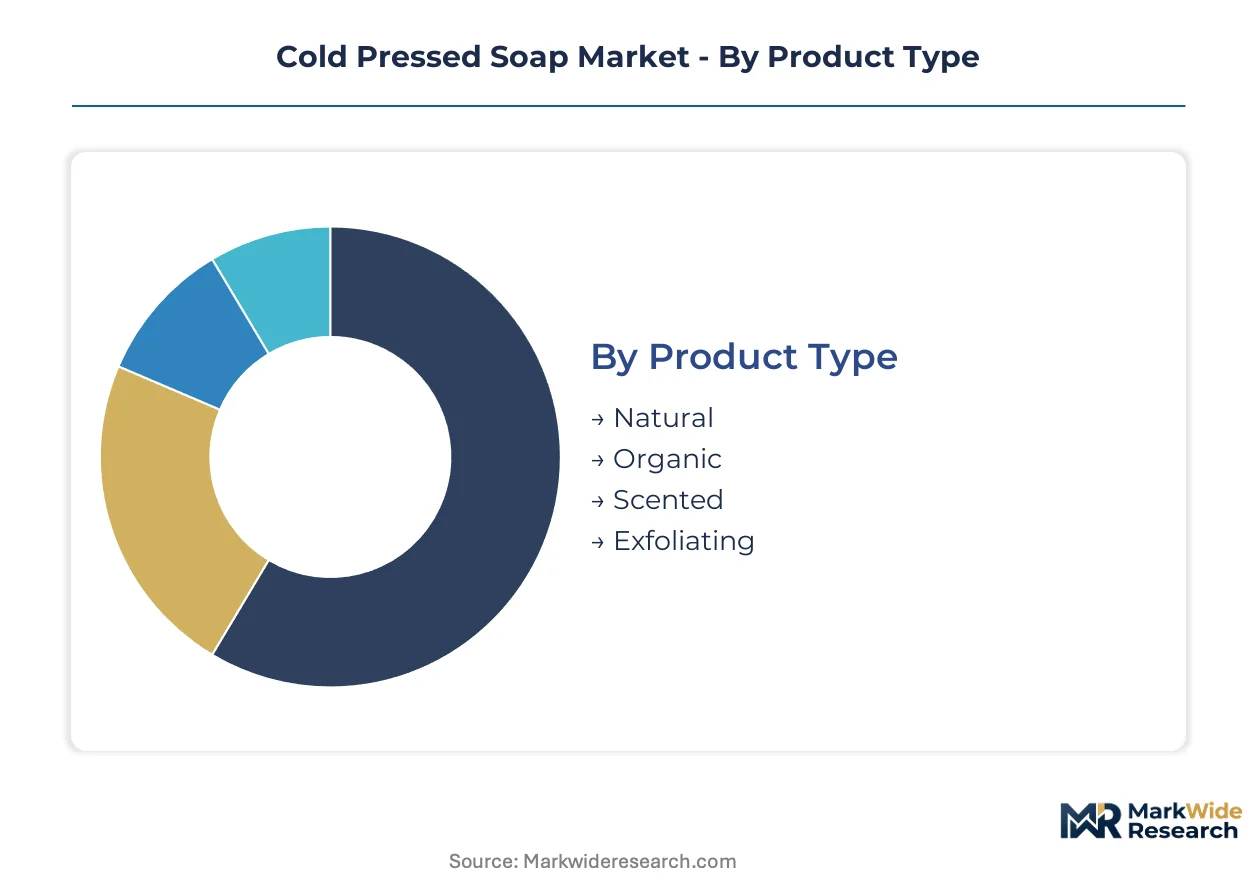
Cold pressed soap manufacturers configure production lines and certification investments around four distinct segmentation axes. Each axis carries different margin profiles, regulatory exposure, and channel access requirements that shape competitive positioning.
Product Type:
After-sales service intensity varies sharply across product tiers, with certified organic variants demanding traceability documentation and reformulation support that natural formulations rarely require.
- Natural:Formulations using plant-derived base oils without synthetic surfactants or petroleum derivatives. Household procurement in the United States and Australia concentrates here, driven by price accessibility and familiar ingredient transparency that reduces purchase friction.
- Organic:Certified formulations meeting third-party organic content standards with full supply chain documentation. Spa centers in Germany and France specify these for premium treatment menus, though certification audit costs compress margins for small-batch producers.
- Scented:Bars incorporating essential oil blends for aromatic profiles.
- Exfoliating:Textured variants with botanical or mineral abrasives.
By volume, Natural leads. By growth pace, Exfoliating is ahead.
End User:
Cost tier stratification separates institutional buyers willing to absorb certification premiums from mass-market households prioritizing unit economics.
- Households:Individual consumers purchasing for personal cleansing routines. Direct-to-consumer subscriptions in the United States capture this segment through algorithm-driven discovery, consolidating recurring revenue away from retail shelf competition.
- Salons:Professional beauty establishments sourcing treatment-grade formulations. Australian salon procurement is expanding most quickly, with Sydney and Melbourne operators seeking transparent ingredient sourcing for service differentiation.
- Spa Centers:Premium wellness facilities specifying certified organic cold pressed soaps for treatment integration.
- Retailers:Third-party distributors including health stores and specialty grocers.
Households dominate absolute volume. Spa centers command the steepest margin premiums.
Material:
Supply concentration for plant-derived inputs creates geographic dependency that shapes batch consistency and reformulation flexibility.
- Vegetable Oils:Base oils including olive, coconut, and shea butter that constitute the primary saponification substrate. REACH-registered supply chains from European farm partnerships now dominate German and French manufacturer procurement, locking out uncertified harvest sources.
- Essential Oils:Concentrated botanical extracts providing scent and therapeutic positioning. ECHA registration mandates for European importation are forcing reformulation around pre-registered sources or synthetic alternatives, consolidating access for documented supply chains.
- Additives:Functional ingredients including botanical extracts and conditioning agents.
- Colorants:Pigments derived from plant, mineral, or clay sources.
Vegetable oils anchor volume throughput. Essential oils face the tightest regulatory compression.
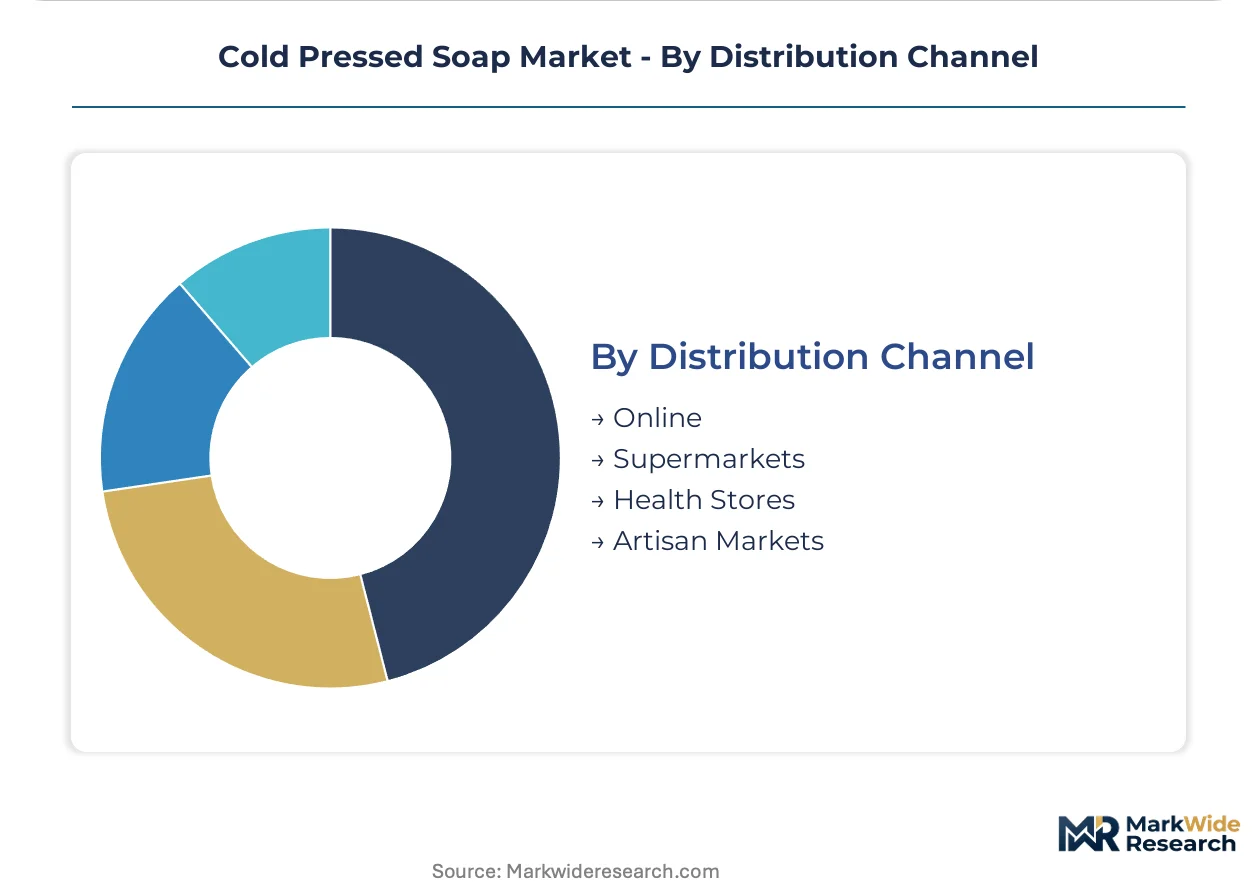
Distribution Channel:
Customer acquisition economics diverge between algorithm-optimized digital funnels and legacy retail shelf commitments with declining foot traffic.
- Online:Direct-to-consumer and marketplace platforms enabling subscription replenishment. Male-oriented grooming subscriptions in the United States concentrate here, with digital-native brands bypassing wholesale margin stacking through algorithm-optimized acquisition.
- Supermarkets:Mass-market retail placement requiring scale production and standardized bar specifications. Australian supermarket penetration remains underdeveloped for artisan positioning, creating expansion white space for transparent sourcing claims.
- Health Stores:Specialty retail channels historically dominant for natural product discovery.
- Artisan Markets:Direct producer-to-consumer venues including farmers markets and craft fairs.
Online channels are gaining share fastest. Health stores retain the highest customer acquisition cost for new brand entry.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Deep-water container terminals at Hamburg and Rotterdam anchor European supply chains for shea butter and olive oil imports that feed cold pressed soap manufacturing clusters across the continent.
United States
Direct-to-consumer subscription channels capture household procurement through algorithm-optimized acquisition funnels. FTC enforcement against unsubstantiated natural claims forces legal review of all marketing collateral before product launches. Artisan formulators in Brooklyn and Austin concentrate on transparent ingredient sourcing for premium positioning.
Germany
Specialty spa centers in Bavaria and Baden-Württemberg specify certified organic cold pressed formulations for treatment-menu integration. ECHA REACH registration requirements for essential oil imports consolidate shelf access for compliant producers with documented supply chains. Manufacturing clusters around Hamburg leverage port infrastructure for vegetable oil sourcing.
France
Premium wellness facilities in Provence-Alpes-Côte d'Azur anchor institutional demand for organic-certified bars. ANSM oversight of cosmetic ingredient safety shapes labeling requirements for natural positioning claims. Supercritical CO2 extraction pilots in Grasse preserve heat-sensitive botanical compounds for spa-grade formulations.
Australia
Sydney and Melbourne salon operators seek transparent ingredient sourcing for service differentiation in underpenetrated artisan segments. TGA guidelines on therapeutic claims restrict dermatological positioning language for cosmetic soap products. Direct-to-consumer channels show pronounced behavioral adoption curves for male-oriented grooming subscriptions.
China
OEM manufacturing scale in Guangzhou and Shenzhen anchors private-label production for Asia-Pacific distribution. SAMR cosmetic registration requirements mandate safety assessments for imported essential oil components. Yangtze River Delta formulators serve as contract manufacturers for brands seeking REACH-compliant export capacity.
Cold Pressed Soap Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in ingredient supply and private-label manufacturing. The vendor base stratifies across three tiers: multinational consumer goods conglomerates with mass-market shelf presence, mid-scale digital-native brands with subscription-optimized funnels, and artisan producers with certified organic positioning. Strategic archetypes include OEM scale players, direct-to-consumer lifestyle brands, and transparent-sourcing specialists. Competitive moves concentrate on algorithm-driven customer acquisition and cross-border certification harmonization.
Within the OEM manufacturing tier, Poleview Biotech Co., Ltd and Guangzhou OEM Cosmetics Co., Ltd exemplify scale-driven contract production capabilities. Zhejiang Anji Green Daily Products Co., Ltd anchors Chinese supply capacity for private-label export programs. Dr. Squatch occupies a position as the archetypal digital-native brand leveraging aggressive lifestyle marketing to consolidate male-oriented subscription segments.
| Leading Market Players |
|---|
| Zhejiang Anji Green Daily Products Co., Ltd |
| Dove (Unilever) |
| Poleview Biotech Co., Ltd |
| Dr. Squatch |
| Irish Spring (Colgate-Palmolive) |
| Shenzhen Yefon Cosmetics Co., Ltd |
| Jiangsu SOHO Int'l Group – H&B Division |
| Chagrin Valley Soap & Salve |
| Guangzhou OEM Cosmetics Co., Ltd |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta manufacturing clusters anchor contract production capacity for cold pressed soap exports, with Guangzhou and Shenzhen formulators translating scale economies into pricing leverage over artisan competitors in North American and European markets. REACH compliance costs and organic certification audits compress margins for small-batch producers while consolidating shelf access for documented supply chains.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates certified organic spa-grade formulations from natural household variants and private-label commodity bars. Price differentiation rests on certification grade and volume scale, with organic tiers absorbing audit costs that commodity producers avoid. Cost compression in the natural tier is intensifying because algorithm-driven discovery channels bypass wholesale margin stacking. Household procurement segments show highest price sensitivity, while German and French spa centers absorb premium positioning with minimal volume negotiation.
Supply Chain Analysis
Export-control regimes through ECHA REACH registration requirements for essential oil imports restrict uncertified harvest sources from European market entry. Geographic supply concentration centers on China for OEM manufacturing scale, Australia for underexploited artisan demand, and France for supercritical CO2 extraction pilots. Raw material dependencies draw from shea butter harvests, olive oil cooperatives, and pre-registered botanical essential oil sources. Single-source vulnerability runs through plant-derived colorant supply concentration tied to specific geographic harvests. Distribution runs through direct-to-consumer subscription channels that displace legacy health store foot traffic.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cold pressed soap markets face high-growth disruption as ECHA REACH transparency mandates and EPA FTC enforcement simultaneously elevate compliance burdens and consolidate access for documented supply chains. Algorithm-driven discovery channels are compressing traditional wholesale economics and rewarding digital-native positioning.
For Market Incumbents: Entrench certified organic supply chain documentation to defend European spa procurement relationships against reformulation-ready competitors. Prioritize backward integration into pre-registered essential oil sourcing to neutralize ECHA import blockages. Channel control through direct-to-consumer subscription infrastructure captures customer lifetime value as health store foot traffic declines. For New Entrants and Emerging Players: Establish a beachhead in Australian salon procurement channels where Sydney and Melbourne operators seek transparent ingredient sourcing for service differentiation. Target exfoliating variant white space in spa and salon treatment menus that commands premium positioning. Go-to-market through algorithm-optimized acquisition funnels bypasses retail shelf competition entirely. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors formulators with ISO 16128 harmonization capabilities that streamline cross-border certification and reduce duplicate testing costs. Long-term viability across the analysis window hinges on documented farm partnerships and REACH-registered supply chains. The signal to watch is California clean beauty timeline compression forcing reformulation cycles that outpace certification renewal schedules.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Channel Expansion | Algorithm-optimized acquisition funnels capture male-oriented grooming subscriptions in the United States and Australia. |
| Certified Organic Supply Chain Investment | Third-party audit documentation secures premium spa procurement in Germany and France against REACH-compliant competitors. |
| Supercritical CO2 Extraction Adoption | Cold-compatible concentration methods preserve antioxidant profiles for spa-grade formulations in Provence-Alpes-Côte d'Azur. |
| ISO 16128 Harmonization Program | Unified natural-content benchmarks reduce duplicate testing costs for multinational formulators across European and Asia-Pacific markets. |
| Private-Label OEM Scale Buildout | Guangzhou and Shenzhen contract manufacturers serve brands seeking REACH-compliant export capacity for European distribution. |
Study Parameters
A spread of perspectives from artisan formulators, spa procurement directors, OEM contract manufacturers, and regulatory affairs specialists converged on the working assumptions driving this analysis. Primary interviews with brand managers at digital-native subscription operators and category buyers at Australian salon distributors combined with secondary validation from ECHA registration databases, FDA cosmetic ingredient filings, and customs trade records. Bottom-up segmentation modeling and top-down market sizing triangulated volume and value estimates across the projection horizon.
Demand-supply-balance framing anchored the analytical approach throughout the forecast period. Segmentation dimensions modeled include product type tier, end-user procurement channel, material input category, and distribution channel structure. CAGRs were derived from growth rate convergence analysis across primary fieldwork and secondary trend validation. Industry-specific forecast inputs incorporated REACH registration timelines and algorithmic customer acquisition cost curves for subscription channels.
Sensitivities concentrate around ECHA essential oil import restriction enforcement intensity and California state-level chemical mandate acceleration. Forecasts reflect documented assumptions on certification cost trajectories and digital channel adoption curves. Material shifts in EU Green Deal chemical restriction timelines or FTC natural claims enforcement posture would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Sweden Cosmetics Products Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Cosmetics ODM Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Malaysia Skin Care Products Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
GCC Bath Soap Market
Cosmetics & Skincare
Russia Lip Care Products Market