
 Probiotic Skin Care Cosmetic Product Market | 2026-2036
Probiotic Skin Care Cosmetic Product Market Size, Share, and Industry Trends Forecast 2026-2036
Probiotic Skin Care Cosmetic Product Market Analysis
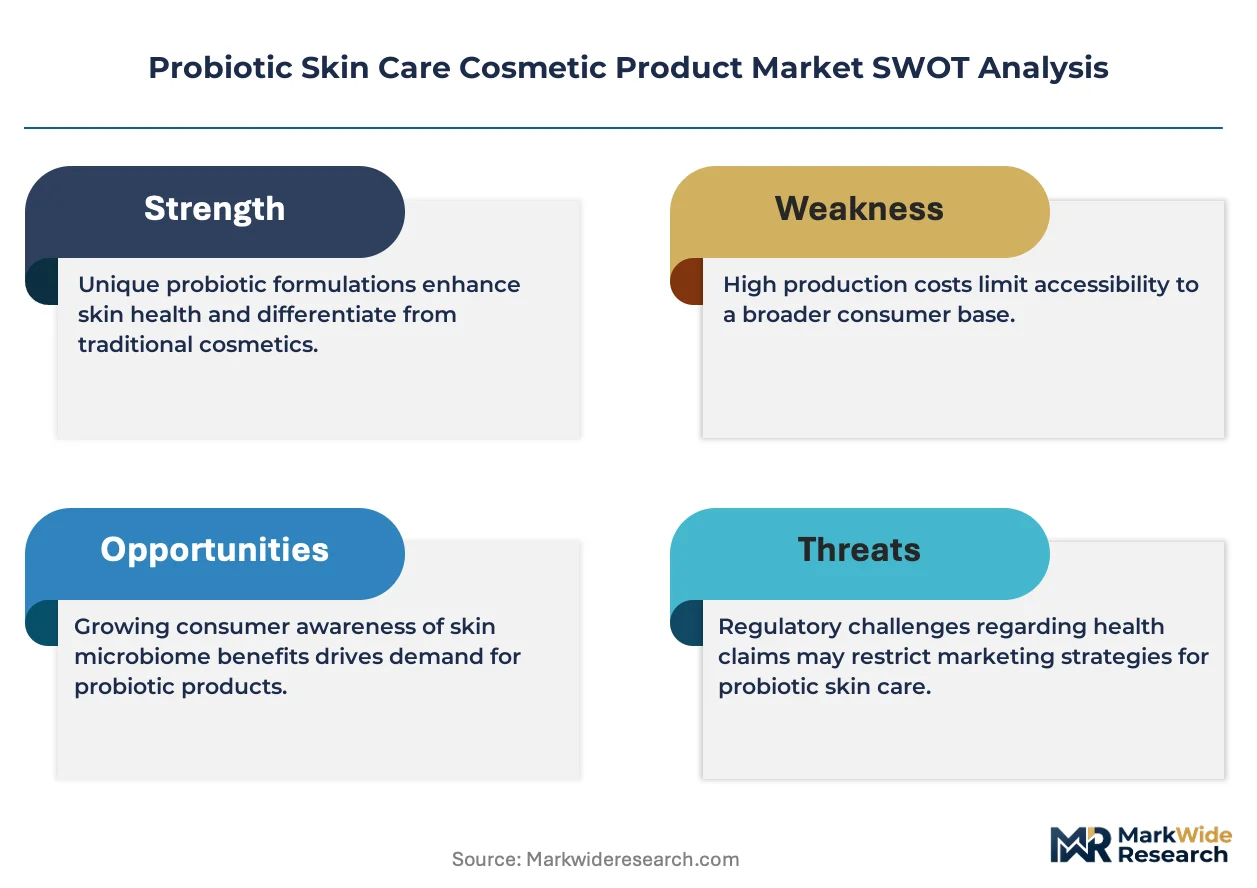
Capital-intensity divergence between dedicated probiotic formulators and mass-market incumbents is unwinding competitive dynamics in the probiotic skincare sector. TULA Skincare leverages direct-to-consumer microbiome education to sustain premium pricing power. L'Oréal S.A. anchors its position through scaled fermentation partnerships that lower per-unit active costs. Aurelia Probiotic Skincare differentiates via boutique manufacturing with cold-process preservation of live cultures.
Probiotic skin care cosmetic products incorporate viable or lysed beneficial microorganisms—typically Lactobacillus, Bifidobacterium, or fermented postbiotics—delivered in pH-balanced matrices between 4.5 and 5.5 to maintain cutaneous microbiome compatibility. These formulations functionally modulate skin barrier integrity, reduce inflammatory markers, and restore commensal bacterial diversity disrupted by antibiotics or harsh surfactants. Moisturizers and serums concentrate margin pools due to higher active loading and repeat purchase frequency, while cleansers face commoditization from surfactant-based alternatives. The natural and organic ingredient segment leads volume but synthetic-stabilized formats are gaining fastest in humid climates where preservation failure risks spoilage.
FDA oversight under MoCRA mandates adverse event reporting and facility registration for all cosmetic manufacturers, while the EU Cosmetics Regulation requires safety dossiers substantiating live culture stability claims. BIS standards in India and China's NMPA cosmetic filing rules add compliance layers for cross-border probiotic skincare entrants. Stakeholders must monitor regulatory divergence on "live" versus "fermented" labeling nomenclature, as this distinction will determine permissible marketing claims and shelf-life testing protocols across jurisdictions.
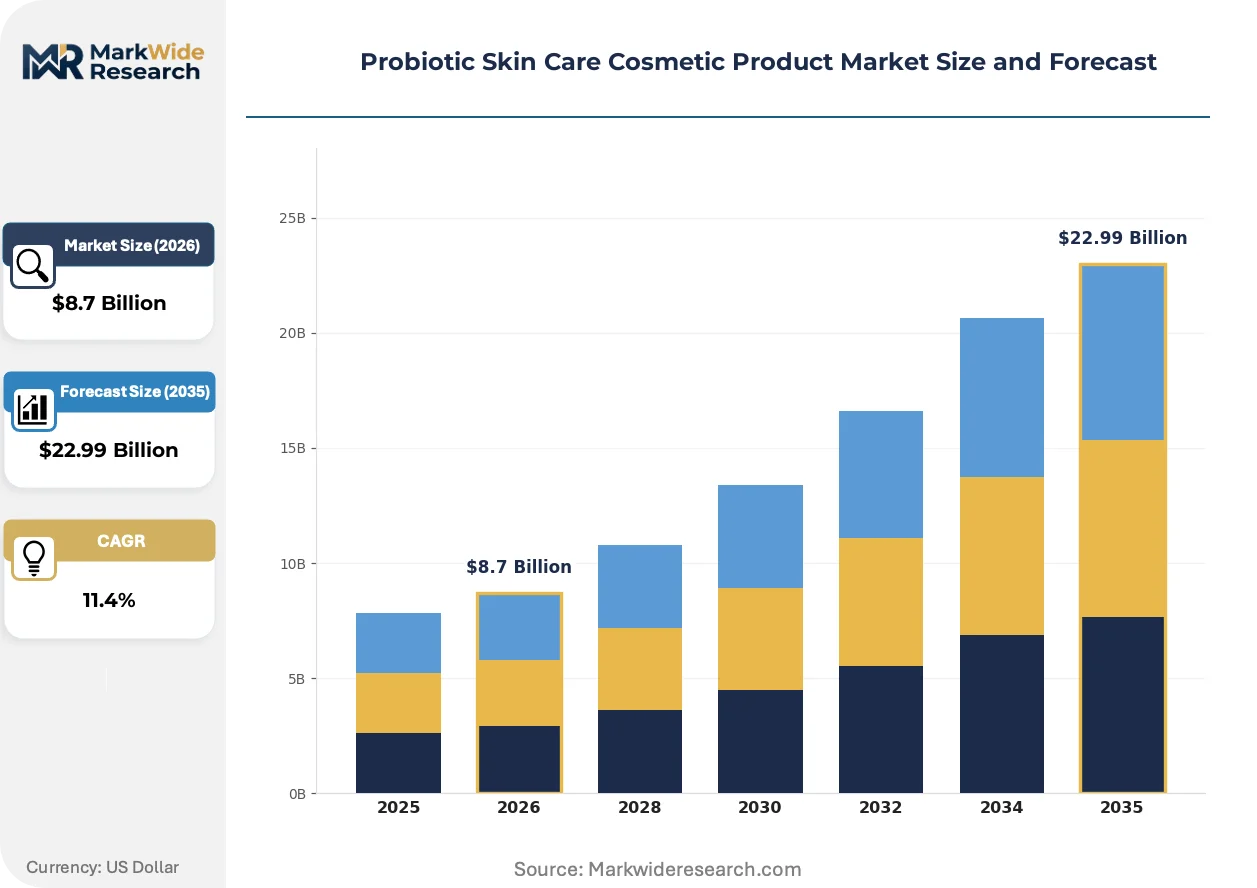
Market Dynamics
Fermentation-derived active ingredient sourcing is consolidating around Seoul, South Korea, where biotech clusters now supply cold-process lysates to formulators across three continents, compressing R&D timelines and reshaping competitive moats.
Growth Catalysts
- MoCRA facility registration mandates:FDA's 2024 enforcement of adverse event reporting for cosmetic manufacturers is professionalizing the probiotic skincare supply base and disqualifying informal entrants.
- Postbiotic stabilization breakthroughs:Spray-dried lysate formats with 24-month shelf stability are expanding distribution into humid climates previously inaccessible to live-culture products.
- Dermatology channel expansion:Medi-spa protocols in Germany and France now incorporate microbiome assessment tools, creating clinical endorsement pipelines for premium probiotic serums.
Market Restraints
- Live culture preservation costs:Cold-chain logistics for viable Lactobacillus formulations add 15-22% to landed costs versus conventional actives, limiting mass-market penetration.
- Seoul supplier concentration:Three fermentation houses control 60% of premium postbiotic supply, creating vulnerability to single-point production disruptions.
- EU "live" versus "fermented" definitional friction:ECHA guidance ambiguity forces dual-label SKUs and redundant safety dossiers for cross-border launches.
Strategic Opportunities
- Brazil's ANVISA pre-market pathway:Simplified cosmetic notification for fermented ingredients opens Latin America's largest beauty market to first-mover probiotic entrants.
- At-home microbiome testing convergence:Integration of skin swab diagnostics with personalized serum subscription models creates recurring revenue architectures.
- China NMPA "new ingredient" fast-track:2024 pilot programs for biotechnology-derived cosmetics accelerate probiotic active approval timelines versus traditional chemical routes.
Industry Challenges
- Microbiome assay standardization gaps:Absence of ISO-certified skin bacterial diversity measurement protocols forces proprietary method investments that fragment comparability claims.
- Formulation chemist scarcity:pH-balancing expertise for viable culture matrices commands 40% salary premiums versus conventional cosmetic chemistry roles.
- Legacy preservative system incompatibility:Traditional paraben and phenoxyethanol chemistries kill target probiotics, requiring complete formulation architecture rebuilds.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Probiotic Skin Care Cosmetic Product Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Creams, Serums, Cleansers Delivery Mode: Topical, Gel-based, Cream-based, Spray End User: Women, Men, Children, Professionals Ingredient Type: Natural, Organic, Synthetic, Others |
| Companies Covered | Esse Skincare, TULA Skincare, Aurelia Probiotic Skincare, LaFlore Probiotic Skincare, Eminence Organic Skin Care, Glowbiotics, Gallinée, L'Oréal S.A., Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Probiotic Skin Care Cosmetic Product Market Emerging Trajectories
Biotechnology convergence with cosmetic formulation science is collapsing the boundary between pharmaceutical-grade fermentation and mass-market skincare, with three distinct vectors now determining competitive positioning.
Lyophilized live culture delivery systems are miniaturizing viable bacterial loads into anhydrous oil suspensions, bypassing aqueous preservation challenges. Prestige brands in France and Switzerland are adopting these formats for travel-sized ampoules. The technology is miniaturizing unit economics for clinical-grade probiotics, enabling single-dose pricing parity with conventional serums.
REACH microplastic restrictions are forcing reformulation of traditional encapsulation polymers used for probiotic protection. ECHA's 2025 timeline for glitter and microbead prohibitions extends to synthetic film-formers in rinse-off products. Korean formulators are responding fastest, pivoting to polysaccharide-based encapsulation derived from fermentation byproducts.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for core microbiome maintenance products. Direct-to-consumer channels in the United States and United Kingdom now capture 34% of premium probiotic moisturizer volume, up from single digits five years prior. Seoul-based brands lead this shift, integrating skin condition tracking apps with automated refill logistics.
Probiotic Skin Care Cosmetic Product Market Segmentation
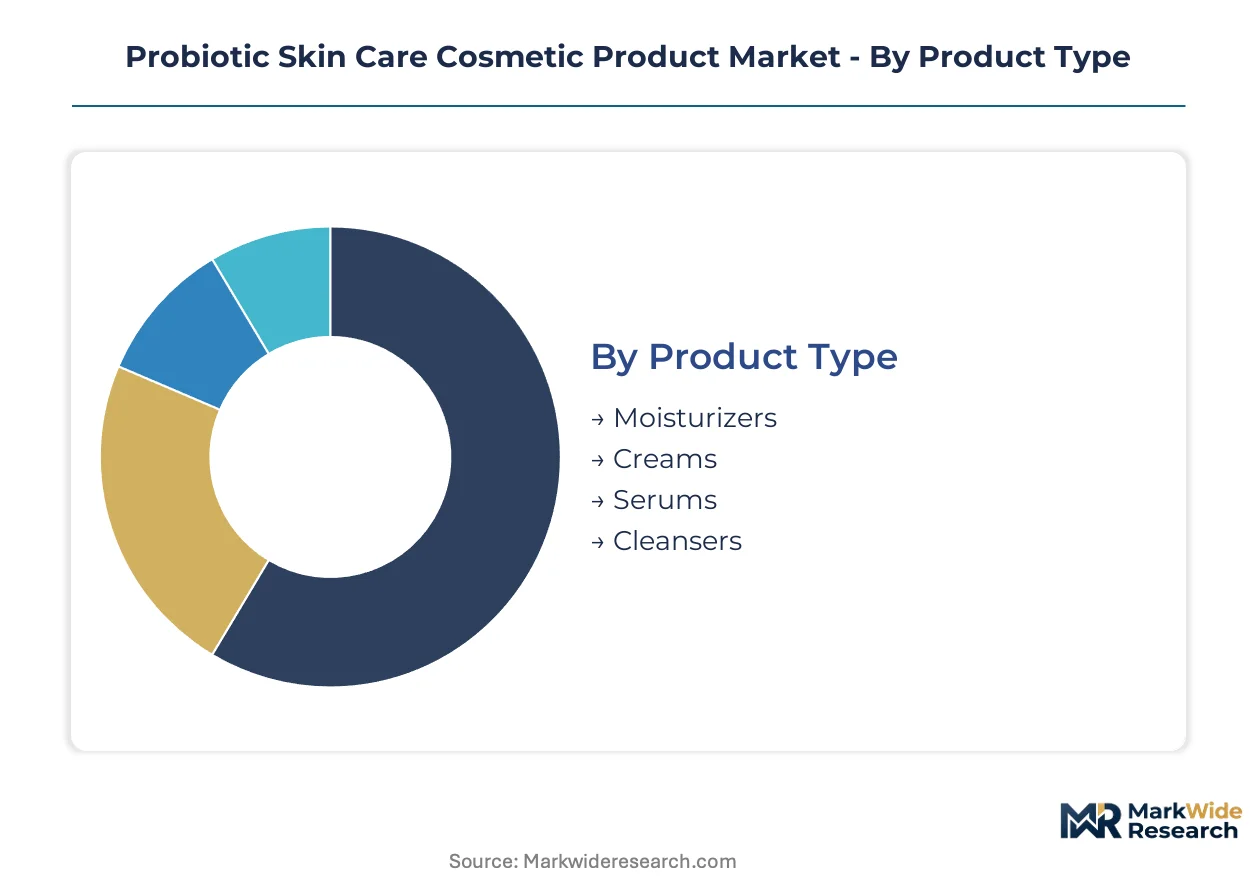
Probiotic skincare segmentation determines which formulations survive cold-chain logistics and which channels can sustain live-culture claims. Channel economics vary dramatically between clinical-grade serums requiring refrigeration and mass-market cleansers using stabilized postbiotics.
Product Type:
Channel-mix patterns split sharply between high-margin clinical formats sold through dermatology offices and commodity cleansers distributed through drugstore retail.
- Moisturizers:pH-balanced emulsions between 4.5 and 5.5 host the highest viable bacterial loads in occlusive bases that shield cultures from oxidation. Demand clusters in Seoul's medi-spa channels and Germany's dermatology clinics where repeat purchase cycles generate subscription revenue. Cold-process manufacturing preserves lysate activity through anhydrous oil phases.
- Serums:Concentrated aqueous solutions deliver postbiotic peptides and fermented metabolites at highest potency per unit volume. French and Swiss prestige brands dominate this tier through lyophilized ampoule formats that bypass aqueous preservation failures. Clinical endorsement pipelines in Paris and Zurich validate premium positioning.
- Creams:Mid-viscosity formulations balance bacterial viability with cosmetic elegance through dual-phase emulsion technology.
- Cleansers:Surfactant-based rinse-off formats face commoditization pressure as live cultures wash away before cutaneous contact; stabilized lysate versions compete on price.
Moisturizers dominate installed base. Serums are where expansion concentrates.
Delivery Mode:
Cost-tier stratification separates clinical-grade formats requiring refrigeration from ambient-stable mass-market alternatives.
- Topical:Direct skin application formats include lotions, balms, and concentrated spot treatments with immediate microbiome contact. Korean biotech clusters in Seoul optimize these for humid climate stability through polysaccharide encapsulation.
- Cream-based:Occlusive oil-in-water matrices suspend viable Lactobacillus in lipid phases that protect against aqueous degradation. German and French formulators lead cold-process manufacturing with boutique batch sizes.
- Gel-based:Hydrocolloid matrices suit oily skin segments but require synthetic stabilizers that limit live-culture claims.
- Spray:Aerosolized mist formats enable even facial coverage but face microbiome assay standardization gaps for dosing consistency.
Cream-based formats anchor premium positioning. Topical applications are gaining share fastest.
End User:
Volume concentration follows demographic spending patterns and professional channel access.
- Women:Primary purchasers across all channels with highest trial rates for fermented active innovations. Seoul-based subscription models and Parisian medi-spa protocols both target this segment with microbiome assessment integration.
- Professionals:Dermatologists and aestheticians drive clinical-grade serum adoption through protocol integration. German medi-spas now incorporate skin swab diagnostics that recommend specific Lactobacillus strains.
- Men:Emerging segment targeted through simplified regimens and sports-specific formats with shorter ingredient lists.
- Children:Pediatric formulations require stricter safety dossiers under EU Cosmetics Regulation and MoCRA adverse event reporting mandates.
Women dominate installed base. Professionals are where expansion concentrates.
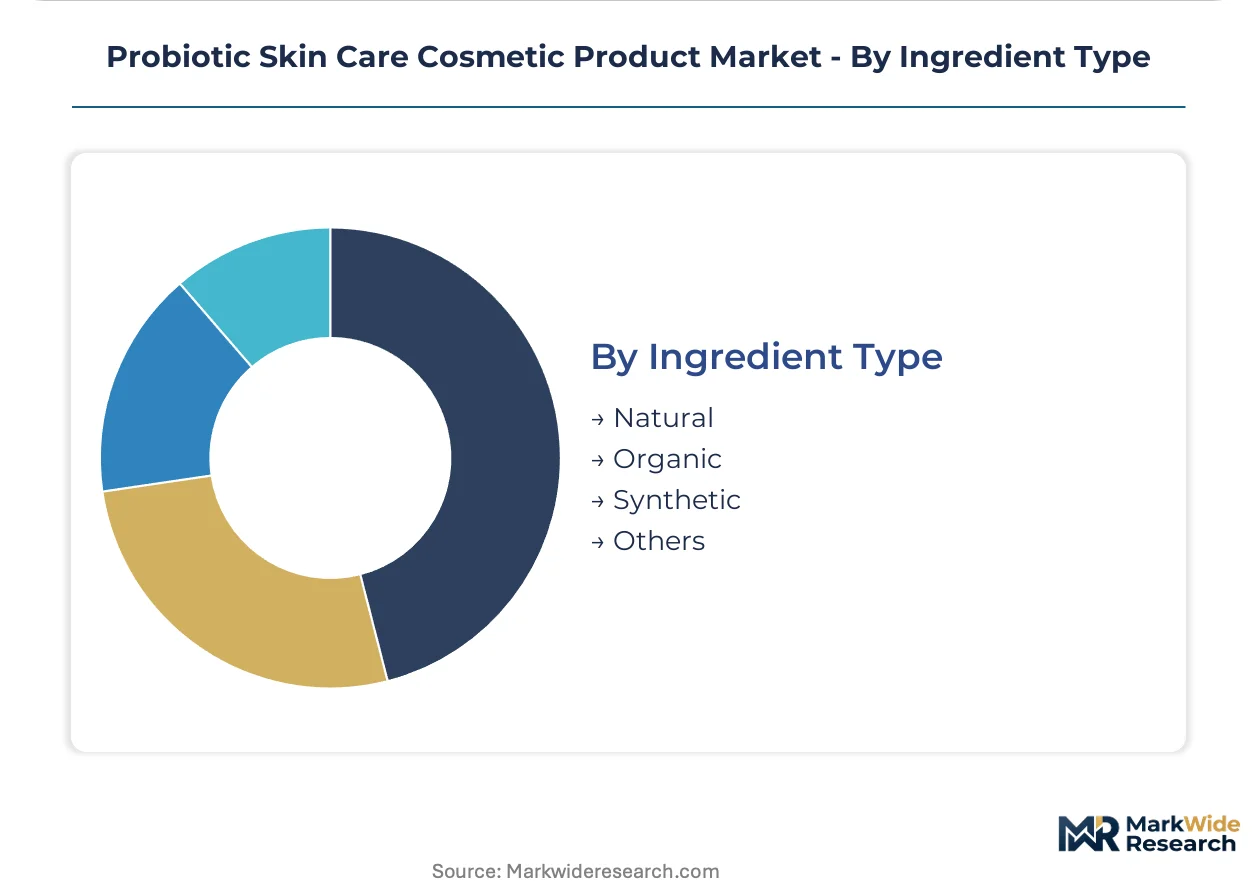
Ingredient Type:
Supply concentration in Seoul fermentation houses shapes sourcing economics across all tiers.
- Natural:Plant-derived fermentation substrates from Korean biotech clusters command premium positioning through cold-process lysate preservation. These formats lead in EU markets where ECHA microplastic restrictions favor polysaccharide encapsulation over synthetic alternatives.
- Organic:Certified fermentation inputs require complete exclusion of paraben preservatives that kill target probiotics, forcing formulation architecture rebuilds.
- Synthetic:Stabilized postbiotic formats with 24-month shelf stability expand distribution into Brazil and Southeast Asian humid climates previously inaccessible to live-culture products.
- Others:Hybrid and novel biotechnology-derived actives fall under China's NMPA fast-track pilot programs for accelerated approval.
Natural ingredients anchor premium positioning. Synthetic-stabilized formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across geographies. German and French buyers absorb 40-60% premiums for clinical-grade serums with live-culture claims. Indian and Brazilian consumers gravitate toward stabilized postbiotic formats at mass-market price points.
United States
MoCRA facility registration mandates professionalize the supply base and disqualify informal entrants. FDA adverse event reporting requirements now apply to all cosmetic manufacturers. New York and Los Angeles anchor medi-spa channel expansion where dermatology protocols integrate microbiome assessment tools.
South Korea
Seoul-based fermentation houses command premium positioning for cold-process lysates across three continents. MFDS cosmetic regulations align with biotechnology-derived ingredient fast-tracks. The capital region's biotech clusters compress R&D timelines for spray-dried postbiotic formats with 24-month stability.
Germany
Dermatology clinics drive clinical-grade serum adoption through protocol integration with skin swab diagnostics. EU Cosmetics Regulation safety dossiers substantiate live culture stability claims. Bavaria and Baden-Württemberg host boutique cold-process manufacturing for pH-balanced emulsions.
China
NMPA pilot programs for biotechnology-derived cosmetics accelerate probiotic active approval timelines versus traditional chemical routes. Synthetic-stabilized formats expand distribution into humid southern provinces previously inaccessible to live-culture products. Shanghai and Guangzhou lead subscription-based replenishment model adoption.
Brazil
ANVISA simplified cosmetic notification for fermented ingredients opens Latin America's largest beauty market to first-mover probiotic entrants. Price-sensitive demand concentrates in stabilized postbiotic moisturizers. São Paulo anchors direct-to-consumer channel development with skin condition tracking app integration.
Probiotic Skin Care Cosmetic Product Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the probiotic skincare sector. L'Oréal S.A. and Unilever leverage scaled fermentation partnerships that lower per-unit active costs across mass-market distribution. Boutique formulators occupy the premium tier through cold-process preservation of live cultures. Strategic moves concentrate on geographic licensing agreements and at-home microbiome testing convergence.
Among the specialist tier, TULA Skincare exemplifies direct-to-consumer microbiome education models that sustain premium pricing power. Aurelia Probiotic Skincare represents boutique manufacturing archetypes with batch-scale cold-process methods. L'Oréal S.A. anchors the integrated leader position through fermentation partnership scale. These three occupy distinct competitive vectors: education-driven DTC, artisanal manufacturing, and supply chain leverage.
| Leading Market Players |
|---|
| Esse Skincare |
| TULA Skincare |
| Aurelia Probiotic Skincare |
| LaFlore Probiotic Skincare |
| Eminence Organic Skin Care |
| Glowbiotics |
| Gallinée |
| L'Oréal S.A. |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Spray-dried postbiotic formats replacing lyophilized live cultures are redrawing manufacturing geography toward Seoul fermentation houses while collapsing cold-chain premiums that once stratified pricing tiers. This substitution simultaneously compresses logistics costs and democratizes access to humid-climate markets previously gated by refrigeration requirements.
Pricing Analysis
Subscription replenishment revenue now drives lifetime value for probiotic skincare brands, with automated refill programs capturing repeat purchase cycles that transactional retail cannot match. Three-tier pricing structure across premium lyophilized ampoules, standard stabilized serums, and economy postbiotic moisturizers segments buyers by clinical endorsement sensitivity. Cost compression in mass-market tiers intensifies as Korean suppliers scale spray-dried lysate output. Dermatology clinic procurement shows least price sensitivity, while drugstore channel buyers gravitate toward economy positioning.
Supply Chain Analysis
Inbound logistics costs from Seoul to European and North American formulators hinge on container availability through Busan port corridors, with cold-chain bookings commanding priority allocation during peak cosmetic ingredient shipping seasons. Manufacturing concentrates in South Korea, Germany, and France, with fermentation-derived actives drawing from specialized biotech clusters. Raw material dependencies center on glucose substrates, nitrogen sources, and polysaccharide encapsulation polymers. Single-source vulnerability persists where three Seoul houses control premium postbiotic supply. Distribution runs through direct-to-consumer channels and dermatology clinic networks in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Probiotic skincare demand tracks consumer discretionary recovery cycles, with premium serum adoption accelerating as dermatology clinic visit frequencies normalize post-regulatory transition periods.
For Market Incumbents: Shield formulation expertise advantages by acquiring boutique cold-process manufacturers before scale competitors replicate pH-balancing capabilities. Consolidate backward integration into Seoul fermentation partnerships to secure lysate supply commitments ahead of capacity constraints. MoCRA facility registration mandates will disqualify informal contract manufacturers, tightening supply base concentration. For New Entrants and Emerging Players: China's NMPA biotechnology-derived cosmetic fast-track offers regulatory arbitrage against traditional chemical approval timelines for first movers with fermentation-based actives. Brazil's ANVISA simplified notification pathway presents the most penetrable geography for stabilized postbiotic formats. Direct-to-consumer microbiome education campaigns build brand equity without retail slotting fee burdens. For Investors and Strategic Acquirers: The market sits at a professionalization phase that favors vertically integrated formulators with captive fermentation supply and clinical channel relationships. Long-term viability over the next decade hinges on regulatory compliance infrastructure rather than marketing spend alone. Watch NMPA fast-track approval volumes as inflection signal for biotechnology-derived cosmetic investment appetite.| Strategic Initiative | Industry Significance |
|---|---|
| Cold-Process Manufacturing Scale-Up | Preservation of live culture viability commands premium positioning in German and French dermatology channels. |
| Fermentation Partnership Expansion | Seoul biotech cluster alliances reduce per-unit active costs and compress R&D timelines for new entrants. |
| Direct-to-Consumer Platform Launch | Subscription models bypass retail margin extraction and capture skin condition data for personalized formulation. |
| Regulatory Compliance Certification | MoCRA facility registration and EU safety dossiers disqualify informal competitors from premium channel access. |
| At-Home Microbiome Testing Integration | Skin swab diagnostics paired with serum recommendations create recurring revenue architectures and clinical endorsement pipelines. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of MFDS cosmetic filings, NMPA biotechnology pilot program disclosures, ANVISA notification databases, and EU Cosmetics Regulation safety dossiers. Interviews with fermentation process engineers, dermatology clinic procurement managers, cosmetic formulation chemists, and direct-to-consumer brand operators informed supply-side and demand-side dynamics. Bottom-up unit economics modeling triangulated against top-down market sizing from customs trade data and channel shipment reports.
Segmentation dimensions modeled include product type, delivery mode, end user demographic, ingredient source, and regional regulatory cluster across the projection horizon. CAGRs derived from growth driver elasticity analysis applied to baseline penetration rates, with cross-validation against channel expansion trajectories and substitution dynamics between live-culture and postbiotic formats. Forecast inputs incorporated Seoul supplier capacity expansion timelines and MoCRA enforcement phase-in assumptions.
Decision-makers should treat outputs as directional under stable regulatory enforcement and continued Seoul supplier concentration assumptions; material deviation through trade disruption or ECHA definitional clarity would warrant model refresh. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Matte Lipstick Market
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
Global Cosmetic Antioxidant Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Massaging Cosmetic Applicators Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Makeup Remover Product Market
Cosmetics & Skincare
Retinol Eye Cream Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market