
 Tea Based Face Masks Market | 2026-2036
Tea Based Face Masks Market Size, Share, and Industry Trends Forecast 2026-2036
Tea Based Face Masks Market Analytics
Aftermarket service revenue from spa-grade application tutorials and personalized skin assessment tools is rewriting how brands capture lifetime value. Innisfree Corporation leverages its Jeju Island green tea supply chain to dominate premium sheet mask positioning. Amorepacific Corporation anchors its portfolio through fermented black tea biotechnology, while The Body Shop competes on ethical sourcing credentials across multi-pack sets.
Tea based face masks constitute topical skincare treatments infused with Camellia sinensis-derived polyphenols, typically manufactured through cold-brew extraction or fermentation processes that preserve epigallocatechin gallate activity for antioxidant delivery. Sheet masks lead volume due to convenience-driven casual users, while clay masks capture margin pools among organic buyers seeking detoxification claims. Matcha-based formulations represent the fastest-growing ingredient segment as spa professionals adopt ceremonial-grade powder standards for premium positioning.
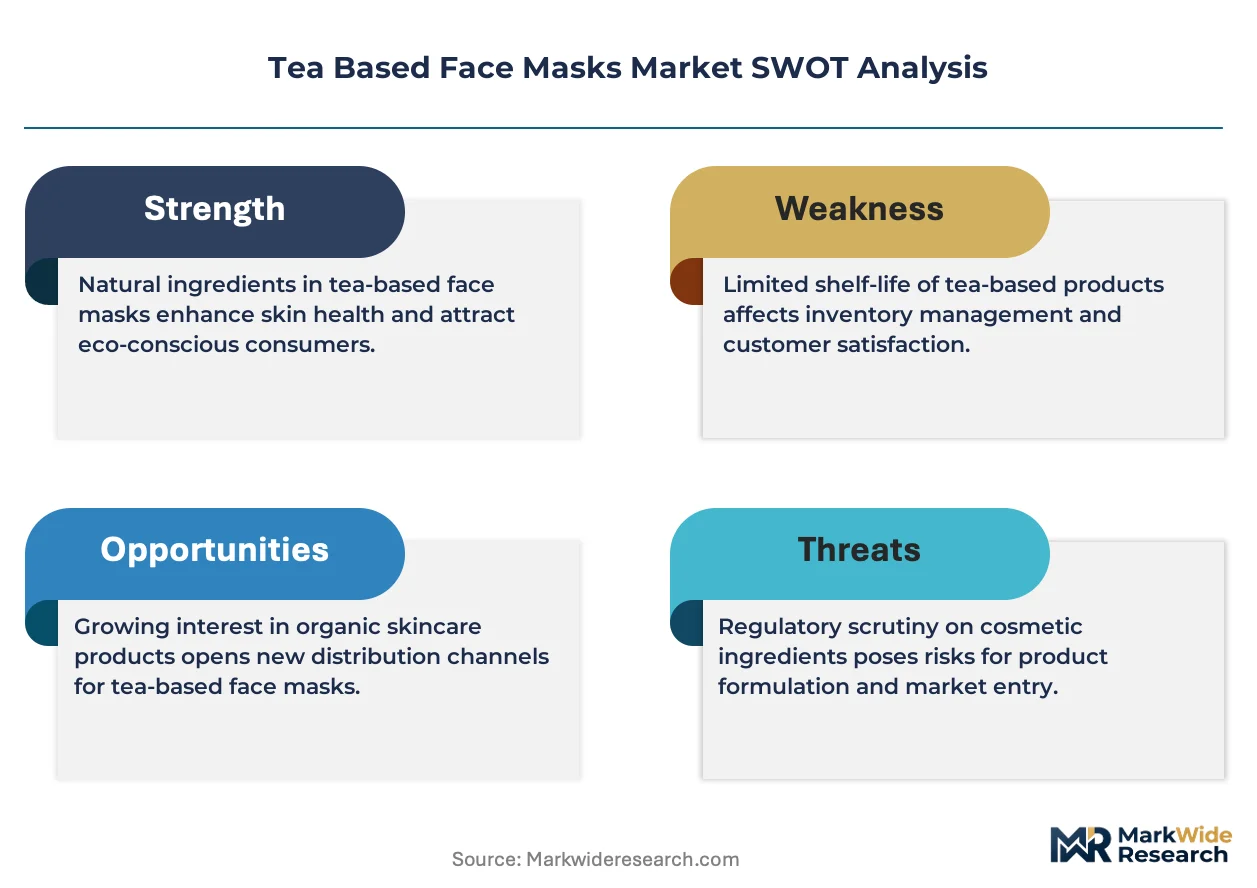
REACH governs chemical safety disclosures for European imports, while FDA cosmetic labeling rules mandate ingredient transparency for US distribution. ECHA substance restrictions on certain preservatives force reformulation cycles that favor natural tea-derived antimicrobials. Stakeholders must monitor evolving greenwashing enforcement across multiple jurisdictions as biodegradability claims face intensified scrutiny.
Market Dynamics
Fermentation biotechnology is compressing production timelines for epigallocatechin gallate preservation while REACH compliance and FDA labeling rules force simultaneous reformulation investments across export portfolios.
Growth Catalysts
- Clean beauty mandates:ECHA substance restrictions on synthetic preservatives accelerate natural tea-derived antimicrobial adoption in European formulations.
- Spa channel expansion:Ceremonial-grade matcha protocols adopted by South Korean aesthetic clinics create premium service tier demand.
- Biodegradability standards:EU Green Deal packaging requirements favor sheet mask substrates manufactured from cellulose derived from tea processing waste streams.
Market Restraints
- Input cost volatility:Camellia sinensis leaf prices fluctuate with climate patterns in Jeju Island and Uji cultivation zones.
- Supply concentration risk:Fermented black tea biotechnology patents cluster within South Korean research institutes.
- Substitution threat:Centella asiatica and mugwort extracts capture similar antioxidant positioning at lower formulation costs.
Strategic Opportunities
- Underpenetrated geography:Brazil's ANVISA cosmetic registration pathway remains underutilized by tea-mask exporters despite growing aesthetic medicine investment.
- Regulatory tailwind:India's PLI scheme for active pharmaceutical ingredients extends to botanical extract manufacturing infrastructure.
- Distribution innovation:Personalized skin assessment algorithms embedded in direct-to-consumer platforms enable subscription-based mask curation.
Industry Challenges
- Formulation talent scarcity:Cosmetic chemists with dual expertise in polyphenol stability and sheet mask substrate engineering command premium compensation.
- Certification timeline compression:MFDS microbial safety testing protocols for fermented extracts extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tea Based Face Masks Market |
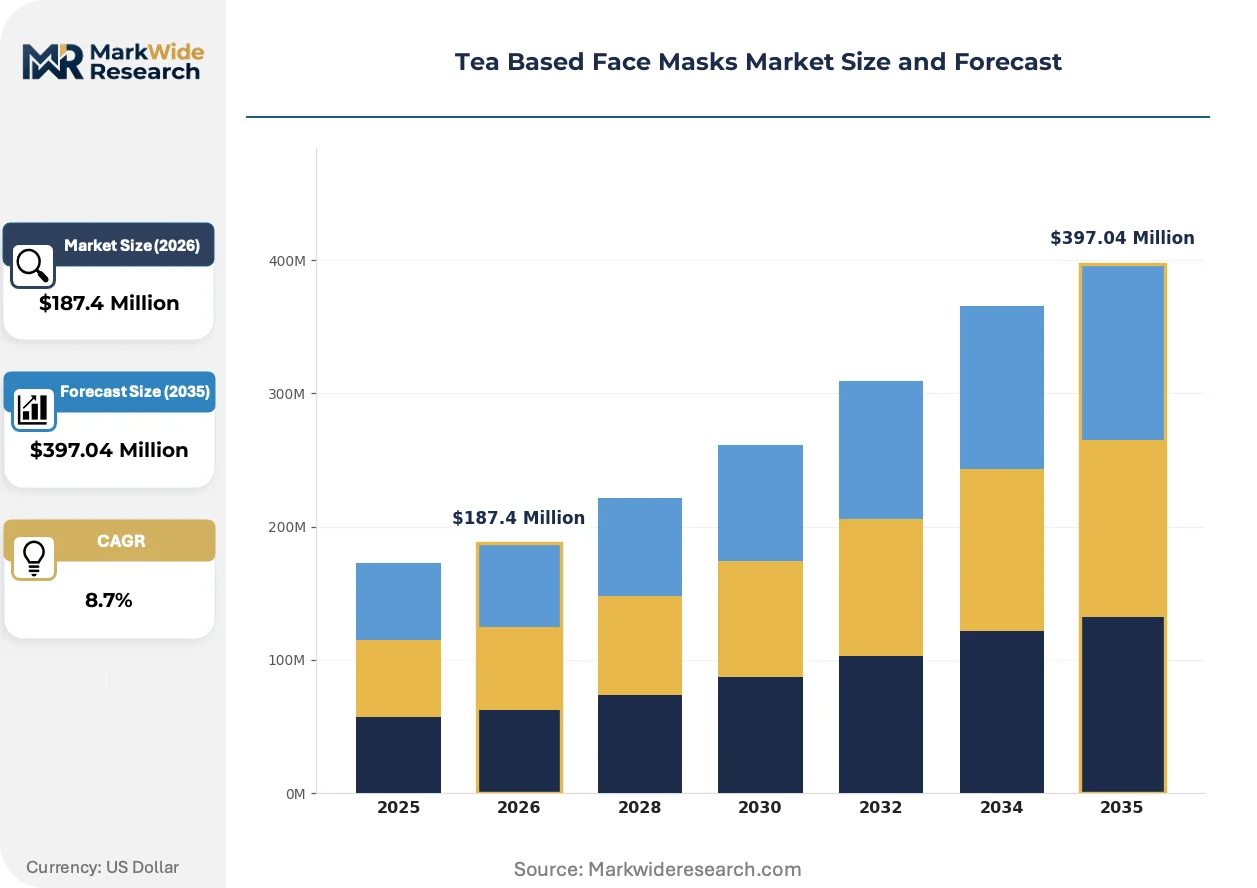
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sheet Masks, Peel-Off Masks, Cream Masks, Clay Masks Main Ingredient: Green Tea, Black Tea, Herbal Blends, Matcha Consumer Type: Skincare Enthusiasts, Casual Users, Spa Professionals, Organic Buyers Packaging Type: Single Use, Multi-Pack Sets, Tubes, Jars |
| Companies Covered | Lotus Herbals, Estée Lauder, Lakmé, L'Oréal Paris, Avon Products, The Body Shop, Innisfree Corporation, Amorepacific Corporation, Lu Ming Tang, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tea Based Face Masks Market Evolving Landscape
Cold-brew extraction protocols and fermentation bioreactors are rewriting manufacturing economics while regulatory transparency mandates reshape competitive disclosure practices across export markets.
Bioreactor-based fermentation is collapsing the yield gap between artisanal tea processing and industrial-scale epigallocatechin gallate concentration. South Korean contract manufacturers deploy 10,000-liter vessels for black tea fermentations that previously required six-month traditional curing. This compression enables mid-tier brands to access antioxidant potencies previously reserved for luxury positioning.
REACH chemical safety disclosures now mandate full supply chain transparency for preservative systems used in rinse-off cosmetics. European importers face ECHA substance restriction deadlines that eliminate paraben alternatives without documented biodegradability. Formulators pivot toward tea polyphenol complexes with inherent antimicrobial properties to bypass disclosure complexity.
Subscription-based personalization algorithms now displace conventional retail assortment strategies for recurring mask purchases. Direct-to-consumer platforms in South Korea deploy computer vision skin analysis to curate monthly sheet mask selections. This behavioral shift concentrates lifetime value capture among brands with captive data infrastructure rather than traditional retail distribution.
Tea Based Face Masks Market Segmentation
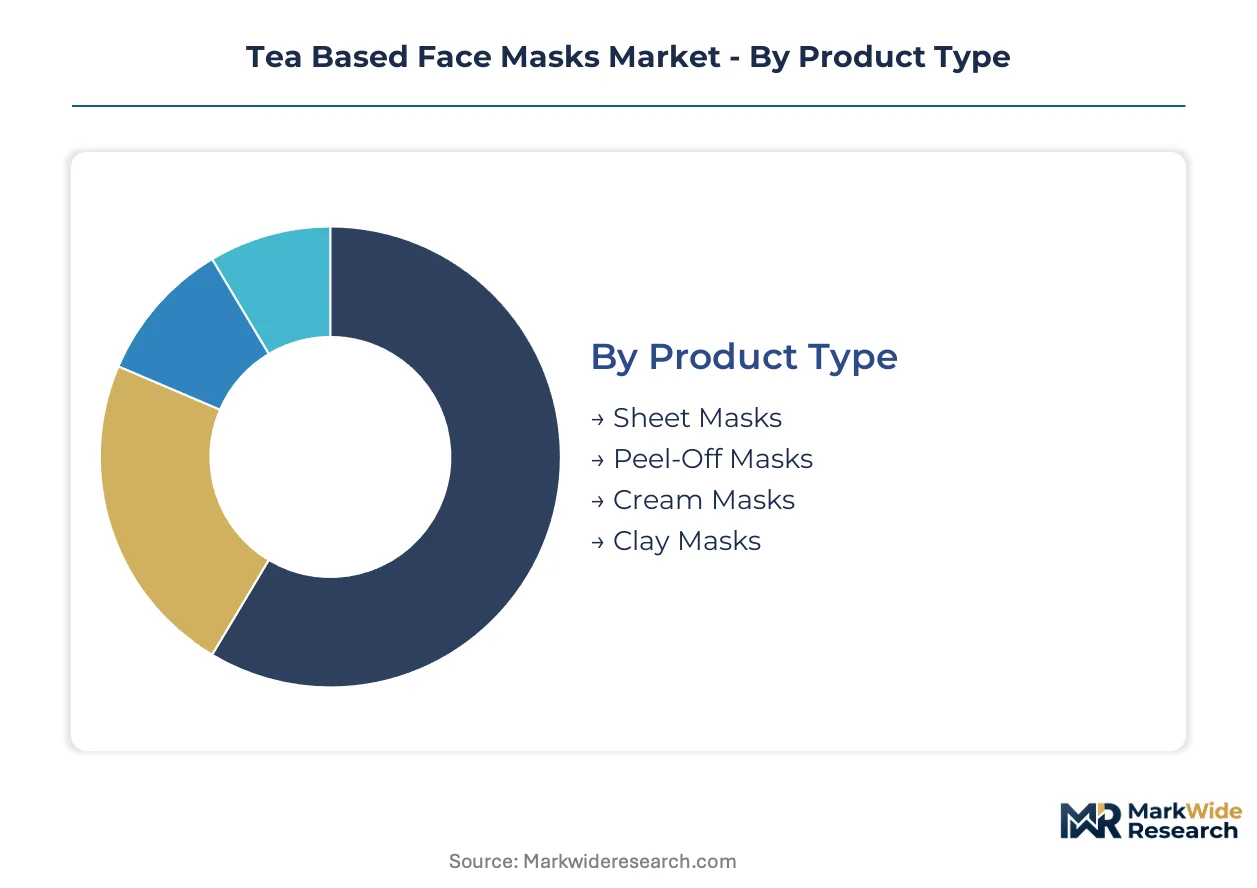
Tea based face masks fragment across four distinct category axes, each governing different margin pools and channel access. Product format determines manufacturing complexity and shelf positioning, while ingredient provenance separates commodity formulations from biotechnology-enhanced premium tiers.
Product Type:
Mature formats dominate volume throughput while emerging structures capture margin expansion through convenience innovation.
- Sheet Masks:Cellulose or biocellulose substrates pre-saturated with tea extract serums enable single-application dosing without mixing. South Korean manufacturing clusters supply global demand as convenience-driven casual users in urban centers prioritize portability and zero cleanup.
- Clay Masks:Bentonite or kaolin bases blended with powdered tea leaves deliver detoxification claims through physical adsorption. Organic buyers in North American and European markets drive premium positioning as ECHA substance restrictions eliminate synthetic preservative alternatives.
- Peel-Off Masks:Polyvinyl alcohol or alginate bases form occlusive films that lift upon drying, incorporating tea extracts for antioxidant delivery during the setting phase.
- Cream Masks:Emulsion-based formulations with sustained contact time target overnight repair protocols and mature skin concerns.
Sheet masks handle the majority of throughput; clay masks are gaining share fastest among regulatory-sensitive European markets.
Main Ingredient:
Cost tier stratification separates commodity leaf extracts from fermentation-enhanced biotechnology inputs.
- Matcha:Ceremonial-grade stone-ground powder delivers concentrated epigallocatechin gallate content with verified origin traceability. Spa professionals in Seoul and Tokyo aesthetic clinics adopt pharmaceutical-grade protocols that justify service-tier pricing premiums.
- Green Tea:Cold-brew extracted Camellia sinensis leaves from Jeju Island supply chains anchor mass-market positioning through established antioxidant claims and familiar sensory profiles.
- Black Tea:Fermented leaf bioprocessing generates theaflavin complexes with distinct anti-inflammatory signaling properties.
- Herbal Blends:Composite formulations incorporating camomile, calendula, or centella alongside tea bases target sensitive skin positioning.
Green tea commands the largest volume footprint; matcha demonstrates the steepest expansion trajectory as professional channel adoption accelerates.
Consumer Type:
Application context separates self-directed home use from professionally administered treatment protocols.
- Skincare Enthusiasts:Information-seeking consumers with established multi-step routines drive ingredient literacy and fermentation technology curiosity. Direct-to-consumer subscription platforms in South Korea capture this cohort through algorithmic skin assessment tools.
- Spa Professionals:Licensed aestheticians and medical spa operators require bulk formats with treatment-room efficiency and liability documentation. Matcha protocols with ceremonial-grade certification enable service tier differentiation in competitive urban markets.
- Casual Users:Occasional purchasers prioritizing convenience and immediate sensory gratification over long-term regimen adherence.
- Organic Buyers:Certification-driven consumers evaluating supply chain ethics, biodegradability, and preservative system transparency.
Skincare enthusiasts generate the highest lifetime value per account; spa professionals are expanding most quickly as aesthetic medicine investment rises.
Packaging Type:
Volume scale and margin structure diverge sharply between single-unit trial formats and committed-use bulk configurations.
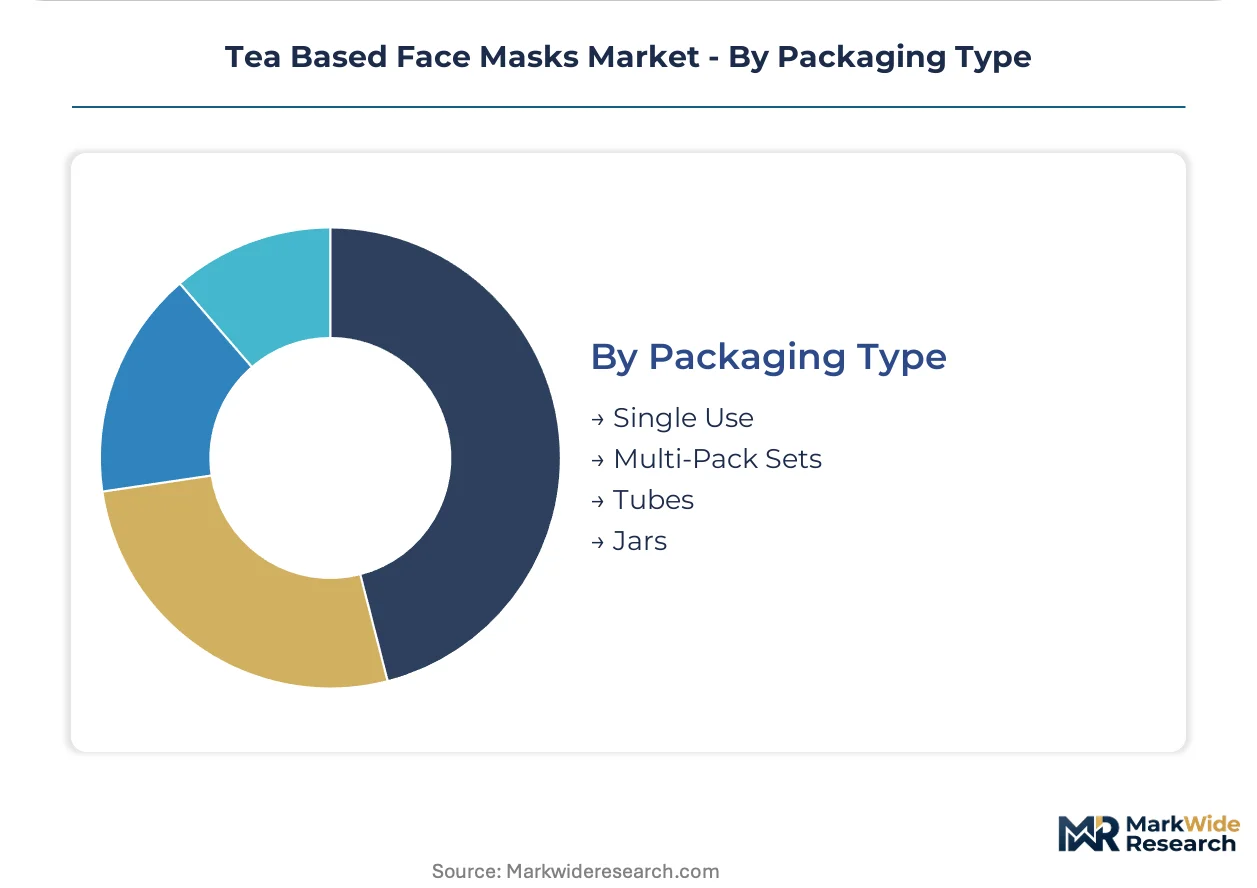
- Single Use:Individually sealed sachets or pouches maintain serum stability through nitrogen flushing and metallized barrier films. Travel retail and impulse channels favor this format for trial conversion without inventory commitment.
- Multi-Pack Sets:Assortment configurations with 5-10 unit counts enable regimen bundling and gift positioning. The Body Shop competes on ethical sourcing credentials through this format.
- Tubes:Collapsible aluminum or laminate structures for cream and clay mask formats with controlled dispensing.
- Jars:Wide-mouth glass or polypropylene containers for professional back-bar and high-frequency home use scenarios.
Single use formats dominate unit velocity; multi-pack sets capture superior margin per transaction through bundling economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea treats tea masks as professional-grade aesthetic tools, while Western markets position them as accessible self-care commodities, creating divergent pricing architectures and channel strategies across consumption zones.
South Korea
Seoul Capital Area aesthetic clinics drive ceremonial-grade matcha adoption for service-tier differentiation. MFDS microbial safety testing protocols for fermented extracts extend product launch cycles but elevate quality benchmarks. Jeju Island green tea supply chains anchor Amorepacific Corporation and Innisfree Corporation manufacturing clusters with captive cultivation control.
United States
FDA cosmetic labeling rules mandate ingredient transparency that favors clean beauty positioning among skincare enthusiasts. Direct-to-consumer subscription platforms concentrate in California and New York Metro, deploying algorithmic skin assessment for personalized curation. The Body Shop competes through ethical sourcing credentials in multi-pack retail configurations.
China
NMPA registration pathways for imported cosmetics create compliance barriers that domestic brands exploit through local fermentation biotechnology partnerships. Yangtze River Delta manufacturing hubs near Shanghai supply sheet mask substrates from tea processing waste cellulose. Lu Ming Tang represents traditional Chinese medicine positioning in premium tier formulations.
Germany
ECHA substance restrictions on synthetic preservatives accelerate natural tea-derived antimicrobial adoption among organic buyers. REACH chemical safety disclosures mandate full supply chain transparency that favors established European brands with documented biodegradability credentials. Bavaria-based distributors control Central European wholesale channels for professional spa formats.
Brazil
ANVISA cosmetic registration pathways remain underutilized by tea-mask exporters despite accelerating aesthetic medicine investment in São Paulo and Rio de Janeiro. Local consumers demonstrate rising ingredient literacy that matches skincare enthusiast profiles in Asian markets. Minas Gerais botanical extract infrastructure supports potential backward integration opportunities for regional manufacturing.
Tea Based Face Masks Market Competitive Landscape
Capability concentration sits with biotechnology specialists commanding fermentation patents; scale advantage sits with multinational beauty houses controlling retail distribution. The vendor base stratifies across three tiers: South Korean research-linked specialists, Western ethical sourcing brands, and mass-market conglomerates with portfolio breadth. Dominant competitive moves include captive supply chain development through plantation acquisitions and algorithmic personalization infrastructure deployment in direct-to-consumer channels.
Within the biotechnology specialist tier, Amorepacific Corporation and Innisfree Corporation exemplify fermentation-enhanced positioning through South Korean research institute partnerships. Among Western ethical sourcing brands, The Body Shop occupies a position defined by multi-set bundling and supply chain transparency credentials. At the mass-market scale end, L'Oréal Paris and Estée Lauder represent portfolio diversification strategies that treat tea masks as ingredient-line extensions within broader skincare architectures.
| Leading Market Players |
|---|
| Lotus Herbals |
| Estée Lauder |
| Lakmé |
| L'Oréal Paris |
| Avon Products |
| The Body Shop |
| Innisfree Corporation |
| Amorepacific Corporation |
| Lu Ming Tang |
| Others |
Value Network & Pricing Analysis
Shanghai-to-Busan container freight corridors govern landed cost differentials for sheet mask substrates, compressing margins for European and North American importers while amplifying price separation between Jeju Island-sourced green tea formulations and commodity-grade alternatives. This logistics architecture concentrates pricing power among South Korean manufacturers with captive cultivation assets, forcing distant buyers to absorb tariff-adjusted premiums or accept lower-grade matcha inputs.
Pricing Analysis
Long-term offtake contracts with Jeju Island tea cooperatives anchor premium-tier pricing stability, while spot-market Camellia sinensis leaf procurement exposes mid-tier brands to climate-driven volatility. Three-tier pricing structure across ceremonial-grade matcha, cold-brew green tea extracts, and fermented black biotechnology separates spa professional channels from mass-market retail. Pricing pressure stems from Centella asiatica substitution in antioxidant positioning, eroding green tea premium capture. Casual users exhibit highest price sensitivity, whereas skincare enthusiasts absorb fermentation technology premiums through subscription commitments.
Supply Chain Analysis
Export-control regimes on fermentation biotechnology equipment limit South Korean bioreactor technology transfer, concentrating advanced epigallocatechin gallate preservation capabilities within Seoul Capital Area research institutes. Raw material flows draw from Jeju Island green tea plantations, Uji matcha cultivation zones, and Yangtze River Delta cellulose substrate manufacturers. Single-source vulnerability sits with fermented black tea patent clusters held by domestic research partnerships. Distribution runs through Bavaria-based wholesale channels for European spa formats and California direct-to-consumer platforms for North American subscription models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense imperatives as Centella asiatica and mugwort extracts capture comparable antioxidant claims at reduced formulation costs, threatening tea-derived premium positioning.
For Market Incumbents: Build biotechnology patent moats through exclusive fermentation research institute partnerships that lock up theaflavin complex production methods. Secure backward integration into Jeju Island tea cultivation to insulate input costs from climate volatility. Anchor channel control through direct-to-consumer skin assessment algorithms that concentrate lifetime value capture and reduce retail margin leakage to multi-brand distributors. For New Entrants and Emerging Players: Brazil's ANVISA registration pathway offers underpenetrated white-space opportunity as aesthetic medicine investment accelerates in São Paulo without established tea-mask incumbents. Target skincare enthusiast segments through algorithmic personalization platforms that bypass traditional retail gatekeepers. Pursue go-to-market entry via subscription-based curation models that leverage computer vision skin analysis for differentiated positioning. For Investors and Strategic Acquirers: Carve-out targets emerge from multinational beauty conglomerates treating tea masks as non-core portfolio extensions rather than biotechnology platforms. Long-term viability hinges on fermentation infrastructure ownership and data-captive subscription economics rather than brand equity alone. Monitor MFDS microbial safety testing protocol revisions as inflection signals for regulatory compliance cost escalation that favors scaled manufacturers over artisanal entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Tea Cultivation Acquisition | Jeju Island plantation control eliminates climate-driven input cost volatility for green tea supply chains. |
| Fermentation Bioreactor Scale-Up | 10,000-liter vessel deployment collapses epigallocatechin gallate yield gaps between artisanal and industrial production. |
| Direct-to-Consumer Platform Launch | Algorithmic skin assessment tools concentrate lifetime value capture among skincare enthusiast subscribers. |
| ANVISA Registration Pathway Entry | Brazilian aesthetic medicine investment growth creates first-mover advantage in underpenetrated Latin American markets. |
| Ceremonial-Grade Matcha Certification | Pharmaceutical-grade protocol adoption enables service-tier pricing premiums in Seoul and Tokyo aesthetic clinics. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulation chemists, spa professional channel managers, direct-to-consumer platform operators, and tea cultivation supply chain directors, then refined through secondary validation against MFDS regulatory filings, REACH substance restriction databases, customs import records for tea extract shipments, and SEC disclosures from listed beauty conglomerates. Bottom-up segment sizing triangulated against top-down category spend estimates to anchor volume and value outputs.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling segmentation dimensions spanning product format, ingredient provenance tier, consumer application context, and packaging configuration. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and channel shift dynamics. Forecast inputs incorporated Jeju Island tea yield patterns, bioreactor fermentation capacity expansion timelines, and ECHA substance restriction implementation schedules.
Practitioners should monitor ANVISA registration pathway simplification, MFDS testing protocol revisions, and EU Green Deal packaging mandate enforcement for early signals of competitive repositioning requirements. Forecasts reflect documented assumptions regarding fermentation technology diffusion rates and subscription platform adoption curves. Material shifts in Centella asiatica substitution economics or REACH preservative restriction scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Thailand Skin Care Products Market
Cosmetics & Skincare
Microbiome Cosmetic Products Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Reusable Makeup Remover Pad Market
Cosmetics & Skincare
Makeup Remover Market
Cosmetics & Skincare
Cold Pressed Soap Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Japan Bath Soap Market
Cosmetics & Skincare
Liquid Makeup Market
Cosmetics & Skincare
Eyeliner Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Eye Cream Market
Cosmetics & Skincare
Mushroom Cosmetics Market
Cosmetics & Skincare
Pillow Spray Market