
 China Skincare Market | 2026-2036
China Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
China Skincare Market Intelligence
Premium clinical-grade formulations is redrawing competitive boundaries across the China skincare landscape. L'Oréal S.A. leverages its dermatological science heritage to anchor high-margin professional channels in tier-one cities. Estée Lauder Inc. sustains brand equity through concentrated R&D investment in bio-fermentation technologies. Kao Corporation differentiates via sensorial innovation tailored to East Asian skin microbiome research.
Skincare encompasses topical preparations designed to cleanse, protect, or improve skin condition through active ingredients such as niacinamide, retinoids, or hyaluronic acid at specified concentrations, manufactured via emulsification, fermentation, or encapsulation processes for cosmetic or quasi-drug applications. Moisturizers and serums occupy the deepest margin pools as consumers prioritize barrier repair and targeted treatment over basic cleansing. Online retail channels are capturing the fastest volume growth, driven by live-stream commerce ecosystems and direct-to-consumer subscription models. The women's segment dominates absolute spend, though men's skincare is expanding from niche grooming into preventive anti-aging protocols.
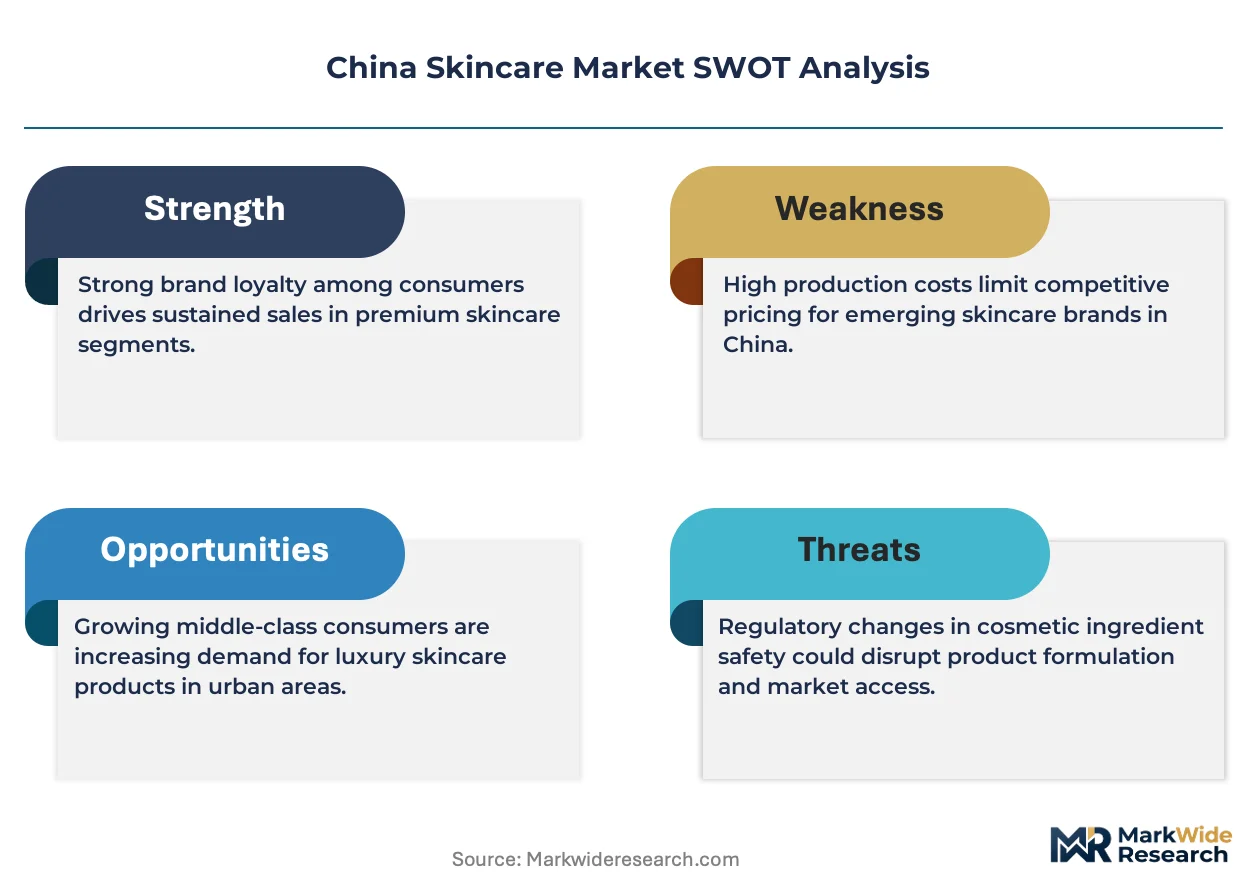
NMPA cosmetic ingredient registration rules, GB standards for product safety, and SAMR advertising enforcement collectively elevate compliance costs while accelerating consolidation toward scientifically substantiated brands. These regulatory filters reward companies with in-house toxicology and clinical validation capabilities. Stakeholders must monitor NMPA's evolving whitelist for novel ingredients to preempt formulation pipeline disruptions.
Market Dynamics
NMPA's novel cosmetic ingredient registration pathway is compressing formulation pipelines and rewarding brands with captive toxicology capabilities. Tier-one cities now demand clinical-grade substantiation that smaller domestic formulators cannot replicate without external validation partnerships.
Growth Catalysts
- Live-stream commerce ecosystems:Douyin and Xiaohongshu creator networks collapse discovery-to-purchase cycles for serums and medical-aesthetic aftercare. Professional women in Shanghai and Beijing drive repeat purchase velocity through algorithmic personalization.
- GB standards for product safety:Mandatory safety assessments elevate consumer trust in domestic brands. Compliance investments by established players widen the gap from unverified imports.
- Medical-aesthetic clinic expansion:Post-treatment aftercare protocols create institutional demand for barrier-repair formulations. Clinic partnerships lock in professional channel shelf space.
Market Restraints
- NMPA registration timelines:Novel ingredient approvals stretch 18-24 months, freezing pipeline innovation for mid-tier formulators without pre-registered active libraries.
- Peptide and biotech input concentration:Fermentation-derived actives depend on a limited supplier base concentrated in Zhejiang and Jiangsu provinces, exposing margins to batch consistency volatility.
- SAMR advertising enforcement:Strict prohibitions on unverified efficacy claims force creative asset destruction and agency retainer inflation.
Strategic Opportunities
- Men's preventive anti-aging protocols:Male grooming graduates from basic cleansing to retinoid and antioxidant routines, opening white space in tier-two cities.
- Direct-to-consumer subscription models:Replenishment algorithms for hyaluronic acid and niacinamide serums capture lifetime value through locked-in repurchase cycles.
- Dual carbon goals alignment:Carbon-neutral packaging and biotechnology manufacturing processes attract ESG-mandated institutional investment and premium positioning.
Industry Challenges
- Clinical validation talent scarcity:Dermatology-trained formulators and biostatisticians command compensation premiums that strain R&D budgets outside multinational structures.
- Legacy ERP integration with traceability systems:Batch-level ingredient tracking for NMPA audits requires middleware investments that fragment IT roadmaps.
- Cross-border IP enforcement:Active ingredient patents filed abroad face delayed recognition under China's patent examination backlog, complicating licensing negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Skincare Market |
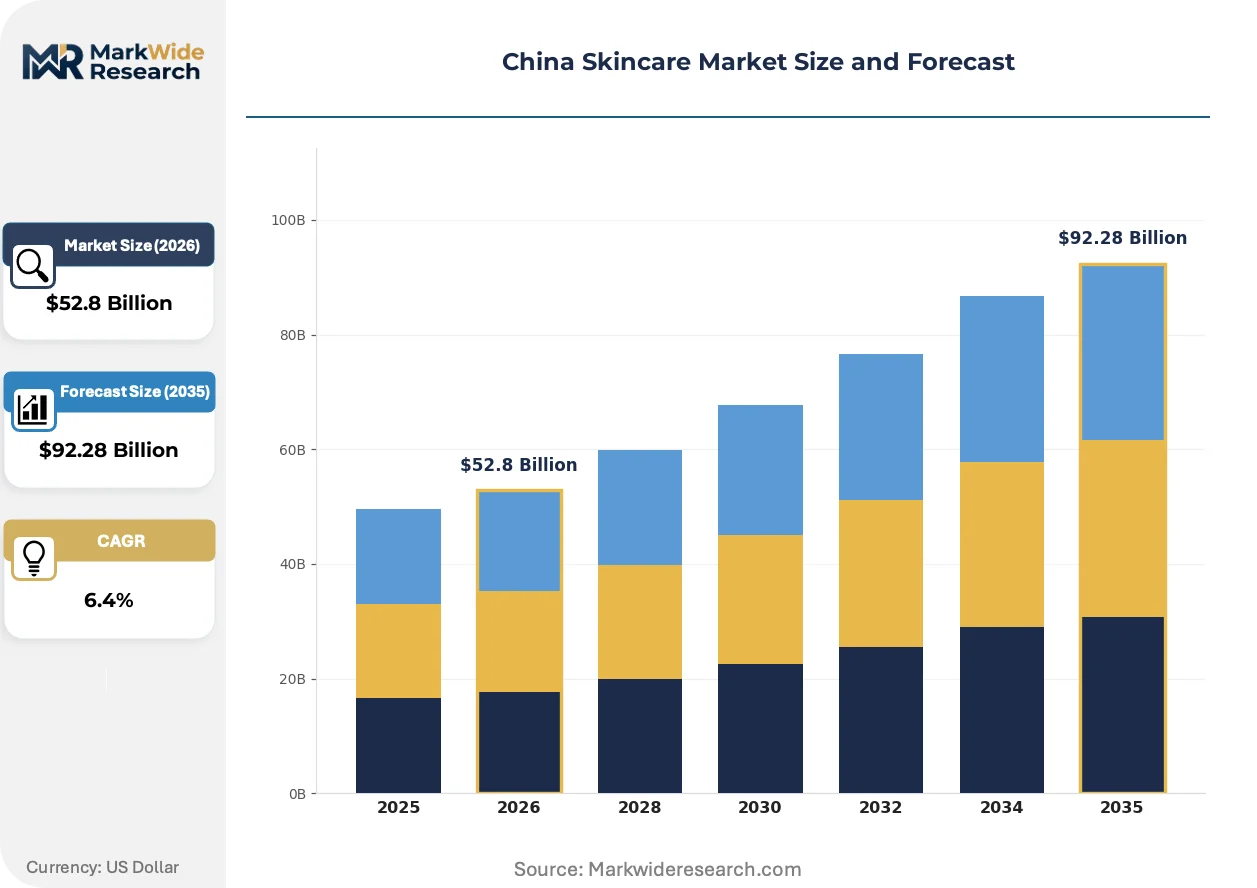
| Market Size in 2026 | $52.8 Billion |
| Market Size in 2035 | $92.28 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cleansers, Moisturizers, Sunscreens, Serums End User: Women, Men, Teens, Seniors Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Pharmacies Price Tier: Luxury, Premium, Mid-range, Budget |
| Companies Covered | Shiseido Company Ltd., Johnson & Johnson, L'Oréal S.A., Kao Corporation, Beiersdorf AG, The Procter & Gamble Company, Unilever, Pierre Fabre Group, Estée Lauder Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Skincare Market Strategic Shifts & Innovations
Biotechnology and digital commerce infrastructure are compressing product development cycles while elevating substantiation requirements. Formulation science now converges with data-driven personalization engines.
Encapsulation technology for retinoid and vitamin C stabilization is miniaturizing delivery systems to sub-micron liposome and niosome architectures. Premium serum brands in Beijing and Shanghai adopt these systems to claim enhanced dermal penetration. The technology is miniaturizing equipment footprints for domestic manufacturers, enabling in-house production that previously required European contract manufacturing.
NMPA's evolving whitelist for novel cosmetic ingredients is accelerating ingredient innovation timelines for compliant brands. The regulation forces toxicology investment concentration among top-tier formulators while disqualifying gray-market imports. Medical-aesthetic aftercare segments respond fastest, integrating newly approved peptides into post-laser recovery protocols.
Algorithmic skin diagnostics through smartphone imaging are displacing in-person dermatologist consultations for initial product selection. Young professional women in Guangzhou and Shenzhen trust AI-generated regimen recommendations over counter sales associates. This behavioral pivot concentrates marketing spend on platform-native content rather than traditional retail slotting fees.
China Skincare Market Segmentation
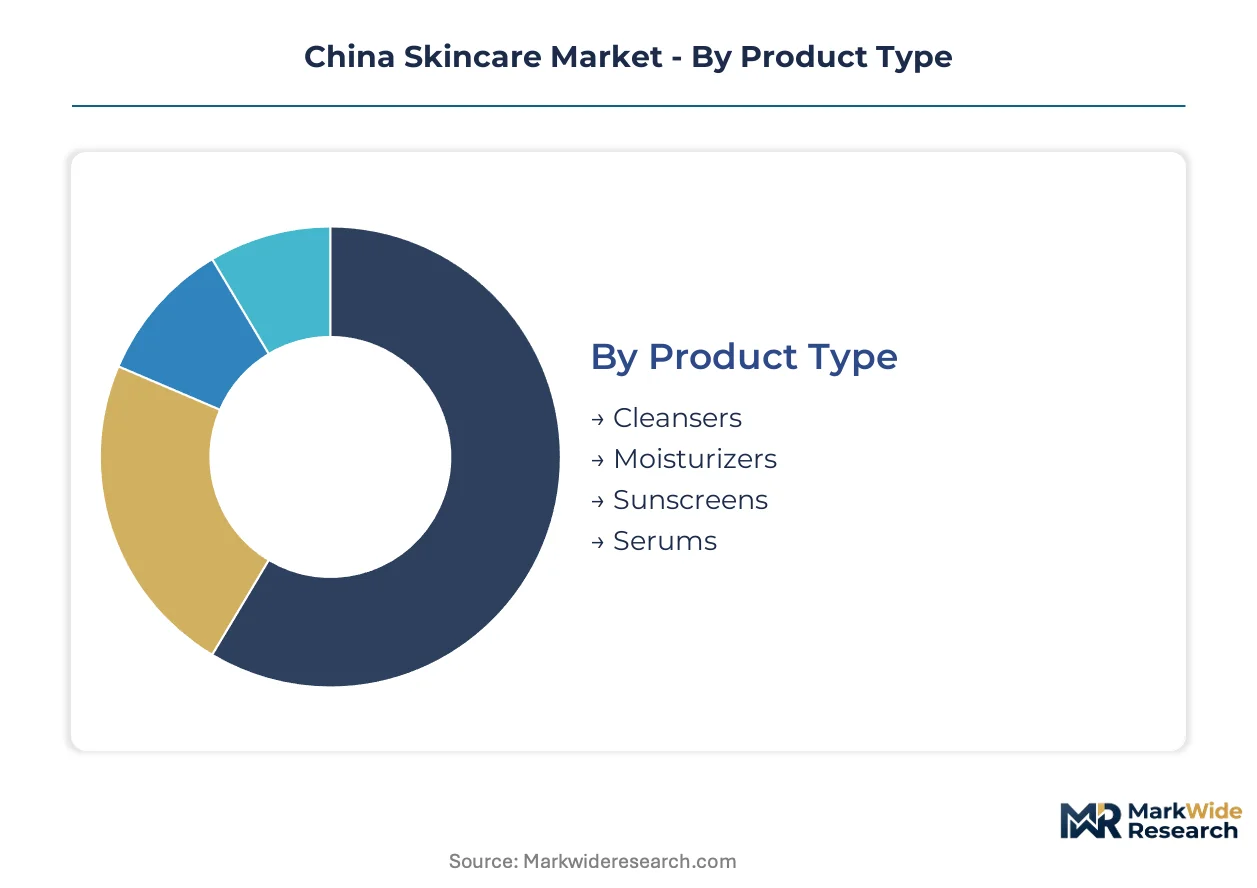
China's skincare segmentation reveals how NMPA compliance costs and live-stream commerce are redrawing competitive boundaries. Distinct product, user, channel, and price tiers now demand specialized formulation pipelines and distribution infrastructure.
Product Type:
Substitution pressure runs strongest against basic cleansers as consumers trade up to multifunctional treatment products with clinical substantiation.
- Serums:Concentrated active delivery systems featuring niacinamide, retinoids, or peptides at therapeutic concentrations. Professional women in Shanghai and Beijing drive repeat purchase velocity through algorithmic personalization on Douyin and Xiaohongshu.
- Moisturizers:Barrier-repair formulations leveraging ceramide complexes and hyaluronic acid matrices. Medical-aesthetic clinics in tier-one cities institutionalize post-treatment protocols, locking in professional channel shelf space.
- Sunscreens:Photostable UV filters meeting GB standards for daily protection against urban pollution.
- Cleansers:pH-balanced surfactant systems facing margin compression from private-label alternatives.
Moisturizers retain volume leadership; serums hold the steepest expansion curve.
End User:
Cost tier stratification separates clinically validated professional lines from mass-market alternatives across demographic cohorts.
- Women:Primary demand anchor spanning preventive aging routines in tier-one cities to basic hydration in emerging markets. Live-stream commerce ecosystems collapse discovery-to-purchase cycles for this cohort.
- Men:Grooming graduates into retinoid and antioxidant preventive protocols, opening white space in tier-two cities where clinical-grade masculinity positioning remains underdeveloped.
- Seniors:Barrier-repair and gentle exfoliation addressing thinning epidermal structures.
- Teens:Acne management and oil-control formulations with social media-native marketing.
Women retain volume leadership; men gain share fastest through preventive anti-aging adoption.
Distribution Channel:
Volume concentration in digital channels is displacing legacy retail infrastructure while elevating traceability requirements.
- Online Retail:Direct-to-consumer platforms and creator networks enabling subscription replenishment algorithms. Douyin's live-stream commerce captures the fastest volume growth through locked-in repurchase cycles for hyaluronic acid and niacinamide serums.
- Specialty Stores:Experiential retail with skin diagnostics and personalized regimen building in Shanghai and Beijing malls.
- Pharmacies:Quasi-drug positioning and NMPA-registered dermocosmetic distribution.
- Supermarkets:Mass-market cleansers and basic moisturizers with high inventory turnover.
Online retail retains volume leadership; specialty stores command the highest margin expansion trajectory.
Price Tier:
Supply concentration of fermentation-derived actives in Zhejiang and Jiangsu provinces shapes margin structures across pricing strata.
- Luxury:Biotech-manufactured formulations with carbon-neutral packaging attracting ESG-mandated institutional positioning. Captive toxicology capabilities and NMPA pre-registration libraries defend premium pricing.
- Premium:Clinical-grade substantiation with medical-aesthetic clinic partnerships and algorithmic personalization engines.
- Mid-range:Domestic brands leveraging GB standards compliance to displace unverified imports.
- Budget:Private-label and gray-market alternatives facing SAMR enforcement pressure.
Mid-range retains volume leadership; luxury commands the steepest margin expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Active ingredient fermentation capacity clusters in Zhejiang and Jiangsu provinces, creating regional dependencies that shape formulation economics across eastern China. NMPA registration timelines compress competitive windows for brands without pre-established toxicology partnerships in these manufacturing hubs.
Yangtze River Delta
Shanghai anchors clinical-grade serum demand among professional women seeking medical-aesthetic aftercare. NMPA's evolving whitelist for novel cosmetic ingredients accelerates compliant brand pipelines here. Zhejiang province's fermentation-derived active suppliers concentrate peptide and biotech input manufacturing, exposing margins to batch consistency volatility.
Pearl River Delta
Guangzhou and Shenzhen drive algorithmic skin diagnostics adoption through smartphone imaging platforms. SAMR advertising enforcement reshapes creative asset strategies for live-stream commerce ecosystems on Douyin. The region's electronics manufacturing base enables in-house encapsulation technology production for retinoid stabilization systems.
Beijing-Tianjin-Hebei
Beijing's tier-one consumer base demands carbon-neutral packaging and biotechnology manufacturing alignment with dual carbon goals. GB standards for product safety elevate compliance investments that widen gaps from unverified imports. Hebei province's logistics infrastructure supports direct-to-consumer subscription replenishment models for hyaluronic acid serums.
Sichuan-Chongqing
Chongqing's emerging professional class expands premium moisturizer adoption beyond traditional coastal markets. NMPA registration pathways for novel ingredients create 18-24 month innovation freezes for mid-tier formulators lacking pre-registered active libraries. Chengdu's medical-aesthetic clinic networks institutionalize post-treatment barrier-repair protocols.
Shandong Peninsula
Qingdao's port infrastructure facilitates cross-border ingredient sourcing for domestic brands building NMPA-compliant pipelines. The province's chemical manufacturing heritage supports surfactant production for pH-balanced cleanser formulations. Local formulators leverage GB standards compliance to displace gray-market alternatives in budget-tier retail channels.
China Skincare Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes across the China skincare landscape. Multinational dermatological science heritage anchors premium clinical-grade positioning in tier-one cities, while domestic formulators exploit GB standards compliance to capture mid-range volume. Three archetypes dominate: captive toxicology platforms with NMPA pre-registration libraries, sensorial innovation specialists leveraging East Asian skin microbiome research, and live-stream commerce-native brands with algorithmic personalization engines. Competitive moves concentrate on medical-aesthetic clinic partnerships for professional channel shelf space and direct-to-consumer subscription infrastructure for serum replenishment cycles.
Within the dermatological science tier, L'Oréal S.A. and Estée Lauder Inc. represent multinational heritage positioning, while Kao Corporation exemplifies sensorial innovation tailored to regional skin biology research. These entities anchor distinct competitive vectors—clinical substantiation versus microbiome-specific formulation—without overlapping positioning in the same consumer segments.
| Leading Market Players |
|---|
| Shiseido Company Ltd. |
| Johnson & Johnson |
| L'Oréal S.A. |
| Kao Corporation |
| Beiersdorf AG |
| The Procter & Gamble Company |
| Unilever |
| Pierre Fabre Group |
| Estée Lauder Inc. |
| Others |
Cost & Logistics Intelligence
Fermentation capacity utilization rates in Zhejiang and Jiangsu provinces anchor cost structures across the China skincare landscape. Scale economies at biotech active suppliers compress unit costs for niacinamide and peptide inputs while elevating price floors for mid-tier brands lacking captive manufacturing.
Pricing Analysis
NMPA registration requirements dictate the pricing tier structure through compliance cost allocation. Three-tier pricing structure across premium, standard, and economy levels separates clinical-grade substantiation from basic GB-standard compliance. Cost compression in the mid-range segment is intensifying because domestic brands leverage GB standards to displace unverified imports. Budget-tier buyers exhibit highest price sensitivity; medical-aesthetic clinics demonstrate lowest sensitivity due to institutional procurement protocols.
Supply Chain Analysis
China anchors fermentation-derived active manufacturing for niacinamide, hyaluronic acid, and peptide complexes. South Korea and Japan supply photostable UV filters and encapsulation technology for retinoid stabilization. Raw material dependencies rest on corn-derived feedstocks for fermentation, specialty surfactants for emulsification, and pharmaceutical-grade solvents for extraction. Single-source vulnerability concentrates in Zhejiang province peptide suppliers. Distribution runs through direct-to-consumer platforms and medical-aesthetic clinic networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription replenishment algorithms for hyaluronic acid and niacinamide serums expand faster than one-time transactional sales, converting hardware-like product purchases into recurring revenue streams with superior lifetime value economics.
For Market Incumbents: Consolidate toxicology capabilities and NMPA pre-registration libraries to defend against pipeline freezes affecting mid-tier competitors. Lock in medical-aesthetic clinic partnerships for professional channel shelf space. Expand backward integration into fermentation capacity in Zhejiang province to secure peptide supply against batch consistency volatility.
For New Entrants and Emerging Players: Lead with algorithmic skin diagnostics and live-stream commerce-native positioning on Douyin and Xiaohongshu to bypass traditional retail slotting fee barriers. Target men's preventive anti-aging protocols in tier-two cities where clinical-grade masculinity positioning remains underdeveloped. Deploy direct-to-consumer subscription models with replenishment algorithms to capture locked-in repurchase cycles.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among brands with direct-to-consumer subscription infrastructure and medical-aesthetic clinic network density. Long-term viability favors acquirers of captive toxicology platforms with NMPA pre-registration libraries and carbon-neutral packaging capabilities aligned with dual carbon goals. Monitor NMPA whitelist expansions for novel cosmetic ingredients as inflection indicators for compliant brand pipeline acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| NMPA Pre-Registration Library Buildout | Captive toxicology capabilities compress competitor innovation timelines by 18-24 months. |
| Medical-Aesthetic Clinic Partnership | Professional channel shelf space locks in institutional demand for barrier-repair formulations. |
| Direct-to-Consumer Subscription Launch | Replenishment algorithms for serums capture lifetime value through locked-in repurchase cycles. |
| Carbon-Neutral Packaging Transition | Dual carbon goals alignment attracts ESG-mandated institutional investment and premium positioning. |
| Algorithmic Skin Diagnostics Integration | AI-generated regimen recommendations displace counter sales associates in tier-one cities. |
Research Approach
A spread of perspectives from brand managers at multinational and domestic skincare companies, NMPA regulatory affairs specialists, medical-aesthetic clinic procurement directors, and live-stream commerce platform operators converged on the working assumptions. Secondary validation drew from NMPA cosmetic ingredient registration databases, SAMR advertising enforcement records, GB standards documentation, and customs trade data for active ingredient imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, end user, distribution channel, and price tier segments.
Segmentation dimensions modeled include product formulation type, demographic cohort, channel infrastructure, and regional regulatory cluster across the analysis window. CAGRs were derived from regression analysis of historical adoption curves and elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated NMPA registration timeline assumptions and live-stream commerce penetration rates by city tier.
The analysis sits within stated boundaries; outcomes outside sustained NMPA regulatory enforcement, live-stream commerce ecosystem stability, or medical-aesthetic clinic expansion trajectories would require recalibration. Forecasts reflect documented assumptions regarding novel ingredient approval velocities and professional channel shelf space allocation. Recalibration cycles align with material shifts in NMPA whitelist expansions, SAMR advertising policy revisions, and dual carbon goals implementation timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Probiotic Skin Care Cosmetic Product Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Facial Serum Market
Cosmetics & Skincare
Halal Cosmetic Products Market
Cosmetics & Skincare
Hyaluronic Acid Beauty Products Market
Cosmetics & Skincare
Sports Sun Care Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Qatar Cosmetic Products Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
E Commerce Cosmetic and Fragrance Market
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Snail Beauty Products Market