
 Face Bronzer Market | 2026-2036
Face Bronzer Market Size, Share, and Industry Trends Forecast 2026-2036
Face Bronzer Market Analysis
Aftermarket service revenue from virtual try-on tools and shade-matching algorithms is reshaping how consumers engage with face bronzer brands before purchase. Benefit Cosmetics leverages its specialized boutique footprint to sustain direct customer relationships across North America and Europe. MAC Cosmetics anchors its competitive stance through professional artist programs that dominate backstage and editorial environments. L'Oréal extends its reach via mass-market distribution networks that compete aggressively on accessibility and shade range breadth.
Face bronzer constitutes a pigmented cosmetic formulation designed to simulate sun-induced melanin deposition on facial skin, typically incorporating iron oxides, mica, and titanium dioxide within talc or emulsion bases to achieve buildable, light-reflecting coverage. Its primary commercial purpose centers on enabling consumers to modify perceived facial structure, warmth, and dimension without ultraviolet exposure. Powder formulations occupy the mature volume position given their historical dominance and lower price accessibility, while liquid and cream segments attract margin concentration due to their association with skin-nourishing ingredients and professional application rituals. The professional use and makeup artist application categories demonstrate the most pronounced structural momentum, driven by social media tutorial culture and bridal industry demand.
The FDA oversees color additive safety and labeling requirements for face bronzers distributed in the United States, while the EU Cosmetics Regulation mandates rigorous safety assessments and ingredient disclosure that elevate compliance costs for market entrants. REACH restrictions on specific pigment chemistries and the EU Green Deal's push toward sustainable packaging are forcing reformulation investments across multinational portfolios. Stakeholders must monitor evolving state-level clean beauty legislation in California and New York, where disclosure requirements often precede federal standards and reshape competitive positioning for domestic and imported brands alike.
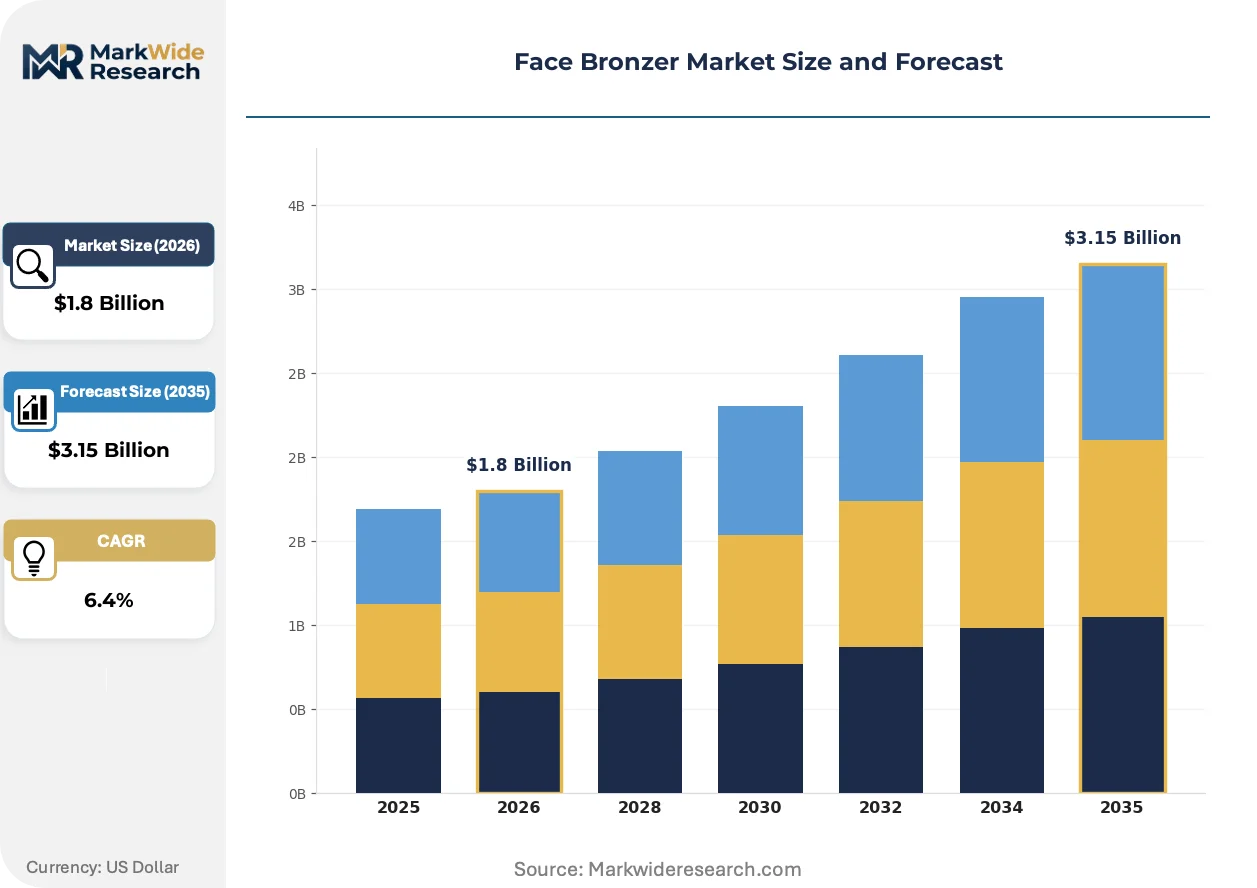
Market Dynamics
Professional makeup artist channels are compressing the traditional retail pathway for face bronzer distribution, with social media tutorial culture redirecting consumer preference toward pro-grade formulations and shade-matching precision tools.
Growth Catalysts
- EU Cosmetics Regulation:Mandatory ingredient disclosure and safety assessment protocols are elevating consumer trust in certified formulations, accelerating premium segment uptake across France, Germany, and Italy.
- Bridal industry demand:Professional makeup services for weddings and events are standardizing multi-product kits that include specialized bronzing products for photography-optimized finishes.
- Virtual try-on algorithms:Shade-matching technology deployed through mobile applications is reducing return rates and expanding online purchase confidence among first-time buyers.
Market Restraints
- Titanium dioxide supply concentration:Pigment sourcing dependency on Chinese processing facilities creates input cost volatility and formulation timeline uncertainty for emulsion-based products.
- REACH pigment restrictions:ECHA limitations on specific iron oxide chemistries are forcing reformulation investments that compress margins for mid-tier portfolio holders.
- Mineral oil substitution pressure:Clean beauty positioning is displacing traditional emollient bases, requiring R&D expenditure to validate plant-derived alternatives without compromising blendability.
Strategic Opportunities
- Clean beauty legislation in California:State-level disclosure mandates are creating first-mover advantage for brands with pre-established ingredient transparency protocols and sustainable packaging credentials.
- Men's grooming vertical:Underpenetrated male consumer segments in the United States and United Kingdom present whitespace for neutral-tone bronzing products marketed toward subtle contouring.
- EU Green Deal packaging mandates:Refillable compact and mono-material component requirements are opening partnership opportunities with specialized sustainable packaging suppliers ahead of compliance deadlines.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging color science and skin-nourishing ingredient compatibility commands premium compensation, constraining mid-cap brand innovation velocity.
- Cross-border certification timelines:Divergent safety assessment requirements between FDA color additive rules and EU Cosmetics Regulation notification procedures delay synchronized product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Face Bronzer Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Cream, Gel, Liquid Application: Personal Use, Professional Use, Makeup Artists, Salons Distribution Channel: Online Retail, Specialty Stores, Department Stores, Drugstores End User: Beauty Enthusiasts, Makeup Professionals, Everyday Users, Celebrities |
| Companies Covered | Benefit Cosmetics, MAC Cosmetics, Chanel, NARS Cosmetics, Bourjois, Estée Lauder Companies, Bobbi Brown Cosmetics, L'Oréal, Tom Ford, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Face Bronzer Market Emerging Trajectories
Formulation chemistry and distribution infrastructure are undergoing parallel transformation, with digital engagement tools and regulatory compliance frameworks acting as simultaneous accelerants and filters on competitive entry.
Skin-nourishing bronzer bases incorporating hyaluronic acid and peptide complexes are migrating from prestige salon channels toward mass-market accessibility. Professional makeup artists initially validated these hybrid cosmetic-skincare formulations for editorial work. The technology is migrating from pro-only supply chains into direct-to-consumer subscription models, compressing the traditional prestige-to-mass adoption cycle from years to months.
REACH restrictions on nano-scale titanium dioxide are forcing pigment supplier consolidation and safety dossier investments across European manufacturing footprints. ECHA's 2022 classification of certain pigment grades as suspected carcinogens by inhalation has triggered reformulation mandates. Powder-format products face the steepest compliance burden, with several multinational portfolios accelerating liquid and cream development to circumvent respiratory exposure classification.
After-sales engagement is unbundling from product purchase through standalone virtual consultation services. Beauty enthusiasts in the United States increasingly access professional shade-matching and application tutorials through subscription platforms rather than in-store counter interactions. This behavioral pivot concentrates customer relationship value with brands owning proprietary algorithmic tools and licensed artist networks, marginalizing traditional department store distribution.
Face Bronzer Market Segmentation
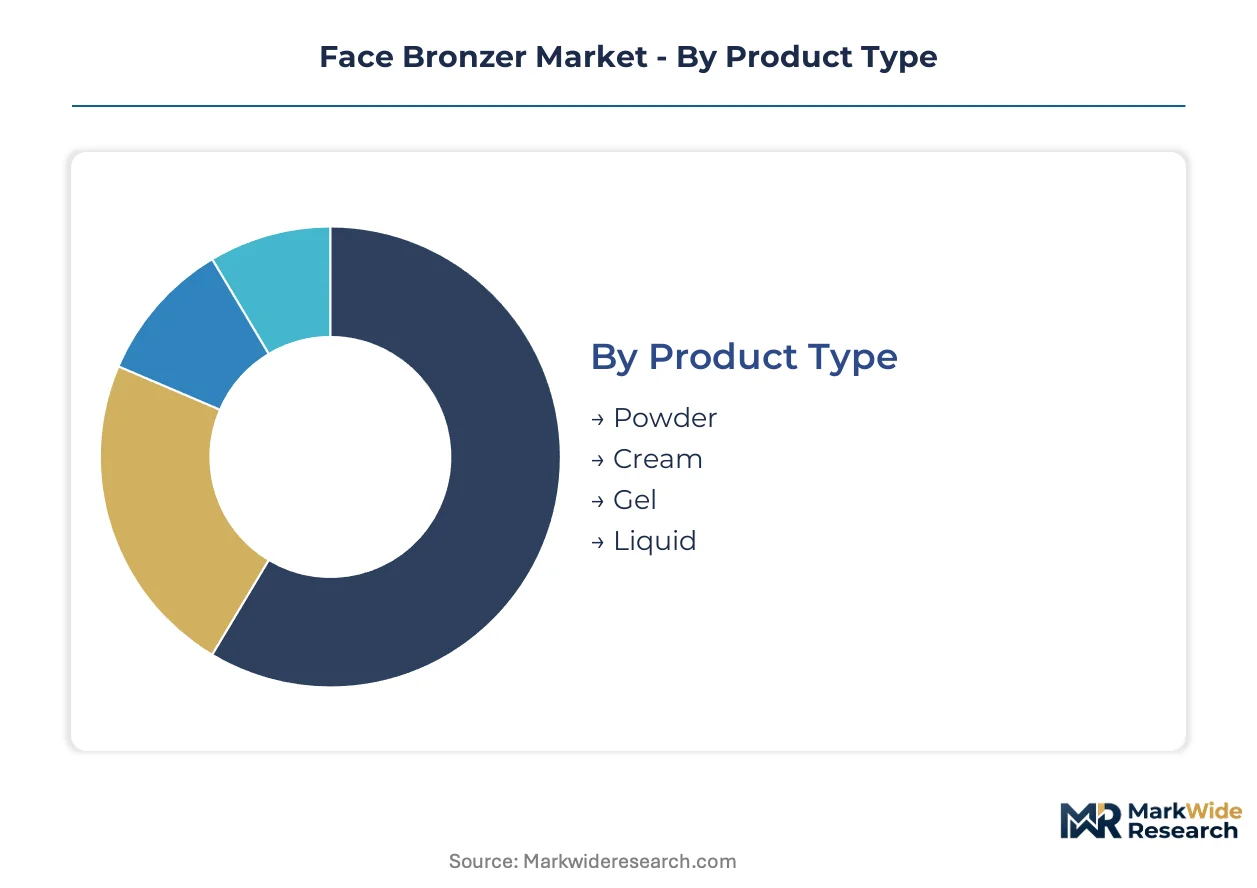
Face bronzer segmentation reveals how after-sales engagement intensity varies sharply across product formats and buyer profiles. Professional channels demand ongoing shade-matching support and application education, while mass-market formats compete on standalone purchase convenience.
Product Type:
After-sales service intensity peaks with emulsion-based formats requiring personalized shade consultation and technique guidance, while powder formats minimize post-purchase touchpoints through intuitive application.
- Powder:Talc or mica-based pressed or loose formulations deliver buildable coverage through iron oxide and titanium dioxide pigments. Demand concentrates among everyday users in the United States seeking accessible price points and familiar application rituals. Powder formats face the steepest REACH compliance burden from ECHA nano-scale titanium dioxide restrictions.
- Liquid:Emulsion suspensions incorporate skin-nourishing bases with hyaluronic acid or peptide complexes for blendable, photography-optimized finishes. Professional makeup artists in bridal and editorial channels drive demand concentration, requiring brands to maintain licensed artist networks for technique certification and shade-matching algorithms.
- Cream:Oil-in-water or anhydrous balms provide satin-to-dewy finishes with higher pigment load for contouring precision. Beauty enthusiasts seeking premium skin-feel properties favor cream textures for their association with skincare hybrid positioning.
- Gel:Water-based or silicone-dispersed systems offer lightweight, transfer-resistant wear for humid climates and active lifestyles. Gel formats attract experimentation among younger demographics through social media tutorial visibility.
By volume, Powder leads. By growth pace, Liquid is ahead.
Application:
Customer lifetime value diverges dramatically between self-directed personal use and relationship-intensive professional channels requiring sustained education investment.
- Professional Use:Salon and spa services integrate bronzer application within multi-step facial treatments, demanding bulk procurement and staff training programs. Makeup professionals in the United States and United Kingdom require ongoing product education and shade-matching tool access.
- Makeup Artists:Freelance and agency-affiliated artists operating in bridal, editorial, and entertainment contexts validate formulations for consumer market migration. This segment commands highest per-unit spending and drives prestige brand credibility through backstage placement.
- Personal Use:Individual consumers purchasing for self-application dominate transaction volume through retail and direct-to-consumer channels. Personal use buyers exhibit highest price sensitivity and lowest loyalty switching costs.
- Salons:Established service businesses incorporate bronzer into standard facial and makeup service menus, creating recurring B2B procurement relationships with distributors.
Personal Use generates largest transaction count. Makeup Artists deliver highest margin per unit.
Distribution Channel:
Channel selection determines whether brands capture value through algorithmic personalization or physical counter consultation.
- Online Retail:Direct-to-consumer and marketplace platforms deploy virtual try-on tools and shade-matching algorithms to replicate professional consultation at scale. Online channels concentrate growth in the United States among beauty enthusiasts comfortable with algorithm-driven purchase decisions.
- Specialty Stores:Sephora and Ulta Beauty operate dedicated beauty environments with in-store artist services and loyalty program integration. Specialty retail maintains relevance through exclusive shade launches and sampling programs.
- Department Stores:Traditional counter-based distribution relies on brand-employed makeup artists for personalized consultation. Department store foot traffic compression is forcing format reinvention toward appointment-based services.
- Drugstores:Mass-market accessibility through CVS, Walgreens, and Boots serves everyday users with limited shade range and minimal service overlay. Drugstore channels compete aggressively on unit price and promotional frequency.
Online Retail is expanding most quickly. Specialty Stores retain highest customer lifetime value.
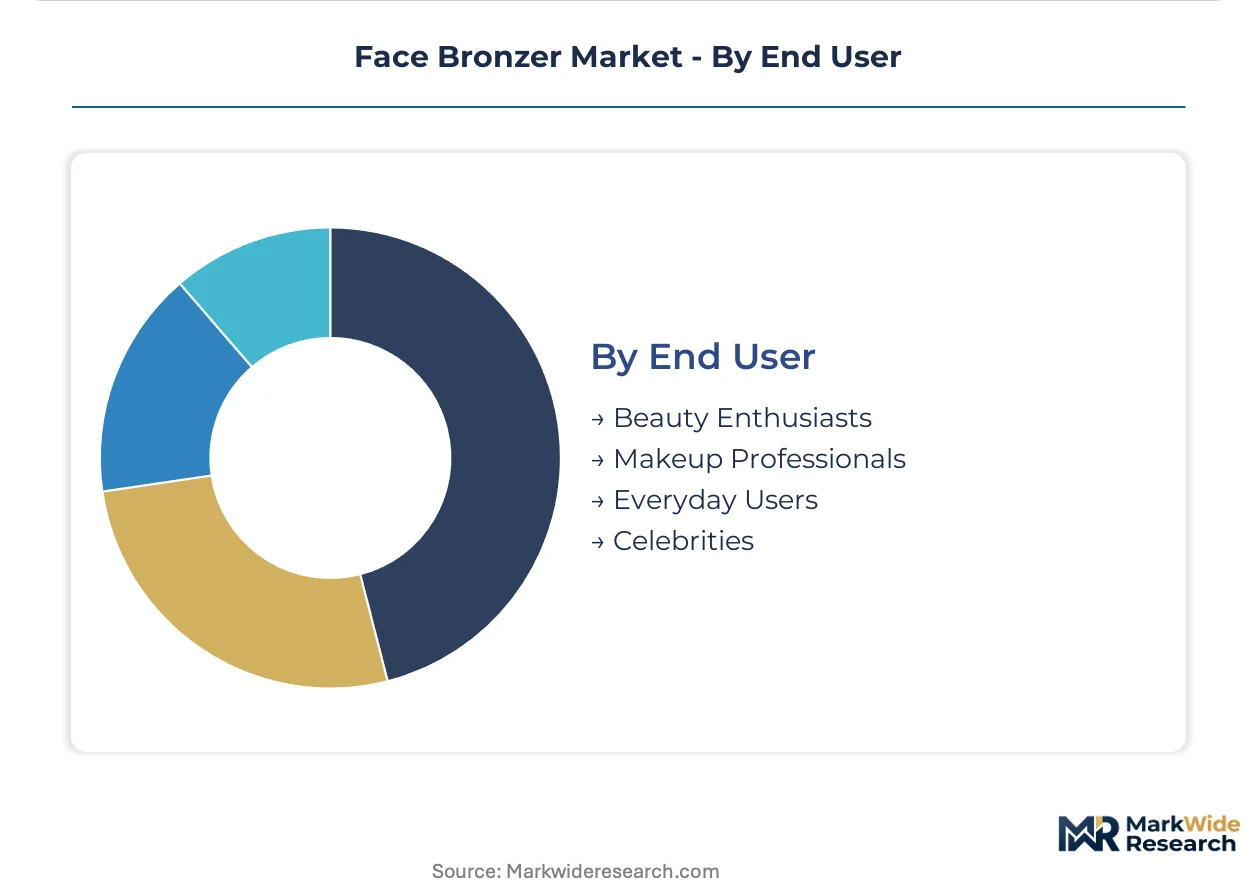
End User:
User sophistication levels dictate whether brands invest in educational content or streamlined purchase pathways.
- Beauty Enthusiasts:Highly engaged consumers actively seek ingredient transparency, sustainability credentials, and advanced application techniques through social media and subscription platforms. This segment in the United States and United Kingdom drives clean beauty positioning and pre-market buzz.
- Makeup Professionals:Licensed artists and salon technicians require professional-grade pigmentation, extensive shade ranges, and wholesale purchasing terms. Professionals validate products for downstream consumer adoption through tutorial content and editorial placement.
- Everyday Users:Occasional cosmetic consumers prioritize intuitive application and forgiving formulation over technical performance. Everyday users respond to mass-market advertising and accessible retail placement.
- Celebrities:Entertainment industry talent and influencers generate outsized visibility impact through red carpet placement and social media endorsement. Celebrity association commands premium licensing fees and exclusive product development.
Everyday Users represent largest population. Beauty Enthusiasts show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States buyers exhibit lowest price elasticity for professional-grade formulations, while mass-market segments in emerging markets compress margins through promotional intensity. Premium positioning succeeds in Western Europe through regulatory credibility, whereas accessible price points dominate volume in Latin America and Southeast Asia.
United States
Beauty enthusiasts and bridal industry professionals drive premium formulation demand through social media-validated purchasing. FDA color additive safety requirements govern labeling and pigment approval timelines. Los Angeles and New York City anchor professional makeup artist concentration, where backstage placement and editorial validation cascade into consumer market migration.
Germany
Clean beauty positioning and sustainability credentials command price premiums among ingredient-conscious consumers. REACH restrictions on nano-scale titanium dioxide force reformulation investments across powder-format portfolios. The Rhine-Ruhr industrial corridor hosts specialized pigment processing facilities adapting to ECHA compliance dossier requirements.
France
Luxury heritage brands leverage Paris-based atelier credibility to sustain prestige pricing in domestic and export markets. EU Cosmetics Regulation mandates rigorous safety assessments that elevate barriers for non-EU entrants. The Île-de-France region concentrates headquarters operations for multinational beauty conglomerates navigating Green Deal packaging mandates.
United Kingdom
Professional makeup artist channels and subscription platform engagement accelerate pro-grade product adoption. Post-Brexit regulatory divergence from EU Cosmetics Regulation notification procedures complicates synchronized launch timelines. London dominates influencer marketing agency concentration, where tutorial culture redirects consumer preference toward algorithmic shade-matching tools.
Japan
Skincare-hybrid positioning and photography-optimized finishes attract sophisticated urban consumers. METI and PMDA oversight of quasi-drug claims restricts marketing language around skin-nourishing benefits. The Kanto region surrounding Tokyo hosts specialized cosmetic chemist talent pools bridging color science and biocompatible ingredient development.
Face Bronzer Market Vendor Landscape
Prestige heritage houses and mass-market conglomerates split the market into divergent value-capture models. Consolidation concentrates among multinational portfolios with dual-channel presence across professional artist networks and retail distribution. Three archetypes dominate: vertically integrated luxury maisons, mass-market accessibility platforms, and pro-grade specialist brands. Competitive intensity manifests through exclusive shade launches and algorithmic personalization investments rather than price warfare.
Within the heritage luxury tier, Chanel and Tom Ford occupy positions sustained by atelier credibility and limited distribution scarcity. Benefit Cosmetics exemplifies the boutique-specialist archetype with concentrated North American and European footprint. L'Oréal anchors mass-market accessibility through shade range breadth and promotional frequency. These three representations illustrate how divergent channel strategies coexist without direct price competition.
| Leading Market Players |
|---|
| Benefit Cosmetics |
| MAC Cosmetics |
| Chanel |
| NARS Cosmetics |
| Bourjois |
| Estée Lauder Companies |
| Bobbi Brown Cosmetics |
| L'Oréal |
| Tom Ford |
| Others |
Supply Flow & Price Mechanics
Undercapacity in European pigment processing facilities drives supplier prioritization toward premium formulation contracts and compresses margin flexibility for mid-tier brands seeking volume discounts on titanium dioxide and iron oxide inputs.
Pricing Analysis
After-sales service revenue from virtual shade-matching subscriptions and artist certification programs now drives lifetime value more than initial product margin. Three-tier pricing structure across premium professional-grade, standard prestige, and mass-market economy levels stratifies by pigmentation intensity and algorithmic personalization access. Cost compression in powder formats is intensifying because REACH nano-scale restrictions force reformulation toward liquid and cream alternatives. Everyday users in drugstore channels exhibit highest price sensitivity, while bridal industry professionals demonstrate lowest elasticity due to photography-optimized finish requirements.
Supply Chain Analysis
Tariff exposure between China and the United States dominates raw material cost volatility for titanium dioxide and mica sourcing. Pigment processing concentrates in China, Germany, and the United States, with emulsion base production anchored in France and Italy. Formulation chemistry rests on iron oxides, titanium dioxide, and plant-derived emollients replacing mineral oil bases. Single-source vulnerability in Chinese nano-pigment processing creates timeline uncertainty for powder-format compliance. Distribution runs through professional artist networks and direct-to-consumer platforms rather than traditional department store counters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among professional makeup artist collectives and subscription platform aggregators, fragmenting individual consumer leverage while consolidating institutional procurement scale.
For Market Incumbents: Pre-empt clean beauty certification requirements in California and New York by accelerating ingredient transparency protocols ahead of state-level mandates. Secure captive supply of REACH-compliant pigments through backward integration into specialized European processing facilities. Channel control through proprietary algorithmic shade-matching tools defends against platform commoditization threats from marketplace aggregators. For New Entrants and Emerging Players: Build out men's grooming verticals in the United States and United Kingdom where neutral-tone contouring products remain underpenetrated. Target bridal industry service providers seeking photography-optimized cream formulations with lower professional education requirements than legacy pro-grade portfolios. Direct-to-consumer launch through TikTok Shop and Instagram Shopping reduces customer acquisition costs versus specialty retail entry. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across liquid and cream formulation segments due to skincare-hybrid R&D and sustainable packaging compliance investments. Long-term viability favors brands with dual-channel presence across professional artist validation networks and scalable direct-to-consumer infrastructure. Acquisition target archetype: mid-cap specialists with pre-established EU Cosmetics Regulation dossiers and refillable compact technology. Signal to watch: ECHA pigment restriction expansion beyond nano-scale titanium dioxide into additional iron oxide chemistries.| Strategic Initiative | Industry Significance |
|---|---|
| Clean Beauty Certification Investment | California and New York disclosure mandates reward pre-compliant brands with first-mover shelf placement. |
| Professional Artist Network Expansion | Licensed makeup artist validation cascades from bridal editorial placement into mass-market consumer adoption. |
| Refillable Compact Development | EU Green Deal packaging mandates create partnership urgency with mono-material sustainable packaging suppliers. |
| Virtual Try-On Algorithm Deployment | Shade-matching technology reduces return rates and concentrates customer relationships with algorithm-owning brands. |
| Men's Grooming Product Line Launch | Neutral-tone bronzing for subtle contouring addresses whitespace in United States and United Kingdom male segments. |
Methodological Framework
A standing panel of cosmetic chemists, professional makeup artists, bridal service coordinators, specialty retail buyers, and clean beauty formulators provided ongoing calibration across primary interview cycles and secondary source validation. FDA color additive filings, EU Cosmetics Regulation notification databases, ECHA REACH restriction updates, and customs trade data on pigment imports supplied quantitative anchors. Bottom-up demand modeling across product formats triangulated against top-down manufacturer capacity assessments.
Scenario-bracketing around regulatory acceleration and supply disruption cases bounded the projection horizon. Segmentation dimensions included product type, application channel, distribution format, and end-user sophistication tier. CAGRs derived from fitted growth curves incorporating professional artist network expansion rates and virtual consultation platform adoption patterns. Pigment cost trajectories and clean beauty legislative timelines served as industry-specific forecast inputs.
Stress conditions across ECHA pigment restriction scope, Chinese processing facility utilization, and California disclosure mandate timing were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on bridal industry demand stability and algorithmic personalization technology diffusion. Material shifts in REACH nano-scale classification scope or state-level clean beauty enforcement intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Glow in the Dark Cosmetics Market
Cosmetics & Skincare
Myanmar Skin Care Products Market
Cosmetics & Skincare
Cosmetics Private Label and Contract Manufacturing Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Natural Baby Skin Care Products Market
Cosmetics & Skincare
Chile Cosmetics Products Market
Cosmetics & Skincare
Israel Cosmetics Market
Cosmetics & Skincare
Baby Skincare Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Magnetic Fake Eyelashes Market
Cosmetics & Skincare
UK Eyelash Serum Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Natural Cosmetic Color Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market