
 Natural and Organic Lipstick Market | 2026-2036
Natural and Organic Lipstick Market Size, Share, and Industry Trends Forecast 2026-2036
Natural and Organic Lipstick Market Outlook
Petroleum-derived colorants is pivoting toward mineral and plant-based alternatives as brands reformulate to meet clean-label expectations. ILIA Beauty leverages its hybrid skincare-color positioning to command premium shelf placement in specialty retail. RMS Beauty anchors its portfolio around raw, food-grade ingredient protocols that simplify supply chain verification. EcoLuxe Beauty competes through vertically controlled sourcing from certified organic farms.
Natural and organic lipstick denotes a cosmetic product formulated without synthetic dyes, parabens, or petrochemicals, relying instead on beeswax, shea butter, and plant-derived pigments to deliver color payoff while meeting biocompatibility standards. The formulation dimension spans matte, glossy, satin, and sheer finishes, with matte variants commanding the deepest margin pools due to higher pigment loading and perceived longevity. Satin formulations represent the fastest-growing segment as consumers seek compromise textures that bridge comfort and coverage. The customer type segmentation reveals eco-conscious consumers as the most price-inelastic cohort, willing to absorb premiums for verified organic certification.
The FDA governs color additive safety and labeling accuracy in the United States, while the EU Green Deal and REACH framework restrict microplastic-containing glitter and certain synthetic preservatives across member states. These layered standards force manufacturers to maintain dual formulation tracks or unify around the stricter European baseline. Stakeholders must monitor evolving ECHA substance restrictions and state-level clean beauty legislation to anticipate reformulation costs and compliance timelines.
Market Dynamics
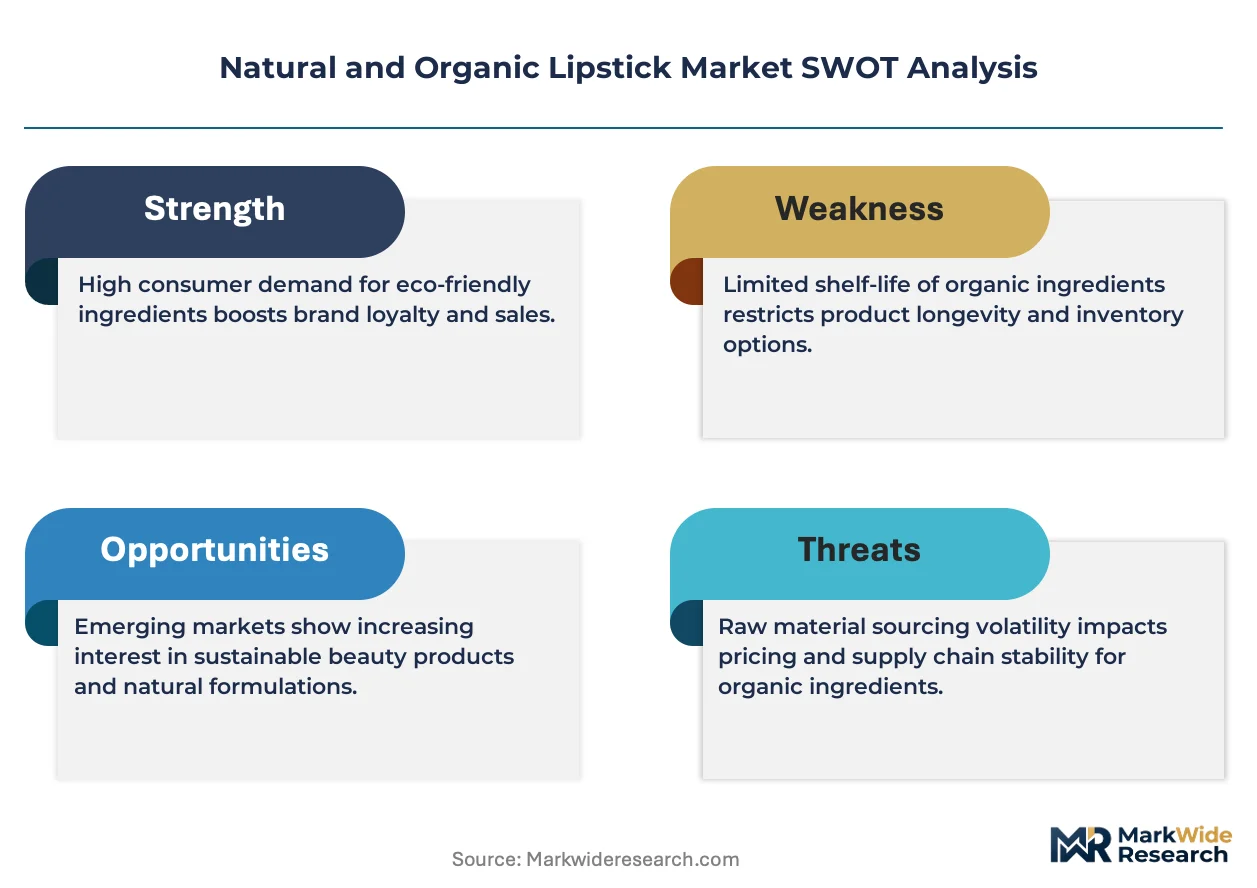
Clean beauty certification protocols are forcing simultaneous reformulation across color cosmetic portfolios as retailers demand third-party organic verification before granting shelf access.
Growth Catalysts
- EU REACH framework:The European Chemicals Agency's expanding substance restrictions filter out synthetic preservatives and microplastic glitter, accelerating mineral and plant-based pigment adoption across formulation labs.
- Professional salon channels:Makeup artists in service environments now require clean beauty credentials as non-negotiable entry tickets, pulling volume through certified organic supply chains.
- Berlin-Hamburg cluster:Dense concentrations of indie beauty retailers and formulation laboratories in these German cities concentrate demand for verified organic raw materials.
Market Restraints
- Beeswax supply volatility:Climate stress on apiary operations in Mediterranean producing regions creates input cost instability for base formulations.
- Pigment loading limitations:Plant-derived colorants deliver lower saturation per unit volume than petroleum-derived alternatives, constraining matte finish performance.
- Dual-track compliance costs:Manufacturers maintaining separate formulations for EU REACH baseline and less restrictive jurisdictions face duplicated testing and documentation overhead.
Strategic Opportunities
- Satin texture expansion:The fastest-growing finish segment bridges comfort and coverage demands, opening formulation white space between matte dominance and sheer minimalism.
- India domestic market:Underpenetrated demand for certified organic color cosmetics among urban professional women creates first-mover positioning potential.
- Skincare-color hybrid protocols:Convergence of cosmetic pigment technology with biocompatible skincare actives enables premium positioning in specialty retail.
Industry Challenges
- Eco-conscious consumer verification:The most price-inelastic buyer cohort demands transparent supply chain documentation that strains legacy procurement systems.
- Organic certification timelines:Multi-year farm conversion periods and batch testing protocols delay new product launches and limit formulation agility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural and Organic Lipstick Market |
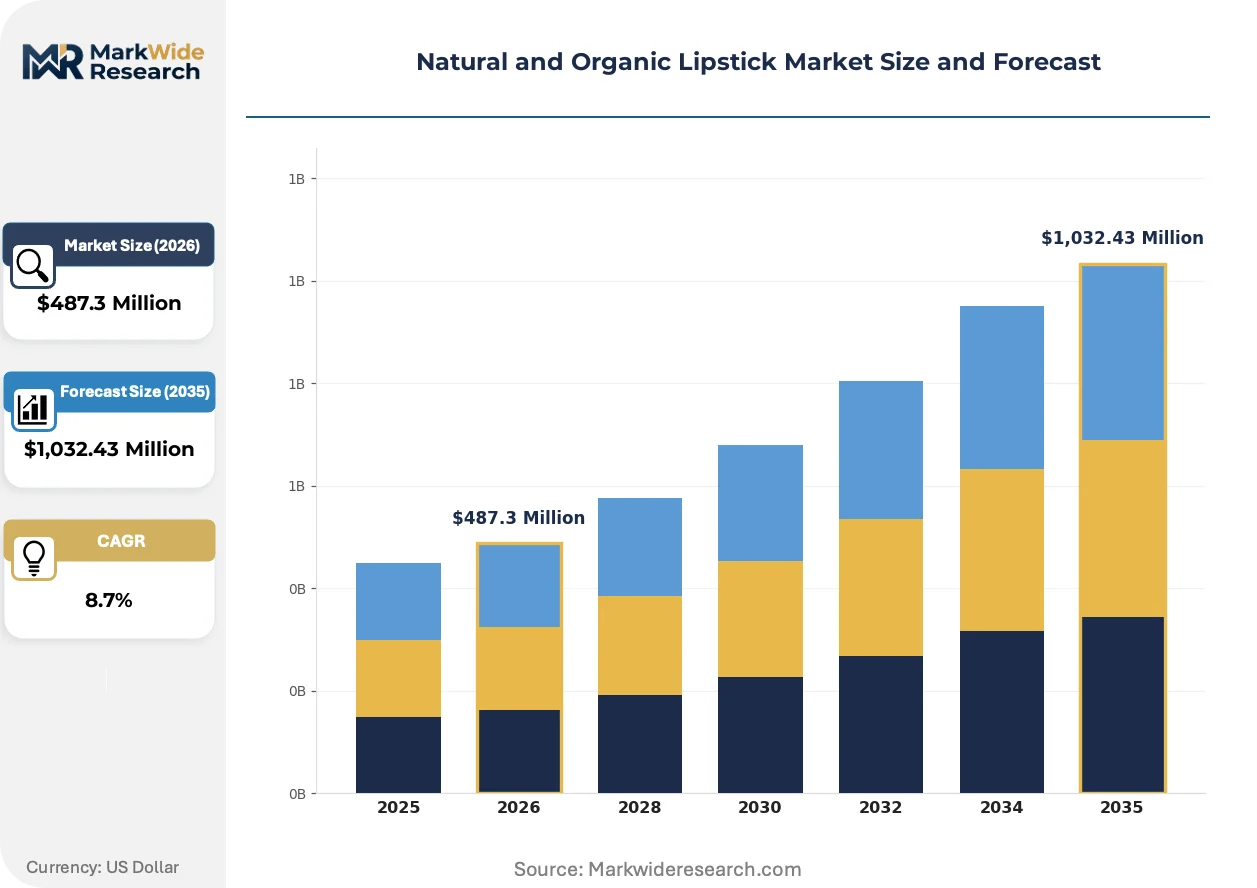
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ingredient Type: Beeswax, Shea Butter, Plant Oils, Natural Pigments Formulation: Matte, Glossy, Satin, Sheer Packaging Type: Recyclable Tubes, Glass Jars, Biodegradable Containers, Eco-Friendly Packs Customer Type: Millennials, Eco-Conscious Consumers, Beauty Enthusiasts, Health-Conscious Users |
| Companies Covered | BioBeauty Essentials, ILIA Beauty, EcoLuxe Beauty, RMS Beauty, MG Naturals, PureCrave Cosmetics, Liht Organics, INIKA Organic, GreenGlam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural and Organic Lipstick Market Strategic Shifts
Raw ingredient protocols and hybrid category positioning are compressing traditional boundaries between color cosmetics and skincare, reshaping how brands structure R&D investment and retail partnerships.
Biomimetic pigment technology is integrating food-grade extraction methods from agricultural byproducts to replace synthetic colorants. Indie formulation labs in Germany and France are adopting these protocols fastest. The technology is integrating raw material sourcing directly into brand identity, collapsing the distinction between supply chain story and product marketing.
ECHA substance restriction updates under REACH are systematically eliminating microplastic-containing glitter and certain phenoxyethanol preservatives from permitted formulations. Cosmetic manufacturers serving EU member states must reformulate existing SKUs or withdraw from distribution. Satin and sheer finish categories face compressed timelines as these textures historically relied on restricted texture agents.
Certification-driven purchasing now dominates professional channel procurement, with salon buyers requiring USDA Organic or COSMOS verification before establishing vendor relationships. Traditional distributor networks lose ground to direct brand partnerships that guarantee documentation transparency. Germany and France exhibit the most advanced procurement sophistication, with professional makeup artists leading consumer education on ingredient standards.
Natural and Organic Lipstick Market Segmentation
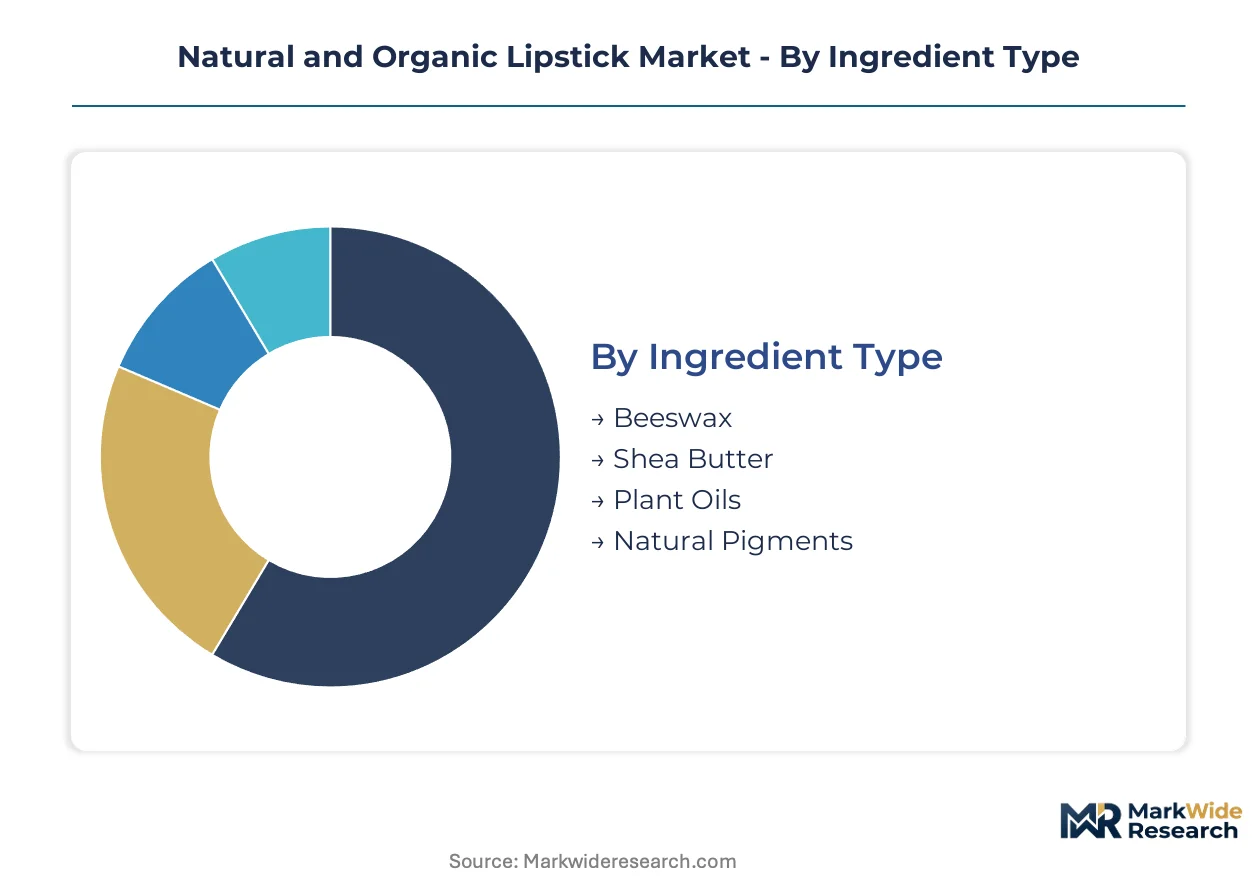
Ingredient provenance and finish texture drive purchasing decisions in natural and organic lipstick markets, with certification status and packaging sustainability acting as secondary filters. Manufacturers must align formulation investments with divergent consumer priorities across professional service channels and direct-to-consumer retail.
Ingredient Type:
Base material selection spans the customization spectrum from commodity agricultural inputs to vertically controlled specialty sourcing with full traceability documentation.
- Beeswax:Serves as the structural backbone for stick formulations, providing thermal stability and emollient texture. Apiary operations in Mediterranean producing regions face climate volatility that transmits directly to input cost structures for German and French formulation labs.
- Shea Butter:Delivers moisturization and creamy application properties through triglyceride-rich nut extracts. Demand concentrates in premium satin finish lines where comfort attributes justify higher raw material expenditure against petroleum-derived alternatives.
- Plant Oils:Jojoba, castor, and coconut oils function as carriers for pigment dispersion and skin-conditioning benefits.
- Natural Pigments:Mineral oxides and plant-derived colorants from agricultural byproducts replace synthetic dyes under REACH-compliant protocols.
Leading the category by volume: Beeswax. Expanding most quickly: Natural Pigments.
Formulation:
Finish texture determines margin architecture and manufacturing complexity, with higher pigment loads commanding premium positioning.
- Matte:Maximum pigment concentration creates opaque coverage with extended wear properties. Professional makeup artists in Berlin and Hamburg salon channels specify matte formulations for editorial work, though plant-derived colorant saturation limits constrain performance parity with synthetic alternatives.
- Satin:Balanced oil-to-pigment ratio bridges comfort and coverage demands. This segment gains share fastest as consumers reject drying matte textures while seeking more substance than sheer finishes provide.
- Glossy:High oil content with light pigment loading emphasizes hydration and reflective finish.
- Sheer:Minimal pigment concentration offers tint-level color with maximum emollient feel.
Generating deepest margins: Matte. Steepest expansion trajectory: Satin.
Packaging Type:
Material choices reflect divergent sustainability priorities across consumer segments and retail channel requirements.
- Recyclable Tubes:Aluminum and post-consumer recycled plastic formats dominate mass-market distribution. Indie beauty retailers in Germany increasingly mandate recyclable tube specifications as baseline shelf access conditions.
- Biodegradable Containers:Mushroom mycelium and plant-fiber molded formats address zero-waste consumer preferences. Supply concentration in specialized European packaging manufacturers limits scale economics.
- Glass Jars:Premium positioning through weight and perceived durability, though fragility constrains travel and professional kit use.
- Eco-Friendly Packs:Refillable systems and zero-plastic alternatives command highest certification compliance documentation.
Highest volume throughput: Recyclable Tubes. Gaining share fastest: Biodegradable Containers.
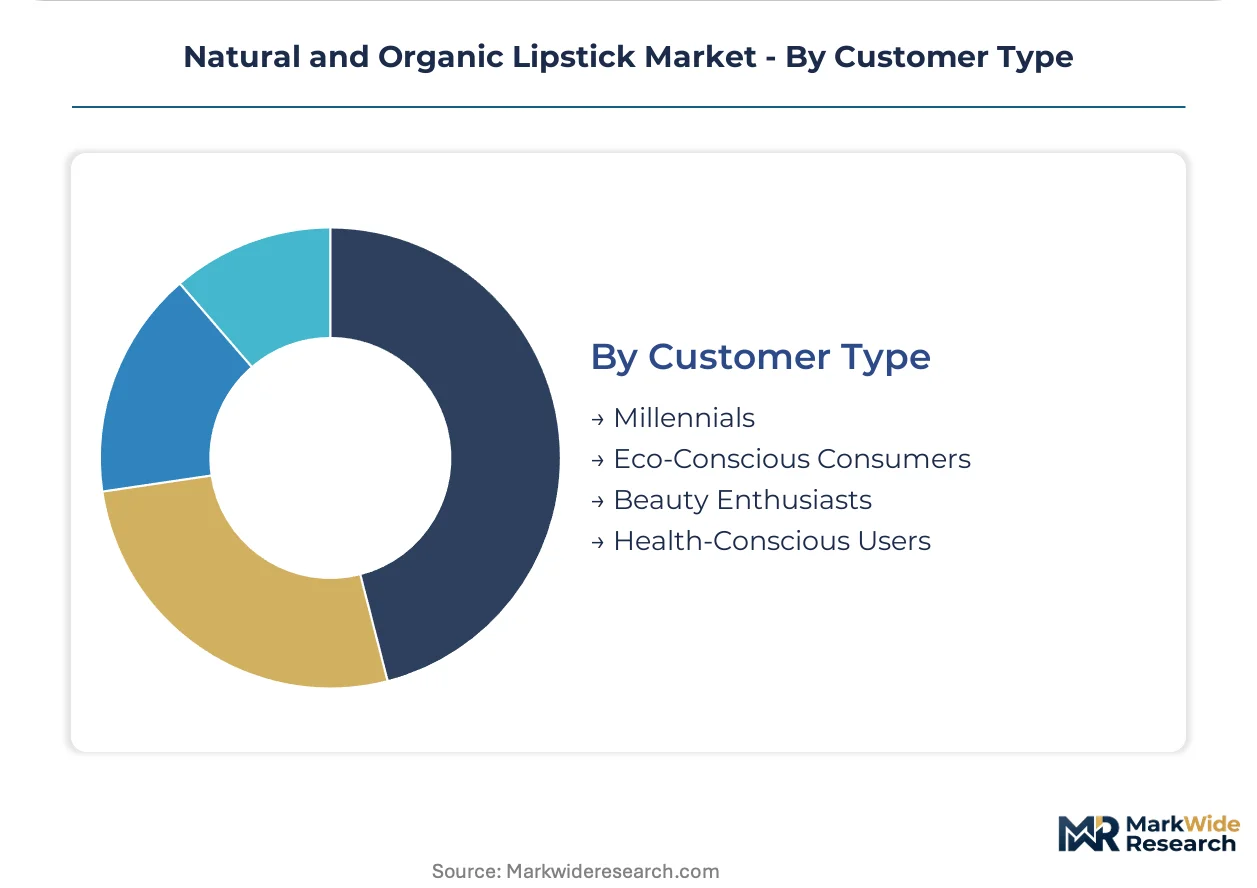
Customer Type:
Purchasing behavior varies sharply by price elasticity and information intensity around supply chain verification.
- Eco-Conscious Consumers:Most price-inelastic cohort demanding USDA Organic or COSMOS certification with transparent farm-to-lip documentation. This segment absorbs substantial premiums and drives professional channel procurement standards in France and Germany.
- Millennials:Digital-native buyers prioritizing hybrid skincare-color positioning and social media-native brand discovery. Urban professional women in underpenetrated markets represent first-mover expansion opportunity.
- Beauty Enthusiasts:Trend-responsive purchasers rotating across finish textures and seasonal color collections.
- Health-Conscious Users:Ingredient-avoidance motivated buyers seeking paraben-free and petrochemical-free formulations for sensitization concerns.
Driving premium pricing power: Eco-Conscious Consumers. Expanding addressable base fastest: Millennials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional makeup artists in Germany and France now require certified organic credentials as baseline procurement standards, concentrating demand in Western European salon channels and indie beauty retail clusters.
United States
Clean beauty legislation in California and New York is tightening disclosure requirements for synthetic fragrance components. The FDA governs color additive safety and labeling accuracy nationwide. Brooklyn and Los Angeles host dense concentrations of direct-to-consumer brands and formulation labs driving hybrid skincare-color innovation.
Germany
Berlin and Hamburg anchor the densest European clusters of indie beauty retailers and organic formulation laboratories. ECHA oversight under REACH systematically restricts microplastic-containing glitter and phenoxyethanol preservatives. Professional makeup artists in these cities lead consumer education on ingredient verification standards.
France
Paris-based luxury houses and indie labs are accelerating mineral and plant-based pigment adoption ahead of EU Green Deal timelines. ANSM enforces cosmetic ingredient safety protocols alongside REACH baseline requirements. The Île-de-France region concentrates premium organic certification expertise and sustainable packaging innovation.
India
Urban professional women in Mumbai and Delhi represent underpenetrated demand for certified organic color cosmetics. BIS standards for cosmetic safety are converging with international organic certification benchmarks. Domestic indie brands are establishing direct farm partnerships in Maharashtra and Karnataka to secure raw material traceability.
United Kingdom
London's specialty retail sector is mandating third-party organic verification before granting shelf access to emerging brands. The UK's post-BREXIT regulatory framework maintains REACH-aligned substance restrictions through retained EU law. Indie formulation labs in Greater Manchester and Bristol are developing biodegradable packaging alternatives for export markets.
Natural and Organic Lipstick Market Competitive Environment
Certification-driven portfolio diversification dominates the current landscape as brands reformulate entire color cosmetic lines to meet retailer organic verification requirements. The vendor base spans vertically controlled specialists, hybrid skincare-color innovators, and commodity organic private-label suppliers. Three archetypes define positioning: raw-ingredient-protocol purists, vertically integrated farm-to-lip operators, and technology-forward hybrid formulators. Portfolio diversification and strategic retail partnerships constitute the dominant competitive moves, with direct brand relationships displacing traditional distributor networks in professional channels.
Within the raw-ingredient-protocol tier, RMS Beauty exemplifies food-grade sourcing standards that simplify supply chain verification. ILIA Beauty anchors the hybrid skincare-color positioning that commands premium shelf placement in specialty retail. EcoLuxe Beauty represents vertically controlled sourcing from certified organic farms, collapsing supply chain narrative into core brand identity.
| Leading Market Players |
|---|
| BioBeauty Essentials |
| ILIA Beauty |
| EcoLuxe Beauty |
| RMS Beauty |
| MG Naturals |
| PureCrave Cosmetics |
| Liht Organics |
| INIKA Organic |
| GreenGlam |
| Others |
Value Chain & Pricing Dynamics
Family-owned apiary cooperatives in Mediterranean producing regions anchor raw material ownership patterns, transmitting climate-driven cost volatility directly into German and French formulation labs while forcing tiered pricing discipline across certification grades.
Pricing Analysis
Volume concentration in recyclable tube formats competes against margin depth in matte finish lines, where higher pigment loading commands premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates COSMOS-certified organic from natural-label and conventional alternatives. Pricing pressure stems from beeswax supply instability as climate stress hits Mediterranean apiary operations. Eco-conscious consumers absorb the steepest premiums with minimal elasticity, while millennials in underpenetrated markets exhibit moderate sensitivity to certification markups.
Supply Chain Analysis
Certification gating through USDA Organic and COSMOS protocols filters supplier eligibility before raw material procurement contracts execute. Sourcing concentrates in Germany, France, and India, with formulation labs in Berlin and Hamburg drawing from certified organic farms in Maharashtra and Karnataka. Beeswax, shea butter, and mineral oxide pigments constitute core input dependencies. Single-source vulnerability runs through Mediterranean apiary networks exposed to climate volatility. Distribution runs through indie beauty retailers and direct brand partnerships displacing traditional wholesale networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Organic certification timelines function as the binding capacity constraint, with multi-year farm conversion periods propping pricing power for verified supply holders.
For Market Incumbents: Deploy backward integration into certified organic farm partnerships to lock apiary and shea cooperative capacity before competitors secure contracts. Accelerate satin finish R&D pipelines to capture the fastest-expanding texture segment. Channel control through direct salon partnerships in Berlin and Hamburg defends against indie brand encroachment.
For New Entrants and Emerging Players: Direct-to-consumer platforms via Instagram-native discovery and subscription boxes offer lowest-friction entry into millennial segments in Mumbai and Delhi. Target underpenetrated urban professional women in India with hybrid skincare-color positioning. White-label manufacturing partnerships with German formulation labs bypass multi-year certification delays.
For Investors and Strategic Acquirers: Distressed-cycle entries favor vertically controlled mid-caps with captive organic farm networks in France and Germany over asset-light brand marketers. Long-term viability hinges on certification durability rather than trend velocity. Watch ECHA substance restriction announcements as inflection triggers for reformulation cost spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Certified Organic Farms | Captive supply of beeswax and shea butter secures margin stability against climate volatility. |
| Satin Finish Line Expansion | Fastest-growing texture segment bridges comfort demands with coverage performance in professional channels. |
| Direct Salon Partnership Programs | Bypasses distributor networks to guarantee documentation transparency for makeup artist procurement standards. |
| Biodegradable Packaging Transition | Addresses zero-waste consumer preferences concentrated in German indie retail clusters. |
| Hybrid Skincare-Color R&D Investment | Convergence with biocompatible actives commands premium shelf placement in specialty retail. |
Study Parameters
Trade publications, customs records, and ECHA regulatory filings formed the secondary backbone, cross-referenced with primary interviews across formulation lab directors, indie beauty retail buyers, professional makeup artists, and organic certification auditors. Bottom-up SKU-level volume data triangulated against top-down category spend estimates from retail audit databases.
Historical trendline analysis tracked ingredient cost movements and finish texture adoption curves across the projection horizon. Segmentation dimensions modeled include ingredient type, formulation finish, packaging material, and customer archetype. CAGRs derived from regression against certification penetration rates and salon channel expansion trajectories, with REACH compliance timelines and farm conversion periods as industry-specific forecast inputs.
The model holds under stable ECHA substance restriction schedules; deviation in accelerated phenoxyethanol or microplastic glitter bans would shift reformulation cost assumptions. Forecasts reflect documented assumptions around certification timeline continuity and apiary yield stability. A model refresh is warranted upon material change in EU Green Deal implementation pace or BIS standard convergence in India.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Philippines Skin Care Products Market
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
Sun Care Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
Mascara Applicators Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Beauty Sheet Mask Market
Cosmetics & Skincare
Pillow Spray Market
Cosmetics & Skincare
Face Wash Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Tinted Cosmetics Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Anti-Fatigue Cosmetics Market
Cosmetics & Skincare
Organic Color Cosmetics Products Market
Cosmetics & Skincare
Cosmetic Mirror Market