
 Makeup Remover Market | 2026-2036
Makeup Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Makeup Remover Market Analysis
ISO 22716 Good Manufacturing Practices certification is redrawing competitive barriers for cosmetic manufacturers seeking retail shelf access in regulated channels. L'Oréal leverages its integrated R&D network to sustain formulation leadership across micellar and oil-based platforms. Estée Lauder anchors its prestige positioning through dermatologist-tested claims and controlled distribution. Shiseido competes by emphasizing Japanese botanical extracts in its remover portfolio, targeting ingredient-conscious consumers in Asian markets.
Makeup remover denotes a cosmetic formulation engineered to dissolve or emulsify cosmetic pigments, waxes, and silicones from skin surfaces, typically incorporating surfactants, emollients, and solubilizers at pH-balanced concentrations between 4.5 and 6.5 to prevent barrier disruption. Its primary commercial purpose centers on enabling complete facial cleansing without mechanical abrasion, supporting subsequent skincare absorption and reducing comedogenic residue. Liquid formats lead volume due to their compatibility with cotton pad dispensing and pump packaging, while balm segments capture premium margin pools through concentrated, travel-friendly formats that command higher per-gram pricing. Wipes face structural pressure from single-use plastic restrictions, redirecting R&D investment toward biodegradable substrate alternatives.
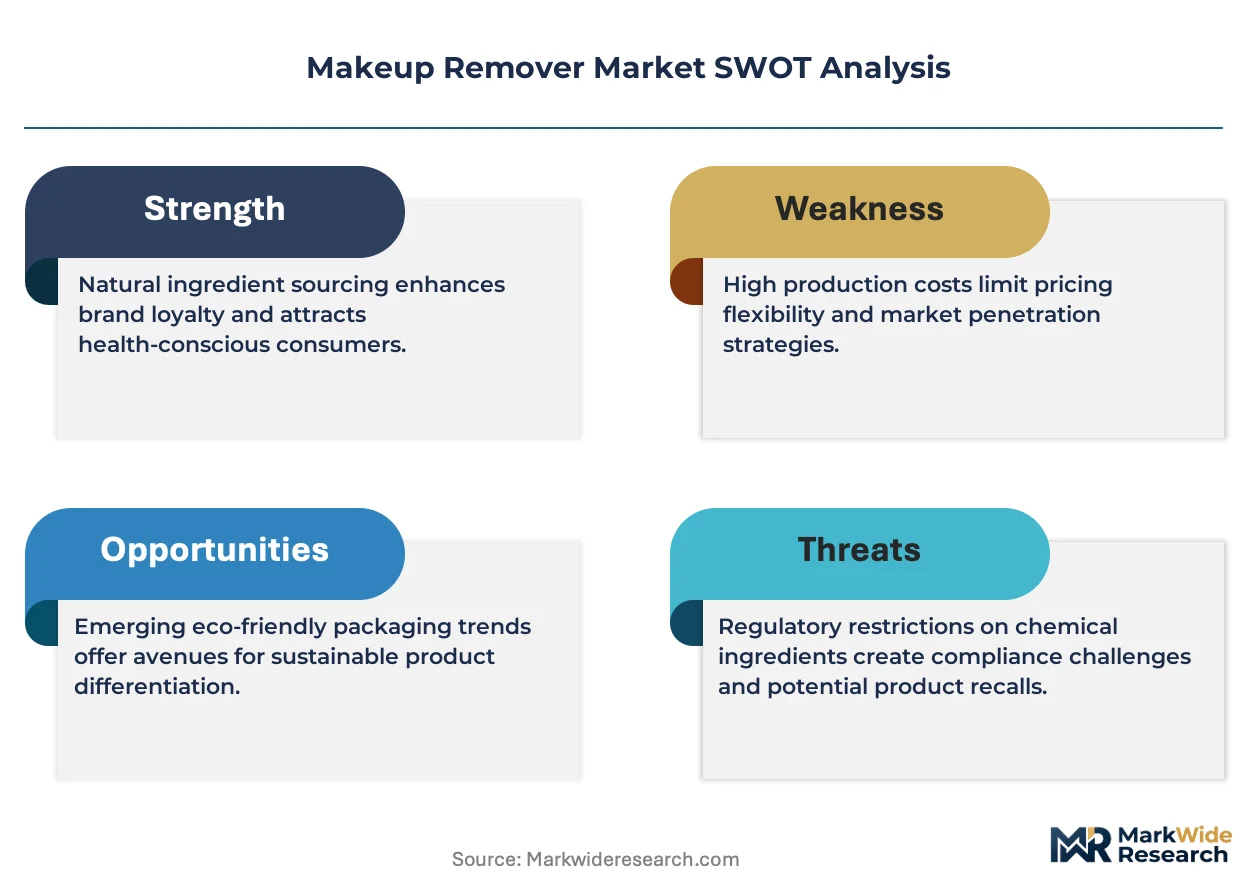
FDA cosmetic labeling requirements under the Modernization of Cosmetics Regulation Act and EU REACH chemical safety frameworks are elevating compliance costs for ingredient transparency and safety substantiation. ECHA's restricted substance lists are directly shaping surfactant selection, accelerating substitution of PEG-based emulsifiers with sugar-derived alternatives. China's NMPA filing requirements for imported cosmetics add a third regulatory layer for brands seeking cross-border e-commerce access. Stakeholders must monitor evolving state-level packaging mandates in California and New York, where extended producer responsibility bills threaten to fragment compliance obligations across the United States.
Market Dynamics
Professional salon chains and spa operators are consolidating procurement volumes, shifting supplier power toward bulk-format manufacturers capable of ISO 22716 certification and REACH-compliant surfactant documentation.
Growth Catalysts
- REACH chemical safety reformulation:EU ECHA restricted substance lists are accelerating plant-derived surfactant adoption, opening premium positioning for compliant suppliers.
- South Korean cleansing ritual anchoring:Multi-step skincare routines in Seoul and Busan sustain category volume for oil-based and micellar formats.
- Bulk institutional procurement:Spa chains in Dubai and Singapore are standardizing remover protocols, driving recurring high-volume contracts.
Market Restraints
- Biodegradable substrate cost inflation:Wipe manufacturers face 15-25% raw material premiums switching from polyester to bamboo-cellulose blends.
- Chinese NMPA filing complexity:Cross-border e-commerce entrants face 12-18 month approval timelines for imported cosmetic filings.
- Waterless balm substitution pressure:Concentrated solid formats threaten liquid volume in travel retail and sustainability-conscious segments.
Strategic Opportunities
- India's emerging organized retail:Reliance Retail and Nykaa expansion creates shelf access for dermatologist-tested remover lines.
- California extended producer responsibility:State-level packaging mandates favor early movers with refillable pump systems and take-back infrastructure.
- Biotech-fermented emollient convergence:Sugar-derived squalane and microbiome-friendly preservatives enable clean-label premium tiers.
Industry Challenges
- Formulation chemist scarcity:Qualified professionals capable of pH-balanced, preservative-free stability testing command premium compensation.
- Dual certification timeline compression:Simultaneous ISO 22716 and COSMOS organic audits strain mid-tier manufacturer resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Makeup Remover Market |
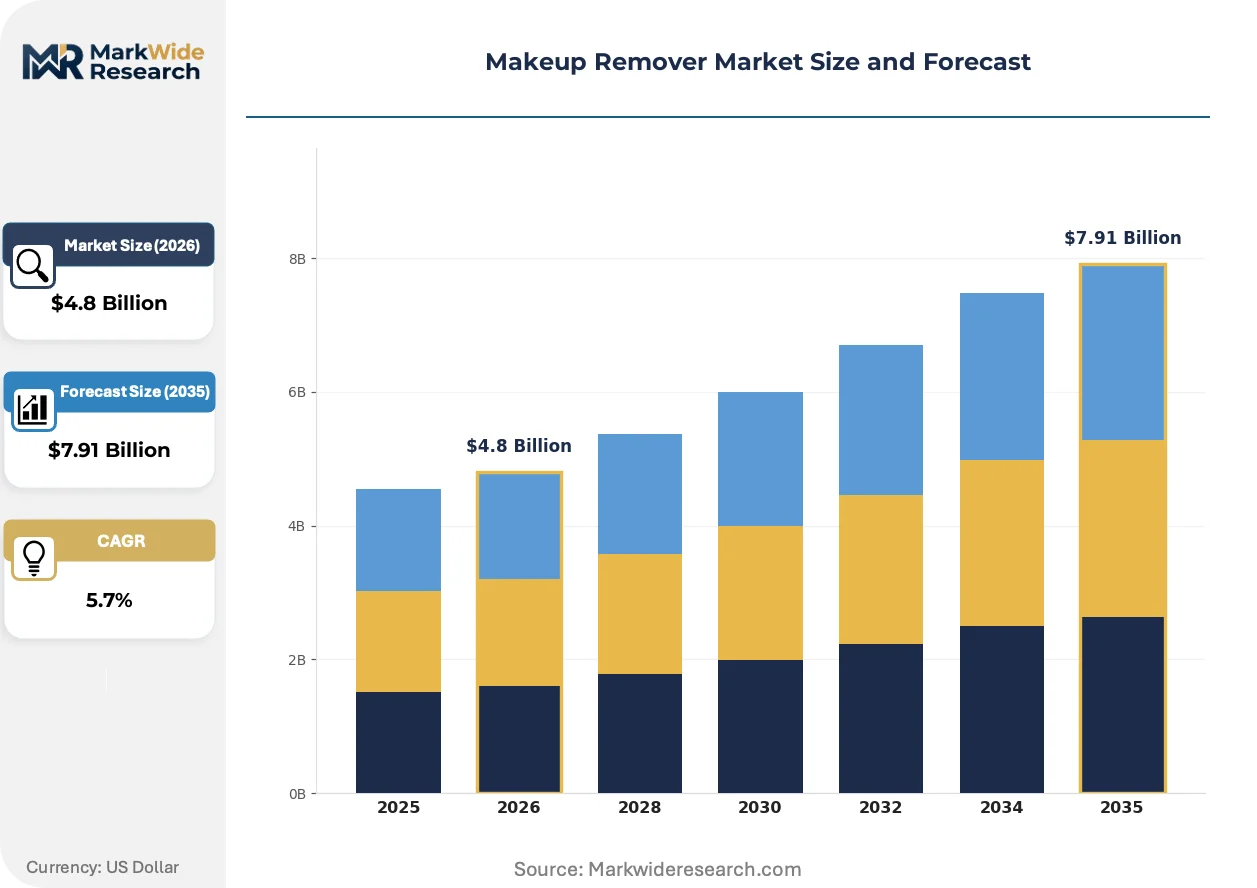
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wipes, Liquid, Balm, Oil Ingredient: Micellar Water, Coconut Oil, Aloe Vera, Chamomile Packaging Type: Bottle, Tub, Sachet, Pump End User: Individual Consumers, Salons, Spas, Retailers |
| Companies Covered | Estée Lauder, Shiseido, L'Oréal, Beiersdorf, Kao Corporation, Procter & Gamble, Johnson & Johnson, LVMH Moët Hennessy Louis Vuitton, Unilever, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Makeup Remover Market Emerging Trajectories
Biotechnology and regulatory chemistry are converging to redefine formulation architectures, with fermentation-derived ingredients and packaging compliance emerging as primary vectors of competitive differentiation.
Micellar technology is miniaturizing surfactant micelle structures to sub-20 nanometer diameters, enabling deeper pigment dissolution without barrier disruption. Prestige dermatology clinics in Seoul and Tokyo are adopting these advanced formulations for pre-treatment skin preparation. The structural consequence is compressing performance gaps between professional-grade and retail-accessible removers.
ECHA's 2023 update to restricted substance candidate lists is forcing immediate PEG-based emulsifier phase-outs across EU-manufactured lines. Formulators in Germany and France are substituting with alkyl polyglucosides and sugar esters at accelerated R&D cycles. Balm and oil segments face the steepest reformulation costs due to higher emulsifier loading requirements.
Subscription-based replenishment models are displacing traditional retail replenishment cycles for liquid removers. Direct-to-consumer platforms in New York and London are bundling remover with cotton pad and toner assortments, capturing recurring revenue streams. This pattern is most visible among millennial and Gen-Z demographics in North American urban markets.
Makeup Remover Market Segmentation
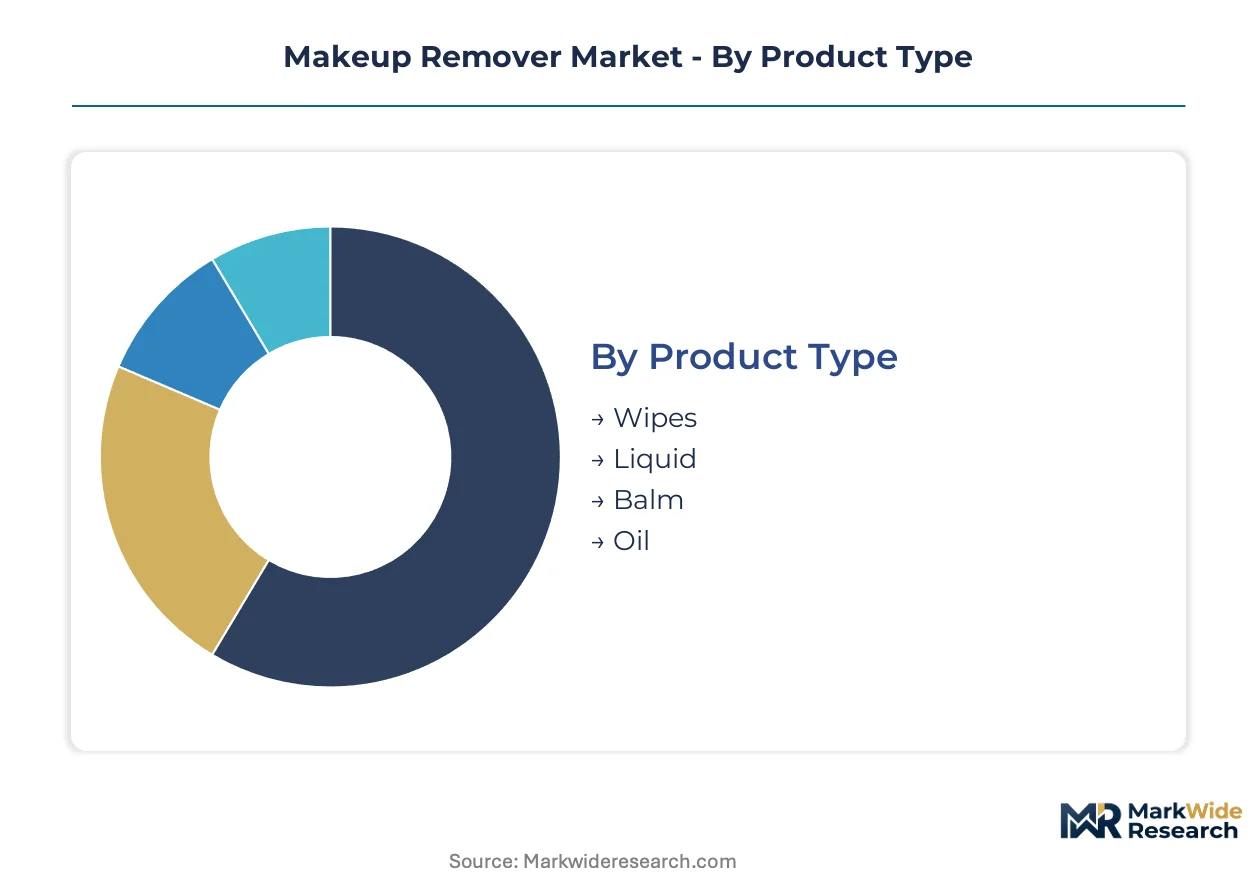
Segmentation in makeup remover markets reveals how formulation chemistry, dispensing convenience, and institutional procurement patterns create divergent margin pools. Manufacturers optimize R&D allocation by mapping these divides against regulatory compliance costs and channel access requirements.
Product Type:
Liquid formats dominate domestic consumption across developed markets, while balm and oil segments concentrate in export-oriented premium channels serving Asian skincare rituals.
- Liquid:Micellar and aqueous solutions incorporate sub-20 nanometer surfactant micelles for pigment dissolution without mechanical abrasion. Demand clusters in Seoul and Tokyo households practicing double-cleansing routines, reinforced by pump-dispensing compatibility and cotton pad rituals.
- Balm:Concentrated solid emulsions combine wax esters with oil-soluble surfactants in travel-friendly formats. Premium positioning in Dubai and Singapore duty-free channels commands elevated per-gram pricing, though reformulation costs spike under ECHA's PEG emulsifier restrictions.
- Wipes:Pre-saturated substrate formats face structural pressure from EU single-use plastic directives and California extended producer responsibility frameworks.
- Oil:Anhydrous or low-water formulations leverage lipophilic solubilizers for heavy pigment and silicone removal, standard in South Korean multi-step cleansing protocols.
Liquid commands the established base. The steepest expansion runs through balm.
Ingredient:
Plant-derived actives attract premium pricing in export markets, while synthetic surfactant bases retain cost advantages for mass-market domestic production.
- Micellar Water:Dilute surfactant solutions with micelle structures that encapsulate cosmetic debris without rinsing. Professional salons in Paris and New York standardize this format for pre-treatment skin preparation, driving bulk procurement contracts.
- Coconut Oil:Medium-chain triglyceride base with inherent emollient properties and consumer familiarity in natural-positioned lines. Indonesian and Philippine supply chains anchor raw material sourcing, though oxidative stability challenges require antioxidant packaging.
- Aloe Vera:Mucopolysaccharide-rich botanical extract marketed for post-removal soothing claims, concentrated in California-formulated clean beauty lines.
- Chamomile:Bisabolol-containing flower extract targeting sensitive-skin positioning, prevalent in German and Swiss dermatologist-tested portfolios.
Micellar water anchors volume leadership. Coconut oil climbs the fastest as natural-positioned lines expand shelf presence.
Packaging Type:
Refill-compatible formats concentrate in European sustainability-mandated channels, while single-use sachets dominate price-sensitive emerging market entry.
- Bottle:Standard PET or glass containers with screw-cap or flip-top closures, optimized for liquid format stability and retail shelf visibility. German and French manufacturers prioritize post-consumer recycled content ratios to satisfy EU Green Deal packaging requirements.
- Pump:Metered-dispensing systems reducing oxidation exposure and enabling precise dosage control. Premium adoption in Japanese and South Korean organized retail supports toner-bundle subscription models.
- Tub:Wide-mouth containers accommodating balm and solid oil formats with finger-access application, prevalent in travel retail sizing.
- Sachet:Single-serve foil or laminate pouches for sampling and hospitality amenity channels, concentrated in Indian and Southeast Asian market entry strategies.
Bottle formats command the established base. Pump systems gain share fastest through subscription commerce expansion.
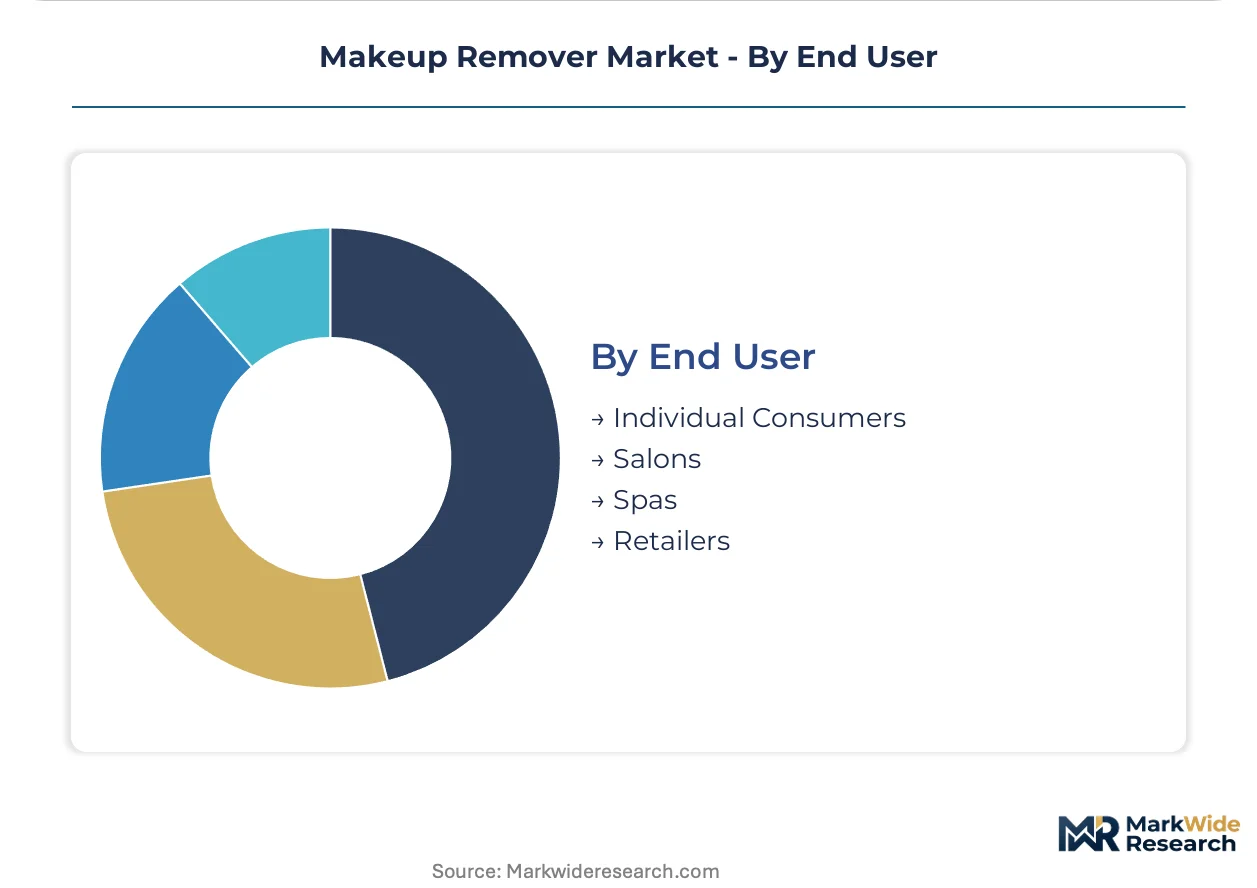
End User:
Institutional procurement by service providers operates on ISO 22716 certification requirements, while individual consumption patterns diverge by cleansing ritual complexity.
- Individual Consumers:Household purchasers selecting formats based on skin type, routine steps, and price tier. Urban millennials in London and New York demonstrate highest subscription-model adoption for bundled remover-cotton-toner assortments.
- Salons:Professional service providers requiring bulk-format supply with consistent batch documentation and REACH-compliant surfactant certification. Dubai and Singapore spa chains are consolidating vendor relationships toward fewer, larger-volume suppliers.
- Spas:Wellness-focused establishments emphasizing pre-treatment skin preparation protocols, standardizing micellar and oil-based removers across treatment menus.
- Retailers:Private-label and third-party brand curators, including Reliance Retail and Nykaa in India, negotiating shelf access based on dermatologist-tested claims and controlled distribution exclusivity.
Individual consumers anchor volume demand. Salon procurement shows the steepest expansion trajectory through spa chain consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU REACH chemical safety frameworks and state-level packaging mandates in California and New York are redrawing compliance requirements across manufacturing footprints. South Korea's multi-step cleansing rituals and India's organized retail expansion create divergent demand architectures that suppliers must navigate simultaneously.
South Korea
Double-cleansing rituals in Seoul and Busan households sustain premium oil-based and micellar format penetration. The Ministry of Food and Drug Safety (MFDS) enforces strict cosmetic ingredient documentation for both domestic and imported formulations. Gangnam district dermatology clinics standardize advanced micellar technology for pre-treatment skin preparation, compressing performance gaps between professional and retail grades.
United States
Millennial and Gen-Z subscription adoption in New York and Los Angeles urban markets displaces traditional retail replenishment cycles. The FDA's Modernization of Cosmetics Regulation Act elevates labeling compliance costs for ingredient transparency. California's extended producer responsibility bills favor early movers with refillable pump infrastructure and take-back programs.
Germany
ECHA's 2023 restricted substance candidate updates force immediate PEG-based emulsifier phase-outs across manufacturing lines. Formulators in Hamburg and Düsseldorf substitute with alkyl polyglucosides at compressed R&D cycles. Bavaria-based manufacturers prioritize post-consumer recycled content ratios to satisfy EU Green Deal packaging requirements.
India
Reliance Retail and Nykaa expansion creates shelf access for dermatologist-tested lines in Mumbai and Delhi-NCR. The Central Drugs Standard Control Organization (CDSCO) filing requirements add complexity for cross-border e-commerce entrants. Gujarat-based contract manufacturers scale ISO 22716-certified production to serve spa chain consolidation in Dubai and Singapore.
Japan
Pump-dispensing subscription bundles in Tokyo and Osaka organized retail support toner-assortment recurring revenue models. The Ministry of Economy, Trade and Industry (METI) standards guide sustainable packaging transitions. Shiseido's integrated R&D network in Kansai anchors botanical extract innovation for ingredient-conscious Asian market export.
Makeup Remover Market Vendor Landscape
Player mix skews toward integrated beauty conglomerates with captive R&D networks and mid-tier contract manufacturers seeking ISO 22716 certification for institutional channel access. Three archetypes dominate: multinational formulators with REACH-compliant surfactant documentation, prestige houses anchoring dermatologist-tested positioning, and private-label suppliers serving retail consolidation. Competitive moves concentrate on biotech-fermented emollient convergence and refillable packaging infrastructure buildout.
Within the multinational tier, L'Oréal S.A. and Estée Lauder Inc. exemplify divergent positioning strategies—L'Oréal leveraging integrated formulation leadership across micellar platforms, Estée Lauder anchoring prestige claims through controlled distribution. Shiseido Co., Ltd. occupies a distinct geography-informed niche emphasizing botanical differentiation for Asian market penetration. These three represent how scale, certification access, and ingredient storytelling separate viable competitors from margin-compressed alternatives.
| Leading Market Players |
|---|
| Estée Lauder |
| Shiseido |
| L'Oréal |
| Beiersdorf |
| Kao Corporation |
| Procter & Gamble |
| Johnson & Johnson |
| LVMH Moët Hennessy Louis Vuitton |
| Unilever |
| Others |
Supply Flow & Price Mechanics
Plant-derived surfactant substitution for PEG-based emulsifiers under EU REACH reformulation mandates simultaneously redraws raw material sourcing geography toward Southeast Asian coconut and palm kernel supply chains and compresses margin structures for manufacturers absorbing reformulation costs. This input transition elevates pricing power for compliant suppliers while penalizing legacy formulation inventories.
Pricing Analysis
Certification level creates the primary spread between mass-market and institutional-grade remover lines, with ISO 22716 and REACH-compliant documentation commanding 15-25% premiums over uncertified alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by dermatologist-tested claims, pump-dispensing convenience, and refill-system compatibility. Cost compression in the standard tier intensifies because of biodegradable substrate material premiums and dual-audit timeline burdens. Individual consumers in price-sensitive emerging markets exhibit highest elasticity, while Dubai and Singapore spa chains prioritize batch consistency over unit cost.
Supply Chain Analysis
ECHA restricted substance list compliance acts as a regulatory chokepoint filtering European market access, forcing immediate reformulation cycles across Hamburg and Düsseldorf manufacturing hubs. Supply concentrates in Germany, France, and South Korea for REACH-compliant surfactant production, with Indonesian and Philippine feedstock anchoring plant-derived input flows. Raw material dependencies center on alkyl polyglucosides, sugar esters, and fermentation-derived squalane. Single-source vulnerability runs through coconut oil supply concentration in Southeast Asian typhoon corridors. Distribution runs through institutional procurement contracts for salon chains alongside direct-to-consumer subscription platforms in North American urban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biotechnology-fermented emollient convergence and ECHA chemical safety mandates are accelerating formulation obsolescence cycles, compressing competitive windows for legacy players while opening white-space for compliant entrants. This regulatory-technological inflection rewards rapid certification investment and penalizes delayed reformulation.
For Market Incumbents: Fortify institutional channel lock-in by deepening ISO 22716 certification moats and securing multi-year spa chain contracts in Dubai and Singapore before mid-tier competitors achieve compliance scale. Prioritize captive R&D networks in Kansai and Hamburg to compress biotech-fermented ingredient development cycles. Waterless balm substitution pressure and PEG emulsifier phase-out costs threaten margin stability for liquid-format leaders slow to pivot. For New Entrants and Emerging Players: ISO 22716 fast-track certification unlocks immediate shelf access at Reliance Retail and Nykaa expansion corridors in Mumbai and Delhi-NCR, the most penetrable organized retail channel for dermatologist-tested lines. Target India's emerging premium tier through aloe vera and chamomile-positioned clean beauty portfolios. Direct-to-consumer subscription bundling with cotton pad and toner assortments offers the lowest customer acquisition friction in London and New York urban millennial segments. For Investors and Strategic Acquirers: Capital is best deployed toward mid-tier contract manufacturers with pending dual ISO 22716 and COSMOS organic certification pipelines, positioned to capture institutional procurement consolidation from spa chain vendor reduction programs. Long-term viability hinges on biotech-fermented emollient integration capability and refillable pump infrastructure ownership. Monitor ECHA restricted substance list expansion velocity as the primary signal for reformulation cost inflection and competitive shakeout timing.| Strategic Initiative | Industry Significance |
|---|---|
| Biotech-Fermented Ingredient Integration | Sugar-derived squalane and microbiome-friendly preservatives enable premium clean-label positioning against legacy PEG formulations. |
| Refillable Pump Infrastructure Buildout | California extended producer responsibility mandates favor early movers with take-back programs and post-consumer recycled content ratios. |
| ISO 22716 Certification Acceleration | Professional salon procurement consolidation in Dubai and Singapore requires compliant batch documentation for vendor shortlist inclusion. |
| Subscription Commerce Platform Launch | Millennial and Gen-Z adoption in New York and London supports recurring revenue capture through bundled remover-cotton-toner assortments. |
| Plant-Derived Surfactant Backward Integration | Upstream control over Indonesian and Philippine coconut oil supply chains secures oxidative stability and cost predictability for natural-positioned lines. |
Methodological Framework
A standing panel of formulation chemists, professional spa procurement directors, retail category buyers, and regulatory affairs specialists provided ongoing calibration across primary interview cycles and secondary validation against ECHA substance restriction updates, MFDS cosmetic filing databases, and EU Green Deal packaging compliance records. Bottom-up demand modeling from salon chain procurement volumes and individual consumer subscription patterns triangulated against top-down market sizing from customs trade flows and organized retail audit data.
Consistency checks validated volume and value outputs against external benchmarks across the analysis window, with segmentation modeling spanning product format chemistry, ingredient sourcing tier, packaging sustainability compliance, and end-user procurement archetype. CAGRs derived from annualized growth rate reconciliation between historical trade data and forward-looking institutional contract pipelines, incorporating biotech-fermented ingredient adoption curves and regulatory phase-out timelines as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under sustained REACH reformulation momentum and South Korean cleansing ritual stability; material deviation in ECHA restricted substance expansion velocity or India organized retail penetration rates would warrant model refresh. Practitioners should keep alternative scenarios live as California extended producer responsibility implementation timelines and biodegradable substrate cost curves evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Organic Makeup Remover Market
Cosmetics & Skincare
Lip Oil Market
Cosmetics & Skincare
Setting Spray Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Cosmetic Pencil and Pen Market
Cosmetics & Skincare
Camellia Skincare and Cosmetics Market
Cosmetics & Skincare
Anti-Pollution Skin Care Products Market
Cosmetics & Skincare
Scalp Scrub Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Face Compact Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Loose Setting Powder Market
Cosmetics & Skincare
Professional Scalp Care Products Market
Cosmetics & Skincare
Asia-Pacific Halal Cosmetics Market
Cosmetics & Skincare
North America Bath Soap Market