
 Lip Oil Market | 2026-2036
Lip Oil Market Size, Share, and Industry Trends Forecast 2026-2036
Lip Oil Market Foresight
Aftermarket service revenue from subscription-based replenishment programs is narrowing as direct-to-consumer brands shift toward bundled skincare routines. Fenty Beauty leverages its R&D intensity to anchor premium positioning across tinted and color-enhancement formats. Dior sustains geographic dominance through controlled distribution in European specialty retail and Asian travel retail corridors.
Lip oil denotes a cosmetic formulation combining emollient plant-derived or synthetic oils with humectants, typically achieving a viscosity between 3,000 and 8,000 centipoise to deliver glossy hydration without the occlusive film of traditional balms. Its primary commercial purpose bridges color cosmetics and skincare, targeting consumers who reject waxy textures yet demand visible shine and barrier support. Tinted lip oil captures the dominant margin pool as consumers accept premium pricing for dual-function color payoff, while unscented variants lead volume growth among organic enthusiasts with sensitivity concerns. Online distribution channels now compete most aggressively for teenager acquisition, though specialty stores retain higher average transaction values among professional consumers.
FDA cosmetic labeling requirements and EU REACH chemical restrictions jointly shape permissible pigment and fragrance chemistries, forcing reformulation cycles that favor compliant suppliers. South Korea's MFDS cosmetic safety standards additionally influence global product development timelines through K-beauty export demand. Stakeholders must monitor evolving cross-border ingredient harmonization as regulatory divergence between North American and European frameworks threatens to fragment supply chain planning.
Market Dynamics
Hybrid cosmetic-skincare formulation requirements are compressing traditional category boundaries, forcing suppliers to recalibrate R&D pipelines around multi-functional viscosity standards and cross-regulatory pigment compliance.
Growth Catalysts
- EU REACH chemical disclosure mandates:Clean beauty certification under tightened European frameworks is accelerating ingredient transparency investments among formulators seeking premium positioning.
- K-beauty texture innovation cycles:South Korean MFDS cosmetic safety standards are redefining global wear expectations through export-driven product development timelines.
- Salon channel professionalization:Makeup artist endorsement networks are pulling hybrid formats into service-based retail environments with higher attachment rates.
Market Restraints
- Plant-derived oil input volatility:Squalane and jojoba supply concentrates in drought-exposed agricultural zones, exposing margin structures to climate-driven harvest variability.
- Pigment chemistry regulatory friction:Divergent FDA and EU REACH permissible colorant lists force parallel formulation tracks that inflate inventory carrying costs.
- Wax-based balm substitution resilience:Occlusive lip protectants retain pharmacy channel dominance among dermatologist-recommended sensitivity protocols.
Strategic Opportunities
- Indian clean beauty regulatory tailwind:BIS cosmetic standards evolution creates first-mover positioning for compliant tinted formats in underpenetrated mass retail.
- Subscription bundling convergence:Skincare routine packaging is digitizing replenishment cadences through algorithmic shade-matching and seasonal rotation.
- Teenager digital-native acquisition:Social commerce integration on short-form video platforms captures pre-brand-loyal cohorts before specialty store entry.
Industry Challenges
- Cross-border ingredient harmonization complexity:Misaligned North American and European safety data requirements delay launch windows by 8-14 months for multi-market SKUs.
- Cosmetic chemist talent scarcity:Formulation expertise spanning both color payoff and barrier function sits concentrated with K-beauty veterans and legacy fragrance houses.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lip Oil Market |
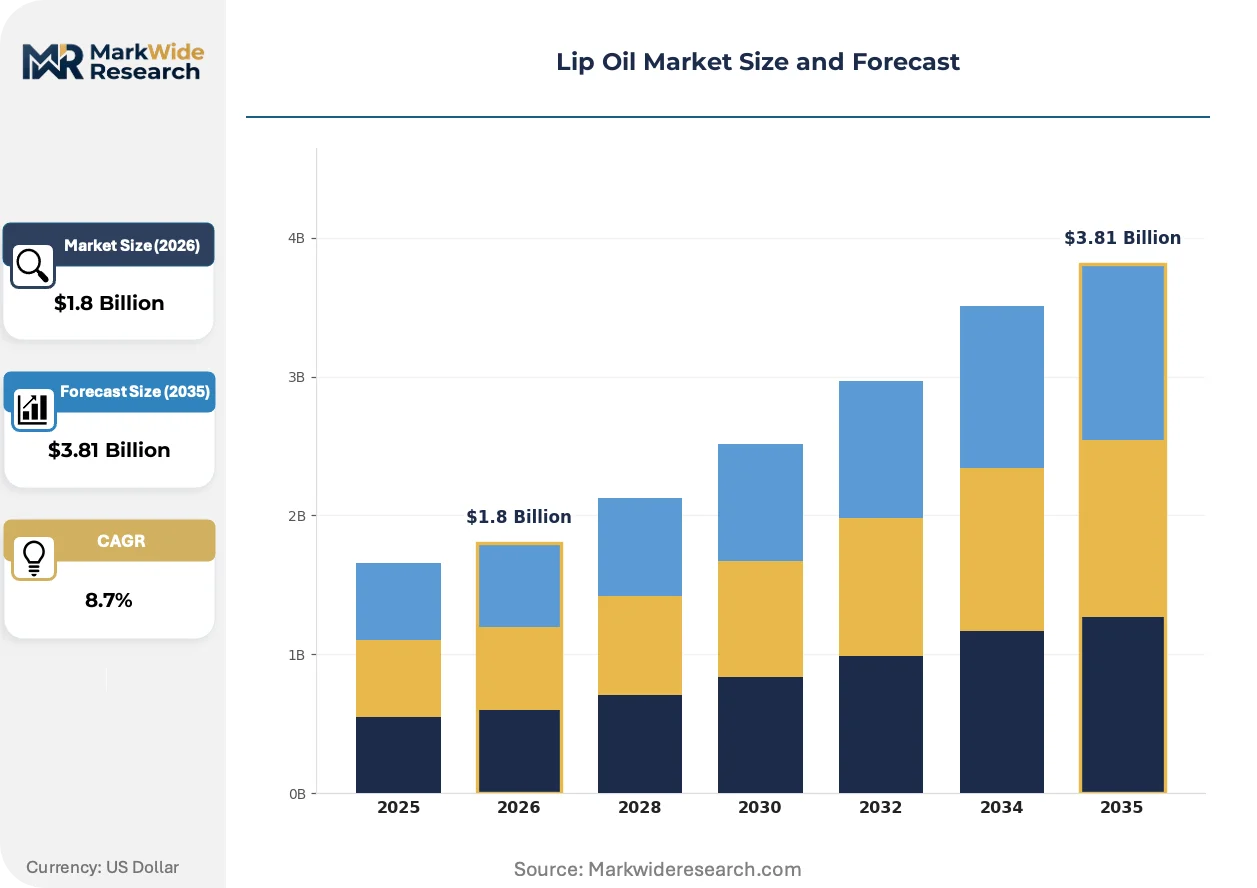
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tinted, Non-Tinted, Flavored, Unscented Application: Daily Care, Hydration, Sun Protection, Color Enhancement Distribution Channel: Online, Drugstores, Supermarkets, Specialty Stores Consumer Type: Teenagers, Adults, Professionals, Organic Enthusiasts |
| Companies Covered | Lady Burd, Auroracos, Fenty Beauty, AG Organica, Pure Source, Dior, New Look Cosmetics, Cosmiko, Xiran Skincare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lip Oil Market Shifts & Advancements
Active ingredient delivery systems and regulatory disclosure automation are compressing traditional development cycles while reshaping how formulators validate hybrid efficacy claims across jurisdictions.
Microencapsulated pigment technology is digitizing color release mechanisms in lip oil formulations, enabling pH-responsive tint adaptation. Prestige cosmetic laboratories in South Korea and France are adopting these systems at pilot scale. The technology is digitizing shade customization by linking biometric skin tone data to dynamic formulation adjustments.
EU REACH Annex XVII restrictions on synthetic fragrance allergens are forcing reformulation of signature scent profiles in mass-market lines. Fragrance houses must now submit extended safety dossiers for all new molecules above 0.01% concentration. Tinted variants targeting European specialty retail are responding with unscented base formulations that defer scent to optional layering products.
Algorithmic shade-matching through smartphone camera integration is displacing in-store color testing among digital-native consumers. Direct-to-consumer brands capture this behavior shift through virtual try-on infrastructure that reduces return rates. South Korea and the United States represent the most visible adoption geographies, where teenager cohorts demonstrate minimal loyalty to physical counter experiences.
Lip Oil Market Segmentation
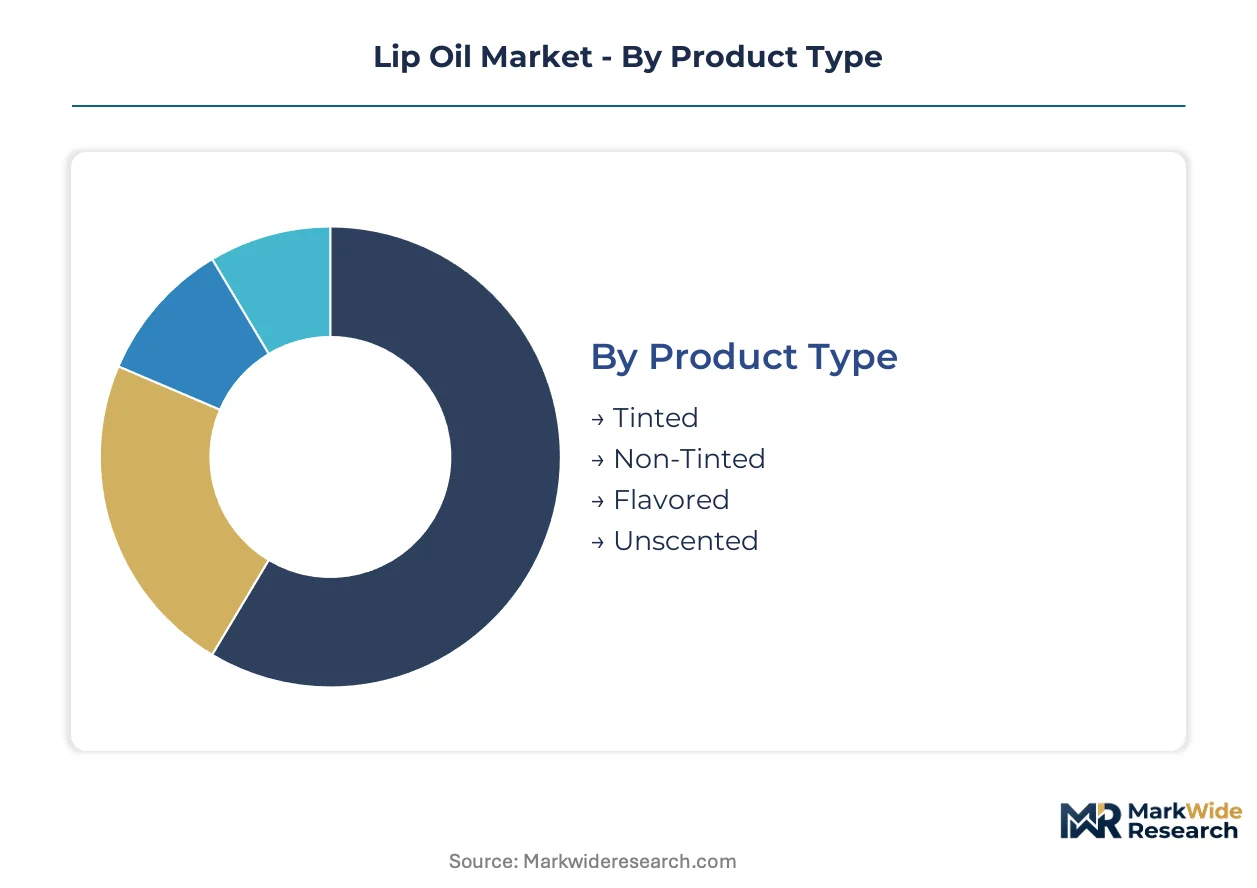
Segmentation in lip oil markets reveals how hybrid cosmetic-skincare positioning fragments across consumer priorities, from color payoff demands to clean ingredient preferences. Understanding these divisions exposes where margin pools concentrate and which channels capture pre-loyal cohorts.
Product Type:
Mature formats dominate revenue while emerging variants reshape formulation pipelines.
- Tinted:Combines emollient oil bases with suspended mineral or synthetic pigments at 3,000-8,000 centipoise viscosity. Demand concentrates among professional makeup artists in South Korea and France who require dual-function color payoff with barrier support. Premium pricing acceptance here anchors the category's margin structure.
- Non-Tinted:Pure oil formulations emphasizing translucency and natural finish without pigment load. Organic enthusiasts in Germany and California drive volume as EU REACH fragrance restrictions push consumers toward minimal ingredient lists. The segment gains shelf space in pharmacy channels.
- Flavored:Synthetic or natural flavor-infused variants targeting younger demographics through sensory differentiation. Teenager acquisition in the United States and Japan favors these formats for social media content creation.
- Unscented:Zero-fragrance formulations designed for sensitivity protocols and clean beauty certification compliance. South Korean export demand and European specialty retail expansion accelerate production.
Tinted formats retain volume leadership; unscented variants hold the steepest expansion curve.
Application:
Functional positioning determines pricing tier and regulatory burden across end-uses.
- Daily Care:Maintenance-oriented formulations with standard emollient ratios for routine lip conditioning. Mass retail in India and Brazil captures this volume through accessible price points.
- Hydration:High-humectant concentrates targeting barrier repair for consumers rejecting waxy balm textures. Professional salon channels in Italy and Spain attach these to service menus.
- Sun Protection:SPF-infused oils requiring FDA or MFDS sunscreen monograph compliance. The United States and South Korea concentrate development timelines as regulatory testing extends launch windows.
- Color Enhancement:pH-responsive or microencapsulated pigment systems enabling dynamic shade adaptation. Prestige laboratories in France and South Korea pilot these technologies for personalized beauty.
Daily care commands baseline volume; color enhancement climbs the fastest as technology matures.
Distribution Channel:
Channel selection directly shapes customer acquisition cost and average transaction value.
- Online:Direct-to-consumer platforms with algorithmic shade-matching and subscription bundling. Teenager cohorts in the United States and South Korea demonstrate minimal loyalty to physical counter experiences here.
- Drugstores:Mass-market access points for occlusive balm substitutes and pharmacy-recommended sensitivity protocols. Germany and Japan concentrate this channel's volume.
- Supermarkets:Impulse purchase environments for flavored and entry-priced formats. Brazil and Mexico expand shelf space for accessible daily care variants.
- Specialty Stores:Controlled distribution with higher average transaction values among professional consumers and clean beauty seekers. France and South Korea anchor prestige positioning here.
Online channels capture acquisition scale; specialty stores defend margin concentration.
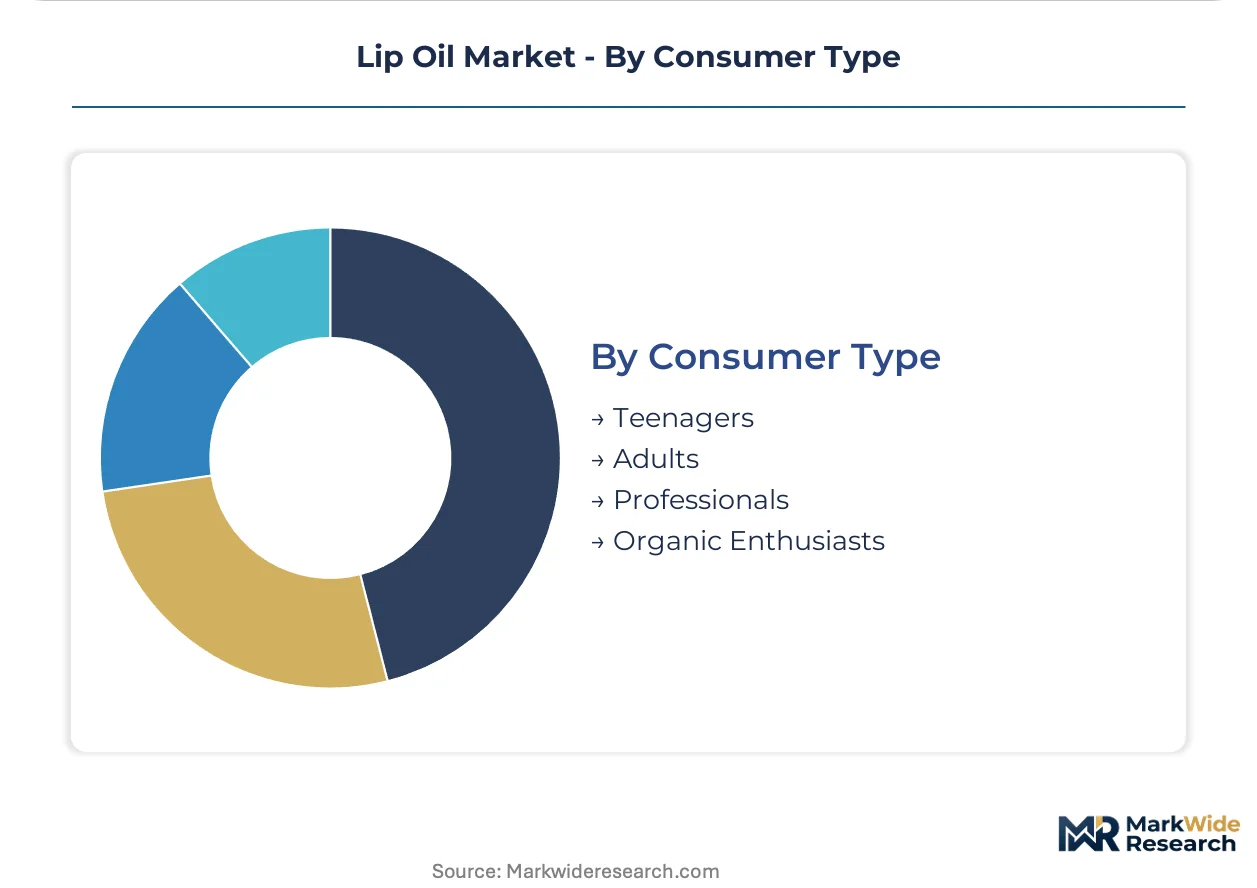
Consumer Type:
Demographic targeting separates mass volume from premium pricing power.
- Teenagers:Digital-native cohorts acquired through short-form video commerce and virtual try-on infrastructure. The United States and South Korea represent visible adoption geographies.
- Adults:Core revenue base balancing efficacy claims with convenience across multi-channel purchase patterns. Urban centers in Japan and Germany concentrate this segment.
- Professionals:Makeup artists and salon service providers pulling hybrid formats into endorsement-driven retail environments. France and Italy sustain network effects here.
- Organic Enthusiasts:Clean beauty certification seekers with sensitivity concerns and ingredient transparency demands. EU REACH compliance and BIS standards evolution in India shape product development.
Adults retain volume leadership; organic enthusiasts gain share fastest as certification requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
South Korea consumes lip oil as a hybrid cosmetic-skincare staple with texture innovation at its core, while the United States treats it primarily as a color-enhancement vehicle acquired through digital channels. Germany emphasizes unscented pharmacy-grade formulations under clean beauty protocols. France anchors prestige positioning through controlled specialty retail.
South Korea
MFDS cosmetic safety standards drive K-beauty export demand with rapid innovation cycles redefining global wear expectations. Seoul Capital Area laboratories pilot microencapsulated pigment systems and pH-responsive tint adaptation. Busan-Ulsan manufacturing clusters supply emollient base formulations to prestige brands worldwide.
United States
FDA cosmetic labeling requirements and evolving sunscreen monograph rules shape SPF-infused oil development timelines. Teenager acquisition concentrates through algorithmic shade-matching and virtual try-on infrastructure on short-form video platforms. Greater Los Angeles and New York Metro anchor direct-to-consumer brand headquarters with subscription bundling operations.
Germany
EU REACH Annex XVII fragrance allergen restrictions push consumers toward unscented variants with minimal ingredient transparency. Pharmacy channels in Bavaria and North Rhine-Westphalia stock clean beauty certified formats for sensitivity protocols. Berlin-Brandenburg specialty retailers command higher average transaction values among organic enthusiasts.
France
Prestige positioning relies on controlled distribution through European specialty retail and Asian travel retail corridors. ANSM cosmetic safety oversight reinforces formulation standards for tinted color-enhancement products. Île-de-France laboratories develop hybrid viscosity standards bridging cosmetic payoff with barrier function claims.
India
BIS cosmetic standards evolution creates first-mover positioning for compliant tinted formats in underpenetrated mass retail. Maharashtra and Gujarat manufacturing zones scale plant-derived oil processing for domestic and export markets. Delhi-NCR urban centers drive daily care volume through accessible price points in modern trade channels.
Lip Oil Market Competitive Landscape
Capability concentration sits with K-beauty veterans and legacy fragrance houses possessing cross-functional formulation expertise; scale advantage sits with multinational beauty conglomerates controlling global distribution infrastructure. The vendor base organizes around three archetypes: prestige houses with R&D-intensive positioning, clean beauty specialists with certification-first strategies, and contract manufacturers serving private label demand. Dominant competitive moves include portfolio diversification into hybrid cosmetic-skincare formats and strategic partnerships with algorithmic shade-matching technology providers.
Within the prestige house tier, Dior and Fenty Beauty exemplify R&D-intensive positioning through controlled distribution and texture innovation. AG Organica occupies a position within the clean beauty specialist archetype, emphasizing plant-derived ingredient transparency. These three anchors illustrate how geographic origin and structural suffixes map to strategic positioning without requiring specific product or financial claims.
| Leading Market Players |
|---|
| Lady Burd |
| Auroracos |
| Fenty Beauty |
| AG Organica |
| Pure Source |
| Dior |
| New Look Cosmetics |
| Cosmiko |
| Xiran Skincare |
| Others |
Supply & Pricing Matrix
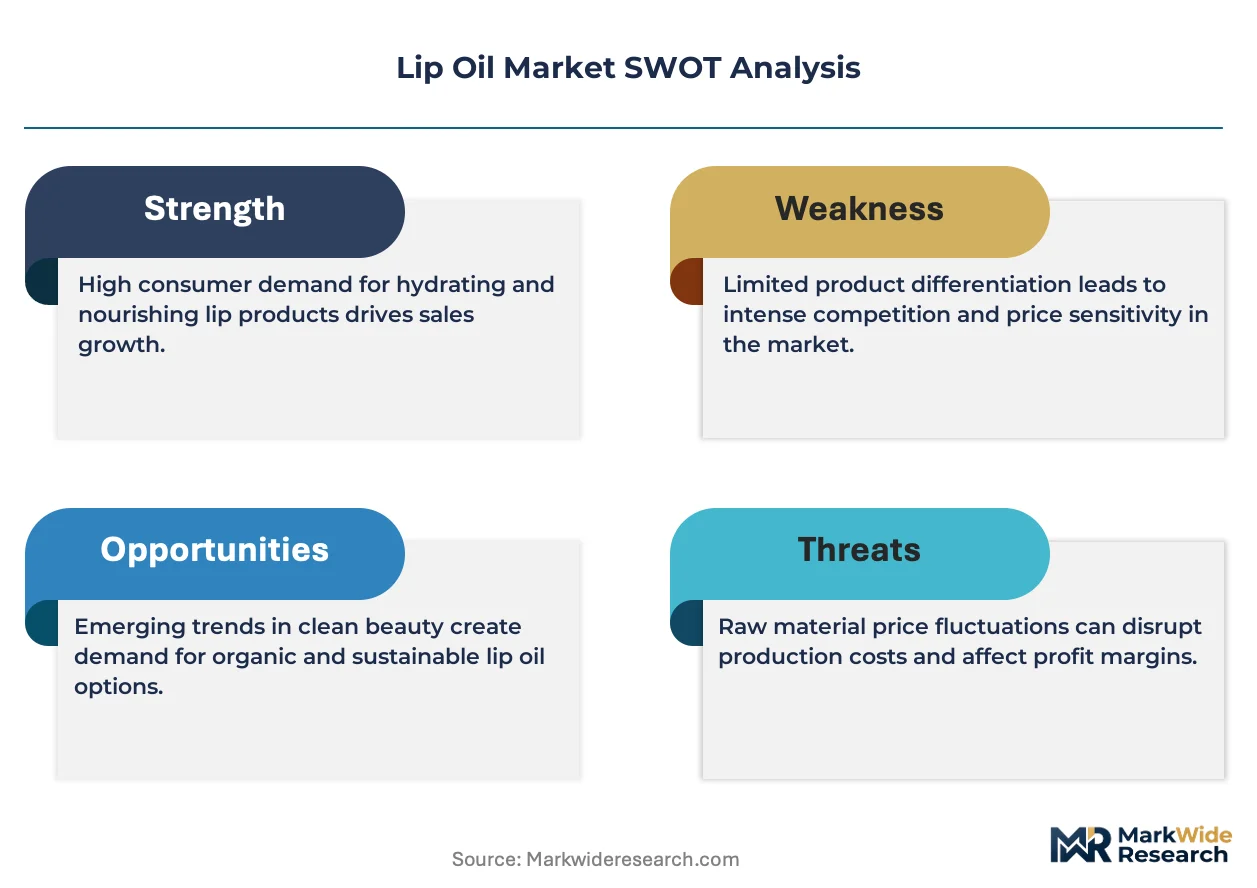
Plant-derived oil input volatility determines both pricing tier spreads and supply chain shape as squalane and jojoba harvest variability in drought-exposed agricultural zones compresses margin structures and forces tier differentiation between premium certified formulations and mass-market alternatives.
Pricing Analysis
Long-term offtake agreements anchor premium tier pricing for K-beauty export volumes while spot market exposure dominates mass-market contract structures. Price differentiation separates EU REACH-certified clean beauty formulations from standard cosmetic-grade alternatives, with certification tier and brand premium as primary drivers. Pricing pressure stems from climate-driven agricultural input cost compression in standard tiers. Teenager cohorts demonstrate highest price sensitivity through algorithmic shade-matching platforms, while professional makeup artists accept premium positioning for hybrid efficacy claims.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for pigment and packaging component flows. Manufacturing concentrates in South Korea, France, and India, with emollient base formulation expertise anchored in Seoul Capital Area laboratories and Île-de-France prestige houses. Raw material dependencies center on squalane from olive and sugarcane sources, jojoba from North American desert cultivation, and synthetic humectants from petrochemical feedstocks. Distribution runs through direct-to-consumer platforms for teenager acquisition and controlled specialty retail for professional endorsement networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Lip oil sits in early-cycle expansion as hybrid cosmetic-skincare formats penetrate pharmacy and salon channels previously dominated by occlusive balms, with K-beauty export demand accelerating global texture standard adoption.
For Market Incumbents: Insulate margin structures by deepening captive supply of plant-derived emollients through backward integration into drought-resilient agricultural zones, while accelerating EU REACH and FDA pigment compliance investments to forestall reformulation cost inflation from regulatory divergence. Channel control through professional makeup artist endorsement networks defends against direct-to-consumer brand erosion in the professional segment. For New Entrants and Emerging Players: Indian mass retail underpenetration offers first-mover positioning for BIS-compliant tinted formats at accessible price points, with Maharashtra and Gujarat manufacturing zones enabling domestic emollient processing scale. White-space capture should target teenager acquisition through short-form video platform integration with virtual try-on infrastructure, leveraging algorithmic shade-matching to reduce customer acquisition costs below specialty store benchmarks. For Investors and Strategic Acquirers: Clean beauty specialists with established EU REACH certification and MFDS cosmetic safety dossiers represent priority acquisition targets as regulatory compliance timelines extend launch windows for multi-market SKUs. Long-term viability hinges on formulation expertise spanning both color payoff and barrier function claims. The signal to monitor is cross-border ingredient harmonization progress between FDA and EU REACH frameworks.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Emollient Agriculture | Captive squalane supply from drought-resilient cultivation zones insulates margin compression. |
| EU REACH Certification Investment | Clean beauty compliance accelerates shelf access in German pharmacy and French specialty retail. |
| Algorithmic Shade-Matching Platform Partnership | Virtual try-on infrastructure reduces return rates for direct-to-consumer teenager acquisition. |
| Professional Makeup Artist Endorsement Network | Service-based retail attachment in Italian and Spanish salon channels defends premium positioning. |
| Microencapsulated Pigment R&D Scale-Up | pH-responsive tint adaptation pilots in Seoul laboratories enable personalized beauty claims. |
Research Methodology
Initial hypotheses were tested against primary input from cosmetic formulators, brand R&D directors, specialty retail buyers, and regulatory affairs leads, and refined through secondary validation across MFDS cosmetic safety filings, EU REACH Annex XVII restriction updates, FDA sunscreen monograph dockets, and customs trade data for plant-derived oil imports. Bottom-up volume estimates from emollient supplier interviews triangulated against top-down category spend analysis from retail audit databases.
Demand-supply-balance framing structured the analytical approach across the projection horizon, modeling segmentation dimensions including product type, application function, distribution channel, and consumer demographic tier. CAGRs were derived from growth rate convergence analysis across these segments, incorporating K-beauty export volume trajectories, salon channel professionalization rates, and clean beauty certification adoption curves as industry-specific forecast inputs.
Macroeconomic conditions sit as an overlay; deviation in agricultural commodity prices, cross-border tariff regimes, or regulatory harmonization timelines would shift the trajectory. Forecasts reflect documented assumptions about innovation cycle velocity and channel migration patterns. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
GCC Halal Cosmetics Market
Cosmetics & Skincare
Halal Cosmetics Market
Cosmetics & Skincare
Eye Shadow Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Lipstick Market
Cosmetics & Skincare
Hand Cream Market
Cosmetics & Skincare
Caffeine Eye Creams Market
Cosmetics & Skincare
Lip Scrub Market
Cosmetics & Skincare
Russia Lip Care Products Market
Cosmetics & Skincare
North America Face Compact Market
Cosmetics & Skincare
Cosmetic Mirror Market
Cosmetics & Skincare
Waterproof Eyebrow Liner Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Deodorant Stick Market
Cosmetics & Skincare
Israel Cosmetics Products Market