
 Deodorant Stick Market | 2026-2036
Deodorant Stick Market Size, Share, and Industry Trends Forecast 2026-2036
Deodorant Stick Market Analysis
Multi-source ingredient procurement is restructuring supply relationships across the deodorant stick value chain as brands hedge against volatile botanical extract costs. Unilever PLC leverages its integrated sourcing network to secure shea butter and coconut oil volumes at scale. Beiersdorf AG anchors its European manufacturing with regional surfactant suppliers to reduce transit-related formulation degradation. Procter & Gamble competes through captive R&D facilities that develop proprietary encapsulation technologies for extended fragrance release.
A deodorant stick is a solid personal hygiene preparation, typically comprising 15-25% active ingredients suspended in a wax or oil-based matrix, designed to reduce perspiration odor through antimicrobial action or sweat inhibition. The product type dimension shows stick formats retaining dominance in North American mass retail while spray alternatives gain velocity in European convenience channels. Natural ingredient positioning commands premium shelf placement as consumers scrutinize INCI lists for paraben and triclosan exclusions, though antiperspirant variants still occupy the largest volume share due to clinical efficacy claims. Distribution channel dynamics reveal online platforms capturing incremental unisex and teenager trial purchases that supermarkets rarely convert.
FDA over-the-counter monographs govern antiperspirant active concentrations in the United States, while REACH compliance in Europe mandates full fragrance allergen disclosure on cosmetic labels. The EU F-Gas Regulation indirectly pressures aerosol spray segments by restricting propellant chemistries, redirecting investment toward solid stick and roll-on formats. Stakeholders must monitor evolving state-level clean beauty legislation in California and New York, where pending disclosure bills could fragment formulation standards well ahead of any federal harmonization.
Market Dynamics
EU Green Deal chemical restrictions are forcing wholesale reformulation across the deodorant stick industry, as manufacturers abandon aluminum salts and synthetic fragrance compounds that have dominated antiperspirant chemistry for decades. This regulatory compression is redrawing competitive boundaries between clinical-efficacy and clean-positioned brands.
Growth Catalysts
- Men's grooming expansion:Male consumers are extending daily routines beyond basic hygiene into specialized body-care categories, creating new volume in premium stick formats.
- REACH fragrance disclosure mandates:Full allergen labeling requirements in Europe are accelerating consumer education and driving trial of transparently formulated alternatives.
- Shea butter and coconut oil scale economics:Integrated agricultural sourcing networks are stabilizing input costs for natural-positioned products.
Market Restraints
- Botanical extract cost volatility:Weather-dependent harvests for essential oil feedstocks create margin pressure that synthetic alternatives avoid.
- Aluminum salt dependency in clinical segments:FDA OTC monographs limit active alternatives for sweat-inhibition claims, trapping efficacy-focused brands in regulatory crossfire.
- EU F-Gas Regulation spillover:Propellant chemistry restrictions on aerosols indirectly constrain spray-to-stick format migration timelines.
Strategic Opportunities
- Teenager unisex trial via direct-to-consumer:Online subscription models capture demographic segments that mass retail fails to convert.
- California and New York clean beauty legislation:Pending state-level disclosure bills create first-mover advantage for pre-compliant formulations ahead of potential federal harmonization.
- Encapsulation technology convergence:Proprietary extended-release fragrance systems are unifying performance claims with natural ingredient positioning.
Industry Challenges
- Formulation chemist scarcity:Expertise in wax-matrix suspension systems for solid formats is concentrating among legacy suppliers.
- Multi-jurisdiction compliance timelines:Divergent FDA and REACH standards force parallel development tracks that compress R&D efficiency.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Deodorant Stick Market |
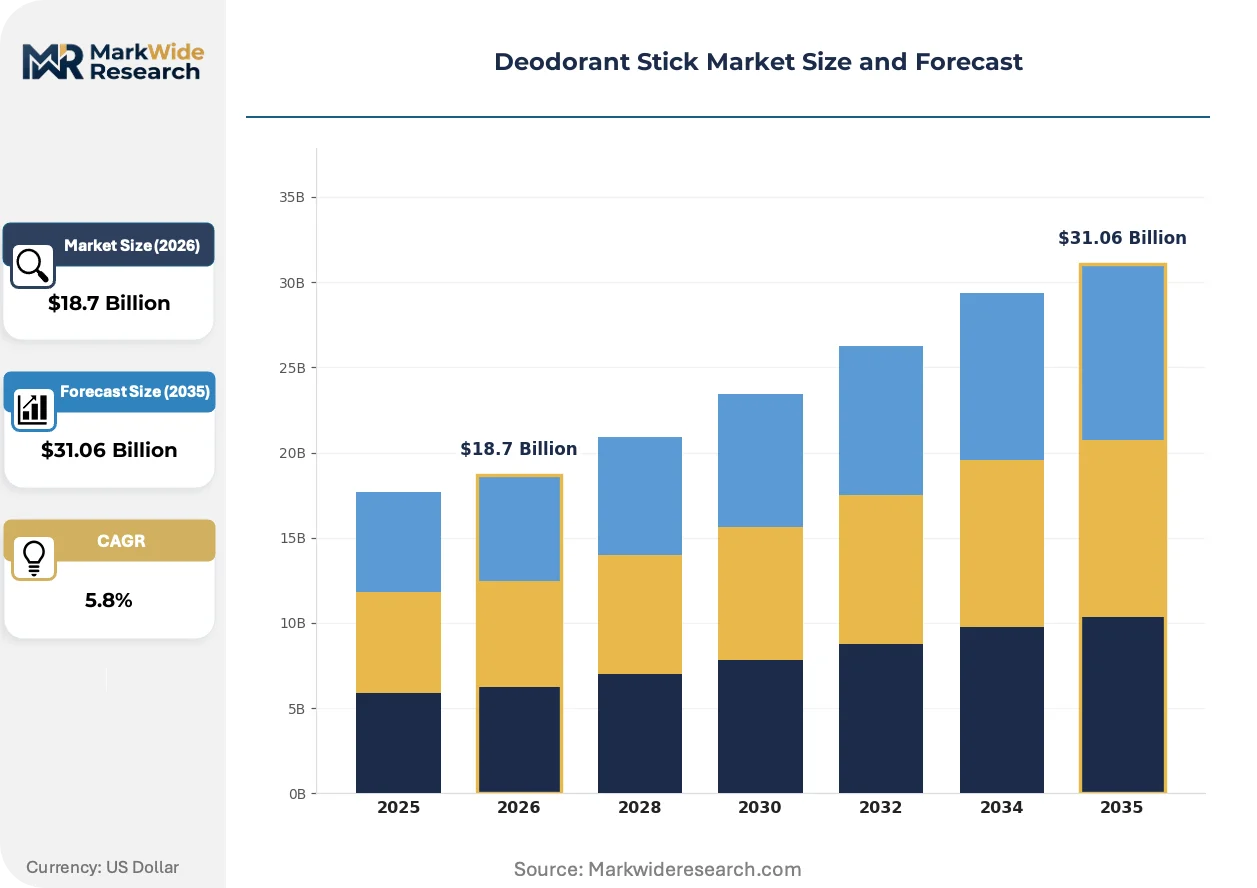
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Roll-On, Spray, Stick, Paste Ingredient Type: Natural, Synthetic, Organic, Antiperspirant End User: Women, Men, Unisex, Teenagers Distribution Channel: Online, Supermarkets, Pharmacies, Specialty Stores |
| Companies Covered | Unilever PLC, Procter & Gamble, Beiersdorf AG, L’Oréal S.A., Colgate-Palmolive Company, The Estée Lauder Companies Inc., Mandom Corporation, Lion Corporation, Henkel AG & Co KGaA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Deodorant Stick Market Emerging Trajectories
Reformulation chemistry is actively displacing legacy active ingredients across the deodorant stick market, with biotechnology-derived alternatives and mineral-based odor neutralizers gaining commercial traction. This shift is compressing the traditional divide between clinical performance and clean-label positioning.
Encapsulation technology is unifying fragrance delivery with skin-conditioning benefits in next-generation stick formulations. Premium and masstige brands are adopting these systems fastest, collapsing the historical trade-off between extended wear-time and reduced synthetic load. The structural consequence is a new product architecture where single sticks deliver previously separate antiperspirant, deodorant, and skincare functions.
REACH compliance in Europe mandates full fragrance allergen disclosure on cosmetic labels, forcing brands to either simplify scent palettes or invest in transparency marketing. The industrial consequence is a bifurcation between hypoallergenic minimalist lines and complex fine-fragrance-positioned products with detailed ingredient storytelling. Mass retail channels in Germany and France are most affected, with shelf resets prioritizing compliant SKUs.
Direct-to-consumer subscription models are capturing teenager and unisex trial purchases that supermarkets rarely convert, with online platforms enabling ingredient education and sampling at scale. Specialty beauty retailers and pharmacy chains are responding with dedicated clean-beauty sections, though their conversion rates lag digital-native entrants. This channel rotation is most visible in the United States, where pharmacy and specialty retail shelf space for premium natural-positioned sticks is expanding fastest.
Deodorant Stick Market Segmentation
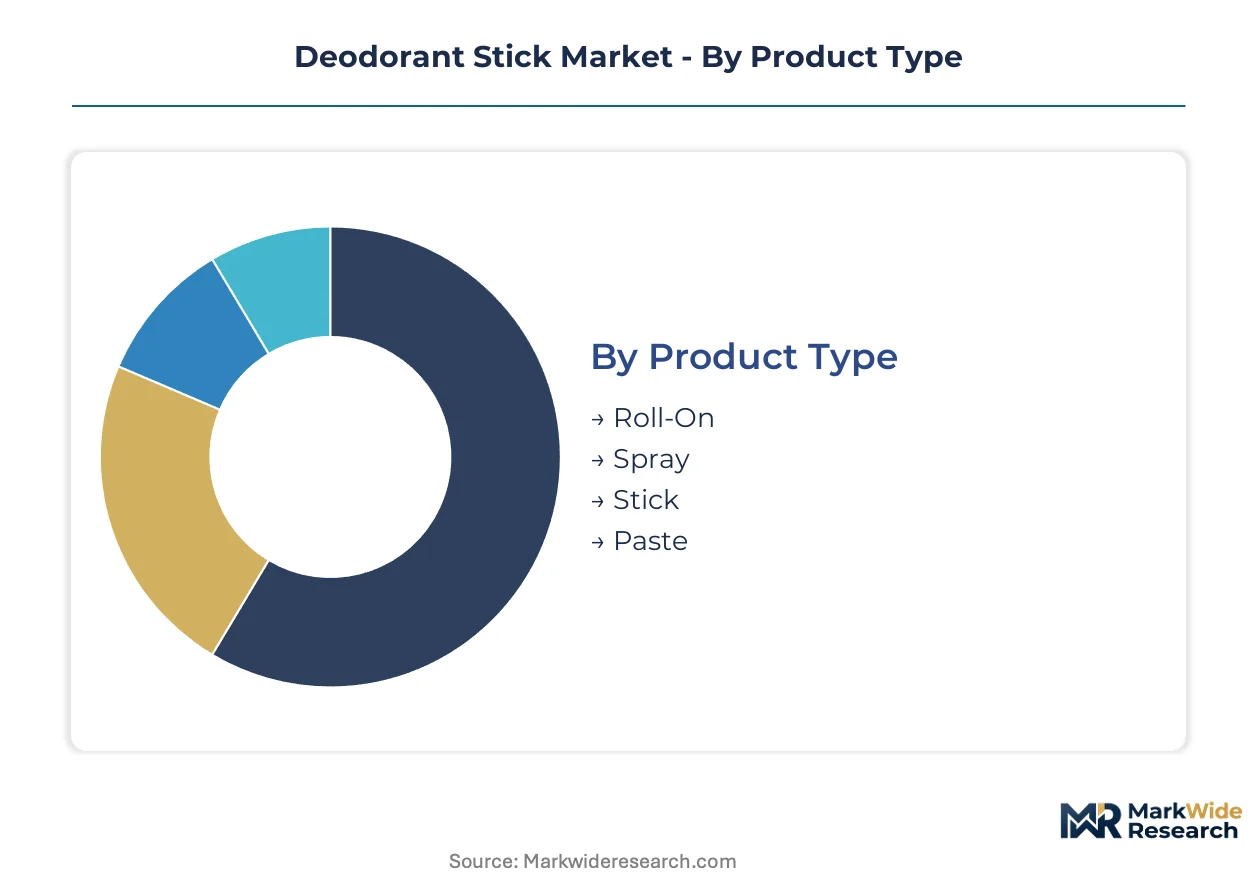
Deodorant stick segmentation reveals how formulation chemistry, user demographics, and channel access create distinct competitive arenas. Each dimension carries specific regulatory burdens and margin profiles that reshape portfolio priorities.
Product Type:
Stick formats anchor North American mass retail through wax-matrix suspension systems that withstand temperature cycling during distribution.
- Stick:Solid wax-oil matrices suspend active ingredients at 15-25% concentration. United States pharmacy and specialty retail channels allocate expanding shelf space to premium natural-positioned variants as clean beauty legislation advances in California and New York.
- Roll-On:Liquid formulations in ball-applicator packaging deliver lower residue profiles. European convenience channels favor this format where EU F-Gas Regulation pressures on aerosol propellants redirect investment from spray alternatives.
- Spray:Aerosol or pump-dispensed formats rely on compressed propellants. Efficacy claims face tightening scrutiny under REACH fragrance disclosure mandates.
- Paste:Cream-based applications in jar or tube packaging. Niche positioning in specialty beauty retail emphasizes skincare-hybrid positioning.
Mature deployment sits with Stick. Newer deployment is concentrated in Roll-On.
Ingredient Type:
Raw material sourcing strategy determines compliance exposure and cost volatility across formulation architectures.
- Antiperspirant:Aluminum salt-based sweat inhibition dominates clinical efficacy segments. FDA OTC monographs constrain active alternatives, trapping brands in regulatory tension with EU Green Deal chemical restrictions.
- Natural:Shea butter and coconut oil matrices bypass synthetic fragrance allergens. Integrated agricultural networks stabilize input costs for brands with captive sourcing.
- Synthetic:Petrochemical-derived active compounds and fragrance systems. Margin advantage persists where botanical extract harvest volatility pressures natural alternatives.
- Organic:Certified feedstock supply chains with full traceability documentation. Premium shelf placement commands in German and French mass retail following REACH allergen disclosure resets.
Volume concentration remains with Antiperspirant. Steepest expansion trajectory belongs to Natural.
End User:
Grooming routine complexity varies sharply across demographic segments, reshaping product architecture and marketing investment.
- Men:Specialized body-care adoption extends beyond basic hygiene into premium stick formats. Direct-to-consumer subscription models capture trial that mass retail rarely converts.
- Women:Established category penetration with fragmentation across clinical, cosmetic, and wellness-positioned lines. Pharmacy channel loyalty persists for dermatologist-recommended variants.
- Unisex:Gender-neutral fragrance profiles and minimalist packaging. Online platforms enable ingredient education at scale for this emerging segment.
- Teenagers:First-category trial and habit formation. Digital-native entrants outperform traditional retail on conversion through sampling and subscription mechanics.
Established penetration sits with Women. Fastest share gain is concentrated in Men.
Distribution Channel:
Channel selection determines margin structure, customer education depth, and regulatory disclosure obligations.
- Online:Direct-to-consumer and marketplace platforms enable unisex and teenager trial through sampling and subscription. Full INCI list transparency satisfies clean beauty scrutiny.
- Supermarkets:Mass retail volume with limited conversion of emerging demographics. Shelf resets prioritize REACH-compliant SKUs in European markets.
- Pharmacies:Clinical efficacy claims and dermatologist endorsement carry weight. United States pharmacy chains expand dedicated clean-beauty sections fastest.
- Specialty Stores:Premium positioning with fine-fragrance storytelling and detailed ingredient narratives. German and French retail leads allergen disclosure compliance.
Volume concentration sits with Supermarkets. Emerging deployment is concentrated in Online.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shea butter sourcing networks from West Africa and coconut oil supply chains across Southeast Asia anchor manufacturing footprints for natural-positioned deodorant stick production in key consumer markets.
United States
Men's grooming expansion and pharmacy channel premiumization drive demand concentration. FDA OTC monographs govern antiperspirant active concentrations, constraining formulation alternatives. California and New York pending clean beauty disclosure bills are accelerating pre-compliant product development in Los Angeles and New York Metro formulation labs.
Germany
REACH fragrance allergen disclosure mandates reshape mass retail shelf resets toward compliant SKUs. EU Green Deal chemical restrictions force aluminum salt reformulation across clinical efficacy segments. Cologne and Hamburg manufacturing clusters specialize in wax-matrix suspension systems for solid stick formats.
France
Fine-fragrance positioning and detailed ingredient storytelling command premium shelf placement in specialty retail. ANSM enforces cosmetic safety standards alongside REACH compliance requirements. Paris and Lyon formulation centers concentrate expertise in encapsulation technology for extended fragrance release.
United Kingdom
Online subscription models capture teenager and unisex trial purchases that supermarkets rarely convert. UKCA marking requirements post-Brexit create parallel compliance tracks with EU regulations. London and Manchester direct-to-consumer brands leverage ingredient education to build digital-native market presence.
Japan
Skincare-hybrid positioning and minimalist scent palettes align with consumer preferences for transparent formulation. METI oversees cosmetic quality standards while industry adheres to ISO cosmetic guidelines. Osaka and Tokyo manufacturing clusters develop biotechnology-derived active alternatives to aluminum salts.
Deodorant Stick Market Vendor Landscape
Global majors compete with regional champions across formulation technology and sourcing network dimensions, producing a tiered structure where scale-driven players anchor mass retail while specialists capture premium positioning. Three archetypes dominate: integrated consumer goods conglomerates with captive R&D facilities, regional dermatology-focused manufacturers with pharmacy channel strength, and digital-native entrants with direct-to-consumer subscription mechanics. Competitive moves concentrate on multi-source ingredient procurement partnerships and proprietary encapsulation technology licensing.
Within the integrated conglomerate tier, Unilever PLC and Procter & Gamble exemplify scale-driven positioning through global sourcing networks and captive manufacturing infrastructure. Beiersdorf AG occupies a specialist position representing European dermatology-rooted formulation expertise with regional supply chain anchoring. These three entities collectively illustrate the competitive tension between clinical-efficacy heritage and clean-positioned reformulation imperatives reshaping portfolio priorities.
| Leading Market Players |
|---|
| Unilever PLC |
| Procter & Gamble |
| Beiersdorf AG |
| L’Oréal S.A. |
| Colgate-Palmolive Company |
| The Estée Lauder Companies Inc. |
| Mandom Corporation |
| Lion Corporation |
| Henkel AG & Co KGaA |
| Others |
Supply Flow & Price Mechanics
Premium-clinical efficacy bifurcation from clean-positioned natural alternatives manifests in both pricing architecture and supply chain sourcing strategies across the deodorant stick market. Brands occupying the aluminum salt-based clinical tier command higher per-unit prices through FDA OTC monograph compliance investments, while natural-positioned competitors absorb botanical extract cost volatility through integrated shea butter and coconut oil procurement networks anchored in West Africa and Southeast Asia.
Pricing Analysis
After-sales service bundling separates premium-positioned sticks with dermatologist endorsement programs from unbundled mass retail economy tiers. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade divergence—REACH-compliant allergen disclosure and organic certification command shelf space premiums in German and French pharmacy channels. Cost compression in the natural tier is intensifying because weather-dependent essential oil harvests create input price instability. Teenager and unisex segments through direct-to-consumer channels exhibit lowest price sensitivity due to subscription model lock-in, while supermarket mass retail buyers remain most price-elastic.
Supply Chain Analysis
Regional distribution centers in Germany, France, and the United States coordinate hub-and-spoke patterns for temperature-sensitive wax-matrix formulations. Manufacturing concentration rests on Indonesia, Philippines, and Côte d'Ivoire for coconut oil and shea butter feedstocks. Raw material dependencies include West African shea nuts, Southeast Asian coconut plantations, and European surfactant production clusters. Single-source vulnerability in botanical extract supply creates exposure to climate-induced harvest failures. Distribution runs through pharmacy and specialty retail channels in developed markets, with online platforms capturing emerging demographic trial.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The deodorant stick market functions as a cost-of-compliance arena where EU Green Deal chemical restrictions and REACH fragrance disclosure mandates erect regulatory moats favoring pre-compliant formulation investments.
For Market Incumbents: To counter digital-native subscription competitors, legacy manufacturers should deepen captive R&D investments in encapsulation technology for extended fragrance release and secure multi-source shea butter procurement contracts across West African agricultural networks. Channel control through pharmacy chain clean-beauty section partnerships provides defensive positioning against direct-to-consumer trial capture. For New Entrants and Emerging Players: Direct-to-consumer subscription platforms represent the most penetrable channel architecture for teenager and unisex demographic conversion that mass retail fails to capture. White-space concentration sits with pre-compliant natural formulations ahead of California and New York state-level disclosure legislation. Sampling-enabled ingredient education campaigns anchor effective go-to-market mechanics. For Investors and Strategic Acquirers: Re-rating potential sits with integrated agricultural sourcing networks given shea butter and coconut oil scale economics stabilizing input cost volatility. Long-term viability over a multi-year horizon favors acquisition targets with captive West African and Southeast Asian feedstock relationships. Watch for EU Green Deal enforcement acceleration as inflection signal for clinical-to-natural formulation migration timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Shea Butter Sourcing | Captive West African agricultural networks stabilize botanical extract input costs against harvest volatility. |
| Encapsulation Technology Licensing | Proprietary extended-release fragrance systems unify clinical performance with clean-label positioning claims. |
| Direct-to-Consumer Subscription Launch | Digital-native mechanics capture teenager and unisex trial that traditional supermarket channels rarely convert. |
| REACH Pre-Compliance Reformulation | Early allergen disclosure investment secures pharmacy shelf space ahead of EU Green Deal enforcement waves. |
| Clean-Beauty Section Partnership | United States pharmacy chain dedicated sections expand distribution for premium natural-positioned variants. |
Methodological Framework
Independent corroboration across formulation chemist interviews, retail category buyer consultations, and regulatory affairs director exchanges underwrites the qualitative findings in this study. Primary fieldwork engaged supply planners at integrated consumer goods conglomerates, procurement leads at regional surfactant suppliers, and channel sales heads at pharmacy chains. Secondary validation drew from FDA OTC monograph filings, ECHA REACH registration databases, EU F-Gas Regulation compliance disclosures, and customs records tracking shea butter and coconut oil trade flows. Bottom-up volume modeling triangulated against top-down value estimates across the analysis window.
Comparable-period anchoring to historical formulation chemistry shifts and regulatory implementation timelines structured the projection horizon. Segmentation dimensions modeled include product type architecture, ingredient chemistry tier, end-user demographic, and distribution channel access pattern. CAGRs derived from volume trajectory analysis incorporating raw material cost elasticity and channel mix evolution. Industry-specific forecast inputs encompass EU Green Deal enforcement phasing and state-level clean beauty legislation progression.
Caveats apply where accelerated EU Green Deal implementation or unanticipated FDA OTC monograph revision could materially shift the outlook. Forecasts reflect documented assumptions around botanical extract cost stabilization and channel migration velocity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Cosmetics & Skincare
China Skincare Market
Cosmetics & Skincare
North America Deodorants Market
Cosmetics & Skincare
Professional Scalp Care Products Market
Cosmetics & Skincare
K-Beauty Products Market
Cosmetics & Skincare
Dark Circles Removing Eye Cream Market
Cosmetics & Skincare
Mushroom Beauty Products Market
Cosmetics & Skincare
Marine Hyaluronic Water Cream Market
Cosmetics & Skincare
Cosmetics OEM and ODM Services Market
Cosmetics & Skincare
South America Cosmetics Products Market
Cosmetics & Skincare
Temporary Tattoo Market
Cosmetics & Skincare
Eye Makeup Market
Cosmetics & Skincare
Botanical Skin Care Ingredients Market
Cosmetics & Skincare
Makeup Setting Powder Market
Cosmetics & Skincare
Natural and Organic Lipstick Market
Cosmetics & Skincare
Color Cosmetics OEM and ODM Market
Cosmetics & Skincare
GCC Halal Cosmetics Market