
 Vertical Mill Market | 2026-2036
Vertical Mill Market Size, Share, and Industry Trends Forecast 2026-2036
Vertical Mill Market Analytics
Chinese heavy machinery foundries is broadening output of cast frames and precision spindles for vertical mill assemblies. DMG MORI leverages its five-axis machining heritage to supply high-tolerance bed mill components to European tool builders. Yamazaki Mazak Corporation anchors its North American installed base through localized spindle service networks and retrofit programs. Pfeiffer SE dominates vertical roller mill supply for cement raw grinding, with particular strength in Middle Eastern clinker lines.
A vertical mill employs a rotating spindle perpendicular to the worktable, with table travel along X and Y axes and spindle movement along Z, typically achieving tolerances of 0.0002 inches in precision configurations; the design suits face milling, end milling, and drilling of large, heavy workpieces in single-setup operations. Bed mill configurations lead capital expenditure in energy-sector turbine housing production, where rigidity demands favor cast-iron box-way construction. CNC technology is displacing manual and hybrid systems in job shops, as FANUC control architectures reduce setup times and enable unattended machining of aerospace structural components.
OSHA machine guarding standards and EPA metalworking fluid emissions rules shape equipment specification and shop-floor compliance costs in the United States. China's MIIT enforces GB standards for machining center energy consumption, directly influencing spindle motor efficiency requirements for domestic and export-bound vertical mills. Stakeholders must monitor how Ecodesign regulations in Europe and carbon-border adjustment mechanisms redirect sourcing patterns for cast-iron structural components.
Market Dynamics
China's GB energy-efficiency standards for industrial equipment are compressing spindle motor specifications across the vertical mill supply base, forcing simultaneous retooling of foundries in Shandong and Jiangsu provinces.
Growth Catalysts
- Cement sector expansion:Clinker producers in India and Vietnam are procuring vertical roller mills for raw meal grinding, with finish-grinding lines driving spindle demand in integrated cement complexes.
- Energy-efficiency mandates:China's MIIT enforces GB standards for machining center energy consumption, pushing domestic and export-bound manufacturers toward higher-efficiency gearless mill drives.
- Steel-cement integration:Coastal manufacturing provinces in China anchor procurement as integrated steel and cement complexes consolidate equipment purchasing power.
Market Restraints
- Cast-iron supply concentration:Heavy machinery foundries in Shandong and Hebei provinces control structural component output, creating geographic chokepoints for precision frame supply.
- Technical limitation in spindle tolerance:Achieving 0.0002-inch precision in large-bed configurations requires specialized five-axis machining capacity that remains scarce outside established European and Japanese supply chains.
- Substitution threat from horizontal machining centers:Aerospace structural component producers are evaluating pallet-based horizontal configurations for multi-face machining of turbine housings.
Strategic Opportunities
- Underpenetrated Southeast Asian markets:Indonesian and Philippine cement producers lack localized vertical roller mill service networks, creating openings for retrofit and spare parts programs.
- Regulatory tailwind from EU Ecodesign:European carbon-border adjustment mechanisms are redirecting sourcing patterns for cast-iron structural components toward certified low-carbon foundries.
- Technology convergence of CNC and IoT:FANUC control architectures are unifying with remote monitoring platforms, enabling unattended machining and predictive spindle maintenance in job shops.
Industry Challenges
- Skill gap in five-axis programming:Job shops face scarcity of operators capable of optimizing tool paths for complex aerospace structural components on vertical configurations.
- Capex intensity for box-way construction:Cast-iron bed mills with rigid box-way designs require substantial upfront investment in foundry and machining capacity.
- Compliance timeline for metalworking fluids:EPA emissions rules for metalworking fluid systems are extending equipment qualification periods in United States manufacturing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Vertical Mill Market |
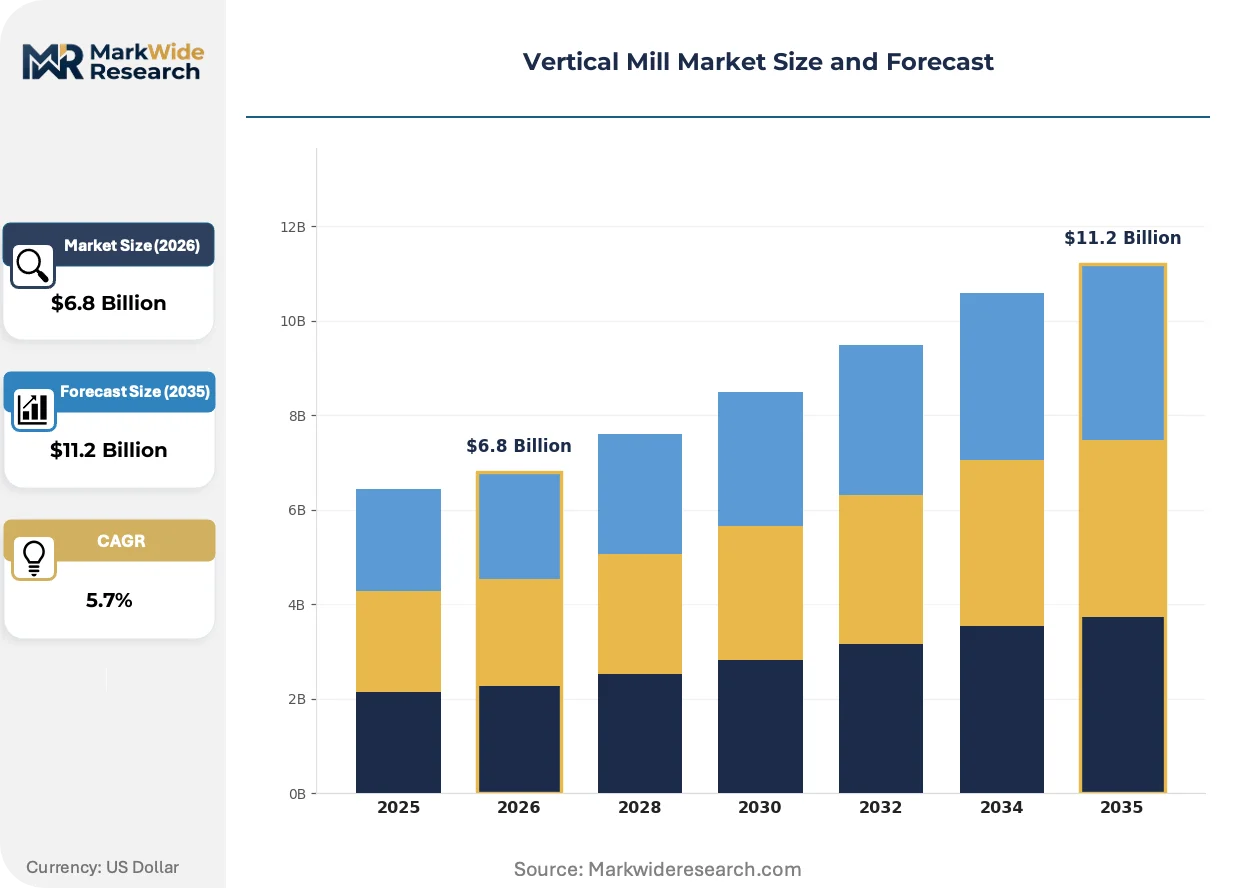
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.2 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
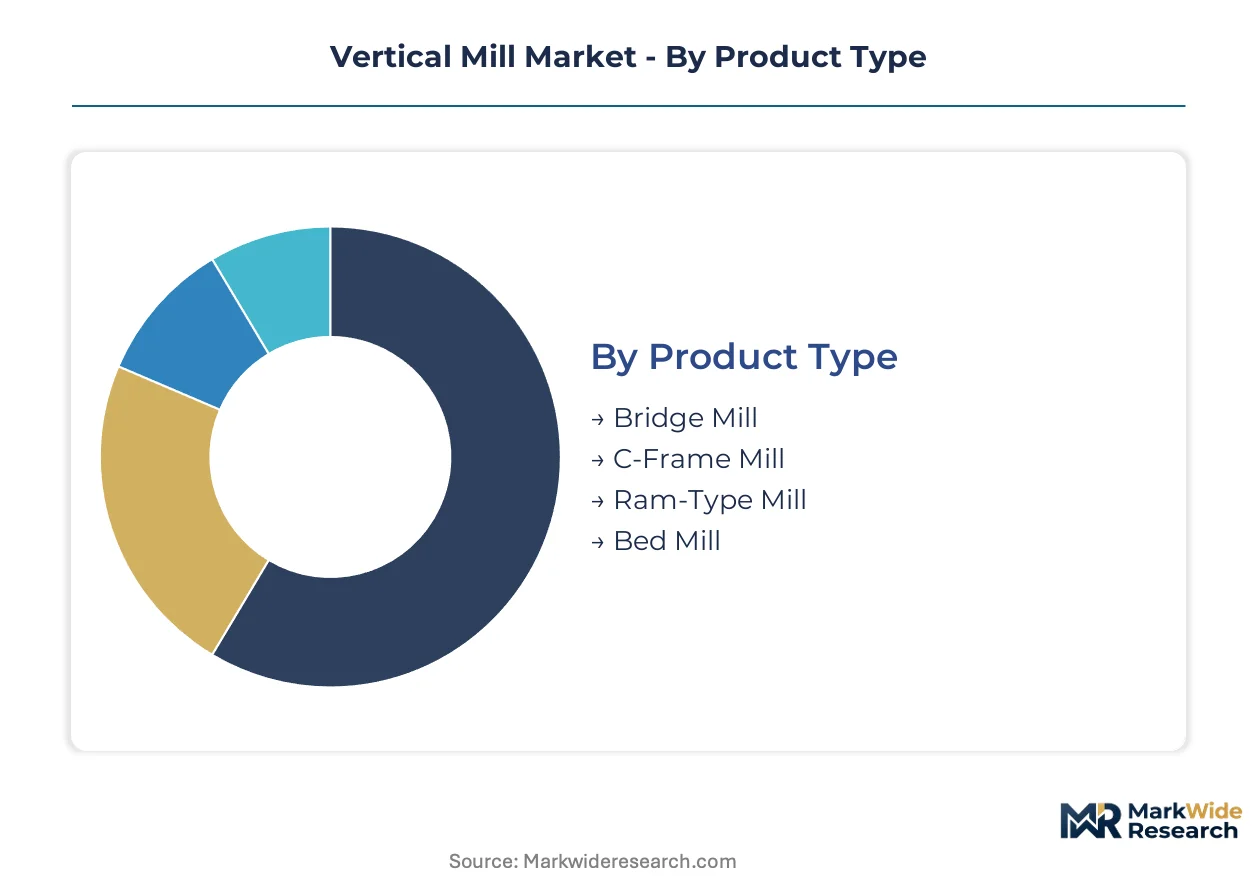
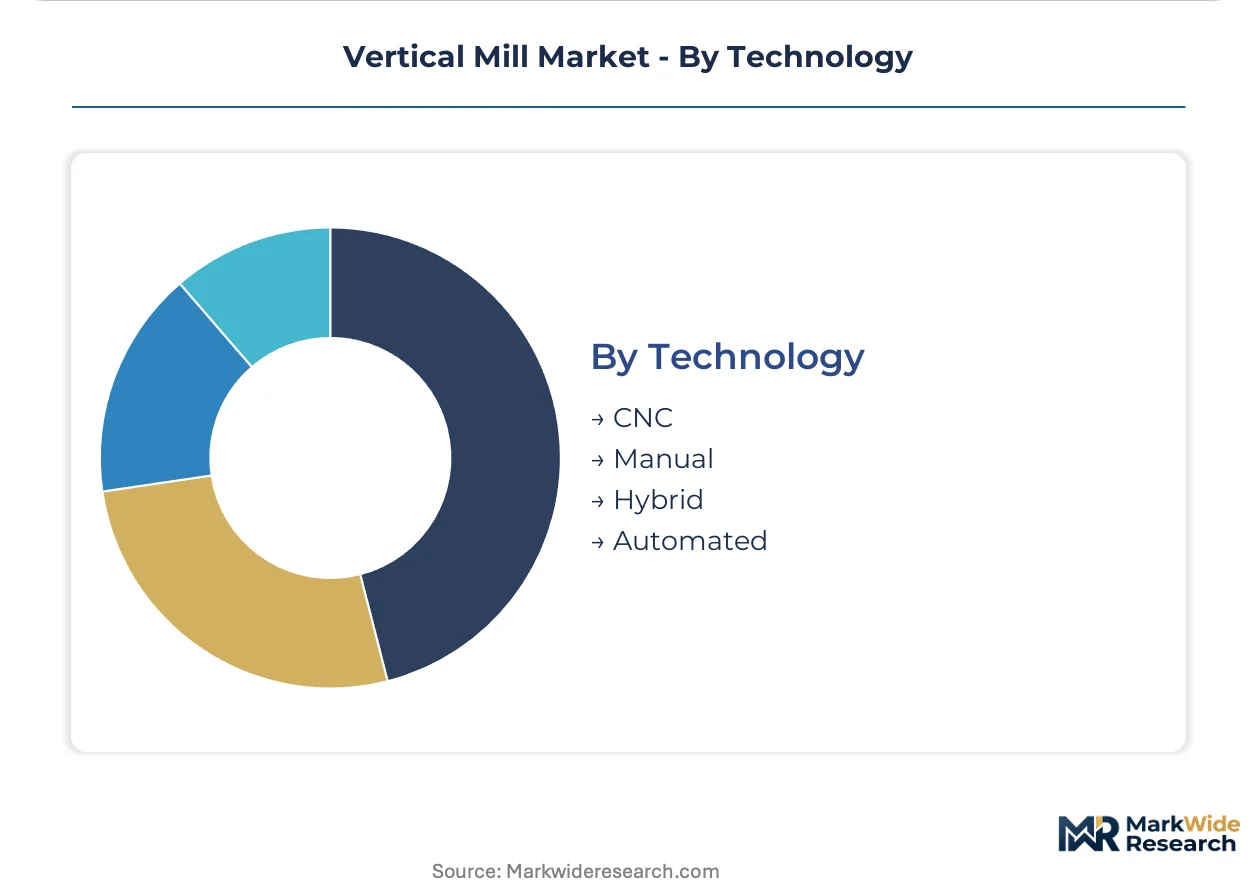
| Segmentation | Product Type: Bridge Mill, C-Frame Mill, Ram-Type Mill, Bed Mill Application: Aerospace, Automotive, Energy, Medical End User: Manufacturers, OEMs, Job Shops, Research Institutions Technology: CNC, Manual, Hybrid, Automated |
| Companies Covered | Haas Automation, Inc., DMG MORI, Yamazaki Mazak Corporation, Okuma Corporation, Hurco Companies, Inc., Mitsubishi Heavy Industries Ltd., Doosan Heavy Industries & Machinery Ltd., Pfeiffer SE, FANUC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Vertical Mill Market Evolving Landscape
Gearless mill drive technology is compressing maintenance intervals and energy profiles across cement and mining applications. Three convergent developments are restructuring competitive positioning in vertical mill supply.
Direct-drive spindle technology is unifying power transmission and rotary motion in a single electromagnetic assembly. Cement producers in the Middle East are adopting these configurations for clinker grinding lines. The technology is unifying formerly separate gearbox, motor, and coupling subsystems into integrated units that reduce footprint and eliminate mechanical wear points.
China's MIIT enforcement of GB energy-efficiency standards for machining centers is tightening spindle motor efficiency requirements. Domestic manufacturers must certify equipment for both domestic sale and export markets. Vertical mill builders in Jiangsu and Zhejiang are responding by redesigning electromagnetic architectures and sourcing higher-grade magnetic materials.
After-sales service unbundling is fragmenting traditional equipment supply contracts. Cement producers in India are separating spindle maintenance, control system upgrades, and retrofits into discrete procurement decisions. This pattern is most visible in Gujarat and Rajasthan, where independent service networks are displacing captive manufacturer technicians for routine spindle rebuilds.
Vertical Mill Market Segmentation
Vertical mill procurement patterns diverge sharply across product configurations and operational technologies. Capital allocation decisions in cement grinding and precision machining drive distinct specification requirements that reshape vendor priorities.
Product Type:
Bed mill configurations demand the heaviest upfront foundry investment for cast-iron box-way construction, while bridge mills require extensive linear guide machining capacity.
- Bed Mill:Cast-iron box-way construction delivers rigidity for heavy workpiece machining in single-setup operations. Energy-sector turbine housing producers in China's coastal provinces anchor procurement, with finish-grinding lines in integrated steel-cement complexes specifying these configurations for face milling and end milling of large components.
- Bridge Mill:Dual-column gantry architecture spans wide work envelopes for aerospace structural components. Demand concentrates in European tool builders sourcing high-tolerance bed mill components, where DMG MORI's five-axis machining heritage supplies precision frame assemblies requiring 0.0002-inch tolerance achievement.
- C-Frame Mill:Single-sided column design suits mid-size job shop applications with moderate rigidity requirements.
- Ram-Type Mill:Overhanging spindle head enables angular positioning for complex geometry machining in research environments.
Bed mill absorbs the bulk of installed capacity; bridge mill is expanding most quickly.
Application:
End-use sectors stratify by tolerance requirements and production volume intensity, with energy and aerospace commanding premium specifications.
- Energy:Turbine housing production requires rigid box-way construction for face milling of large castings. Clinker producers in India and Vietnam drive vertical roller mill procurement for raw meal grinding, with finish-grinding lines in integrated cement complexes specifying gearless mill drive technology.
- Aerospace:Structural component machining demands five-axis programming capability for complex tool paths. Pallet-based horizontal configurations are displacing vertical mills for multi-face machining of turbine housings, creating substitution pressure in this segment.
- Automotive:Powertrain component production favors high-volume CNC configurations with reduced setup times.
- Medical:Implant and instrument machining requires precision spindles with thermal stability control.
Energy maintains the largest equipment base; aerospace is gaining share fastest.
End User:
Procurement authority concentrates differently across captive manufacturing and outsourced machining services.
- Job Shops:CNC technology displacement of manual systems accelerates as FANUC control architectures reduce setup times. Unattended machining capabilities enable aerospace structural component production with predictive spindle maintenance protocols.
- Manufacturers:Integrated steel and cement complexes in China's coastal manufacturing provinces consolidate equipment purchasing power for raw grinding and finish-grinding lines.
- OEMs:Captive production of vertical mill components for aftermarket supply chains.
- Research Institutions:Specialized configurations for prototype development and materials testing.
Manufacturers deploy the most units; job shops are climbing the fastest.
Technology:
Control architecture sophistication determines operator skill requirements and maintenance protocol complexity.
- CNC:FANUC control architectures unify with remote monitoring platforms for predictive spindle maintenance. China's MIIT enforces GB standards for machining center energy consumption, pushing domestic and export-bound manufacturers toward higher-efficiency gearless mill drives with certified electromagnetic architectures.
- Automated:Unattended machining configurations integrate IoT platforms for cement and mining applications. Direct-drive spindle technology unifies power transmission and rotary motion, eliminating mechanical wear points in Middle Eastern clinker grinding lines.
- Manual:Limited to specialty repair operations and training environments.
- Hybrid:Transitional configurations bridging manual operation and CNC retrofit paths.
CNC dominates current installations; automated systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cast-iron foundry clusters in Shandong and Hebei provinces anchor structural component supply for vertical mill assemblies worldwide. These heavy machinery centers feed precision frame demand across cement grinding and aerospace machining end uses. Regulatory pressure on energy efficiency and emissions is redrawing procurement geography.
China
Integrated steel and cement complexes in Jiangsu and Zhejiang provinces drive spindle motor demand for raw meal and finish grinding lines. MIIT enforces GB energy-efficiency standards for machining center energy consumption, forcing domestic manufacturers toward certified electromagnetic architectures. Coastal manufacturing provinces consolidate equipment purchasing power as gearless mill drive adoption accelerates.
Germany
European tool builders source high-tolerance bed mill components for turbine housing production in energy sector applications. Ecodesign regulations and carbon-border adjustment mechanisms redirect sourcing patterns toward certified low-carbon foundries. DMG MORI leverages five-axis machining heritage from its Baden-Württemberg base to supply precision frame assemblies.
United States
Aerospace structural component producers evaluate pallet-based configurations for multi-face machining of turbine housings. OSHA machine guarding standards and EPA metalworking fluid emissions rules extend equipment qualification periods in domestic manufacturing facilities. Job shops in the Midwest and Southeast accelerate CNC displacement of manual systems using FANUC control architectures.
India
Clinker producers in Gujarat and Rajasthan procure vertical roller mills for raw meal grinding, with finish-grinding lines driving spindle demand. Independent service networks displace captive manufacturer technicians for routine spindle rebuilds as after-sales service unbundles. Cement sector expansion concentrates in integrated complexes where localized retrofit programs remain underdeveloped.
Japan
Precision spindle manufacturers anchor North American installed base through localized service networks and retrofit programs. METI industrial standards shape export-bound equipment specifications for thermal stability control in medical implant machining. Yamazaki Mazak Corporation exemplifies the archetype of regional champions building aftermarket presence through technical service density.
Vertical Mill Market Competitive Landscape
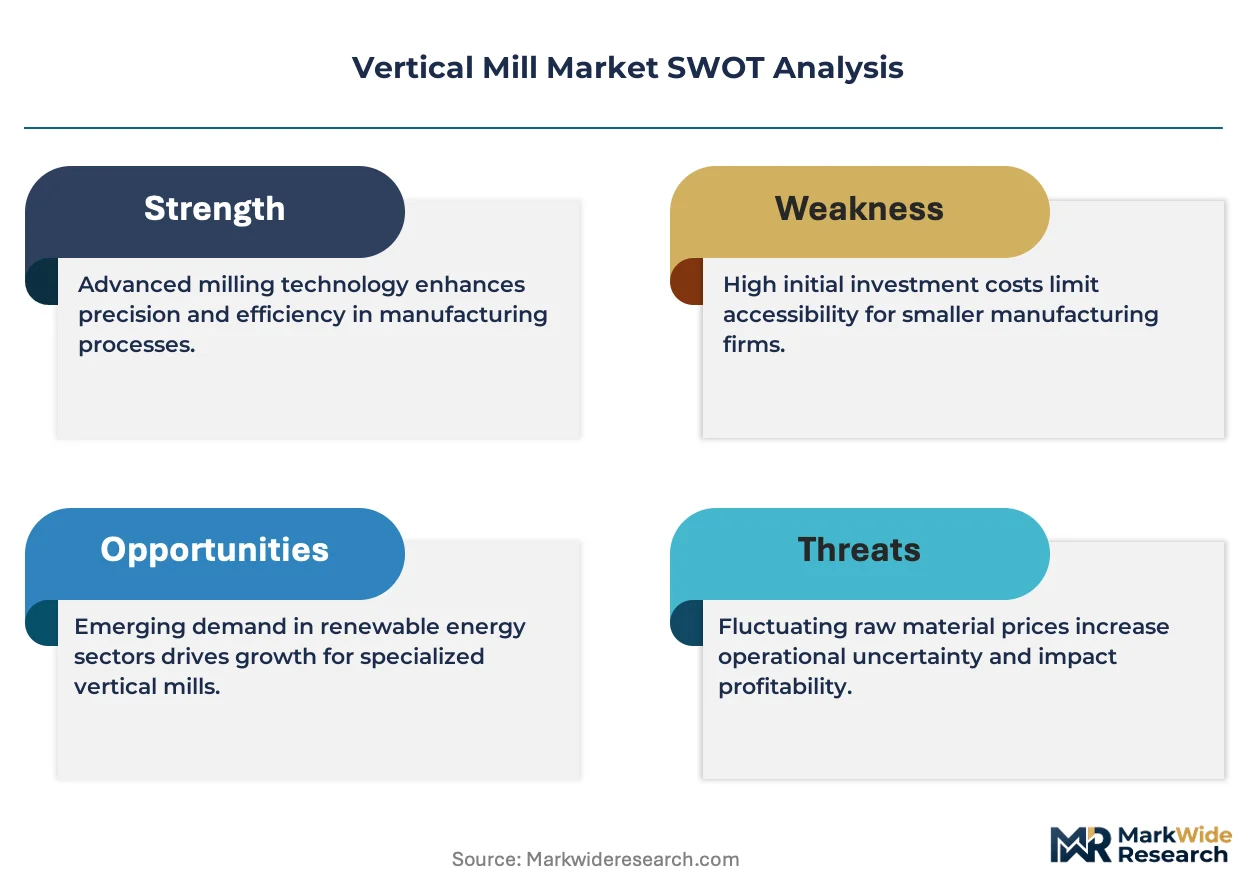
Global majors compete with regional champions across spindle technology and after-sales service density. The supplier base organizes into three tiers: integrated machinery builders with foundry-to-assembly control, precision component specialists focusing on five-axis machining capacity, and regional champions leveraging localized service networks for installed base retention. Dominant competitive moves include backward integration into cast-iron structural component supply and geographic expansion through retrofit program deployment.
Among German-based precision machinery builders, DMG MORI and Pfeiffer SE occupy positions reflecting divergent specialization archetypes. Japanese fabricators Yamazaki Mazak Corporation and Okuma Corporation exemplify regional champions that have built North American presence through technical service infrastructure rather than pure equipment export. Haas Automation, Inc. represents the scale-driven, cost-optimized archetype competing on standardized CNC platform penetration in job shop segments.
| Leading Market Players |
|---|
| Haas Automation, Inc. |
| DMG MORI |
| Yamazaki Mazak Corporation |
| Okuma Corporation |
| Hurco Companies, Inc. |
| Mitsubishi Heavy Industries Ltd. |
| Doosan Heavy Industries & Machinery Ltd. |
| Pfeiffer SE |
| FANUC Corporation |
| Others |
Value Network & Pricing Analysis
Gearless mill drive adoption is compressing both capital expenditure structures and supplier consolidation patterns as electromagnetic architectures displace mechanical subsystems across cement and mining vertical mill installations. China's MIIT enforcement of GB energy-efficiency standards simultaneously raises certification costs for domestic foundries and creates pricing power for certified electromagnetic component suppliers in Jiangsu and Zhejiang provinces.
Pricing Analysis
Warranty and service bundling fragmentation is reshaping procurement economics as cement producers in Gujarat and Rajasthan unbundle spindle maintenance from initial equipment contracts. Three-tier pricing structure across premium certified, standard compliant, and economy non-certified levels reflects GB standard adherence and foundry origin. Pricing pressure stems from independent service networks undercutting manufacturer captive pricing for routine spindle rebuilds. Job shops demonstrate highest price sensitivity due to CNC retrofit budget constraints, while integrated steel-cement complexes absorb premium pricing for gearless configurations.
Supply Chain Analysis
Skilled five-axis programming workforce scarcity in Shandong and Hebei provinces is constraining precision frame output for high-tolerance vertical mill assemblies. Geographic supply concentration centers on China's coastal foundry clusters, Germany's Baden-Württemberg precision machining belt, and Japan's Nagoya-Osaka spindle manufacturing corridor. Raw material dependencies include high-grade cast iron for box-way construction, rare-earth magnetic materials for direct-drive spindles, and precision ball screw assemblies. Single-source vulnerability runs through China's dominance in rare-earth processing. Distribution runs through OEM direct sales for large cement installations and regional distributor networks for job shop CNC configurations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
China's MIIT GB energy-efficiency standards erect a cost-of-compliance moat that favors incumbent foundries with certified electromagnetic architectures and capital reserves for retooling. This regulatory barrier fragments competitive access between certified and non-certified supplier tiers.
For Market Incumbents: Lock in captive foundry capacity through backward integration into Shandong and Hebei cast-iron supply, securing structural component availability against geographic chokepoint risks. Expand localized spindle service networks in Southeast Asian cement markets to preempt independent technician displacement. Prioritize certification investment for GB standard compliance to maintain access to China's domestic and export-bound equipment demand.
For New Entrants and Emerging Players: Enter via aftermarket retrofit and spare parts programs in Indonesian and Philippine cement markets where localized vertical roller mill service networks remain underdeveloped. Target bridge mill configurations for European aerospace structural component producers seeking five-axis machining capacity outside established Japanese supply chains. Pursue partnership-based go-to-market models with FANUC control architecture integrators to bypass captive OEM service infrastructure.
For Investors and Strategic Acquirers: Exit pathways concentrate in precision component specialists with certified five-axis machining capacity and established aftermarket service density. Long-term viability favors suppliers with backward integration into cast-iron structural components and electromagnetic architecture design capability. Watch for inflection signals in carbon-border adjustment mechanism enforcement redirecting European sourcing patterns toward certified low-carbon foundries.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cast-Iron Foundry Capacity | Secures structural component supply against Shandong and Hebei geographic chokepoints for precision frame output. |
| GB Energy-Efficiency Certification Investment | Unlocks domestic Chinese market access and export eligibility under MIIT enforcement protocols. |
| Localized Aftermarket Service Network Expansion | Captures retrofit and spare parts demand in Southeast Asian cement markets with unbundled procurement patterns. |
| Direct-Drive Spindle Technology Licensing | Accelerates gearless mill drive adoption in Middle Eastern clinker grinding lines through electromagnetic subsystem integration. |
| Joint Venture with FANUC Control Integrators | Enables unattended machining and predictive maintenance capabilities for aerospace job shop penetration. |
Research Methodology
Trade association filings, customs and trade flow databases, and equipment registration records formed the secondary backbone for demand quantification and supply mapping. Primary interviews with maintenance directors at integrated cement complexes, plant engineers in steel-cement operations, OEM procurement teams specifying vertical mill configurations, and aftermarket service heads in North American and Southeast Asian markets validated capacity utilization and procurement pattern assumptions. Bottom-up installation base analysis triangulated against top-down capital expenditure tracking across energy, aerospace, and cement end-use sectors.
Historical trendline analysis of spindle motor efficiency trajectories and foundry capacity expansion patterns anchored the projection framework. Segmentation modeling incorporated product type differentiation between bed mill and bridge mill configurations, application intensity across energy and aerospace end uses, and technology tiers from manual through automated CNC architectures. CAGRs derived from equipment replacement cycle analysis and regulatory compliance-driven upgrade demand. Forecast inputs included MIIT GB standard enforcement timelines and carbon-border adjustment mechanism implementation patterns affecting cast-iron sourcing.
Revisions become necessary when GB standard enforcement intensity shifts, rare-earth material export restrictions materialize, or carbon-border mechanisms accelerate European sourcing redirection. Forecasts reflect documented assumptions regarding foundry capacity expansion and certification adoption curves. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Earthmoving Equipment Tyres Market
Construction Equipment
Rockbreakers Market
Construction Equipment
Heating Roller Press Calender Machine Market
Construction Equipment
Global Compact Construction Equipment Market
Construction Equipment
Bitumen Testing Equipment Market
Construction Equipment
Sweden Construction Equipment Market
Construction Equipment
Case Erectors Market
Construction Equipment
Electric Excavators Market
Construction Equipment
Hydraulic Packers Market
Construction Equipment
Mini Cranes Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
Yard Crane Market
Construction Equipment
Heavy Duty IBC Market
Construction Equipment
Asia Pacific Construction Equipment Rental Market
Construction Equipment
Global Seam Welding Machine Market
Construction Equipment
BRICS Aerial Work Platforms Market