
 Green/Intelligent Buildings Market | 2026-2036
Green/Intelligent Buildings Market Size, Share, and Industry Trends Forecast 2026-2036
Green/Intelligent Buildings Market Foresight
Buyer consolidation among commercial real estate portfolios is repositioning vendor relationships toward platform-level contracts rather than point solutions. Siemens AG leverages its digital twin infrastructure to anchor large-scale campus deployments. Schneider Electric differentiates through edge-to-cloud energy orchestration software that sustains recurring revenue attachment. Honeywell International Inc. competes on installed base migration, converting legacy building management systems into connected environments without full hardware replacement.
Green and intelligent buildings integrate automated environmental controls, sensor networks, and renewable energy systems to optimize energy consumption, occupant comfort, and operational carbon intensity. These structures employ IoT-enabled HVAC modulation, real-time air quality monitoring, and photovoltaic-thermal hybrid generation to achieve sub-100 kWh per square meter annual performance targets in advanced implementations. Smart HVAC and energy management systems lead technology adoption where payback periods compress through utility demand-response incentives. Cloud-based control architectures capture the fastest expansion within control system deployment, though on-premises retains preference in data center and defense applications where latency and sovereignty constraints apply.
The EU Green Deal and national building codes in Germany, France, and the Netherlands mandate progressive energy performance certificates and operational carbon disclosure, forcing capital allocation toward retrofit and new construction compliance. The EPA's ENERGY STAR certification and the IRA's efficiency tax credits shape United States demand by altering project finance structures and owner-operator investment horizons. Stakeholders must monitor regulatory tightening on embodied carbon standards, as scope three emissions accounting threatens to shift competitive advantage toward suppliers with verified low-carbon material supply chains and lifecycle transparency tools.
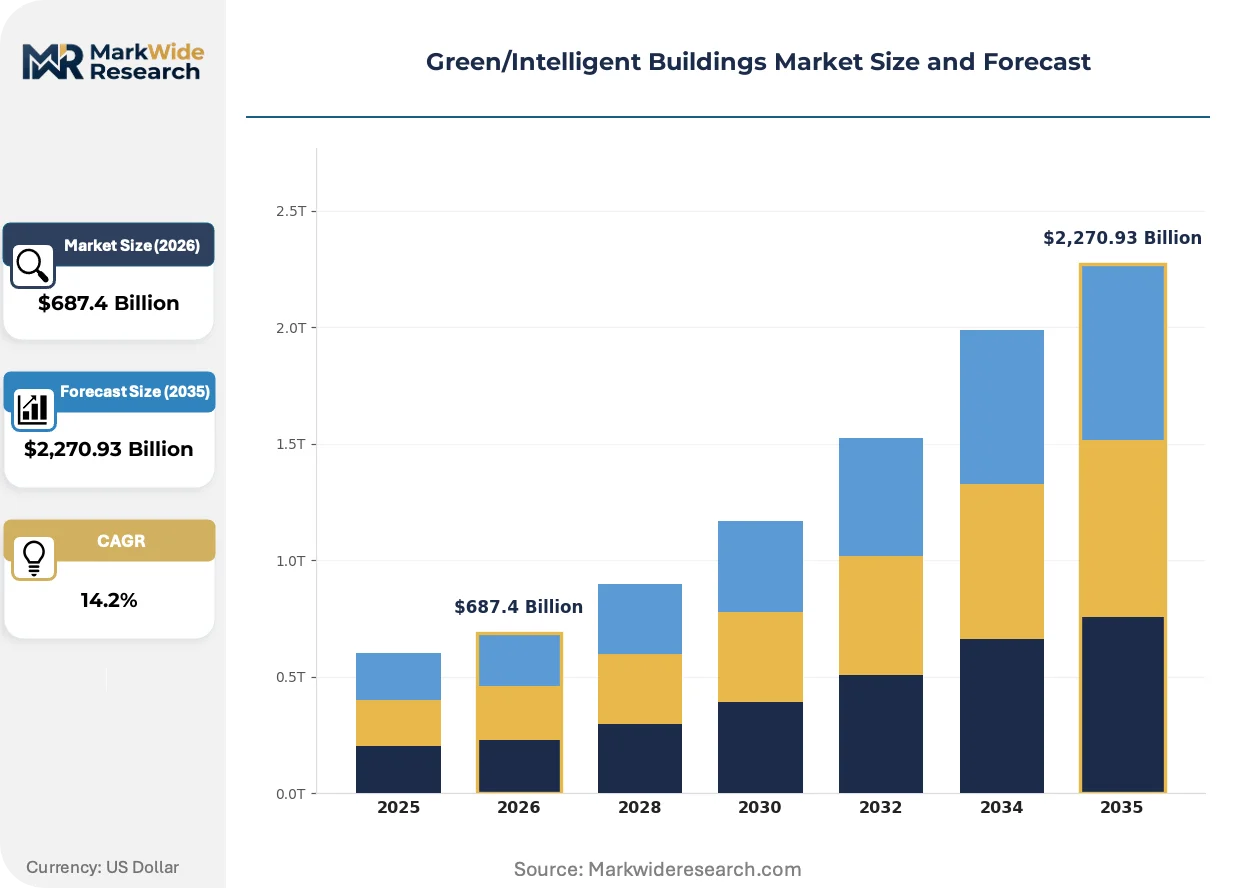
Market Dynamics
Commercial real estate portfolios are consolidating procurement around integrated building platforms, forcing vendors to restructure from point-solution sales toward multi-year platform contracts spanning HVAC, energy management, and digital twin infrastructure.
Growth Catalysts
- EU Green Deal retrofit mandates:Germany, France, and the Netherlands impose progressive energy performance certificates that compel capital allocation toward compliance-driven building upgrades.
- Smart HVAC modulation:IoT-enabled systems with sub-100 kWh per square meter targets compress payback periods through utility demand-response incentives in advanced implementations.
- China's dual carbon goals:Municipal smart city investments overlap with building efficiency mandates, concentrating deployment in tier-one urban clusters.
Market Restraints
- Semiconductor supply concentration:Sensor and controller chip fabrication concentrates in East Asian foundries, exposing project timelines to geopolitical disruption.
- Skilled technician scarcity:Building automation system commissioning requires certified integration specialists whose training pipelines lag deployment demand.
- Embodied carbon accounting gaps:Scope three emissions verification lacks standardized methodologies, delaying low-carbon material specification in procurement.
Strategic Opportunities
- India's PLI scheme for efficiency:Domestic manufacturing incentives for HVAC and solar-thermal components reduce import dependency for commercial retrofit projects.
- Edge-to-cloud orchestration convergence:Energy management software integrating real-time grid signals with on-premise control opens recurring revenue streams.
- Data center sovereignty requirements:On-premises control architectures retain preference where latency constraints and national data localization rules apply.
Industry Challenges
- BMS integration complexity:Legacy building management system protocols fragment across vendor ecosystems, requiring costly middleware development for unified dashboards.
- Certification timeline compression:EPA ENERGY STAR and national building performance standards demand documentation workflows that strain owner-operator administrative capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green/Intelligent Buildings Market |
| Market Size in 2026 | $687.4 Billion |
| Market Size in 2035 | $2,270.93 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart HVAC, Energy Management Systems, IoT Sensors, Renewable Energy Integration End User: Commercial Buildings, Residential Homes, Industrial Facilities, Retail Spaces Installation Type: New Construction, Retrofit, Modular, Hybrid Control System: Centralized, Decentralized, Cloud-Based, On-Premises |
| Companies Covered | Siemens AG, Honeywell International Inc., Schneider Electric, Johnson Controls, ABB Ltd., IBM Corporation, Cisco Systems, Inc., Legrand, Bosch, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green/Intelligent Buildings Market Shifts & Advancements
Digital twin infrastructure is rewriting competitive positioning in the building controls sector, compressing the gap between design-phase simulation and operational optimization. Vendors now compete on real-time fidelity rather than hardware specifications alone.
Photovoltaic-thermal hybrid generation is rewriting how commercial rooftops monetize energy assets. Large-format retail and logistics facility operators in Germany and the United States are deploying these systems at scale. The technology is rewriting project finance structures by combining on-site generation with thermal storage in single capital allocations.
The EU F-Gas Regulation is phasing down hydrofluorocarbon refrigerants in commercial HVAC systems. Equipment manufacturers must redesign compressor architectures around low-global-warming-potential alternatives. Cold storage and supermarket verticals face the steepest retrofit obligations, accelerating adoption of CO2 transcritical systems in Northern European markets.
Building-as-a-service contracting is displacing traditional equipment ownership models among institutional investors. Pension funds and REITs in the United Kingdom and Australia now prefer operational expenditure structures with guaranteed efficiency outcomes. Facility management teams surrender capital risk to vendors in exchange for performance-linked service agreements.
Green/Intelligent Buildings Market Segmentation
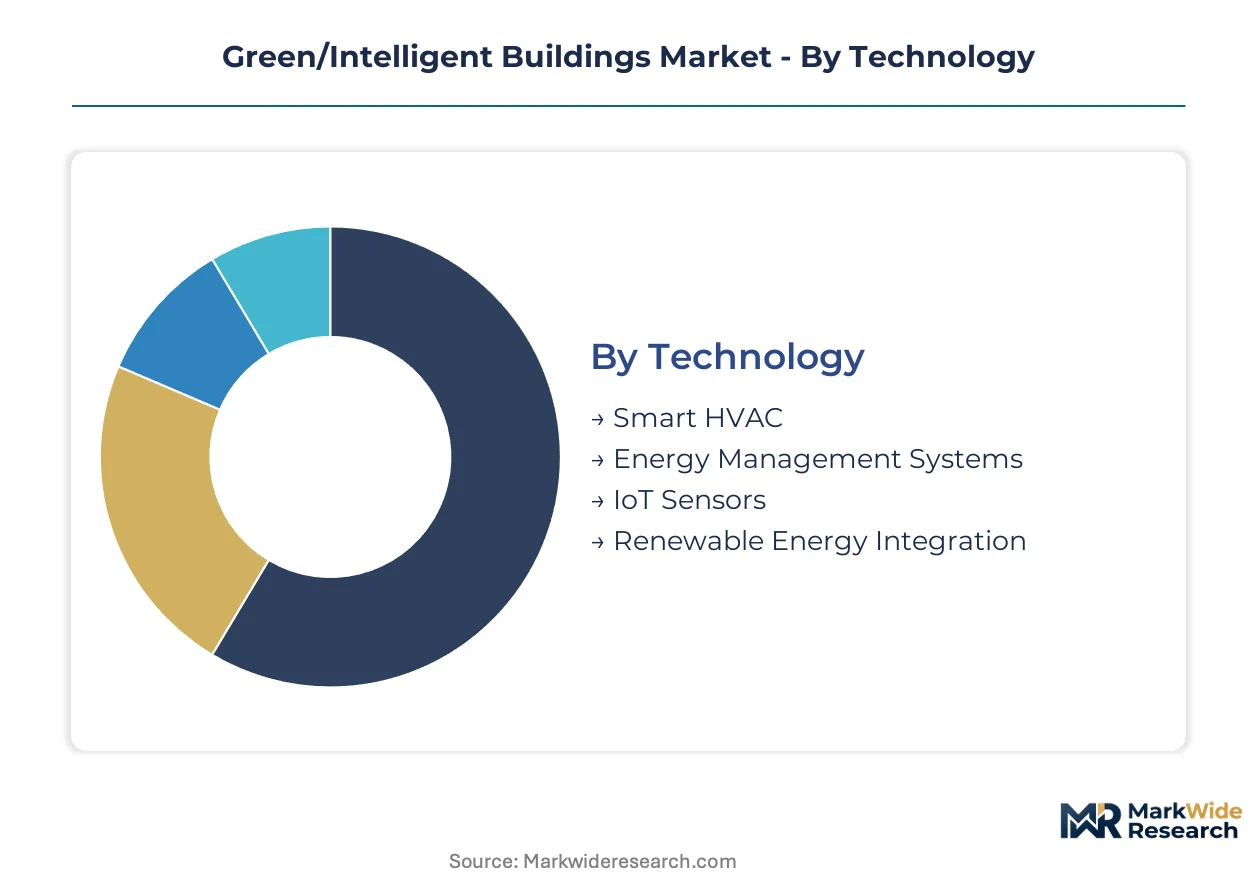
Technology heterogeneity in green buildings demands precise segmentation to align procurement decisions with regulatory compliance timelines and operational carbon targets. Vendor positioning and buyer consolidation patterns diverge sharply across installation maturity, control architecture, and end-use intensity.
Technology:
Standardization dominates HVAC and energy management platforms, while IoT sensor configurations remain highly customized to building topology and occupancy patterns.
- Smart HVAC:Systems modulate thermal output through real-time occupancy detection and weather forecasting algorithms. Demand concentrates in German commercial retrofits where the EU Green Deal mandates progressive energy performance certificates and F-Gas refrigerant phase-downs.
- Energy Management Systems:Software platforms aggregate consumption data across electrical, thermal, and water systems for automated load balancing. Large US office portfolios under EPA ENERGY STAR compliance programs drive procurement, with IRA tax credits compressing owner-operator payback horizons.
- IoT Sensors:Air quality, occupancy, and equipment health monitors feed edge-to-cloud analytics pipelines.
- Renewable Energy Integration:Photovoltaic-thermal hybrid systems and battery storage controllers optimize on-site generation dispatch.
Leading the category by volume: Smart HVAC. Growing fastest: Energy Management Systems.
End User:
Cost tiers separate capital-intensive commercial deployments from residential scalability constraints, with industrial facilities occupying a middle band of process-critical customization.
- Commercial Buildings:Office towers and mixed-use developments deploy integrated digital twin infrastructure for whole-building optimization. China's tier-one municipal smart city investments overlap with dual carbon mandates, concentrating deployment in Beijing and Shanghai clusters.
- Residential Homes:Single-family and multi-family units prioritize plug-and-play thermostat and lighting automation over deep system integration. German KfW efficiency financing programs and Netherlands building code tightening accelerate mass-market penetration.
- Industrial Facilities:Manufacturing plants and warehouses require hardened controls for process thermal management and emissions monitoring.
- Retail Spaces:Large-format stores and logistics centers monetize rooftop solar-thermal assets through power purchase agreements.
Commercial Buildings anchor procurement volume. Residential Homes climb fastest as financing mechanisms democratize access.
Installation Type:
Application urgency distinguishes compliance-driven retrofits from design-integrated new construction, with hybrid approaches gaining traction in phased campus expansions.
- New Construction:Digital twin simulation and embedded sensor infrastructure are specified at design phase. Netherlands and France mandate near-zero energy building standards for new permits, forcing developer capital allocation toward integrated platform procurement.
- Retrofit:Legacy building management system upgrades dominate EU Green Deal compliance spending. Germany's building stock renovation obligation targets multi-family residential and public sector portfolios with binding efficiency thresholds.
- Modular:Prefabricated plant rooms and facade-integrated systems reduce on-site commissioning complexity.
- Hybrid:Phased deployments combine targeted retrofits with new construction wings in campus settings.
Retrofit commands current spending. New construction captures emerging share as building codes tighten.
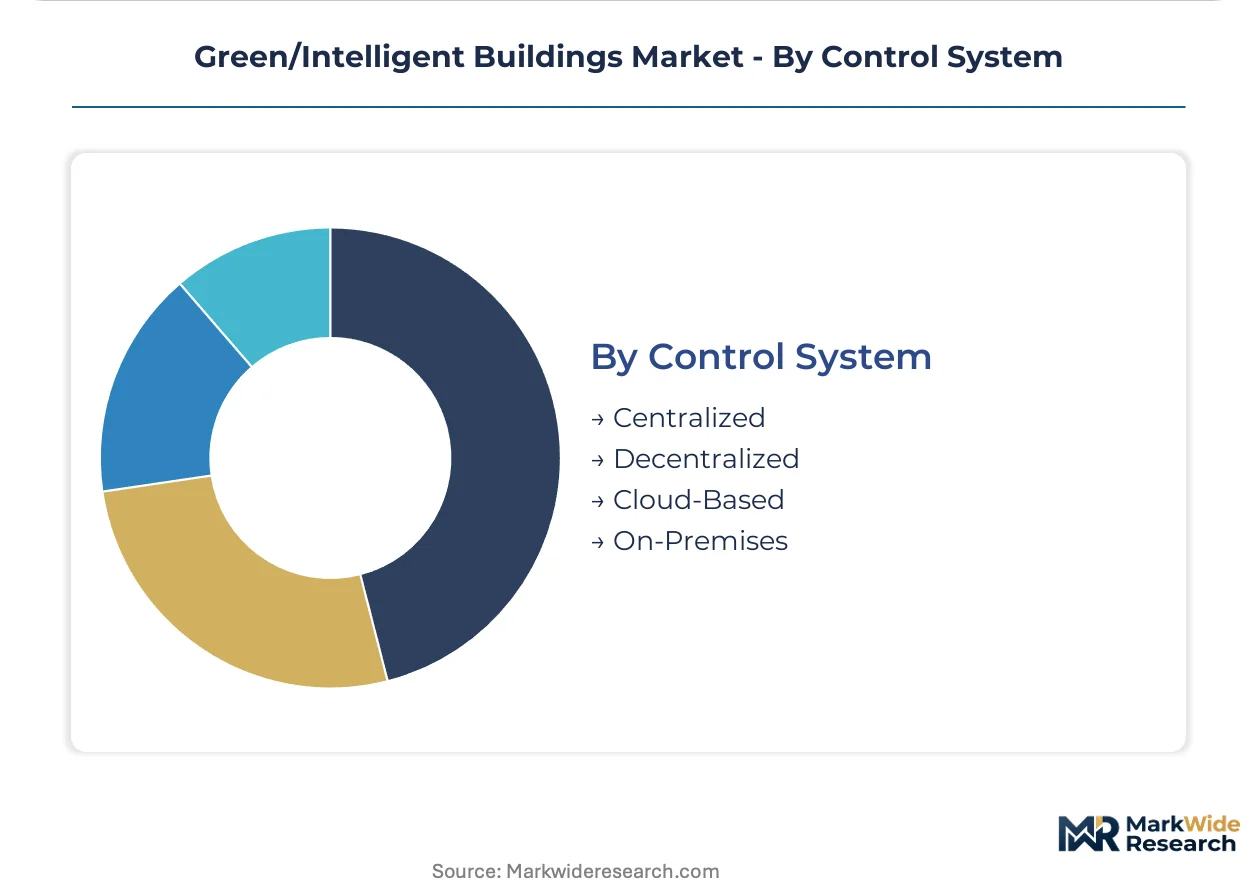
Control System:
Customer type separates enterprise-grade cloud architectures from sovereignty-sensitive on-premises deployments in defense and critical infrastructure.
- Cloud-Based:Centralized data aggregation enables machine learning optimization across distributed building portfolios. US commercial real estate investment trusts favor multi-tenant SaaS platforms for operational expenditure flexibility and guaranteed efficiency outcomes.
- On-Premises:Localized control servers satisfy latency constraints and national data localization requirements. China's data sovereignty regulations and German critical infrastructure protection standards preserve demand for air-gapped architectures in government and defense facilities.
- Centralized:Single control hub manages all building systems through unified dashboards.
- Decentralized:Edge controllers operate autonomously with intermittent cloud synchronization.
Cloud-Based leads deployment share. On-Premises retains preference where regulatory constraints apply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates where retrofit obligations intersect with smart city capital deployment. Germany, the United States, and China anchor procurement volume through divergent regulatory mechanisms and municipal investment programs.
United States
Commercial real estate investment trusts consolidate procurement around integrated building platforms. The EPA's ENERGY STAR certification and the IRA's efficiency tax credits reshape project finance structures. Large-format retail and logistics facility operators in California and Texas deploy photovoltaic-thermal hybrid systems at scale.
Germany
The EU Green Deal mandates progressive energy performance certificates and operational carbon disclosure. The F-Gas Regulation phases down hydrofluorocarbon refrigerants in commercial HVAC systems. Cold storage and supermarket verticals in Bavaria and North Rhine-Westphalia accelerate adoption of CO2 transcritical systems.
China
Municipal smart city investments overlap with dual carbon mandates in tier-one urban clusters. National data sovereignty regulations preserve demand for air-gapped control architectures. Beijing and Shanghai concentrate deployment of digital twin infrastructure for whole-building optimization.
Netherlands
Building codes mandate near-zero energy standards for new construction permits. KfW efficiency financing programs accelerate mass-market penetration in residential segments. The Randstad region forces developer capital allocation toward integrated platform procurement.
India
The PLI scheme for efficiency reduces import dependency for HVAC and solar-thermal components. Domestic manufacturing incentives target commercial retrofit projects. Maharashtra and Gujarat host the fastest-growing deployment of edge-to-cloud energy orchestration software.
Green/Intelligent Buildings Market Competitive Landscape
German producers anchor one tier; French specialists hold differentiated positions in energy orchestration software. The vendor base structures around three tiers: diversified industrial conglomerates with digital twin infrastructure, pure-play building automation specialists, and cloud-native software entrants. Strategic moves concentrate on platform-level contract consolidation and edge-to-cloud capability integration.
Within the diversified industrial tier, Siemens AG and Honeywell International Inc. exemplify archetypes competing on installed base migration and legacy system conversion. Schneider Electric occupies a position bridging hardware and recurring software revenue models. These three anchors represent the competitive tension between comprehensive platform provision and specialized energy management depth.
| Leading Market Players |
|---|
| Siemens AG |
| Honeywell International Inc. |
| Schneider Electric |
| Johnson Controls |
| ABB Ltd. |
| IBM Corporation |
| Cisco Systems, Inc. |
| Legrand |
| Bosch |
| Others |
Supply & Pricing Matrix
The EU Green Deal's progressive energy performance certificate mandates gate qualified supply access for building automation vendors while stratifying procurement tiers around verified carbon transparency. Buyers without documented lifecycle data face exclusion from premium-tier platform contracts, compressing margins for point-solution providers unable to meet disclosure thresholds.
Pricing Analysis
Volume concentrates in standardized HVAC and energy management platforms while margin accrues to digital twin infrastructure with recurring SaaS attachment. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service bundling. Cost compression in economy-tier sensor hardware is intensifying because of semiconductor oversupply in East Asian foundries. Residential retrofit buyers in Germany and the Netherlands exhibit highest price sensitivity; data center operators in defense-critical applications show lowest sensitivity due to sovereignty requirements.
Supply Chain Analysis
India's PLI scheme for efficiency components and China's dual carbon manufacturing mandates are reshaping sourcing patterns for HVAC and solar-thermal equipment. Sensor and controller chip fabrication draws from Taiwan, South Korea, and mainland China, creating single-source vulnerability for IoT-enabled building systems. Copper and rare earth magnet dependencies for motor drives and power electronics feed from Chile and DRC respectively. Distribution runs through EPC contractors and systems integrators with certified commissioning capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Green/Intelligent Buildings Market has become a vertical-integration race where control over edge-to-cloud software stacks determines platform contract capture. Incumbents and challengers alike are pursuing downstream service revenue to escape hardware commoditization.
For Market Incumbents: Deploy digital twin infrastructure as the anchor lever to convert legacy building management system installed bases into recurring SaaS relationships. Consolidate middleware development capabilities to resolve protocol fragmentation across vendor ecosystems. Counter cloud-native software entrants by embedding energy orchestration algorithms directly into HVAC hardware controllers, preserving data gravity at the edge. For New Entrants and Emerging Players: The IRA's efficiency tax credits in the United States open a window for modular retrofit specialists targeting commercial office portfolios with guaranteed outcome contracts. White space concentrates in India's PLI-subsidized domestic manufacturing corridor and in edge-to-cloud orchestration for data center sovereignty deployments. Pursue partnership routes with REITs seeking operational expenditure structures rather than capital equipment sales cycles. For Investors and Strategic Acquirers: Platform-level contract announcements from commercial real estate investment trusts are the leading indicator that vendor consolidation is accelerating toward multi-year recurring revenue models. Over a five-to-ten year horizon, pure-play building automation specialists with certified integration workforces represent the most defensible acquisition profile. Monitor F-Gas refrigerant phase-down compliance timelines as the signal for HVAC equipment replacement demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Infrastructure Deployment | Siemens AG anchors campus-scale contracts through real-time fidelity differentiation from design to operations. |
| Edge-to-Cloud Energy Orchestration | Schneider Electric sustains recurring revenue attachment by integrating grid signals with on-premise control. |
| Legacy System Migration Services | Honeywell International Inc. captures installed base conversion without full hardware replacement capital burden. |
| Photovoltaic-Thermal Hybrid Integration | German and US retail operators monetize rooftop assets through combined generation and thermal storage. |
| CO2 Transcritical System Adoption | Cold storage verticals in Northern Europe accelerate retrofit to meet F-Gas Regulation phase-down mandates. |
Research Methodology
SEC filings from publicly traded building automation vendors, EU regulatory disclosure databases, and IEA building efficiency reports formed the secondary backbone of this analysis. Primary interviews with facility management directors, EPC contractor procurement leads, building automation system commissioning specialists, and smart city investment officers at municipal development agencies combined with secondary validation. Bottom-up and top-down triangulation cross-checked vendor shipment data against national building code compliance timelines and utility demand-response program enrollment statistics.
Bottom-up modeling segmented the market by technology platform, end-use intensity, installation type maturity, and control architecture sovereignty requirements across the projection horizon. CAGRs derived from fitted adoption curves weighted by regulatory enforcement schedules and smart city capital deployment cycles. Forecast inputs included utility tariff restructuring trajectories, semiconductor foundry capacity expansion announcements, and skilled technician training pipeline graduation rates.
The model assumes a particular technology adoption path; alternative pathways for digital twin fidelity standards would alter the outlook if open interoperability protocols displace proprietary vendor stacks. Forecasts reflect assumptions around EU Green Deal enforcement consistency, IRA tax credit continuity, and China dual carbon mandate municipal implementation pace. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Bahrain Facility Management Market
Real Estate
China Office Real Estate Market
Real Estate
Asia Pacific Flexible Office Market
Real Estate
Croatia Facility Management Market
Real Estate
Real Estate Investment Trust (REIT) Market
Real Estate
United States Manufactured Homes Market
Real Estate
India Co-Working Office Spaces Market
Real Estate
Slovenia Facility Management Market
Real Estate
GCC Facility Management Market
Real Estate
Germany Manufactured Homes Market
Real Estate
United Kingdom Flexible Office Space Market
Real Estate
China Residential Real Estate Market
Real Estate
Myanmar Residential Real Estate Market
Real Estate
United States Rental Rate for Residential Real Estate Market
Real Estate
North America Warehousing and Storage Market
Real Estate
Asia-Pacific Self Storage Market