
 North America Warehousing and Storage Market | 2026-2036
North America Warehousing and Storage Market Size, Share, and Industry Trends Forecast 2026-2036
North America Warehousing and Storage Market Intelligence
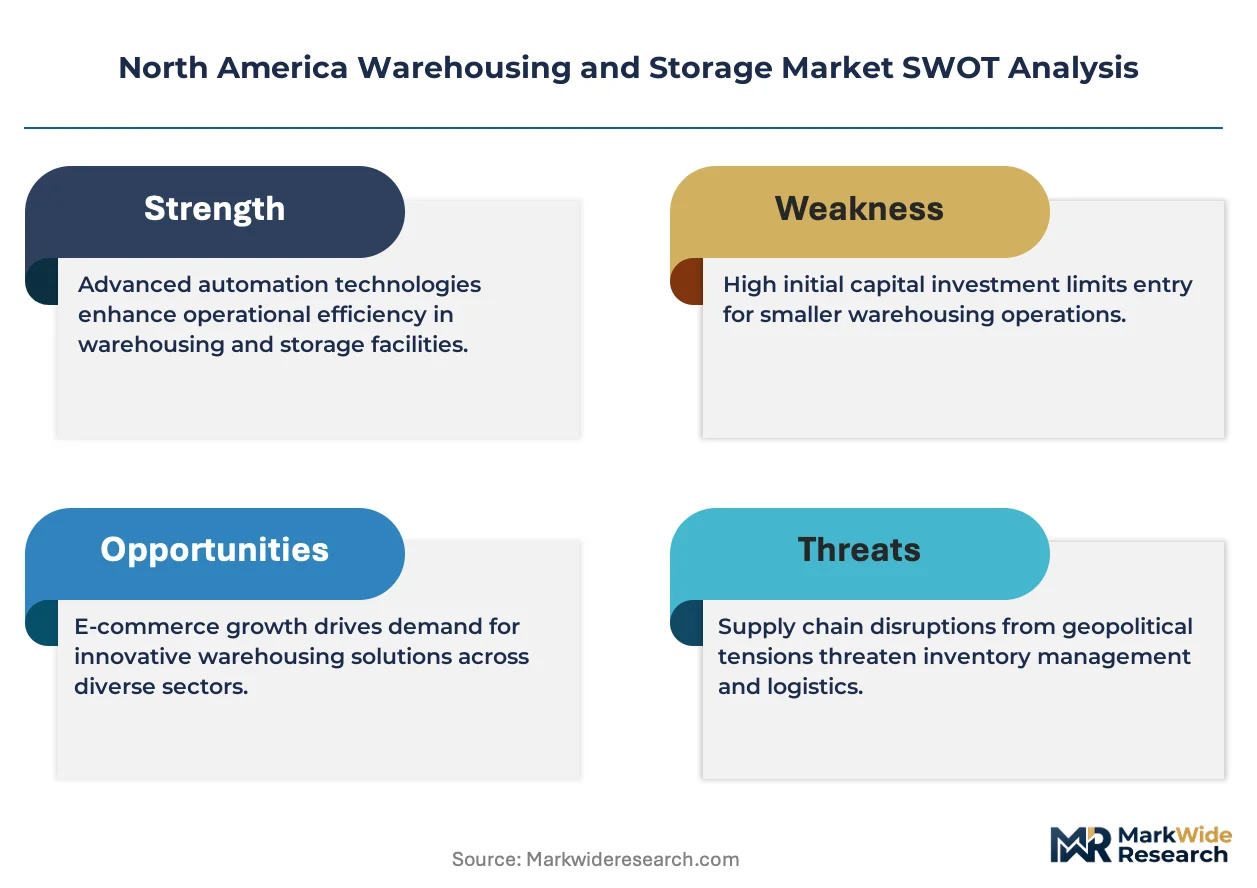
Automation in warehouse management systems is fragmenting traditional operator roles and reshaping facility design across North America. Amazon.com leverages proprietary robotics integration to control fulfillment velocity at scale. Lineage Logistics anchors temperature-controlled networks through specialized cold-storage infrastructure. GXO Logistics competes on multi-client contract flexibility, extending automation deployment across divergent retail and manufacturing accounts.
Warehousing and storage encompasses the physical infrastructure, equipment systems, and operational services for receiving, handling, and dispatching goods within supply chain networks, typically involving racking structures exceeding 20 feet in height, climate-controlled zones, and inventory tracking protocols. The primary commercial purpose centers on temporal buffering between production cycles and consumption demand, reducing stockout risk and transportation cost. Cold storage services command premium margin pools due to pharmaceutical and protein supply chain requirements, while automated storage systems represent the fastest-growing product category as labor scarcity intensifies capital substitution. Shared storage models sustain appeal among mid-market manufacturers seeking variable cost structures without facility ownership burdens.
The Federal Motor Carrier Safety Administration governs driver hours-of-service rules that directly shape cross-dock timing and warehouse labor scheduling across the United States. OSHA warehouse safety standards mandate fall protection, equipment certification, and ergonomic protocols that elevate facility compliance costs and influence automation investment decisions. Canada's Transportation of Dangerous Goods Regulations and Mexico's NOM standards for industrial safety create additional compliance layers for tri-national operators. Stakeholders must monitor regulatory harmonization progress under the United States-Mexico-Canada Agreement framework to anticipate inspection protocol convergence or divergence that will reshape cross-border inventory positioning strategies.
Market Dynamics
Automation capital deployment is compressing labor-dependent operating models across North American warehousing, with robotics integration now determining facility throughput ceilings and site selection criteria.
Growth Catalysts
- OSHA warehouse safety standards:Compliance mandates for fall protection and ergonomic protocols are accelerating capital substitution toward automated storage and retrieval systems.
- Pharmaceutical cold chain expansion:Temperature-controlled infrastructure investment is intensifying across protein and vaccine distribution networks, pulling specialized warehousing demand.
- Texas Triangle logistics corridor:Concentrated distribution center construction across Dallas-Fort Worth, Houston, and San Antonio is creating regional capacity anchors for cross-border fulfillment.
Market Restraints
- Steel and concrete input volatility:Racking structures exceeding 20 feet and climate-controlled shell construction face material cost swings that freeze project timelines.
- Equipment supplier concentration:Automated storage and retrieval system providers cluster in German and Japanese manufacturing bases, exposing North American deployers to currency and shipping friction.
- Labor scarcity in secondary markets:Rural warehousing zones outside major metropolitan radii cannot source certified equipment operators at scale, constraining geographic expansion.
Strategic Opportunities
- Mexico nearshoring acceleration:Manufacturing relocation from Asia-Pacific sources is generating cross-border warehousing demand at Laredo-Nuevo Laredo and Tijuana-San Diego corridor nodes.
- USMCA regulatory harmonization:Inspection protocol convergence under the United States-Mexico-Canada Agreement framework would enable unified inventory positioning strategies across the tri-national zone.
- Robotics-warehouse management system convergence:Integration of autonomous mobile robots with real-time inventory tracking is opening greenfield facility design architectures unconstrained by legacy aisle widths.
Industry Challenges
- Certified maintenance technician deficit:Automated storage and retrieval systems require mechatronics specialists that community college programs have not scaled to produce.
- Legacy warehouse management system integration:Brownfield automation retrofits face protocol incompatibilities with 1990s-era inventory databases that resist API standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Warehousing and Storage Market |
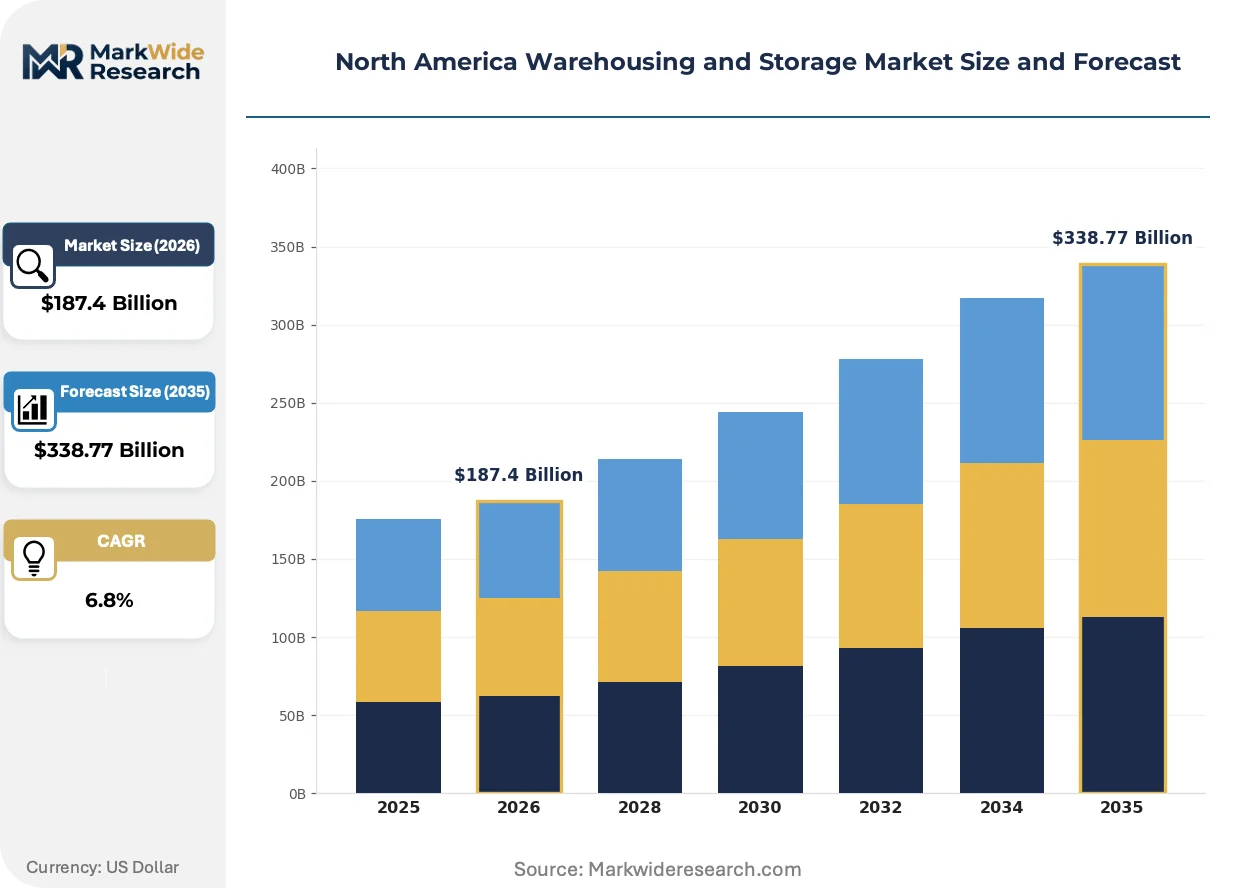
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $338.77 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Fulfillment, Shared Storage, Cold Storage, Bulk Storage Product Type: Pallet Rack, Mezzanine, Storage Bin, Automated Storage End User: Retail, E-Commerce, Manufacturing, Food & Beverage Technology: Warehouse Management System, RFID, Automated Guided Vehicle, Internet of Things |
| Companies Covered | GXO Logistics, GEODIS North America, Amazon.com, FedEx Logistics, Lineage Logistics, DHL Supply Chain North America, NFI, Americold, Ryder Supply Chain Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Warehousing and Storage Market Strategic Shifts & Innovations
Warehouse automation is fragmenting traditional operator roles while compressing order cycle times. Three developments are restructuring competitive positioning across the sector.
Autonomous mobile robots are hybridizing fulfillment workflows. These systems transport inventory to stationary pick stations rather than requiring human travel across warehouse floors. E-commerce fulfillment centers across the United States are deploying fleets at accelerating velocity. The technology is hybridizing labor allocation models, compressing headcount per unit shipped while elevating technical supervision ratios.
Federal Motor Carrier Safety Administration hours-of-service rules are tightening cross-dock timing windows. Driver duty limits constrain loading and unloading schedules, forcing warehouses to compress dock door turnover rates. Food and beverage distribution networks are responding with automated yard management systems that sequence trailer arrivals against labor shifts.
Shared storage contracts are displacing dedicated facility leases among mid-market manufacturers. Variable cost structures without ownership burdens appeal to seasonal demand patterns and new product launch cycles. This procurement evolution is most visible in Canadian consumer goods distribution, where third-party logistics providers capture manufacturing accounts previously served by captive warehouses.
North America Warehousing and Storage Market Segmentation
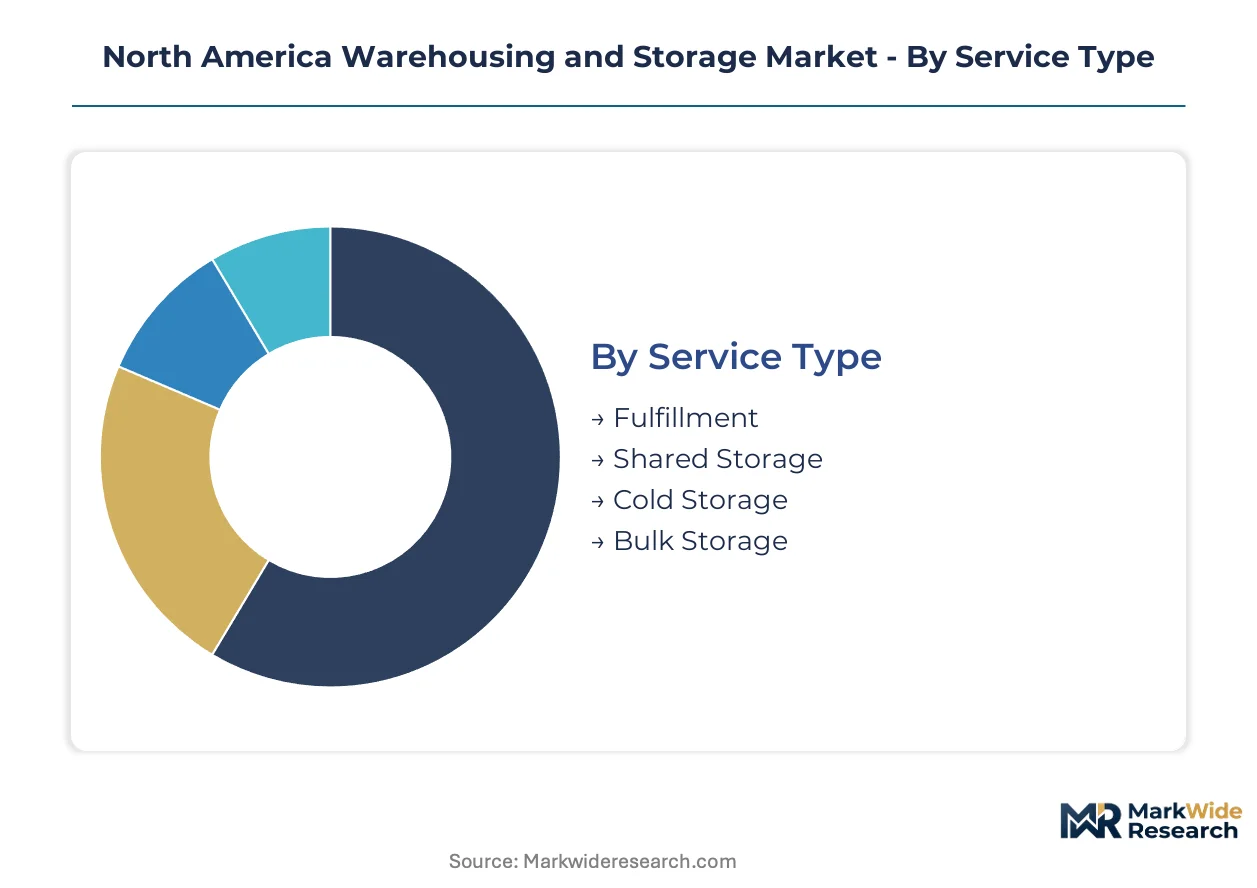
Segmentation in North American warehousing reflects divergent capital intensity, regulatory exposure, and automation readiness across service models and infrastructure types. Procurement patterns vary sharply between e-commerce fulfillment velocity requirements and pharmaceutical cold chain compliance mandates.
Service Type:
Use cases span from high-velocity e-commerce throughput to seasonal inventory buffering for agricultural commodities.
- Fulfillment:Direct-to-consumer order processing with same-day or next-day delivery commitments. Demand concentrates in Dallas-Fort Worth and Houston nodes of the Texas Triangle logistics corridor, driven by Amazon.com and regional e-commerce platform expansion.
- Cold Storage:Temperature-controlled infrastructure maintaining pharmaceutical and protein supply chain integrity. Lineage Logistics anchors specialized networks across the United States as vaccine distribution and fresh food e-commerce intensify freezer capacity requirements.
- Shared Storage:Multi-tenant facilities offering variable cost structures without ownership burdens. Canadian consumer goods manufacturers favor this model for seasonal demand patterns.
- Bulk Storage:High-cube warehousing for raw materials and intermediate goods with low handling frequency. Petrochemical and agricultural commodity traders utilize Gulf Coast facilities near Houston port infrastructure.
Established volume favors fulfillment; emerging adoption favors cold storage.
Product Type:
Capital deployment intensity separates legacy rack infrastructure from integrated robotics systems.
- Automated Storage:Robotic retrieval systems and vertical lift modules eliminating aisle space. GXO Logistics deploys these across divergent retail accounts as OSHA ergonomic mandates accelerate labor substitution.
- Pallet Rack:Selective, drive-in, and push-back configurations exceeding 20 feet in height. The Texas Triangle corridor absorbs the majority of new racking installations for cross-border fulfillment.
- Mezzanine:Elevated platforms creating additional cube utilization within existing shell structures. Food and beverage distributors favor mezzanines for case-pick operations.
- Storage Bin:Small-parts handling systems for electronics, pharmaceuticals, and automotive components. Mexican maquiladora operations near Tijuana source bin systems for assembly-line feeding.
Capital allocation tilts toward automated storage; rack infrastructure retains volume dominance.
End User:
Velocity requirements and compliance exposure create distinct facility specifications across demand segments.
- E-Commerce:High-SKU-count operations demanding rapid order cycle compression. Amazon.com proprietary robotics integration sets throughput benchmarks across United States fulfillment centers.
- Food & Beverage:Temperature-controlled and sanitary design protocols with FDA and USDA inspection exposure. Cold storage investment clusters near protein processing facilities in the Midwest and Southeast.
- Retail:Seasonal inventory buffering and cross-dock consolidation for store replenishment. Shared storage contracts displace dedicated leases among mid-market Canadian retailers.
- Manufacturing:Just-in-time component staging and finished goods marshaling. Mexico nearshoring acceleration generates warehousing demand at Laredo-Nuevo Laredo corridor nodes.
E-commerce commands automation investment; food and beverage drives cold chain specialization.
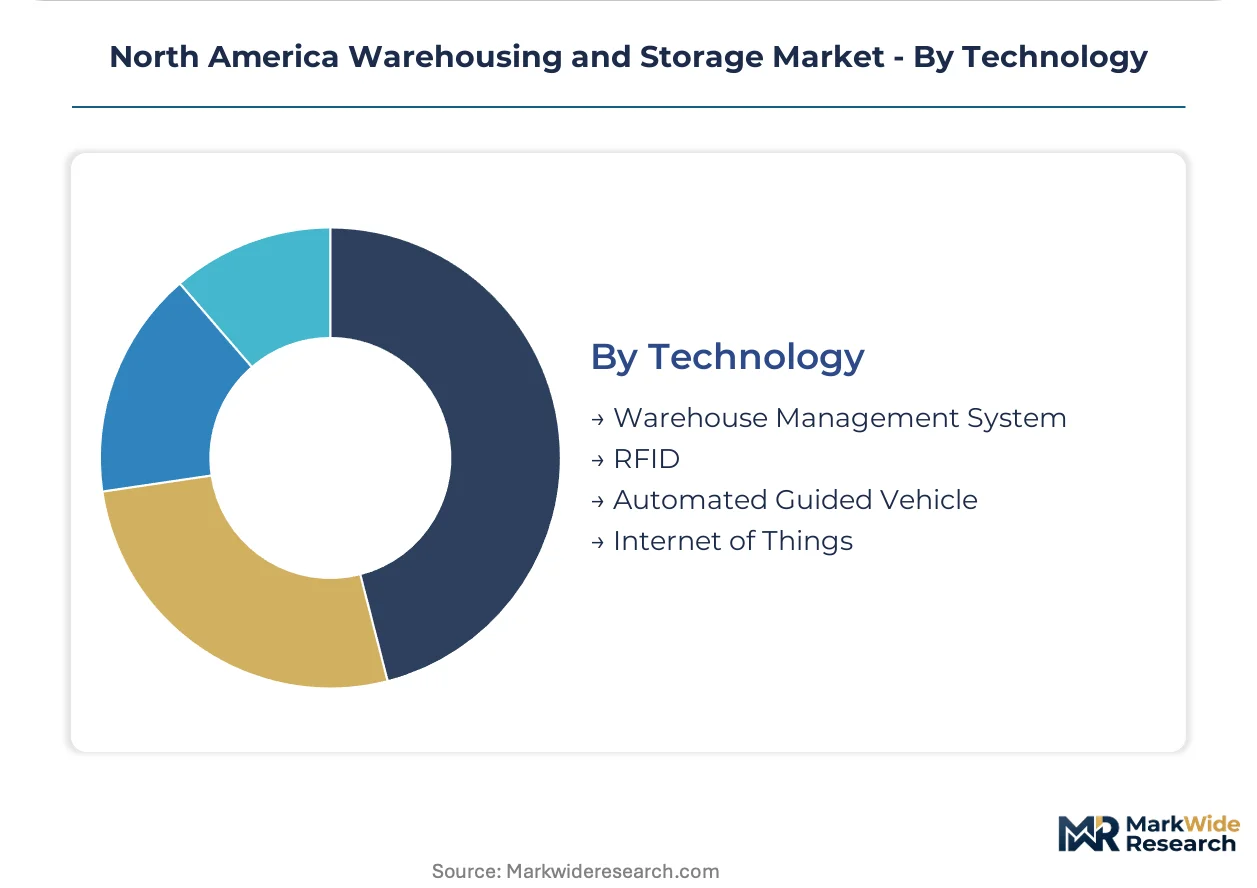
Technology:
Integration maturity separates established inventory tracking from emerging autonomous workflows.
- Automated Guided Vehicle:Fixed-path robotics transporting pallets and cases across warehouse floors. These systems compress labor headcount per unit shipped while elevating technical supervision ratios.
- Warehouse Management System:Software platforms coordinating inventory, labor, and equipment across facility operations. Legacy brownfield retrofits face protocol incompatibilities with 1990s-era databases.
- RFID:Radio-frequency identification enabling real-time inventory visibility without line-of-sight scanning. Pharmaceutical track-and-trace mandates accelerate adoption.
- Internet of Things:Sensor networks monitoring equipment condition, energy consumption, and environmental parameters. Cold storage facilities deploy IoT for continuous temperature logging.
Warehouse Management System penetration is deepest; Automated Guided Vehicle deployment is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
E-commerce fulfillment centers concentrate buyer demand across the tri-national zone. Texas Triangle logistics corridors and cross-border manufacturing relocation are redrawing capacity distribution.
United States
FedEx Logistics and Amazon.com fulfillment velocity requirements drive automation investment. OSHA warehouse safety standards mandate fall protection and ergonomic protocols that elevate facility compliance costs. Dallas-Fort Worth anchors the Texas Triangle corridor where distribution center construction concentrates regional capacity.
Canada
Shared storage contracts displace dedicated facility leases among mid-market manufacturers. Health Canada and PMRA pharmaceutical track-and-trace mandates accelerate cold chain infrastructure deployment. Ontario's consumer goods distribution networks capture manufacturing accounts previously served by captive warehouses.
Mexico
Nearshoring acceleration from Asia-Pacific sources generates cross-border warehousing demand. NOM standards for industrial safety create compliance layers for tri-national operators. Laredo-Nuevo Laredo and Tijuana-San Diego corridor nodes absorb manufacturing relocation flows.
North America Warehousing and Storage Market Key Industry Players
Channel-controlling players compete with product-specialist players across fragmented service tiers. The vendor base clusters around three archetypes: integrated logistics platforms, temperature-controlled specialists, and multi-client contract operators. M&A activity concentrates among cold storage networks, while automation deployment represents the dominant capacity expansion vector.
Within the integrated platform tier, Amazon.com exemplifies proprietary robotics integration at scale. GXO Logistics and Lineage Logistics occupy distinct specialization positions—multi-client contract flexibility versus temperature-controlled network density. These three entities anchor competitive positioning across fulfillment velocity, cold chain compliance, and variable cost structures.
| Leading Market Players |
|---|
| GXO Logistics |
| GEODIS North America |
| Amazon.com |
| FedEx Logistics |
| Lineage Logistics |
| DHL Supply Chain North America |
| NFI |
| Americold |
| Ryder Supply Chain Solutions |
| Others |
Cost & Logistics Intelligence
Overcapacity in Dallas-Fort Worth fulfillment centers is compressing contract rates while elevating service-level competition. Facility utilization below break-even thresholds forces operators to absorb steel and concrete input volatility rather than pass through costs, reshaping supplier negotiations and automation investment timelines across the Texas Triangle logistics corridor.
Pricing Analysis
Cost-plus contracts indexed to steel futures and labor hour standards dominate multi-year agreements between third-party logistics providers and retail clients. Price differentiation rests on automation tier—facilities with autonomous mobile robots command premium rates over conventional rack infrastructure—and geographic delivery cost to final-mile nodes. Cost compression in shared storage services is intensifying because mid-market manufacturers are consolidating vendor relationships. E-commerce fulfillment centers show least price sensitivity due to velocity requirements; bulk storage for agricultural commodities faces highest sensitivity as traders arbitrage location spreads.
Supply Chain Analysis
Automated storage and retrieval system manufacturing concentrates in Germany and Japan, with North American deployers drawing from these bases for vertical lift modules and robotic retrieval equipment. Racking structures exceeding 20 feet and climate-controlled shell construction hinge on domestic steel and concrete suppliers. Single-source vulnerability runs through German-Japanese equipment providers exposed to currency friction and shipping chokepoints. Distribution runs through third-party logistics networks that sequence inventory positioning against Federal Motor Carrier Safety Administration hours-of-service constraints.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is entering cyclical recovery as e-commerce fulfillment center construction rebounds from 2023-2024 overbuild corrections. Inventory-to-sales ratios across United States retail are normalizing, pulling warehousing demand off trough levels.
For Market Incumbents: Entrench automation moats through proprietary warehouse management system-robotics integration that locks in multi-client contracts. Defend against GXO Logistics-style flexibility plays by anchoring capacity in the Texas Triangle corridor where land scarcity is accelerating. Certification investment in OSHA fall protection and ergonomic protocols elevates compliance costs that marginal operators cannot absorb. For New Entrants and Emerging Players: Pursue Mexico nearshoring corridors at Laredo-Nuevo Laredo and Tijuana-San Diego where cross-border warehousing demand outstrips specialized cold storage supply. Canadian shared storage for consumer goods manufacturers offers penetrable white space as captive warehouses convert to variable-cost outsourcing. A go-to-market angle targeting pharmaceutical cold chain compliance—Health Canada and PMRA track-and-trace mandates—opens premium rate tiers unavailable to generalist competitors. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among temperature-controlled specialists with long-term protein and vaccine distribution contracts. Long-term viability across the analysis window favors operators with backward integration into automation deployment capabilities rather than equipment-reliant capital structures. The acquisition target archetype is regional cold storage networks with FDA and USDA inspection infrastructure. The signal to watch is OSHA regulatory harmonization progress that would accelerate capital substitution timelines and compress labor-dependent competitor margins.| Strategic Initiative | Industry Significance |
|---|---|
| Robotics-Warehouse Management System Integration | Amazon.com proprietary deployment sets throughput benchmarks that reshape facility design standards. |
| Cold Storage Network Expansion | Lineage Logistics anchors temperature-controlled infrastructure as vaccine distribution intensifies freezer requirements. |
| Cross-Border Corridor Positioning | Laredo-Nuevo Laredo nodes capture Mexico nearshoring flows from Asia-Pacific manufacturing relocation. |
| Multi-Client Contract Flexibility | GXO Logistics extends automation across divergent retail accounts without captive facility ownership. |
| OSHA Compliance Certification Investment | Fall protection and ergonomic protocol mandates elevate facility costs that filter marginal operators. |
Research Approach
A spread of perspectives from warehouse operations directors, third-party logistics procurement leads, automation equipment vendors, and commercial real estate developers converged on the working assumptions underlying this analysis. Primary interviews with facility managers at Dallas-Fort Worth and Houston distribution centers were cross-validated against secondary sources including Federal Motor Carrier Safety Administration regulatory filings, OSHA enforcement databases, and commercial industrial lease transaction records. Bottom-up capacity utilization data and top-down regional construction permitting statistics were triangulated to anchor demand estimates.
Demand-supply balance modeling across the projection horizon incorporated service type segmentation—fulfillment, cold storage, shared storage, bulk storage—alongside product type tiers from automated storage systems to conventional pallet rack infrastructure. End-user velocity requirements and technology integration maturity provided additional segmentation dimensions. CAGRs were derived from facility construction pipelines, equipment order backlogs, and labor substitution elasticities observed across automation deployment waves.
Macroeconomic conditions sit as an overlay; deviation in United States retail inventory-to-sales ratios, steel price volatility, and cross-border manufacturing relocation velocity would shift the trajectory. Forecasts reflect documented assumptions about regulatory enforcement intensity and equipment supplier delivery timelines. Quarterly review of OSHA rulemaking dockets, Federal Motor Carrier Safety Administration hours-of-service amendment proposals, and Mexico NOM industrial safety updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Germany Real Estate Services Market
Real Estate
Singapore Customs Brokerage Market
Real Estate
Public Warehousing Market
Real Estate
UAE Flexible Office Space Market
Real Estate
Myanmar Residential Real Estate Market
Real Estate
Switzerland Facility Management Market
Real Estate
China Office Real Estate Market
Real Estate
Sweden Facility Management Market
Real Estate
Canada Commercial Real Estate Market
Real Estate
South Africa Facility Management Market
Real Estate
Saudi Arabia Residential Real Estate Market
Real Estate
North America Hard Facility Management Market
Real Estate
Italy Office Real Estate Market
Real Estate
United Arab Emirates Co-Working Space Market
Real Estate
China Luxury Residential Real Estate Market
Real Estate
Australia Co-Working Office Spaces Market