
 China Office Real Estate Market | 2026-2036
China Office Real Estate Market Size, Share, and Industry Trends Forecast 2026-2036
China Office Real Estate Market Analysis
A capital-intensity divergence between state-backed developers and private operators is reorganizing competitive dynamics in China's office sector. China Vanke Co., Ltd. leverages its integrated development platform to control project timelines from land acquisition to tenant fit-out. China Resources Land Limited anchors its portfolio in mixed-use districts that blend retail, residential, and premium office towers. Longfor Group Holdings Limited differentiates through specialized commercial property management capabilities that sustain occupancy premiums.
China office real estate comprises purpose-built commercial structures designed for administrative, professional, and corporate functions, typically featuring reinforced concrete or steel-frame construction with centralized HVAC, fiber-optic infrastructure, and floor loading capacities of 300-500 kg per square meter. These assets serve as operational headquarters for domestic enterprises and multinational corporations seeking Class A and Class B space in urban cores. Grade A properties command the deepest tenant pools and longest lease durations across tier-one cities. Co-working and managed office formats are capturing growing share among technology startups and flexible enterprise users. Business park segments in satellite cities attract manufacturing-affiliated R&D tenants seeking lower per-square-meter costs than central business districts.
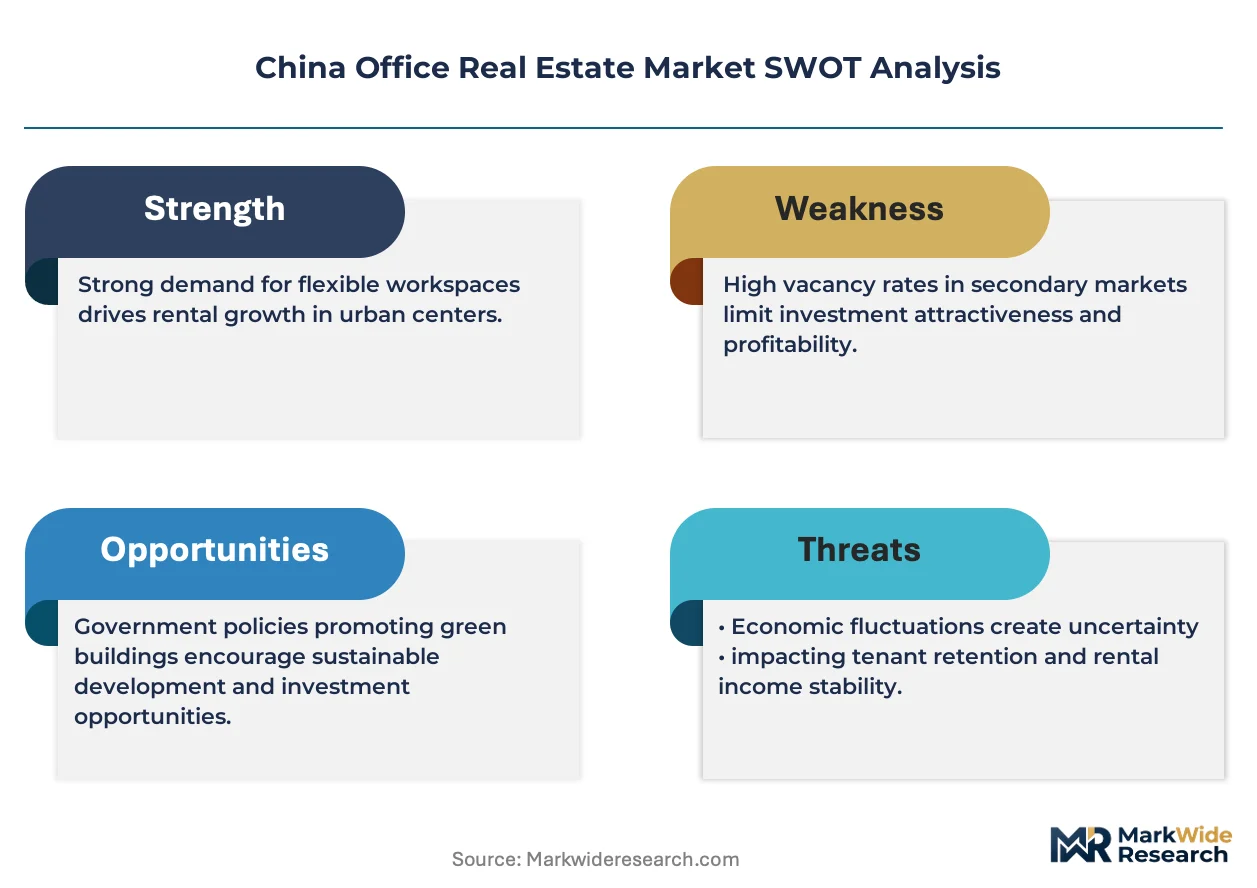
China's Ministry of Housing and Urban-Rural Development enforces green building evaluation standards that mandate energy efficiency benchmarks for new office construction, while local planning bureaus in Shanghai and Beijing impose floor-area-ratio restrictions that constrain supply expansion in prime sub-markets. SAMR oversight of commercial lease contracts shapes tenant-landlord negotiation frameworks and dispute resolution protocols. Stakeholders must monitor how evolving green finance incentives and carbon accounting rules will reshape capital allocation between retrofitting existing stock and developing new certified assets.
Market Dynamics
China's dual carbon goals and green building evaluation standards are forcing a wholesale retrofit imperative across existing office stock while constraining new supply through floor-area-ratio restrictions in prime sub-markets.
Growth Catalysts
- Green Finance Incentives:SAMR oversight of commercial lease contracts aligns with carbon accounting rules that reward certified assets, channeling institutional capital toward LEED-equivalent and three-star green buildings in Shanghai and Beijing.
- Financial Services Expansion:Domestic banks and insurance groups are enlarging headquarters footprints in Lujiazui and Beijing CBD, generating sustained absorption of Class A space with 5-10 year lease tenures.
- Flexible Space Formats:Co-working and managed office operators are capturing technology startup demand that prioritizes short-term commitments and plug-and-play infrastructure over traditional fit-out cycles.
Market Restraints
- Land Supply Constraints:Beijing and Shanghai planning bureaus enforce strict floor-area-ratio caps that limit new Grade A deliveries to sub-2% annual stock growth in core districts.
- Debt-Driven Developer Stress:Private operators face refinancing pressure as state-backed competitors access lower-cost capital, compressing development margins and delaying project completions.
- Substitution to Business Parks:Manufacturing-affiliated R&D tenants are migrating to satellite city locations offering 40-60% lower per-square-meter occupancy costs than central business districts.
Strategic Opportunities
- Greater Bay Area Satellite Cities:Dongguan and Foshan office sub-markets remain underpenetrated relative to Shenzhen, offering first-mover positioning for mixed-use developers ahead of infrastructure convergence.
- Retrofit Certification Pipeline:MEE carbon intensity benchmarks create regulatory tailwinds for energy efficiency upgrades that qualify existing buildings for green finance preferential rates.
- Smart Building Convergence:Integration of IoT sensor networks with centralized HVAC systems enables predictive maintenance contracts that extend tenant retention and command rent premiums.
Industry Challenges
- Green Certification Talent Scarcity:Shortage of accredited professionals capable of navigating three-star green building documentation and carbon accounting verification creates project timeline risk.
- Legacy System Integration:Retrofitting 1990s-era office stock with fiber-optic infrastructure and modern floor loading specifications demands complex structural engineering without full demolition.
- Tenant Improvement Coordination:State-backed developers with integrated platforms compress fit-out timelines that private operators struggle to match, eroding competitive position in lease negotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Office Real Estate Market |
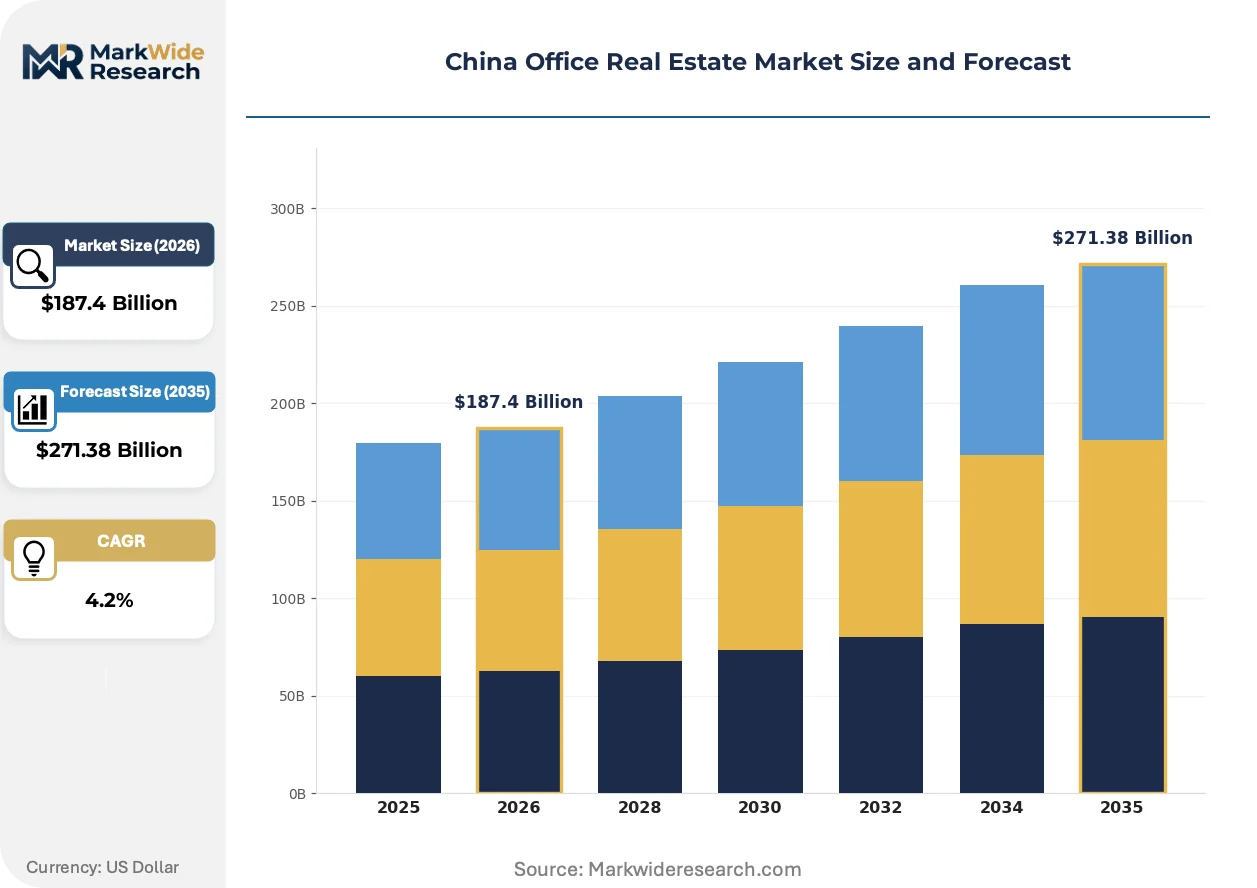
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $271.38 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Property Type: Grade A, Grade B, Grade C, Serviced Office, Business Park Leasing Model: Direct Lease, Sublease, Co-working Space, Managed Office, Rent-to-Own Tenant Industry: Information Technology, Financial Services, Legal Firms, Consulting Agencies, Media Companies Building Classification: High-Rise, Mid-Rise, Low-Rise, Boutique Office, Campus Style |
| Companies Covered | China Vanke Co., Ltd., China Resources Land Limited, China Overseas Land & Investment Limited, Longfor Group Holdings Limited, Poly Developments and Holdings Group Co., Ltd., Sunac China Holdings Limited, Greenland Holdings Corporation Limited, China Merchants Shekou Industrial Zone Holdings Co., Ltd., Wanda Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Office Real Estate Market Emerging Trajectories
Technology-enabled space optimization and regulatory carbon mandates are converging to transform how office assets are designed, operated, and financed across Chinese tier-one cities.
Building-integrated photovoltaics and advanced glazing systems are supplanting conventional curtain wall construction in premium office developments. Multinational corporate tenants with net-zero commitments are specifying these technologies in pre-leasing negotiations. The shift is compressing acceptable payback periods for developer capital expenditure from seven years toward four.
China's Ministry of Housing and Urban-Rural Development three-star green building standard is tightening energy efficiency benchmarks for new construction and major renovations. Developers must now demonstrate 15% energy savings above baseline to qualify for certification. Shanghai and Beijing projects are responding by mandating geothermal exchange systems and rainwater harvesting in design briefs.
Enterprise leasing decisions now prioritize outcome-based occupancy metrics over traditional cost-per-square-meter comparisons. Technology sector tenants are unbundling long-term leases in favor of managed service agreements that transfer HVAC and facilities risk to landlords. This behavioral pivot is most pronounced among artificial intelligence and fintech firms clustering in Beijing's Zhongguancun corridor.
China Office Real Estate Market Segmentation
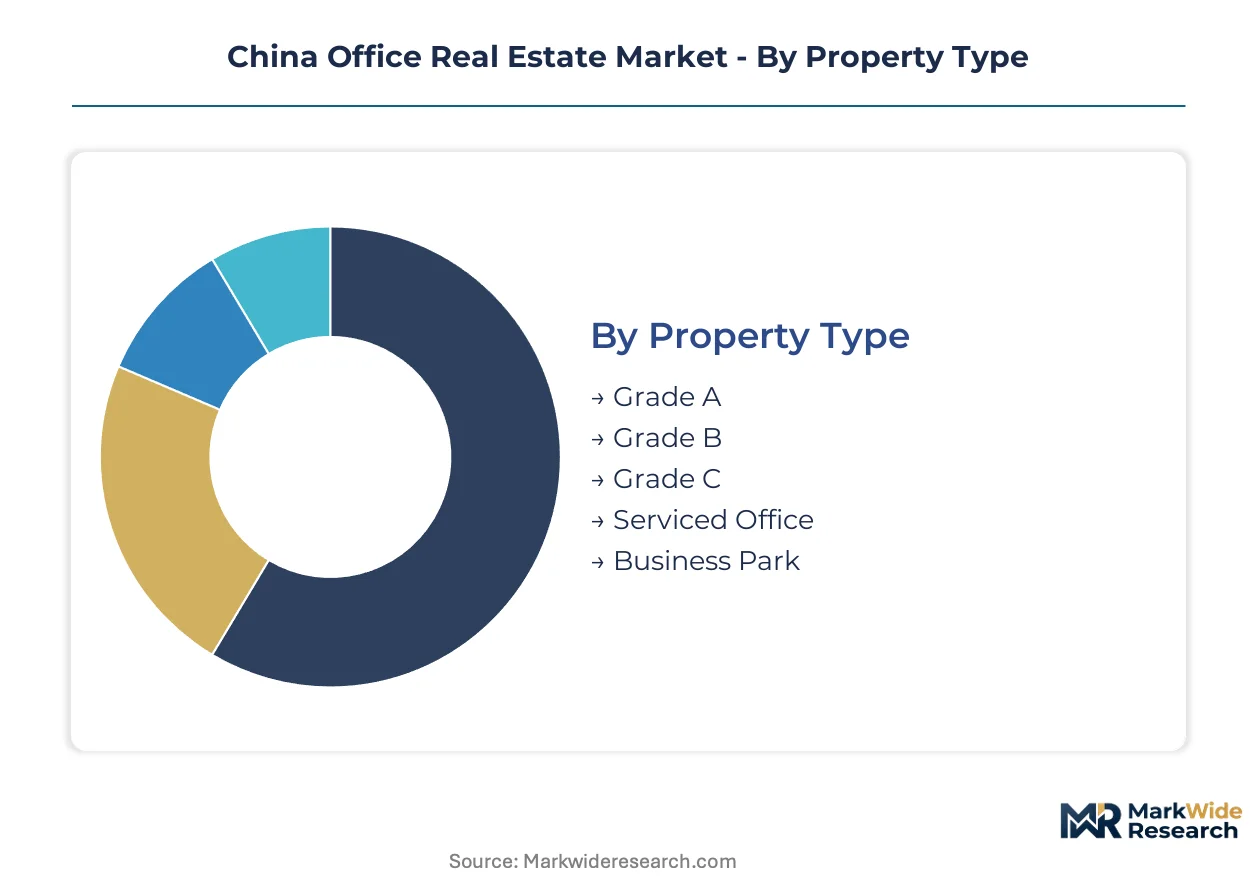
China's office market fragmentation demands granular segmentation to capture how tenant preferences, building specifications, and lease structures diverge across tier-one cities. Distinct property grades and leasing models command different capital commitments and occupancy premiums.
Property Type:
Substitution pressure intensifies as business parks and serviced offices capture demand that previously defaulted to conventional Grade A towers in central business districts.
- Grade A:Premium structures feature reinforced concrete or steel-frame construction with centralized HVAC, fiber-optic infrastructure, and floor loading capacities of 300-500 kg per square meter. Financial services firms in Shanghai's Lujiazui and Beijing's CBD generate sustained absorption with 5-10 year lease tenures.
- Grade B:Mid-tier assets offer functional office space with standard mechanical systems and moderate fit-out specifications. Domestic enterprises and professional services firms concentrate in Beijing's Chaoyang sub-markets where per-square-meter costs trail Grade A premiums.
- Grade C:Older stock with limited amenity provision serves cost-sensitive tenants in peripheral districts.
- Serviced Office:Fully furnished, short-term flexible space formats capture technology startup demand prioritizing plug-and-play infrastructure over traditional fit-out cycles.
- Business Park:Campus-style developments in satellite cities attract manufacturing-affiliated R&D tenants seeking 40-60% lower occupancy costs than central business districts.
Grade A anchors the volume base while business parks gain share at the steepest rate.
Leasing Model:
Cost tier differentiation separates institutional-grade direct leases from flexible formats that transfer facilities risk to landlords.
- Direct Lease:Traditional long-term contracts between tenant and landlord, typically 3-5 years with tenant responsibility for fit-out and operating expenses. Multinational corporations in Beijing CBD and Shanghai Lujiazui prefer this structure for headquarters stability.
- Sublease:Secondary market arrangements where primary tenants monetize excess capacity. Technology sector contraction in Zhongguancun has expanded sublease availability at 15-25% discounts to direct terms.
- Co-working Space:Membership-based access to shared amenities and hot-desking infrastructure. Artificial intelligence and fintech firms cluster in Beijing's innovation corridor with month-to-month commitments.
- Managed Office:All-inclusive service agreements bundling rent, facilities management, and IT infrastructure. Landlords assume HVAC and maintenance risk while tenants pay outcome-based occupancy fees.
- Rent-to-Own:Hybrid structures converting lease payments toward eventual ownership, rare in China but emerging for state-affiliated enterprises in Greater Bay Area satellite cities.
Direct lease commands the revenue base while managed offices expand most quickly among technology tenants.
Tenant Industry:
Application-driven demand concentration varies sharply by sub-market, with financial services and information technology commanding opposing space configurations.
- Information Technology:Artificial intelligence and fintech firms prioritize managed service agreements and short-term commitments. Zhongguancun corridor absorption reflects preference for flexible formats over conventional leases.
- Financial Services:Domestic banks and insurance groups enlarge headquarters footprints in Lujiazui and Beijing CBD. Class A space with 5-10 year tenures dominates this segment's procurement patterns.
- Legal Firms:Partnership structures favor prestigious addresses in core business districts with traditional fit-out specifications.
- Consulting Agencies:Project-based staffing drives demand for hybrid space configurations blending dedicated suites with co-working access.
- Media Companies:Content production requirements favor boutique offices with specialized acoustic and technical infrastructure in Shanghai's former industrial zones.
Financial services anchors the volume base while information technology climbs the fastest in square-meter absorption.
Building Classification:
Geography and maturity determine where each building type concentrates, with high-rise towers dominating prime sub-markets and campus formats expanding in satellite cities.
- High-Rise:Structures exceeding 20 floors with centralized mechanical systems and premium elevator banks. Shanghai Lujiazui and Beijing CBD concentration reflects land scarcity and floor-area-ratio optimization.
- Mid-Rise:8-20 story buildings balancing efficiency with tenant accessibility. Secondary business districts in Shenzhen and Guangzhou favor this format for professional services tenants.
- Low-Rise:Sub-8 story structures with limited vertical transportation, concentrated in older urban cores and peripheral zones.
- Boutique Office:Small-scale, architecturally distinctive buildings targeting creative industries and specialized professional firms. Shanghai's former French Concession and Beijing's 798 Art Zone host this format.
- Campus Style:Low-density, multi-building configurations with shared outdoor amenities. Dongguan and Foshan sub-markets attract first-mover developers ahead of Greater Bay Area infrastructure convergence.
High-rise anchors the volume base while campus style gains share at the steepest rate in satellite city locations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Chinese office sub-markets, with financial services tenants in Shanghai Lujiazui and Beijing CBD absorbing rent premiums while manufacturing-affiliated R&D operators migrate to satellite cities for 40-60% cost reductions.
Yangtze River Delta
Shanghai Lujiazui and Hangzhou technology corridors drive Grade A absorption through financial services and artificial intelligence firm expansion. Shanghai's planning bureau enforces strict floor-area-ratio caps limiting annual stock growth in core districts to sub-2%. Nanjing's Jiangbei New Area attracts provincial headquarters relocations with lower land costs than Shanghai core.
Pearl River Delta
Shenzhen Qianhai and Guangzhou Tianhe sub-markets concentrate fintech and multinational regional headquarters demand. Guangdong Province implements three-star green building standards mandating 15% energy savings above baseline for new construction. Dongguan and Foshan office markets remain underpenetrated, offering first-mover positioning ahead of Greater Bay Area infrastructure convergence.
Beijing-Tianjin-Hebei
Beijing CBD and Zhongguancun innovation corridor anchor financial services and technology tenant demand with opposing space configurations. SAMR oversight of commercial lease contracts shapes tenant-landlord negotiation frameworks across the capital region. Tianjin's Binhai New Area captures back-office functions seeking lower occupancy costs than Beijing core districts.
Sichuan-Chongqing
Chengdu's Tianfu New Area and Chongqing Liangjiang New Zone attract domestic enterprise regional headquarters and technology sector tenants. Western China development programs channel infrastructure investment toward these twin hubs. Chongqing's Jiangbeizui CBD concentrates Class A supply as developers respond to inland market deepening.
Shandong Peninsula
Qingdao's Shinan and Laoshan districts serve manufacturing-affiliated corporate functions and regional trade operations. Shandong Province enforces dual carbon compliance timelines accelerating retrofit demand across 1990s-era office stock. Jinan's High-Tech Industrial Development Zone captures R&D tenants from Beijing-Tianjin spillover.
China Office Real Estate Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across China's office development sector. State-backed developers access lower-cost capital and integrated development platforms that compress project timelines from land acquisition to tenant fit-out. Private operators compete through specialized commercial property management capabilities and flexible leasing formats. Dominant competitive moves include portfolio diversification into mixed-use districts and strategic positioning in underpenetrated satellite city markets ahead of infrastructure convergence.
Within the state-backed tier, China Vanke Co., Ltd. and China Resources Land Limited exemplify integrated development platforms controlling full project lifecycles. China Overseas Land & Investment Limited occupies a position among premium-grade specialists with concentrated exposure to tier-one city core districts. Longfor Group Holdings Limited represents the specialized management archetype, competing through commercial property management capabilities that sustain occupancy premiums against capital-advantaged rivals.
| Leading Market Players |
|---|
| China Vanke Co., Ltd. |
| China Resources Land Limited |
| China Overseas Land & Investment Limited |
| Longfor Group Holdings Limited |
| Poly Developments and Holdings Group Co., Ltd. |
| Sunac China Holdings Limited |
| Greenland Holdings Corporation Limited |
| China Merchants Shekou Industrial Zone Holdings Co., Ltd. |
| Wanda Group |
| Others |
Supply Flow & Price Mechanics
China's three-star green building certification gates both developer qualification and rent differentiation simultaneously, compressing acceptable payback periods for energy efficiency investments while stratifying Class A premiums from uncertified stock.
Pricing Analysis
Managed service agreements and facilities management contracts now drive lifetime value capture across institutional portfolios. Three-tier pricing structure across premium, standard, and economy levels separates LEED-equivalent certified towers from conventional Grade A and aging Grade B assets. Cost compression in satellite city business parks is intensifying because manufacturing-affiliated R&D tenants prioritize per-square-meter savings over prestige addresses. Domestic banks and insurance groups show least price sensitivity, absorbing core-district premiums for headquarters stability, while technology startups exhibit highest elasticity, migrating to co-working formats.
Supply Chain Analysis
Port congestion along Yangtze River Delta shipping lanes and container availability fluctuations on Asia-Europe trade routes elevate inbound logistics costs for curtain wall systems and HVAC equipment. Supply concentrates in China, Germany, and Japan for building automation systems, advanced glazing, and elevator banks. Raw material dependencies span structural steel, low-emissivity glass, and copper piping for geothermal exchange installations. Single-source vulnerability from concentrated German sensor manufacturers creates procurement risk. Distribution runs through state-backed developer platforms with captive construction subsidiaries and third-party general contractors serving private operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among state-backed financial services tenants enlarging headquarters footprints, fragmenting negotiating leverage for private developers without integrated platforms.
For Market Incumbents: Fortify green certification pipelines ahead of MEE carbon intensity benchmark enforcement, locking in preferential financing rates. Accelerate backward integration into facilities management capabilities to match Longfor's occupancy premium model. State-backed competitors with lower-cost capital access threaten margin compression in core-district lease negotiations.
For New Entrants and Emerging Players: SAMR commercial lease compliance fast-track offers regulatory positioning ahead of incumbent adaptation. Target Dongguan and Foshan satellite city sub-markets where Grade A penetration trails Shenzhen by substantial margins. Deploy smart building IoT convergence as differentiated go-to-market angle for predictive maintenance contracts.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across retrofit certification pipelines as dual carbon deadlines approach. Long-term viability over the coming decade rests on positioning between state-backed scale players and specialized management operators. Acquisition target archetype: boutique developers with three-star green building accreditation capability in underpenetrated Greater Bay Area corridors. Signal to watch: green finance incentive rate spreads between certified and conventional assets.
| Strategic Initiative | Industry Significance |
|---|---|
| Retrofit Certification Pipeline | MEE carbon benchmarks channel institutional capital toward energy efficiency upgrades at preferential rates. |
| Smart Building Convergence | IoT-HVAC integration enables predictive maintenance contracts that extend tenant retention in Zhongguancun. |
| Satellite City Positioning | First-mover mixed-use development in Dongguan captures infrastructure convergence ahead of Greater Bay Area integration. |
| Integrated Development Platform | State-backed operators compress land-to-fit-out timelines that erode private competitor lease negotiation position. |
| Flexible Format Expansion | Managed office agreements transfer facilities risk to landlords serving artificial intelligence startup demand. |
Methodological Framework
Desk research of SAMR regulatory filings, Shanghai and Beijing planning bureau floor-area-ratio documentation, and green building certification databases preceded structured interviews with commercial property management executives, institutional leasing directors, and facilities engineering specialists. Primary fieldwork with China Vanke and China Resources Land development teams combined with secondary validation against Ministry of Housing and Urban-Rural Development construction permits. Bottom-up project pipeline analysis triangulated against top-down absorption estimates from tier-one city sub-market tracking.
Variance decomposition across property grade, leasing model, tenant industry, and building classification dimensions shaped the analytical framework over the projection horizon. CAGRs derived from rolling stock growth constraints and demand elasticity by tenant segment. Forecast inputs incorporated green finance incentive spread assumptions and carbon accounting rule evolution timelines.
Decision-makers should treat outputs as directional under sustained dual carbon policy enforcement and floor-area-ratio cap maintenance; material deviation would warrant model refresh. Specific risk factors include refinancing stress among private developers and accelerated R&D tenant migration to business parks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Real Estate
India Office Real Estate Market
Office Real Estate
Bahrain Flexible Office Space Market
Office Real Estate
China Co Working Office Space Market
Office Real Estate
Asia Pacific Office Real Estate Market
Office Real Estate
Canada Office Real Estate Market
Office Real Estate
North America Flexible Office Market
Office Real Estate
Europe Flexible Office Market
Office Real Estate
Spain Office Real Estate Market
Office Real Estate
Japan Office Real Estate Market
Office Real Estate
Latin America Office Real Estate Market
Office Real Estate
India Co-Working Office Spaces Market
Office Real Estate
United States Co-Working Office Space Market
Office Real Estate
Europe Office Real Estate Market
Office Real Estate
Saudi Arabia Office Real Estate Market
Office Real Estate
Canada Flexible Office Space Market
Office Real Estate
Australia Co-Working Office Spaces Market