
 Germany Manufactured Homes Market | 2026-2036
Germany Manufactured Homes Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Manufactured Homes Market Foresight
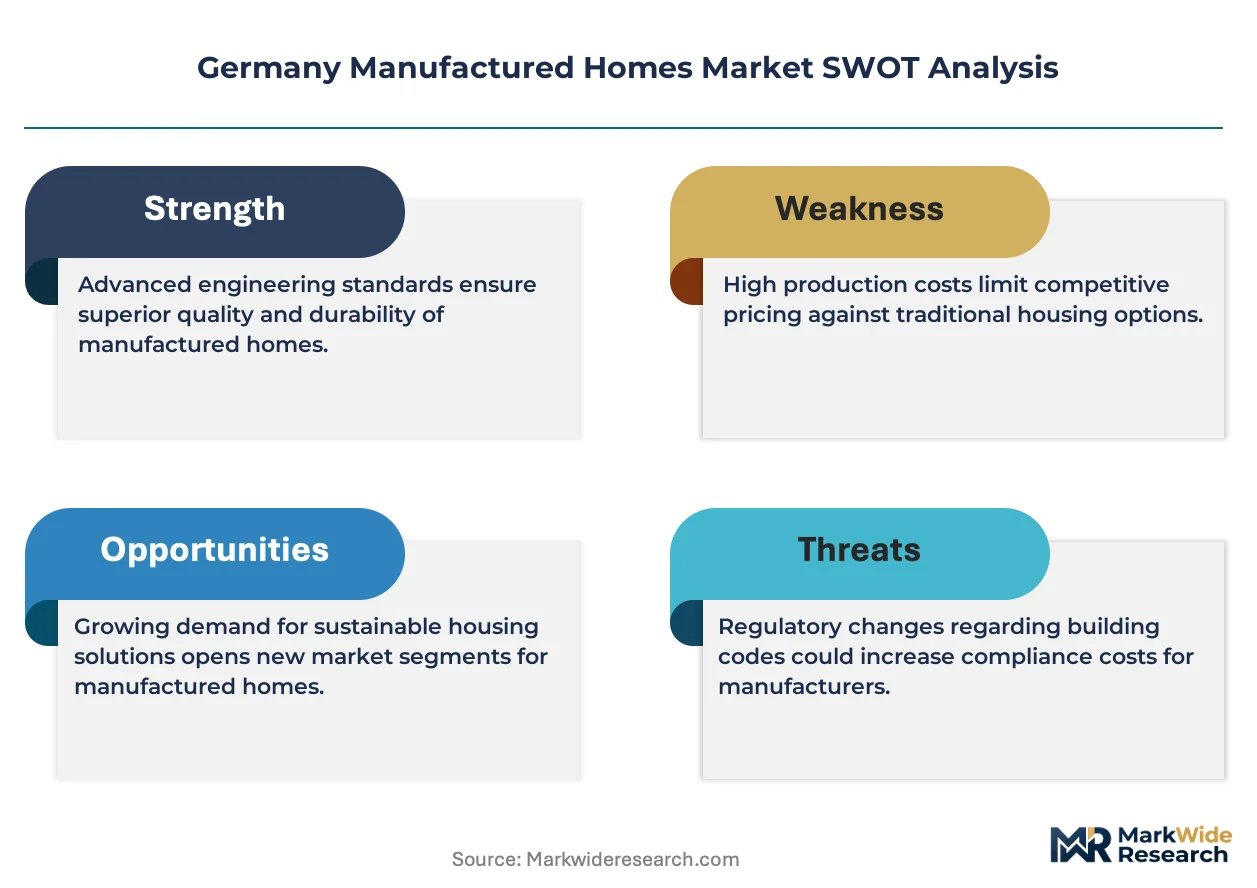
Turnkey bundling of foundation, transport, and on-site finishing is consolidating buyer preference toward full-service packages. Fertighaus Weiss GmbH leverages its vertically integrated supply chain to control lead times across southern Germany. Baufritz differentiates through premium timber-frame specialization and third-party sustainability certifications. ALHO Modular Buildings anchors its position in commercial-to-residential conversions, a niche with limited domestic competition.
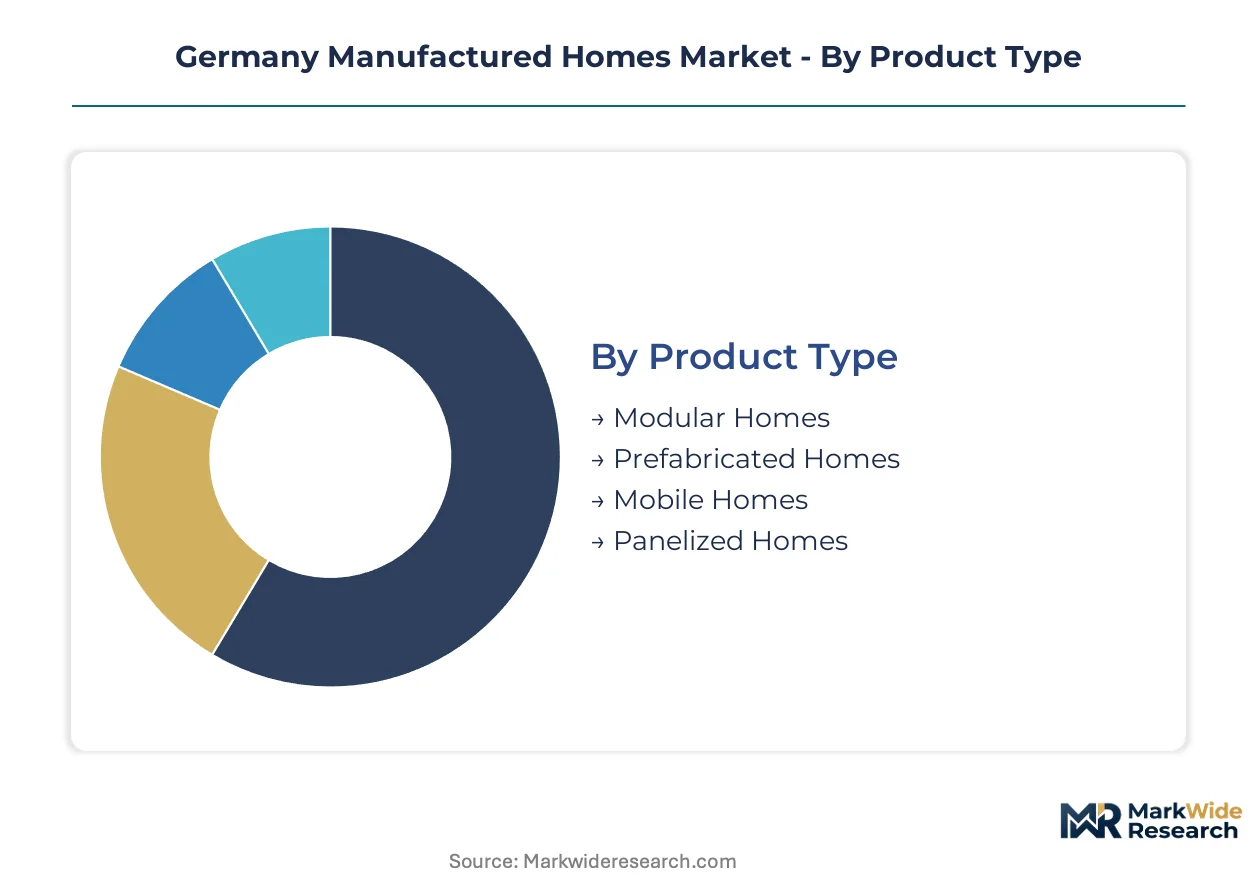
Germany manufactured homes are prefabricated dwelling units produced in factory-controlled environments, typically employing timber frames, steel modules, or cross-laminated timber panels engineered to DIN 68800 durability standards, then transported for on-site assembly. These structures serve residential, commercial-adaptive, and institutional housing purposes where speed and cost predictability outweigh conventional construction timelines. Modular homes command the dominant share among product types, reflecting German engineering preferences for precision-fit volumetric units. Panelized homes represent the fastest-expanding segment, as manufacturers respond to GEG thermal performance mandates with factory-insulated wall systems. Residential buyers form the deepest end-user pool, though investors and developers are gaining share amid rental housing yield compression.
KBA vehicle-type approval requirements govern mobile home transport compliance, while the GEG and state-level building codes shape energy efficiency thresholds that manufacturers must meet for market access. DIN standards and regional Bauaufsichtsbehörden enforcement create a layered compliance environment that favors established producers with dedicated certification teams. Stakeholders must monitor pending amendments to federal zoning laws that could expand manufactured home placement rights beyond current land-use restrictions.
Market Dynamics
The Germany Building Energy Act (GEG) is compressing design-to-delivery timelines by mandating factory-insulated wall systems that conventional site-built construction cannot execute at comparable speed. Manufacturers are retooling panel lines to meet thermal performance thresholds that now gate market access.
Growth Catalysts
- Land scarcity in Bavaria and Baden-Württemberg:Municipal zoning relaxations in these southern states are permitting manufactured homes on smaller plots than conventional construction requires, accelerating placement approvals.
- GEG thermal performance mandates:The regulation's efficiency thresholds favor factory-controlled insulation installation over variable site work, pulling demand toward panelized systems.
- First-time buyer financing access:German development banks are extending preferential loan terms for turnkey manufactured home packages, reducing down-payment barriers relative to site-built mortgages.
Market Restraints
- Cross-laminated timber input volatility:Bavarian sawmill capacity constraints and Baltic supply disruptions are compressing margins for timber-frame specialists dependent on certified spruce sources.
- KBA transport compliance costs:Vehicle-type approval requirements for oversized module haulage add fixed costs that penalize smaller manufacturers without dedicated logistics fleets.
- Site-built construction substitution:Conventional developers in eastern Germany retain cost advantages where land availability reduces the time-value premium that justifies factory production.
Strategic Opportunities
- Commercial-to-residential conversion niche:Adaptive reuse of obsolete office and retail stock in Rhine-Ruhr cities creates demand for modular infill units that ALHO Modular Buildings and similar specialists can supply.
- GEG amendment pipeline:Pending federal revisions to efficiency thresholds will favor manufacturers with pre-certified wall systems already tested to DIN 68800 durability standards.
- Rental housing yield compression:Institutional investors are sourcing manufactured units for build-to-rent portfolios, creating volume contracts that stabilize production scheduling.
Industry Challenges
- DIN certification timeline compression:Regional Bauaufsichtsbehörden inspection backlogs are extending type-approval cycles, delaying revenue recognition for new product lines.
- Integration complexity with legacy utility hookups:Municipal water and electrical connection standards vary across German states, forcing customization that erodes the cost advantage of standardized factory output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Manufactured Homes Market |
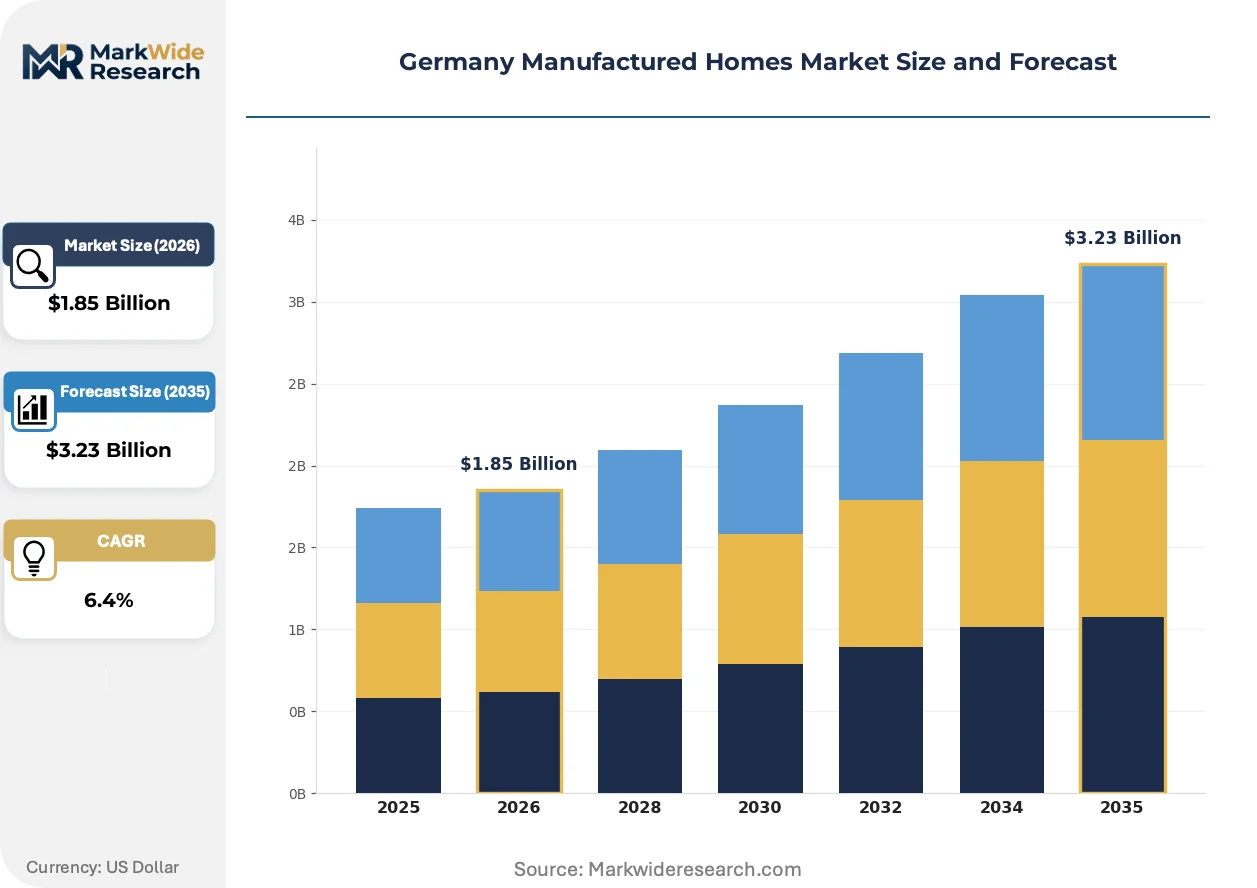
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Modular Homes, Prefabricated Homes, Mobile Homes, Panelized Homes End User: Residential Buyers, Investors, Developers, Real Estate Firms Distribution Channel: Direct Sales, Retail Outlets, Online Platforms, Construction Companies Installation Type: On-Site Assembly, Off-Site Construction, Full-Service Package, Turnkey Solutions |
| Companies Covered | Swietelsky AG, DFH Group, Portakabin, ALHO Modular Buildings, Baufritz, Fertighaus Weiss GmbH, Hanse Haus, HusCompagniet A/S, Karmod, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Manufactured Homes Market Shifts & Advancements
Factory automation and digital prefabrication are collapsing the traditional separation between design engineering and physical production. German manufacturers are deploying these capabilities to compress delivery windows while satisfying tightening regulatory thresholds.
Cross-laminated timber (CLT) is overtaking conventional timber-frame methods in premium manufactured home segments. CLT panels deliver structural rigidity and thermal mass in a single factory-fabricated element. Bavarian and Baden-Württemberg developers specify CLT for multi-story modular projects where fire resistance ratings exceed stick-frame capabilities. The technology is overtaking site-built alternatives in projects requiring rapid weatherproofing closure.
GEG efficiency thresholds are tightening faster than site-built contractors can adapt insulation installation methods. The regulation mandates specific U-values for wall and roof assemblies that factory-controlled environments achieve with repeatable precision. Panelized home manufacturers in southern Germany are capturing share from conventional builders unable to guarantee thermal performance compliance on variable job sites. State-level enforcement by regional Bauaufsichtsbehörden is accelerating this displacement.
Rental housing investors are consolidating procurement around turnkey package contracts that bundle foundation, transport, and on-site finishing. This purchasing consolidation displaces the traditional model where buyers separately contracted each phase. Institutional investors in Rhine-Ruhr and Frankfurt metropolitan areas now specify fixed-price, fixed-timeline delivery contracts that only vertically integrated manufacturers can underwrite. The shift is most visible in build-to-rent portfolios targeting yield-stabilized long-term holdings.
Germany Manufactured Homes Market Segmentation
Segmentation in the Germany manufactured homes market reveals how regulatory pressure and buyer sophistication are fragmenting demand across technical specifications and service models. Manufacturers must align product architecture with distinct procurement channels and installation requirements to capture share.
Product Type:
Replacement cycles for aging housing stock in Bavaria and Baden-Württemberg are accelerating upgrade decisions toward factory-built alternatives that compress weatherproofing timelines.
- Modular Homes:Volumetric units engineered to DIN 68800 durability standards arrive site-ready with MEP rough-ins completed. Rhine-Ruhr institutional investors specify these for build-to-rent portfolios where lease commencement dates are fixed.
- Panelized Homes:Factory-insulated wall and roof assemblies meet GEG thermal performance thresholds through repeatable precision that variable site work cannot replicate. Southern German municipalities favor these for infill on plots too constrained for conventional crane access.
- Prefabricated Homes:Broad category spanning timber-frame and steel systems with standardized connection details.
- Mobile Homes:KBA vehicle-type approval governs transport compliance for units relocated across state boundaries.
Modular homes sit at the top of the volume ranking, with panelized homes climbing the fastest.
End User:
Cost tier differentiation separates buyers seeking turnkey convenience from those optimizing per-unit acquisition economics through self-managed assembly.
- Residential Buyers:First-time purchasers in southern Germany leverage KfW development bank financing for turnkey packages that reduce down-payment barriers versus site-built mortgages. These buyers prioritize fixed-price contracts and occupancy timelines.
- Investors:Institutional capital in Frankfurt and Rhine-Ruhr metropolitan areas sources manufactured units for yield-stabilized rental portfolios. Volume procurement contracts stabilize production scheduling for preferred manufacturers.
- Developers:Project sponsors commercializing small-lot infill where land scarcity justifies factory production speed.
- Real Estate Firms:Brokerage-advisory entities bundling manufactured home placement with land acquisition services.
Residential buyers anchor current volume, with investors gaining share fastest amid rental housing yield compression.
Distribution Channel:
Geography dictates channel viability, with rural municipalities favoring relationship-based procurement while urban infill buyers migrate toward digital configuration tools.
- Direct Sales:Manufacturer-employed consultants engage buyers through design centers in Bavaria and Baden-Württemberg. These channels capture premium margins by bundling customization with foundation and transport coordination.
- Retail Outlets:Independent dealers display model units and manage local permitting relationships. Regional concentration in southern Germany reflects land scarcity-driven demand density.
- Online Platforms:Digital configuration tools with instant pricing attract younger buyers comfortable with remote specification.
- Construction Companies:General contractors subcontract manufactured home installation as component of broader development scope.
Direct sales dominate revenue concentration, with online platforms expanding most quickly among first-time buyer segments.
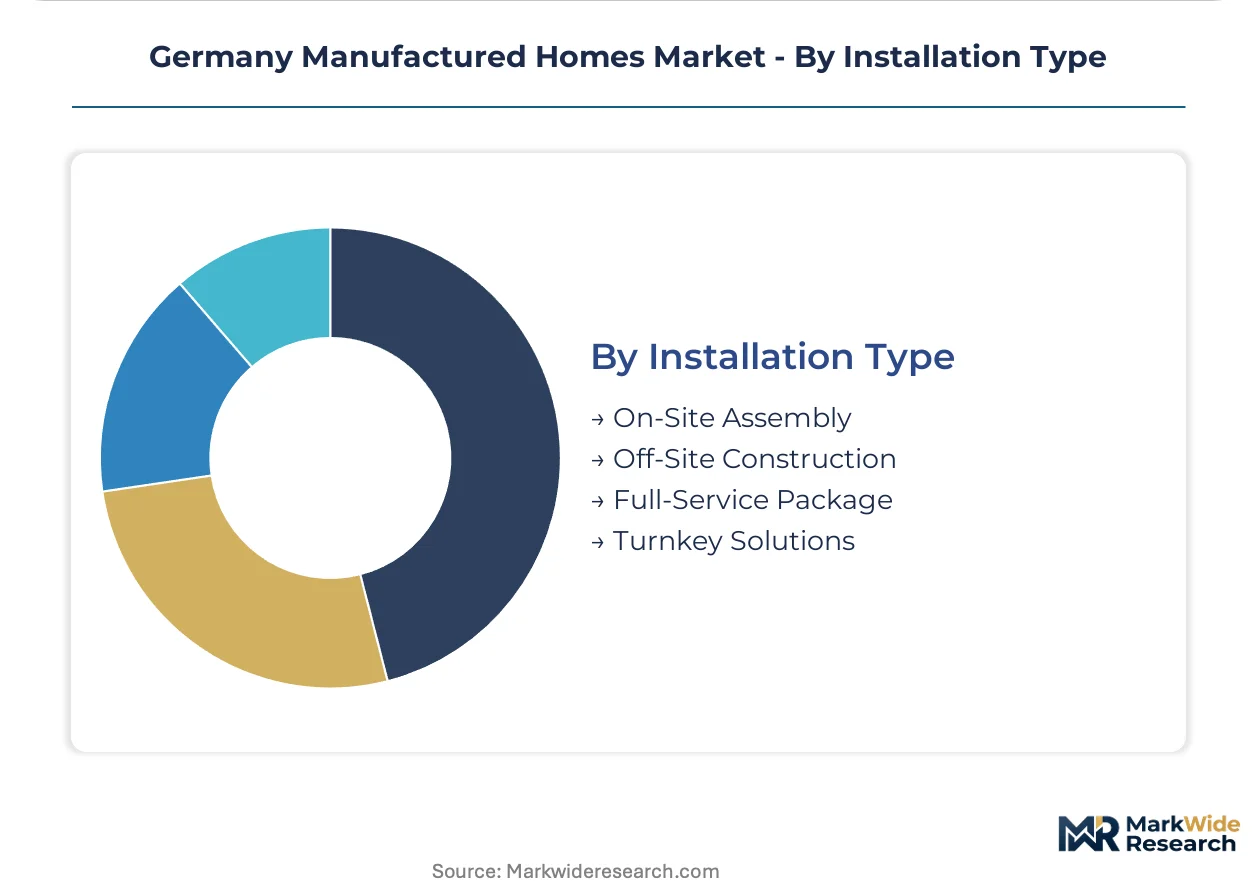
Installation Type:
Margin structure varies sharply by service depth, with full integration commanding premium pricing over component supply.
- Turnkey Solutions:Vertically integrated providers control foundation, transport, on-site finishing, and utility hookup through single-contract liability. These packages capture preference where municipal water and electrical connection standards vary across German states.
- Full-Service Package:Bundled offerings spanning factory delivery through weatherproofing closure, with buyer-retained finishing trades.
- On-Site Assembly:Buyer-contracted local crews complete module connection and envelope sealing.
- Off-Site Construction:Factory-only scope with buyer responsibility for all site logistics and regulatory compliance.
Turnkey solutions lead volume rankings, with full-service packages climbing fastest as investors seek balanced risk allocation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Factory-built housing first achieved industrial scale in Germany during the post-war reconstruction era, establishing Bavaria and Baden-Württemberg as the foundational manufacturing clusters that persist today.
Bavaria
Land scarcity around Munich and Nuremberg drives municipal zoning relaxations permitting manufactured homes on sub-400-square-meter plots. The GEG thermal performance mandates favor factory-insulated wall systems that manufacturers in the Augsburg industrial corridor deliver with repeatable precision. Timber-frame specialists cluster along the Alpine foothills where Bavarian sawmill networks supply certified spruce feedstock.
Baden-Württemberg
Stuttgart's automotive supplier belt generates skilled labor pools that panelized home manufacturers recruit for precision assembly operations. State-level Bauaufsichtsbehörden enforcement of DIN 68800 durability standards accelerates type-approval cycles for producers with dedicated certification teams. The Black Forest region hosts cross-laminated timber innovators supplying multi-story modular projects to Freiburg and Karlsruhe developers.
North Rhine-Westphalia
Rhine-Ruhr metropolitan adaptive reuse projects create demand for modular infill units as obsolete office stock converts to rental housing. KfW development bank preferential loan terms for turnkey packages reduce down-payment barriers for first-time buyers in Cologne and Düsseldorf suburbs. ALHO Modular Buildings anchors commercial-to-residential conversion activity from its base in the region.
Hesse
Frankfurt's institutional investor community sources manufactured units for yield-stabilized build-to-rent portfolios requiring fixed-price, fixed-timeline delivery contracts. The KBA vehicle-type approval framework governs oversized module transport compliance for haulage routes connecting central German production to Rhine-Main construction sites. Wiesbaden-area manufacturers specialize in turnkey bundling of foundation, transport, and on-site finishing.
Lower Saxony
Hanover and Brunswick municipalities experiment with manufactured home placement rights expansion as federal zoning law amendments pend. Conventional site-built construction retains cost advantages in eastern districts where land availability reduces the time-value premium justifying factory production. Regional water and electrical connection standard variations force customization that erodes standardized factory output advantages.
Germany Manufactured Homes Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification depth and service bundling intensity. The vendor base stratifies into vertically integrated turnkey providers, timber-frame specialists, and commercial-modular converters. Three archetypes dominate: full-service package bundlers controlling foundation-to-finishing liability, premium timber-frame engineers holding third-party sustainability credentials, and adaptive-reuse modularists targeting obsolete commercial stock. Capacity expansion and backward integration into captive CLT supply represent the dominant competitive moves.
Among German fabricators, Fertighaus Weiss GmbH, Baufritz, and ALHO Modular Buildings occupy distinct positioning vectors. Fertighaus Weiss exemplifies the vertically integrated archetype with supply chain control across southern German markets. Baufritz represents premium timber-frame specialization anchored by sustainability certification depth. ALHO Modular Buildings sits within the commercial-conversion tier where limited domestic competition protects margin structures. Swietelsky AG and DFH Group represent scale-driven alternatives with broader construction portfolio diversification. Hanse Haus and HusCompagniet A/S illustrate Nordic-German cross-border positioning in turnkey residential delivery.
| Leading Market Players |
|---|
| Swietelsky AG |
| DFH Group |
| Portakabin |
| ALHO Modular Buildings |
| Baufritz |
| Fertighaus Weiss GmbH |
| Hanse Haus |
| HusCompagniet A/S |
| Karmod |
| Others |
Supply & Pricing Matrix
Captive control over cross-laminated timber feedstock anchors both supply security and margin protection for southern German manufacturers responding to GEG thermal mandates. Bavarian sawmill networks and Baltic import channels concentrate upstream leverage, while turnkey bundling downstream captures pricing power through single-contract liability structures.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates DIN 68800-certified timber-frame specialists from panelized commodity producers and mobile home assemblers. Price differentiation hinges on third-party sustainability credential depth and volume-scale procurement contracts with institutional investors. Cost compression in the standard tier intensifies as eastern German site-built competition retains advantage where land availability reduces factory production premiums. First-time buyers in Bavaria exhibit highest price sensitivity, while Rhine-Ruhr rental housing investors prioritize fixed-timeline certainty over per-unit economics.
Supply Chain Analysis
Direct-to-developer channels handle institutional volume demand, bypassing independent retail networks for build-to-rent portfolio procurement. Raw material sourcing draws from Bavarian spruce forests, Austrian engineered timber mills, and Baltic cross-laminated timber producers. Component dependencies center on factory-insulated wall systems, precision-fit MEP rough-ins, and KBA-compliant transport chassis. Single-source vulnerability in certified timber feedstock poses structural risk as regional sawmill capacity constraints tighten. Distribution runs through vertically integrated manufacturer consultants in southern design centers and general contractor subcontracts in eastern municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany manufactured homes constitute a late-cycle quality story as GEG efficiency thresholds displace conventional construction toward factory-certified thermal performance. Residential buyer demand shifts toward turnkey packages with fixed-price liability and third-party sustainability verification.
For Market Incumbents: Acquire captive cross-laminated timber supply to secure margin protection against Bavarian sawmill capacity constraints and Baltic import volatility. Expand certification team capacity to compress DIN 68800 type-approval cycles as regional Bauaufsichtsbehörden inspection backlogs extend revenue recognition delays. Defensive positioning requires backward integration into engineered timber production and pre-emptive wall system testing to pending GEG amendment thresholds. For New Entrants and Emerging Players: The Building Energy Act in Germany opens a window for panelized home specialists with pre-certified thermal performance systems already validated to DIN standards. Target commercial-to-residential conversion white-space in Rhine-Ruhr obsolete office stock where ALHO Modular Buildings faces limited domestic competition. Pursue direct sales channel establishment with digital configuration tools to capture first-time buyer segments in southern municipalities. For Investors and Strategic Acquirers: Roll-up economics work for mid-scale turnkey providers because municipal zoning relaxations in Bavaria and Baden-Württemberg expand addressable plot inventory faster than organic capacity growth. Long-term viability frames around five-to-ten year rental housing yield compression sustaining institutional procurement volume. Acquisition target archetype: vertically integrated southern German fabricators with captive CLT supply and established KfW financing relationships. Signal to monitor: federal zoning law amendments expanding manufactured home placement rights beyond current land-use restrictions.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CLT Supply | Captive timber feedstock secures margin protection against Bavarian sawmill capacity constraints. |
| Pre-Certification to Pending GEG Amendments | Pre-tested wall systems accelerate revenue recognition as Bauaufsichtsbehörden enforcement tightens. |
| Digital Configuration Platform Launch | Remote specification tools capture first-time buyer segments in southern German municipalities. |
| Commercial-to-Residential Conversion Specialization | Rhine-Ruhr obsolete office adaptive reuse creates defensible niche with limited domestic competition. |
| Institutional Volume Contracting | Fixed-price, fixed-timeline delivery terms stabilize production scheduling for build-to-rent portfolios. |
Research Methodology
Coverage spans Bavaria, Baden-Württemberg, North Rhine-Westphalia, Hesse, and Lower Saxony, with primary inputs from each region's manufacturing clusters and municipal planning authorities. The study combines structured interviews with factory operations directors, regional Bauaufsichtsbehörden certification officers, KfW development bank lending specialists, and institutional real estate portfolio managers with secondary validation. Secondary sources include DIN standards documentation, KBA vehicle-type approval filings, federal GEG regulatory texts, and state-level zoning ordinance databases. Bottom-up production volume estimates triangulate against top-down housing completion data.
Granularity-level modeling disaggregates volume and value outputs across product type, end user, distribution channel, and installation type dimensions, with additional segmentation by regional regulatory enforcement intensity and timber-frame versus steel-module material architecture. CAGRs derive from regression analysis of historical placement rates against GEG compliance cost curves and municipal zoning relaxation timelines. Forecast inputs incorporate cross-laminated timber supply elasticity, KBA transport compliance cost trajectories, and KfW preferential loan term availability.
Revisions become necessary when federal zoning law amendments materially expand or restrict manufactured home placement rights, when Baltic timber supply disruptions exceed historical volatility bands, or when GEG thermal performance thresholds accelerate beyond current regulatory pipeline indications. Forecasts reflect documented assumptions regarding municipal enforcement consistency and development bank financing continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Residential Real Estate Market
South Africa Residential Real Estate Market
Residential Real Estate Market
Online Home Rental Market
Residential Real Estate Market
India Manufactured Homes Market
Residential Real Estate Market
Turkey Residential Real Estate Market
Residential Real Estate Market
United States Residential Real Estate Market
Residential Real Estate Market
Armenia Real Estate Market
Residential Real Estate Market
Qatar Residential Real Estate Market
Residential Real Estate Market
United States Manufactured Homes Market
Residential Real Estate Market
ASEAN Manufactured Homes Market
Residential Real Estate Market
E House Market
Residential Real Estate Market
Global Log Cabins or Log Homes Market
Residential Real Estate Market
India Residential Construction Market
Residential Real Estate Market
Vietnam Residential Real Estate Market
Residential Real Estate Market
UK Residential Real Estate Market
Residential Real Estate Market
Asia Pacific Manufactured Homes Market
Residential Real Estate Market
Malaysia Residential Real Estate Market