
 Real Estate Investment Trust (REIT) Market | 2026-2036
Real Estate Investment Trust (REIT) Market Size, Share, and Industry Trends Forecast 2026-2036
Real Estate Investment Trust (REIT) Market Insights
Modular fund structuring is expanding across REIT offerings as sponsors unbundle property-specific vehicles from diversified portfolio trusts to match risk-return appetites. Prologis leverages its industrial specialization to dominate logistics-heavy Sun Belt markets. Equinix sustains technology leadership in data center REITs through hyperscale leasing relationships. American Tower Corporation anchors wireless infrastructure exposure as 5G densification drives tower demand.
A Real Estate Investment Trust is a corporation, trust, or association that owns, operates, or finances income-producing real estate and distributes at least 90% of taxable income to shareholders to maintain pass-through tax status. The vehicle pools capital from multiple investors to acquire or develop commercial property portfolios spanning office towers, apartment complexes, warehouses, and specialized facilities. Industrial REITs now lead asset-class inflows as e-commerce fulfillment requirements reshape warehouse specifications and locations. Core strategies attract pension fund allocations seeking stabilized yield, while opportunistic vehicles compete for value-added repositioning plays in transitional submarkets. Equity structures control the majority of fund flows, though mortgage REITs occupy a specialized niche financing commercial real estate debt.
The US SEC enforces disclosure and registration frameworks under the Investment Company Act of 1940, while the IRS administers qualifying income tests and distribution requirements that preserve REIT tax advantages. The EU's AIFMD and individual member-state regulators shape cross-border fund marketing and leverage constraints for European-listed vehicles. Stakeholders must monitor interest-rate trajectories and their compression effects on capitalization rates across property sectors.
Market Dynamics
Capital rotation from fixed-income instruments into yield-bearing real assets is compressing cap rates across institutional-grade property portfolios, while the Federal Reserve's policy trajectory restructures leverage economics for acquisition finance.
Growth Catalysts
- Sun Belt Migration:Population inflows into Texas, Florida, and Arizona metropolitan corridors are tightening industrial and multifamily vacancy rates, lifting net operating income projections for logistics and residential REITs concentrated in these corridors.
- IRS Qualifying Income Tests:The Internal Revenue Code's distribution requirements preserve pass-through tax status for REITs meeting the 90% taxable income distribution threshold, sustaining yield competitiveness against corporate bond alternatives.
- Hyperscale Data Center Demand:Cloud computing providers are pre-leasing speculative shell space in primary and secondary markets, accelerating absorption timelines and reducing lease-up risk for data center REIT development pipelines.
Market Restraints
- Interest Rate Volatility:SOFR-linked floating-rate construction debt exposes development pipelines to margin compression when central bank policy tightens, particularly affecting value-add repositioning strategies dependent on bridge financing.
- Construction Input Cost Escalation:Steel and concrete price volatility in North American markets is eroding development yields on ground-up industrial and multifamily projects, forcing sponsors to restructure joint venture promote hurdles.
- Zoning Entitlement Timelines:Municipal approval processes in supply-constrained coastal jurisdictions extend project completion schedules by 18-36 months, trapping capital and diluting internal rate of return targets.
Strategic Opportunities
- India REIT Market Liberalization:SEBI's 2019 REIT regulations and subsequent amendments are enabling institutional capital formation for commercial office and warehousing assets in Bengaluru, Mumbai, and Delhi-NCR corridors.
- Edge Computing Facility Deployment:Convergence of 5G network densification and latency-sensitive application workloads is creating demand for sub-10 megawatt facilities in secondary metropolitan markets currently underserved by hyperscale campuses.
- EU Green Deal Alignment:CSRD disclosure mandates and taxonomy alignment requirements are directing capital toward REITs with certified sustainable building portfolios, creating premium valuation multiples for ESG-compliant assets.
Industry Challenges
- Asset-Level Data Integration:Legacy property management systems across acquired portfolios resist seamless integration with centralized investment analytics platforms, delaying real-time occupancy and rent roll visibility for portfolio managers.
- Specialized Asset Valuation Expertise:Scarce underwriting talent for data center power density specifications and cooling redundancy tiers constrains due diligence velocity for technology infrastructure acquisitions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Real Estate Investment Trust (REIT) Market |
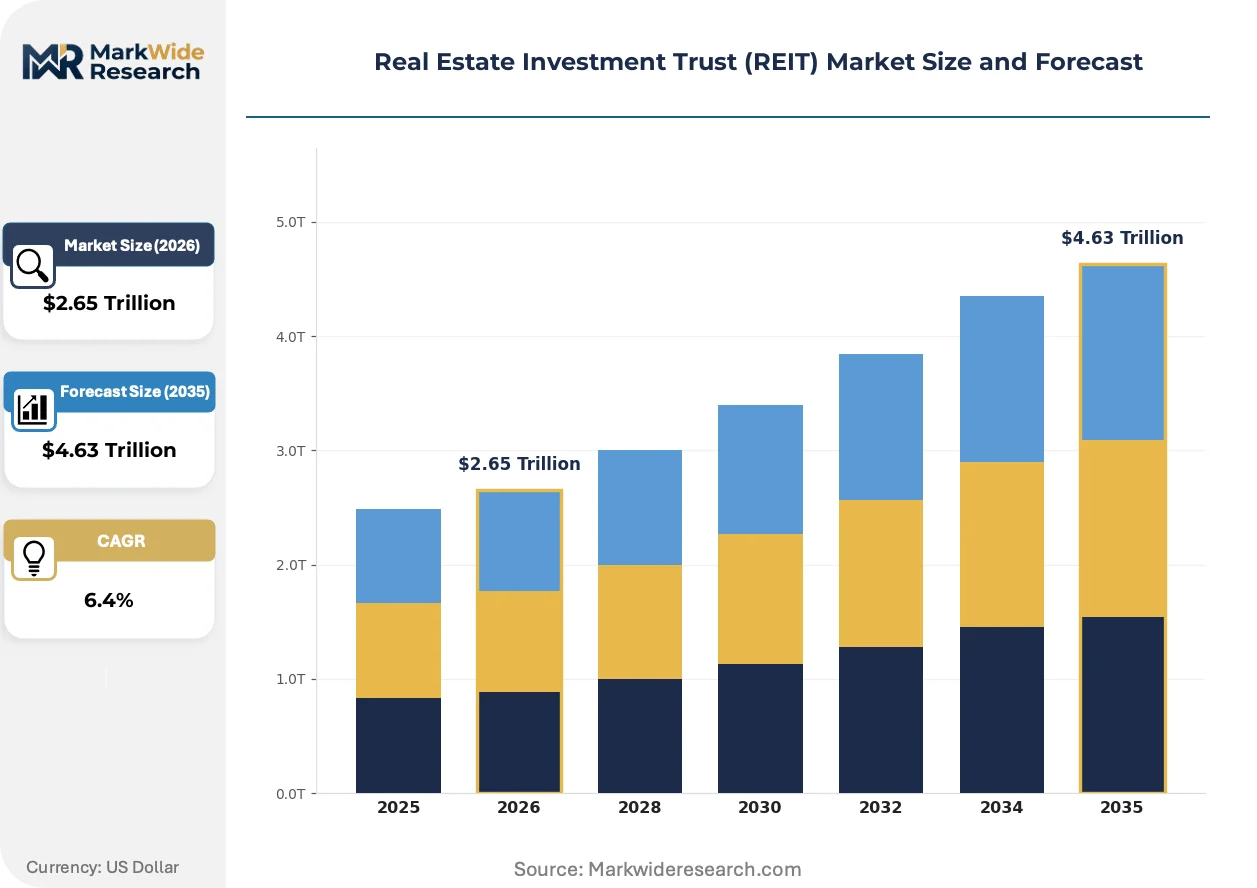
| Market Size in 2026 | $2.65 Trillion |
| Market Size in 2035 | $4.63 Trillion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Asset Class: Office, Retail, Residential, Industrial, Hospitality, Healthcare Investment Strategy: Core, Core Plus, Value-Added, Opportunistic Investor Type: Institutional, High Net Worth Individuals, Pension Funds, Sovereign Wealth Funds, Retail Investors Fund Structure: Equity, Mortgage, Hybrid, Public Non-Listed |
| Companies Covered | Prologis, Equinix, American Tower Corporation, Welltower, Digital Realty, Realty Income, Crown Castle International, Equity Residential, Federal Realty Investment Trust, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Real Estate Investment Trust (REIT) Market Trends and Innovations
Operational technology deployment is transforming how income-producing assets are managed, with sensor networks and predictive analytics compressing operating expense ratios while repositioning property management from cost center to value driver.
Smart building management systems are expanding into core operational infrastructure for Class A office and industrial portfolios. Institutional landlords are deploying these platforms to optimize HVAC energy consumption and predictive maintenance scheduling across million-square-foot footprints. The technology is expanding into tenant experience applications, with mobile-enabled access control and space utilization analytics commanding rent premiums in competitive submarkets.
The SEC's climate disclosure rules are mandating Scope 1 and 2 emissions reporting for publicly traded REITs, with materiality assessments extending to financed emissions in mortgage REIT portfolios. This regulatory architecture is forcing asset-level utility data aggregation and third-party verification engagements. Industrial and data center segments face the steepest compliance burden given energy intensity profiles, with some sponsors accelerating on-site renewable generation to deflect regulatory scrutiny.
Institutional capital deployment is rotating from core stabilized assets to value-add and opportunistic strategies as compressed cap rates in primary markets erode return targets. Pension fund allocators are directly underwriting development joint ventures rather than paying promote structures to external sponsors, capturing fee savings and governance control. This behavioral shift is most pronounced in Sun Belt logistics corridors where e-commerce absorption supports speculative development without pre-leasing commitments.
Real Estate Investment Trust (REIT) Market Segmentation
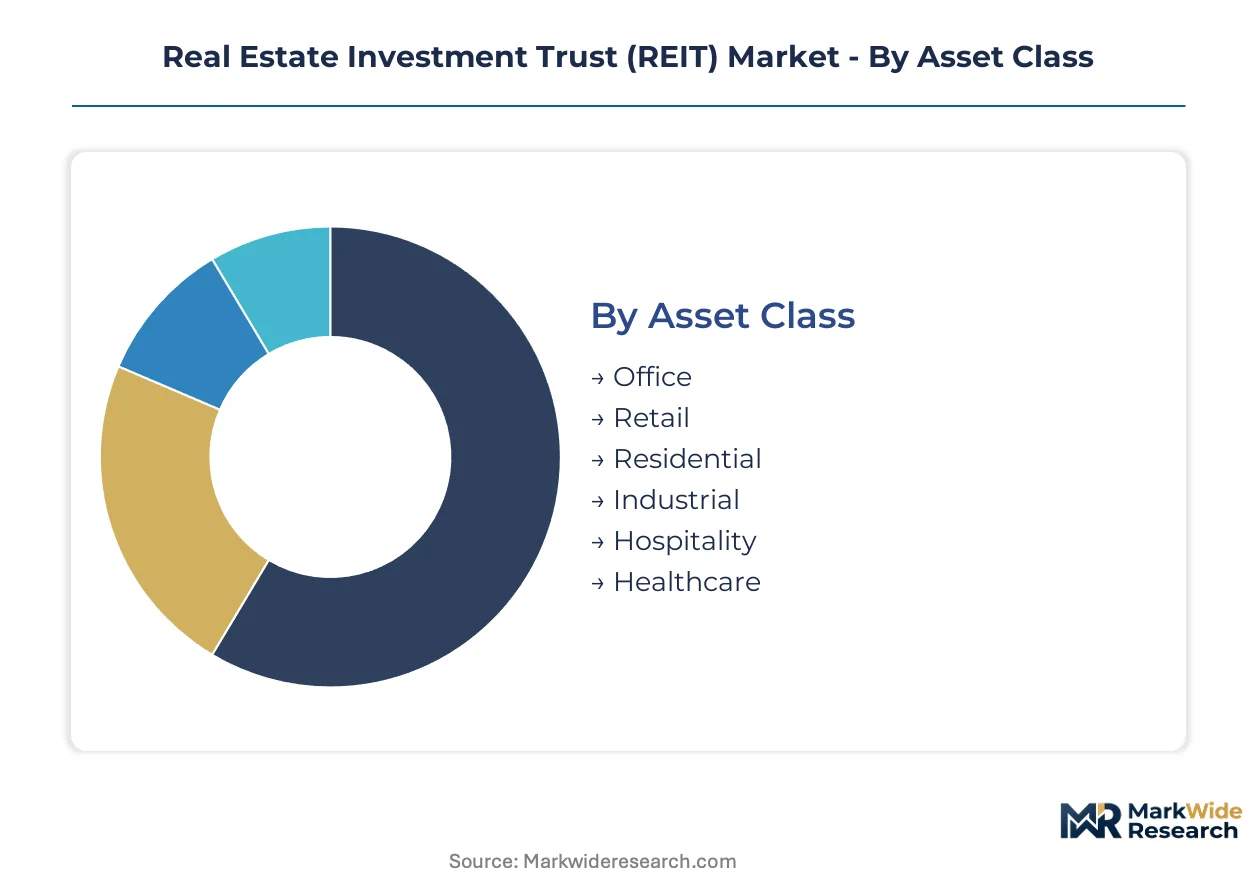
REIT segmentation reveals how capital partitions across risk-return profiles and asset-specific income streams. Sponsors structure vehicles to match liability duration with property cash flow stability.
Asset Class:
Standardization dominates income-producing property, yet specialization accelerates in logistics and digital infrastructure segments.
- Industrial:Warehouse and distribution facilities command premium valuations as e-commerce fulfillment requirements reshape specifications. Demand concentrates in Dallas-Fort Worth, Phoenix, and Atlanta corridors where land availability supports million-square-foot campuses.
- Data Center:Hyperscale leasing relationships with cloud computing providers drive pre-leasing velocity for speculative shell developments. Northern Virginia, Frankfurt, and Singapore anchor primary market absorption for power-dense facilities.
- Residential:Multifamily apartment complexes generate stabilized yield in supply-constrained metropolitan areas.
- Healthcare:Medical office buildings and senior housing facilities capture demographic-driven occupancy growth.
- Office:Central business district towers face hybrid work headwinds compressing effective rents.
- Retail:Grocery-anchored neighborhood centers outperform regional mall formats experiencing tenant attrition.
- Hospitality:Full-service hotels and select-service properties exhibit cyclical cash flow volatility.
Leading the category by volume: Industrial. Expanding most quickly: Data Center.
Investment Strategy:
Risk tolerance stratifies capital deployment from stabilized income to ground-up development exposure.
- Core:Fully leased institutional-grade assets in primary markets deliver bond-like income stability. Pension fund allocations target these positions for liability matching.
- Core Plus:Properties with modest lease rollover or light value-add components attract investors seeking yield enhancement without development risk.
- Value-Added:Repositioning strategies involving tenant mix optimization or physical renovation capture rent growth in transitional submarkets.
- Opportunistic:Ground-up development and distressed acquisition strategies offer the highest return targets alongside construction and entitlement risk.
Dominating institutional flows: Core. Gaining share fastest: Opportunistic Sun Belt logistics development.
Investor Type:
Capital source determines governance rights, liquidity expectations, and fee tolerance in fund structures.
- Pension Funds:Defined benefit plans with long-duration liabilities favor core and core-plus strategies for yield stability. CalPERS and Canadian Maple Eight directly underwrite joint ventures to capture promote savings.
- Sovereign Wealth Funds:State-owned investment vehicles deploy patient capital into trophy assets and development platforms.
- Institutional:Insurance companies and endowments balance liquidity needs with real asset inflation hedging.
- High Net Worth Individuals:Family offices access private REITs and 1031 exchange vehicles for tax-deferred accumulation.
- Retail Investors:Publicly traded REIT shares provide liquid exposure to commercial real estate returns.
Controlling majority capital: Pension Funds. Expanding allocation fastest: Sovereign Wealth Funds.
Fund Structure:
Legal and tax architecture shapes distribution mechanics and investor access tiers.
- Equity:Direct property ownership structures dominate institutional flows, with sponsors charging asset management and acquisition fees.
- Mortgage:Commercial real estate debt financing occupies a specialized niche for yield-focused investors.
- Hybrid:Structures combining property ownership with debt exposure balance income stability with upside optionality.
- Public Non-Listed:Perpetual-life vehicles offer retail access without exchange volatility, though secondary liquidity remains constrained.
Commanding institutional preference: Equity. Attracting retail inflows: Public Non-Listed.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Capital deployment for income-producing real estate concentrates in jurisdictions offering favorable tax pass-through structures and deep institutional investor pools. Consumption of REIT vehicles spans pension funds, sovereign wealth vehicles, and retail shareholders seeking yield-bearing real asset exposure.
United States
Sun Belt metropolitan corridors in Texas, Florida, and Arizona absorb the majority of industrial and multifamily development capital as population migration tightens vacancy rates. The SEC enforces disclosure frameworks under the Investment Company Act of 1940 alongside IRS qualifying income tests that preserve pass-through tax status for vehicles distributing 90% of taxable income. Northern Virginia anchors data center absorption as hyperscale cloud providers pre-lease speculative shell space.
United Kingdom
London and Southeast England concentrate listed REIT activity for commercial office and logistics assets, though hybrid work patterns compress central business district effective rents. The Financial Conduct Authority administers prospectus and listing rules for premium and standard segments of the Main Market. Regional logistics clusters around the Midlands and Yorkshire attract institutional capital for last-mile fulfillment facilities serving e-commerce demand.
Germany
Frankfurt and Munich metropolitan areas dominate commercial office REIT portfolios, while Hamburg and Düsseldorf logistics corridors benefit from central European distribution positioning. BaFin supervises investment fund regulation under the German Capital Investment Code, with EU AIFMD shaping cross-border marketing constraints. The Rhine-Ruhr industrial conurbation supports warehouse absorption as automotive and manufacturing supply chains require modernized storage infrastructure.
Singapore
The city-state serves as a listing venue for Asia-Pacific property vehicles, with sponsors accessing regional institutional capital through the Singapore Exchange. The Monetary Authority of Singapore regulates REITs under the Code on Collective Investment Schemes, with tax transparency provisions attracting cross-border fund formation. Data center and logistics assets across Southeast Asia increasingly feature in Singapore-listed vehicle portfolios.
India
SEBI's 2019 REIT regulations and subsequent amendments enable institutional capital formation for commercial office and warehousing assets in Bengaluru, Mumbai, and Delhi-NCR corridors. Foreign portfolio investors access rupee-denominated yields through these vehicles as the regulator relaxes investment restrictions. The Mumbai financial district and Hyderabad's IT corridors anchor initial listings, with warehousing penetration expanding in Pune and Chennai peripheral markets.
Real Estate Investment Trust (REIT) Market Competitive Landscape
The competitive structure tilts toward specialized asset-class vehicles rather than diversified portfolio trusts. Industrial and data center REITs command premium valuations as e-commerce fulfillment and cloud computing demand reshape investor preferences. Three archetypes dominate: logistics-heavy industrial specialists, hyperscale data center operators, and wireless infrastructure platforms. Consolidation through portfolio acquisitions and development joint ventures represents the primary competitive dynamic, alongside geographic expansion into secondary metropolitan markets.
Among specialized industrial operators, Prologis anchors logistics-heavy Sun Belt exposure. Equinix occupies a position exemplifying hyperscale data center leasing relationships with cloud providers. American Tower Corporation represents wireless infrastructure specialization as 5G densification requirements sustain tower demand. These three entities collectively illustrate how asset-class focus commands institutional capital allocation in a market rotating away from diversified office and retail exposure.
| Leading Market Players |
|---|
| Prologis |
| Equinix |
| American Tower Corporation |
| Welltower |
| Digital Realty |
| Realty Income |
| Crown Castle International |
| Equity Residential |
| Federal Realty Investment Trust |
| Others |
Pricing and Supply Chain Analysis
Smart building management system deployment across institutional-grade portfolios is compressing operating expense ratios while simultaneously concentrating supplier relationships among integrated technology vendors. This operational technology transition simultaneously reshapes cost economics for property management and creates sourcing concentration around sensor hardware and predictive analytics platforms.
Pricing Analysis
Margin tightening in core stabilized assets reflects capital rotation into value-add strategies as compressed cap rates erode yield targets. Three-tier pricing structure across premium, standard, and economy levels stratifies by asset vintage and ESG certification tier, with LEED Platinum and BREEAM Outstanding commanding rent premiums. Pricing pressure intensifies in secondary office markets as hybrid work patterns reduce effective rents. Pension fund allocators exhibit lowest price sensitivity given liability-matching mandates, while retail investors in non-listed vehicles demonstrate highest sensitivity to fee load and distribution yield.
Supply Chain Analysis
Domestic-content mandates in Indian warehousing development and US Buy America provisions for infrastructure-adjacent real estate are reshaping sourcing patterns for steel and concrete inputs. Supply concentrates in China for HVAC equipment and building automation systems, in Germany for precision engineering components, and in Mexico for structural steel serving US Sun Belt construction. Raw material dependencies span structural steel, cement, copper wiring, and semiconductor chips for smart building controls. Single-source vulnerability concentrates in HVAC compressor manufacturing and specialized data center cooling equipment. Distribution runs through regional building material distributors and direct manufacturer relationships for large-scale development projects.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The REIT market operates as a cost-of-compliance arena where IRS qualifying income tests and SEC disclosure frameworks create structural moats for sponsors with established regulatory infrastructure and distribution capabilities.
For Market Incumbents: Deploy modular fund structuring to unbundle property-specific vehicles from diversified portfolio trusts, matching risk-return appetites with targeted investor segments. Consolidate Sun Belt logistics exposure through development joint ventures rather than external promote structures, capturing fee savings as pension funds directly underwrite positions. Counter interest rate volatility by lengthening debt maturity profiles and securing fixed-rate construction financing ahead of policy tightening cycles.
For New Entrants and Emerging Players: Enter via edge computing facility deployment in secondary metropolitan markets currently underserved by hyperscale campuses, leveraging 5G densification tailwinds and latency-sensitive application demand. Target India REIT market liberalization under SEBI regulations as the most penetrable geography, where foreign portfolio investor access is expanding and initial listings in Bengaluru and Mumbai establish precedent. Pursue go-to-market angles through joint ventures with established domestic developers to navigate entitlement timelines and local regulatory relationships.
For Investors and Strategic Acquirers: Exit pathways concentrate in portfolio acquisitions by sovereign wealth funds seeking trophy assets and development platforms, with IPO windows for specialized data center and logistics vehicles offering secondary liquidity routes. Long-term viability centers on sponsors with demonstrated entitlement execution capabilities and established hyperscale tenant relationships. Monitor Federal Reserve policy trajectory as the primary inflection signal for leverage economics and cap rate compression velocity across property sectors.
| Strategic Initiative | Industry Significance |
|---|---|
| Modular Fund Structuring | Unbundling property-specific vehicles matches risk-return profiles to institutional liability durations. |
| Sun Belt Development Joint Ventures | Direct pension fund underwriting eliminates external sponsor promotes in Dallas-Fort Worth corridors. |
| Edge Computing Facility Deployment | Sub-10 megawatt facilities in secondary markets capture 5G densification and latency-sensitive workloads. |
| ESG Certification Investment | LEED Platinum and BREEAM Outstanding assets command rent premiums under EU Green Deal alignment. |
| Hyperscale Tenant Pre-leasing | Cloud computing provider relationships accelerate absorption timelines for speculative data center shells. |
Research Methodology
Document review covered SEC registration statements, IRS revenue rulings, and SEBI regulatory circulars, complemented by interviews with REIT portfolio managers, pension fund real asset allocators, commercial mortgage underwriters, and property development executives. Secondary validation drew from NAREIT industry statistics, EPA energy benchmarking data, and sovereign wealth fund annual reports. Bottom-up property-level cash flow modeling triangulated against top-down institutional capital flow analysis.
Historical absorption patterns cross-referenced against panel input from development sponsors and investment consultants informed the analytical framework across the projection horizon. Segmentation dimensions modeled include asset class specialization, investment strategy risk tier, investor type governance structure, and fund structure tax architecture. CAGRs derived from rolling cap rate assumptions, rent growth trajectories, and development yield compression across metropolitan corridors. Forecast inputs incorporated interest rate scenario analysis and entitlement timeline distributions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained monetary tightening or construction input cost escalation scenarios. Projections reflect assumptions regarding Sun Belt migration velocity, hyperscale data center absorption rates, and regulatory stability for pass-through tax structures. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Real Estate
Sweden Luxury Residential Real Estate Market
Real Estate
Denmark Facility Management Market
Real Estate
South Africa Facility Management Market
Real Estate
Latin America Office Real Estate Market
Real Estate
Netherlands Luxury Residential Real Estate Market
Real Estate
Moldova Facility Management Market
Real Estate
Vietnam Self-Storage Market
Real Estate
China Residential Real Estate Market
Real Estate
Latin America Home Mortgage Finance Market
Real Estate
Central and Eastern Europe (CEE) Facility Management Market
Real Estate
Croatia Facility Management Market
Real Estate
Mexico Facility Management Market
Real Estate
South Korea Office Real Estate Market
Real Estate
United States Property Management Market
Real Estate
Belgium Luxury Residential Real Estate Market
Real Estate
Taiwan Facility Management Services Market