
 GCC Facility Management Market | 2026-2036
GCC Facility Management Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Facility Management Market Analysis
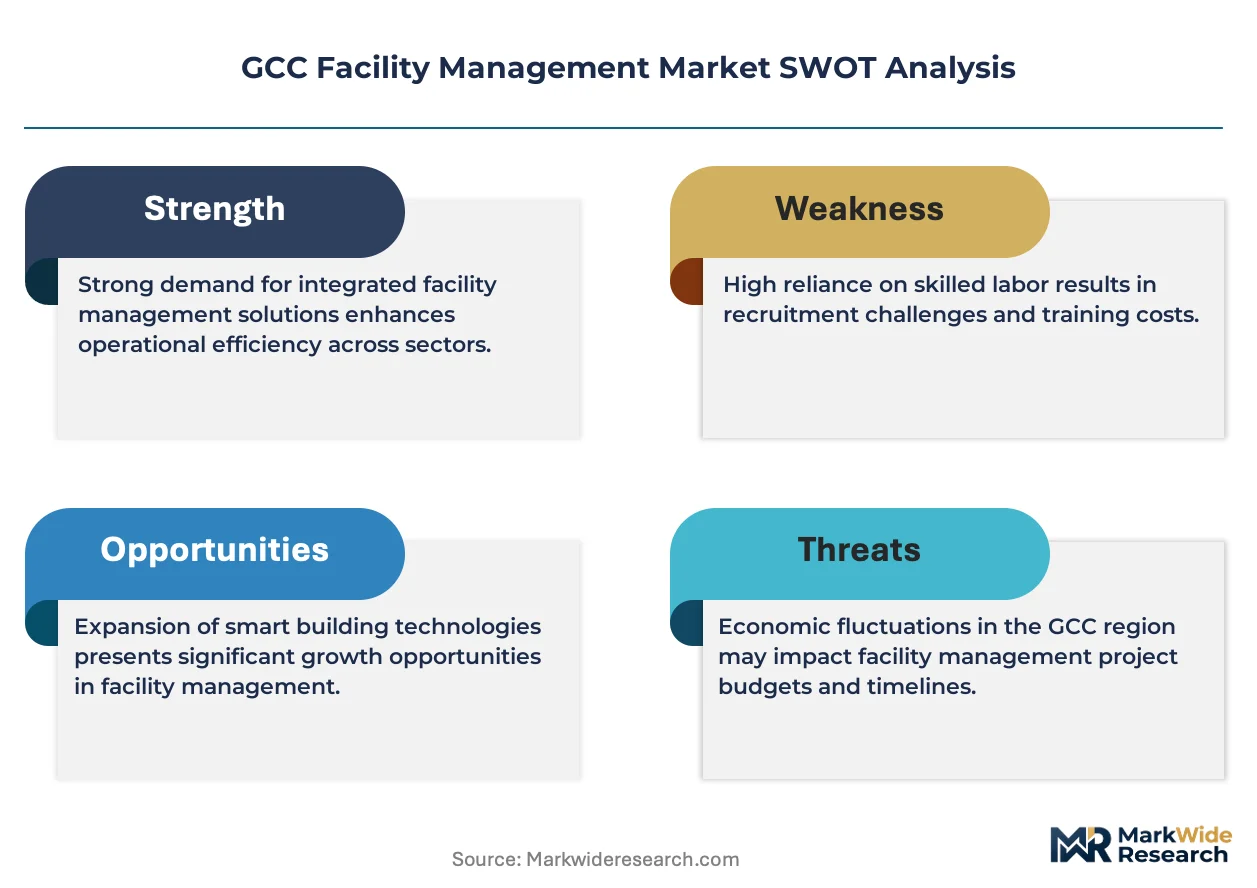
The capability gap between asset-heavy operators and labor-dependent contractors is collapsing across the GCC. Imdaad L.L.C. leverages its in-house workforce and fleet scale to dominate integrated hard services in Dubai's commercial core. Emrill Services LLC anchors its position through technology leadership in CAFM platforms and energy analytics. Farnek Services LLC differentiates via sustainability certification depth, competing for green-building contracts under escalating environmental compliance.
GCC facility management encompasses the coordinated delivery of hard services (mechanical, electrical, plumbing), soft services (cleaning, security, landscaping), and technology-enabled asset optimization across built environments. The discipline integrates IoT sensor networks, building automation protocols, and computerized maintenance management systems to extend asset life cycles and reduce operational expenditures. Maintenance services command the largest revenue pool due to mandatory regulatory inspections and climate-driven equipment degradation, while IoT Solutions within the Technology segment represents the fastest-expanding margin corridor as owners shift from reactive to predictive intervention models. Commercial client types generate disproportionate contract value through multi-site portfolio agreements, though government sector procurement is professionalizing under centralized tendering frameworks.
MOHAP in the UAE and Saudi Arabia's Saudi Building Code impose fire safety, water efficiency, and indoor air quality standards that elevate compliance costs for uncertified operators. Estidama Pearl Rating and LEED equivalents across Qatar and Bahrain further tie FM contract awards to verified sustainability performance. Stakeholders must monitor how carbon disclosure requirements and smart-city integration mandates reshape service bundling and vendor qualification thresholds.
Market Dynamics
The GCC facility management sector is compressing around integrated service bundling as giga-project developers demand single-accountability contracts spanning hard services, energy management, and predictive asset optimization.
Growth Catalysts
- Estidama Pearl Rating System:UAE's green building mandate is mandating energy analytics and water efficiency verification, forcing developers to outsource to certified FM operators capable of continuous compliance monitoring.
- Saudi giga-project pipeline:NEOM, Red Sea Global, and Qiddiya developments are awarding decade-long integrated FM contracts that bundle security, MEP maintenance, and IoT-enabled asset management under unified performance metrics.
- Predictive maintenance platforms:Computerized maintenance management systems with AI-driven failure prediction are displacing scheduled maintenance regimes, reducing downtime penalties for critical infrastructure operators.
Market Restraints
- Skilled technician scarcity:Saudi Arabia's Saudization quotas and UAE's Emiratization targets are constraining availability of certified MEP engineers, inflating wage costs for labor-dependent contractors.
- Equipment import dependency:HVAC components, BMS controllers, and IoT sensor hardware concentrate sourcing from East Asian manufacturers, exposing operators to shipping cost volatility and customs clearance delays.
- Fragmented subcontractor networks:Small cleaning and security providers lack CAFM integration capabilities, creating coordination friction for prime contractors attempting unified service delivery.
Strategic Opportunities
- Bahrain healthcare privatization:The kingdom's hospital outsourcing initiatives are creating demand for clinical-grade FM services combining infection control, medical gas maintenance, and 24/7 critical systems redundancy.
- Qatar smart city mandates:Lusail City and Msheireb Downtown Doha specifications require building automation protocol integration, opening contracts for FM-technology hybrid providers.
- Carbon disclosure convergence:Emerging Scope 3 reporting requirements for real estate investment trusts are creating advisory revenue streams around energy benchmarking and retrofit planning.
Industry Challenges
- CAFM-legacy BMS integration:Older buildings in Dubai's commercial core operate on proprietary automation protocols that resist seamless data extraction, forcing expensive gateway installations.
- Multi-certification compliance:Operators serving pan-GCC portfolios must maintain parallel ISO 55000, LEED AP, and Estidama PQP credentials, stretching training budgets and audit cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Facility Management Market |
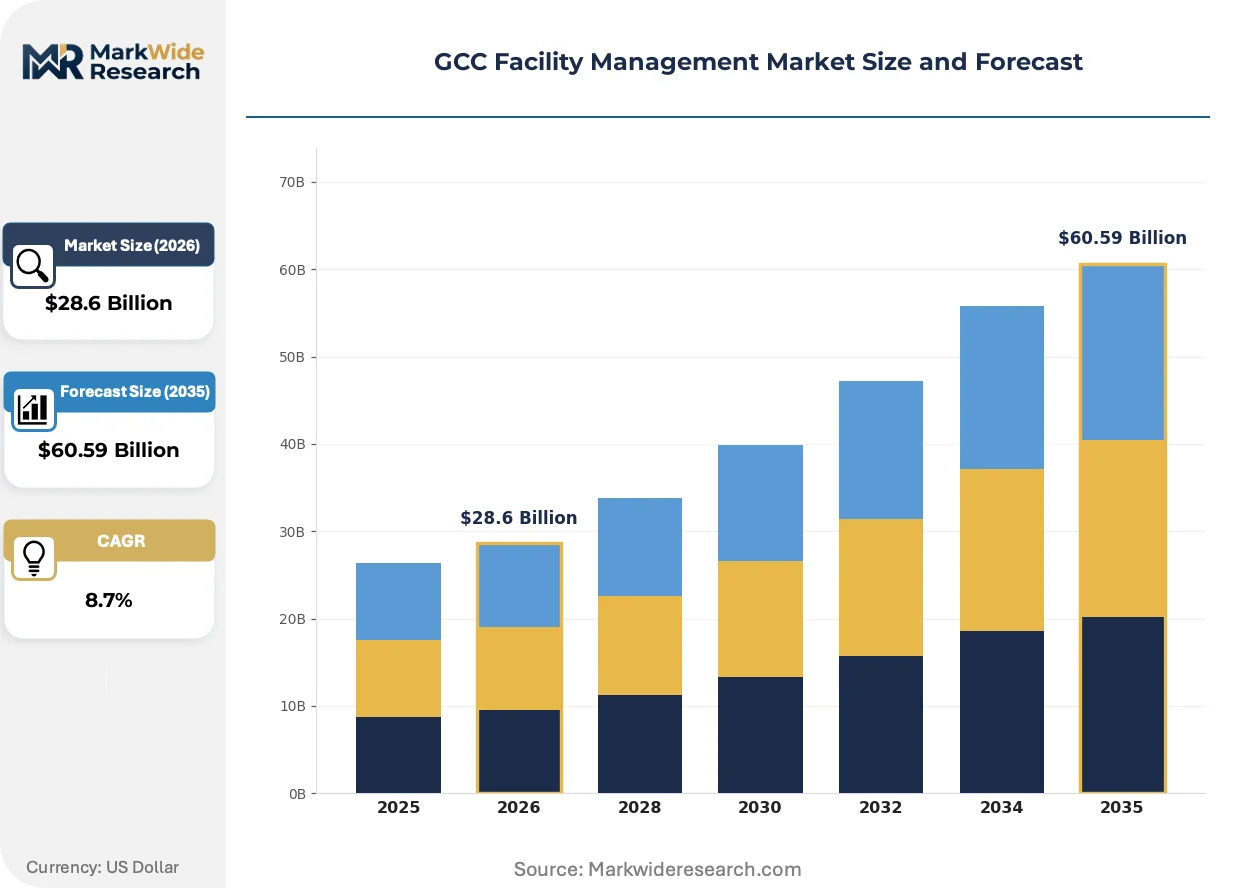
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Cleaning, Security, Maintenance, Landscaping Client Type: Commercial, Residential, Government, Industrial Technology: IoT Solutions, Automation Systems, Software Management, Energy Management End User: Office Buildings, Hospitals, Retail Spaces, Educational Institutions |
| Companies Covered | G4S Qatar SPC, Emrill Services LLC, Emcor Facilities Services WLL, Farnek Services LLC, Imdaad L.L.C., Sodexo Qatar Services, Cofely Besix Facility Management, Khidmah LLC, Al-Asmakh Facilities Management, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Facility Management Market Emerging Trajectories
Digital twin deployment is redefining asset lifecycle planning across GCC commercial portfolios, compressing the gap between design-phase specifications and operational performance data.
IoT sensor networks for vibration analysis, thermal imaging, and indoor air quality monitoring are miniaturizing from building-level installations to equipment-embedded units. Saudi Aramco's residential compounds and Dubai airport terminals are piloting chip-scale sensors with five-year battery life. This density shift is miniaturizing the cost per data point, enabling granular failure prediction for individual pump motors and air handling units rather than zone-level approximations.
MOHAP's updated fire safety and water efficiency technical guidelines are mandating real-time monitoring submission to centralized compliance portals. Facility operators must now maintain continuous data streams rather than quarterly inspection reports. Healthcare and education assets in Abu Dhabi and Dubai are responding by integrating their CAFM platforms directly with regulator APIs, automating deviation alerts and corrective action documentation.
Developer procurement teams are consolidating vendor panels around performance-guarantee contracts that transfer energy and maintenance cost risk to FM operators. This model displaces unit-rate invoicing for cleaning and security hours. Saudi giga-projects and Qatar's sovereign wealth real estate arms are pioneering this shift, selecting contractors based on guaranteed operational expenditure ceilings rather than input-based pricing.
GCC Facility Management Market Segmentation
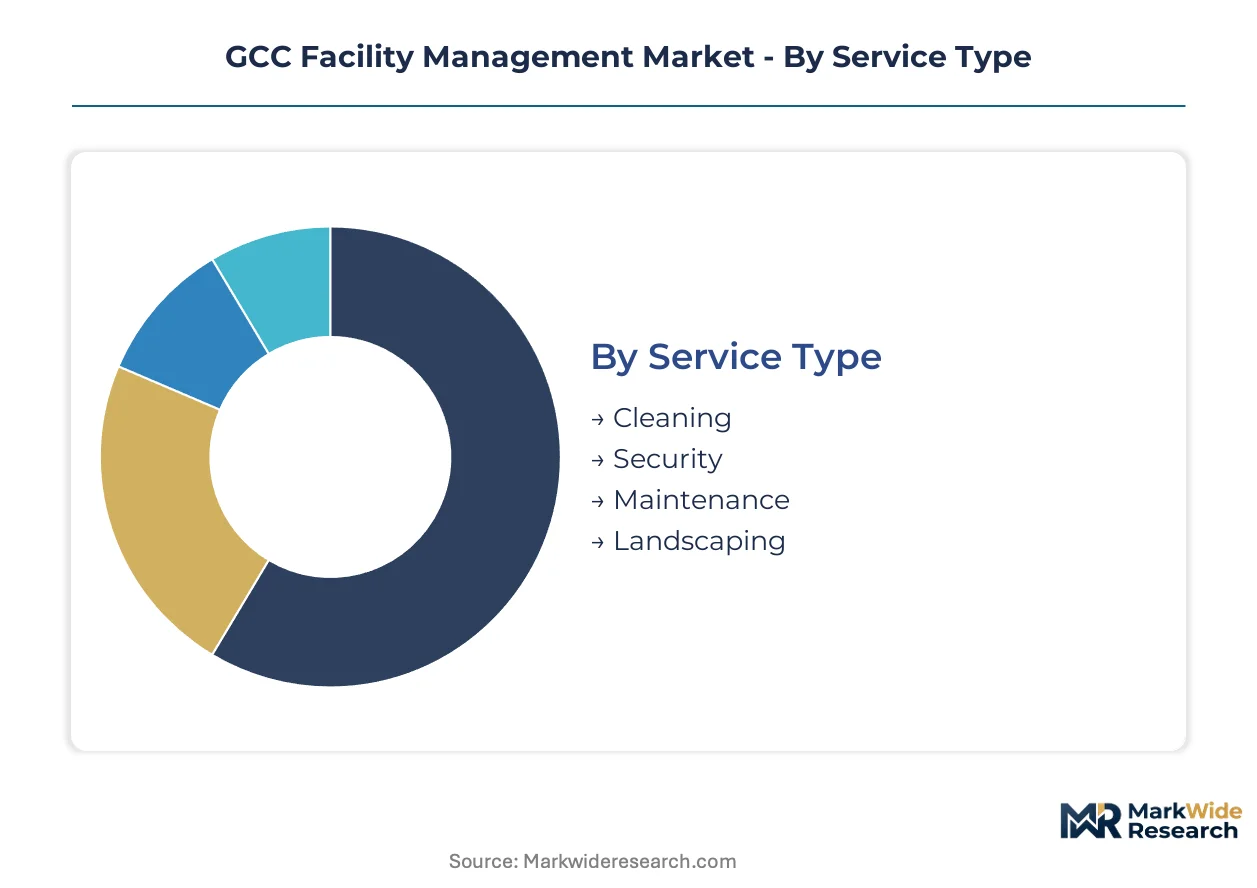
Service bundling patterns across the GCC facility management sector reflect divergent regulatory compliance burdens and asset criticality levels. Procurement teams weight segment selection against Estidama Pearl Rating mandates and Saudi Building Code enforcement intensity.
Service Type:
MOHAP fire safety directives and Saudi Building Code MEP inspection schedules create tiered compliance obligations that reshape contract scope allocation.
- Maintenance:Hard services encompassing mechanical, electrical, and plumbing systems operate under mandatory regulatory inspection cycles. Demand concentrates in Saudi Arabia's giga-project developments where decade-long integrated contracts bundle predictive asset optimization with energy performance guarantees.
- Security:Personnel-based and technology-enabled access control, surveillance, and threat response services. Procurement in Dubai's commercial core favors operators with in-house workforce scale capable of 24/7 critical infrastructure coverage under unified accountability structures.
- Cleaning:Commercial and clinical-grade sanitation services spanning routine janitorial to infection control protocols.
- Landscaping:Exterior grounds maintenance and irrigation management adapted to arid climate water efficiency requirements.
Maintenance handles the majority of throughput; IoT-enabled predictive maintenance within this segment is expanding most quickly on share.
Client Type:
Contract value scales with portfolio complexity and performance guarantee risk transfer intensity.
- Commercial:Multi-site office, retail, and hospitality portfolios generate disproportionate contract value through centralized procurement frameworks. Saudi sovereign wealth real estate arms and Qatar's Lusail City developers are pioneering performance-guarantee models that transfer operational expenditure risk to FM operators.
- Government:Public sector procurement is professionalizing under centralized tendering frameworks with escalating sustainability credential requirements.
- Residential:Compound and high-rise building management services driven by developer handover obligations and owner association mandates.
- Industrial:Manufacturing, logistics, and energy facility maintenance subject to specialized safety and continuous operations protocols.
Commercial clients dominate absolute contract value; Government procurement is gaining share fastest as Saudization and Emiratization targets reshape public sector outsourcing patterns.
Technology:
Digital infrastructure maturity determines margin expansion potential and competitive differentiation durability.
- IoT Solutions:Sensor networks for vibration analysis, thermal imaging, and indoor air quality monitoring are miniaturizing to equipment-embedded units. Saudi Aramco residential compounds and Dubai airport terminals pilot chip-scale sensors with extended battery life, enabling granular failure prediction for individual pump motors.
- Software Management:Computerized maintenance management systems and CAFM platforms anchor operational data integration. UAE healthcare and education assets are integrating directly with MOHAP regulator APIs to automate deviation alerts and corrective action documentation.
- Automation Systems:Building automation protocol integration for HVAC, lighting, and access control.
- Energy Management:Analytics platforms supporting carbon disclosure and retrofit planning for real estate investment trusts.
Software Management anchors current deployment scale; IoT Solutions demonstrates the steepest expansion trajectory as predictive intervention models displace scheduled maintenance regimes.
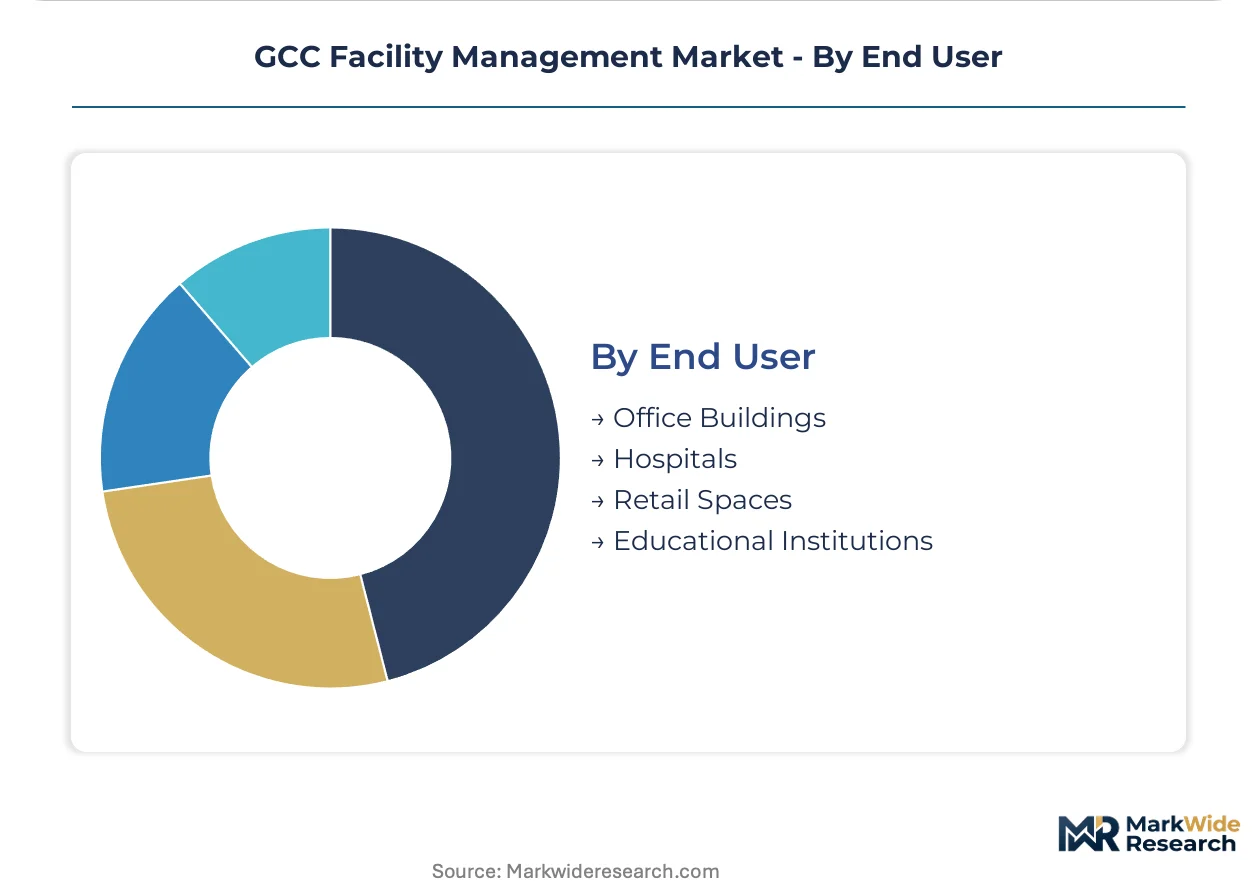
End User:
Asset criticality and regulatory inspection frequency segment service intensity and technology penetration rates.
- Hospitals:Clinical-grade FM combining infection control, medical gas maintenance, and 24/7 critical systems redundancy. Bahrain's healthcare privatization initiatives are creating specialized demand for operators with parallel ISO 55000 and clinical certification depth.
- Office Buildings:Commercial core assets in Dubai and Abu Dhabi where CAFM-legacy BMS integration friction creates upgrade revenue for technology-hybrid providers.
- Retail Spaces:High-traffic environments with compressed maintenance windows and brand-sensitive presentation standards.
- Educational Institutions:K-12 and university campuses subject to MOHAP indoor air quality and water efficiency monitoring mandates.
Hospitals command premium pricing tiers; Office Buildings represent the deepest installed base for technology-enabled service conversion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity in GCC facility management procurement varies sharply by project scale. Saudi giga-developments prioritize performance-guarantee contracting over unit-rate pricing, while smaller Bahraini healthcare facilities remain cost-elastic on soft services.
Saudi Arabia
NEOM, Red Sea Global, and Qiddiya developments drive decade-long integrated FM contracts bundling security, MEP maintenance, and IoT-enabled asset management. The Saudi Building Code imposes mandatory fire safety and water efficiency inspections that elevate compliance costs. Riyadh's commercial core and the Eastern Province industrial corridor concentrate demand for predictive maintenance platforms.
United Arab Emirates
Dubai's commercial tower stock and Abu Dhabi's healthcare expansion sustain multi-site portfolio agreements with centralized procurement. MOHAP mandates real-time monitoring submission to centralized compliance portals, automating deviation alerts. Dubai International Airport terminals pilot chip-scale IoT sensors with extended battery life for granular equipment monitoring.
Qatar
Lusail City and Msheireb Downtown Doha specifications require building automation protocol integration, opening contracts for FM-technology hybrid providers. The country's smart city mandates tie contract awards to verified interoperability with centralized urban management systems. Doha's sovereign wealth real estate arms pioneer performance-guarantee models transferring operational expenditure risk to operators.
Bahrain
Hospital outsourcing initiatives create demand for clinical-grade FM services combining infection control, medical gas maintenance, and 24/7 critical systems redundancy. The kingdom's healthcare privatization program lacks equivalent scale to Saudi or UAE developments, keeping procurement price-sensitive on non-critical services. Manama's medical district and planned healthcare clusters anchor specialized operator requirements.
Kuwait
Government building stock modernization and ministry decentralization programs sustain steady contract flow for integrated hard and soft services. The country's public sector procurement professionalizes under centralized tendering frameworks with escalating sustainability credential requirements. Kuwait City's administrative district and emerging commercial zones concentrate service demand.
GCC Facility Management Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the GCC facility management sector. Asset-heavy operators with captive workforce scale dominate integrated hard services in high-volume commercial cores, while technology-forward specialists capture premium margins on CAFM-enabled predictive maintenance contracts. Three archetypes define competitive positioning: fleet-scale integrated operators, platform-centric technology hybrids, and certification-depth sustainability specialists. Consolidation pressure intensifies as giga-project developers reduce vendor panels, while strategic partnerships between FM operators and IoT hardware providers accelerate.
Within the integrated services tier, Imdaad L.L.C. and Emrill Services LLC exemplify contrasting scale-versus-technology positioning. Farnek Services LLC occupies a sustainability-specialist niche competing for green-building contracts under environmental compliance mandates. These three entities anchor the competitive structure visible across UAE and Saudi procurement panels, with Qatar-based G4S Qatar SPC and Emcor Facilities Services WLL representing geographically concentrated alternatives in adjacent markets.
| Leading Market Players |
|---|
| G4S Qatar SPC |
| Emrill Services LLC |
| Emcor Facilities Services WLL |
| Farnek Services LLC |
| Imdaad L.L.C. |
| Sodexo Qatar Services |
| Cofely Besix Facility Management |
| Khidmah LLC |
| Al-Asmakh Facilities Management |
| Others |
Supply Flow & Price Mechanics
Chip-scale IoT sensor substitution for legacy building management hardware is redrawing procurement geography while compressing lifetime service margins across GCC facility management contracts. This component transition shifts supplier leverage toward East Asian electronics manufacturers and forces operators to restructure pricing around predictive analytics bundles rather than discrete maintenance events.
Pricing Analysis
After-market predictive maintenance subscriptions now anchor lifetime value extraction across integrated FM contracts. Three-tier pricing structure across premium, standard, and economy levels separates operators with CAFM-native platforms from labor-dependent subcontractors and uncertified local providers. Cost compression in the economy tier is intensifying because Saudi giga-project developers consolidate vendor panels around single-accountability performance guarantees. Government procurement offices demonstrate highest price sensitivity due to Saudization-mandated workforce cost inflation, while sovereign wealth real estate arms accept premium pricing for decade-long operational expenditure ceilings.
Supply Chain Analysis
Strait of Hormuz transit underwrites critical component flows for HVAC controllers, BMS hardware, and embedded sensor modules serving UAE and Saudi installations. Manufacturing concentrates in China, South Korea, and Taiwan for IoT chipsets, thermal imaging equipment, and building automation controllers. Raw material dependencies span rare earth elements for sensor magnets, copper for electrical infrastructure, and lithium for battery-backed embedded units. Single-source vulnerability runs through East Asian semiconductor foundries serving predictive maintenance platforms. Distribution runs through Dubai's Jebel Ali logistics hub for regional forwarding to Riyadh, Doha, and Manama project sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from technology-forward platform providers capable of unseating labor-scale operators through CAFM-native service delivery. Defense requires securing certification depth and captive technology development before regulatory mandates harden vendor qualification thresholds.
For Market Incumbents: Secure Estidama PQP and ISO 55000 credential stacking to defend integrated contract eligibility as MOHAP and Saudi Building Code enforcement intensifies. Acquire or develop in-house IoT sensor deployment capabilities to displace subcontractor coordination friction and capture predictive maintenance margin expansion. Vertical integration into chip-scale hardware partnerships reduces import dependency exposure.
For New Entrants and Emerging Players: Differentiate on clinical-grade FM specialization targeting Bahrain's hospital privatization pipeline and Saudi healthcare infrastructure expansion. White-space availability concentrates in medical gas maintenance certification and infection control protocol integration where incumbent capability gaps persist. Pursue technology-hybrid positioning through direct CAFM platform partnerships rather than labor-scale competition.
For Investors and Strategic Acquirers: Capital is best deployed toward mid-scale operators with existing government panel registration and latent technology integration capacity across the five-to-ten year viability window. Acquisition targets should demonstrate parallel hard services workforce scale and software management platform deployment. Monitor Saudi giga-project contract award velocity as inflection signal for integrated FM consolidation timing.
| Strategic Initiative | Industry Significance |
|---|---|
| CAFM Platform Integration | Direct API connectivity with MOHAP compliance portals automates deviation documentation for healthcare assets. |
| Predictive Maintenance Scale-Up | AI-driven failure prediction contracts displace scheduled maintenance regimes in Dubai airport terminals. |
| Green Certification Investment | Estidama Pearl Rating alignment unlocks giga-project procurement panels under UAE sustainability mandates. |
| Workforce Saudization Compliance | In-house technician training programs satisfy Saudi Building Code inspection credential requirements. |
| Technology Partnership Formation | IoT hardware alliances with East Asian manufacturers secure sensor supply for embedded deployment. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with FM contract directors at Saudi giga-project developers, UAE healthcare facility managers, Qatar sovereign wealth real estate procurement leads, and Bahrain hospital outsourcing coordinators. Secondary validation drew from MOHAP technical guideline releases, Saudi Building Code enforcement circulars, Estidama Pearl Rating system documentation, and customs records for HVAC and BMS equipment imports. Bottom-up contract value aggregation was cross-checked against top-down market sizing from regulatory filing patterns.
Across the projection horizon, the analytical framework modeled service type segmentation against client type intensity and technology penetration tiers. End-user criticality levels and regulatory inspection frequency shaped adoption curve assumptions. CAGRs were derived from contract award velocity tracking and workforce expansion patterns across Saudi Arabia and UAE commercial cores. Forecast inputs incorporated giga-project pipeline announcements and smart city mandate implementation schedules.
The analysis sits within stated boundaries; outcomes outside sustained Saudi infrastructure commitment and UAE green building enforcement continuity would require recalibration. Forecasts reflect documented assumptions regarding technician certification availability and import clearance efficiency. Practitioners should keep alternative scenarios live as geopolitical shipping disruptions and carbon disclosure requirement evolution reshape supply economics and contract structuring.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Facility Management
Australia Facility Management Market
Facility Management
Spain Facility Management Market
Facility Management
Global Unified Facility Management Market
Facility Management
Malaysia Facility Management Market
Facility Management
Middle East and Africa Soft Facility Management Market
Facility Management
Belgium Facility Management Market
Facility Management
Poland Facility Management Market
Facility Management
North America Hard Facility Management Market
Facility Management
Slovenia Facility Management Market
Facility Management
Taiwan Facility Management Services Market
Facility Management
Qatar Facility Management Market
Facility Management
Greece Facility Management Market
Facility Management
Singapore Facility Management Market
Facility Management
Italy Facility Management Services Market
Facility Management
Egypt Facility Management Market
Facility Management
Czech Republic Facility Management Market