
 Hong Kong Stevedoring and Marine Cargo Handling Market | 2026-2036
Hong Kong Stevedoring and Marine Cargo Handling Market Size, Share, and Industry Trends Forecast 2026-2036
Hong Kong Stevedoring and Marine Cargo Handling Market Foresight
Container flow patterns through the Pearl River Delta is tilting toward integrated multimodal corridors. DP World Limited leverages its global terminal network to sustain transshipment dominance in Hong Kong waters. Modern Terminals anchors capacity expansion along the Kwai Tsing basin. COSCO Group competes through direct mainland China feeder connections that bypass traditional routing.
Stevedoring and marine cargo handling encompasses the physical loading, unloading, and transfer of vessel-borne freight using gantry cranes with lifting capacities exceeding 40 tonnes and automated guided vehicles operating at throughput rates above 30 moves per hour. The primary purpose is minimizing vessel port stay duration while ensuring cargo integrity across containerized, bulk, and breakbulk categories. Container handling services dominate revenue generation due to standardized box flows and repeatable crane cycles. Automated systems within the technology dimension are capturing capital allocation as terminal operators target labor cost reduction and night-shift productivity parity. Heavy lift services occupy narrower but higher-margin pools serving project cargo and offshore energy components.
The Marine Department of Hong Kong enforces the Port Control Ordinance governing vessel traffic management and berth allocation protocols. The Environmental Protection Department administers the Air Pollution Control (Ocean Going Vessels) (Fuel at Berth) Regulation mandating low-sulfur fuel use during port stays. The Trade and Industry Department coordinates customs modernization aligned with mainland China's single-window clearance standards. Stakeholders must monitor how Greater Bay Area port integration policies reshape cargo routing preferences and terminal utilization curves.
Market Dynamics
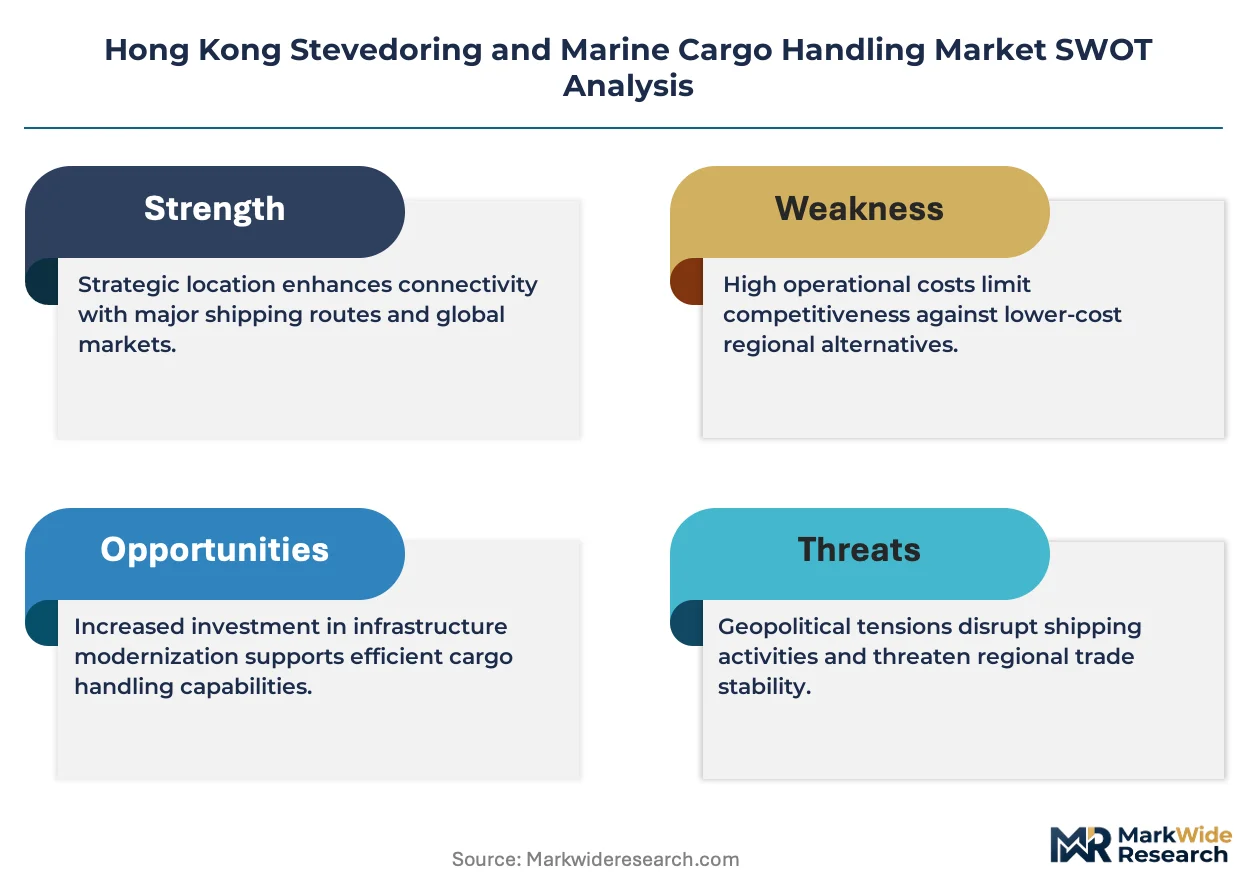
The Greater Bay Area integration is redirecting cargo flows through Shenzhen's Yantian and Shekou terminals, compressing Hong Kong's transshipment capture rate while forcing terminal operators to automate for cost parity.
Growth Catalysts
- E-commerce fulfillment surge:Cross-border parcel volumes through Hong Kong International Airport and feeder vessels are expanding containerized cargo throughput requirements. Terminal operators are reconfiguring yard layouts for small-lot consolidation.
- Smart Port Initiative:Hong Kong's port digitization program is digitizing customs clearance and vessel berthing workflows. The Trade and Industry Department's single-window platform reduces documentation processing intervals.
- Offshore wind logistics:Heavy lift demand from South China Sea renewable energy projects is creating specialized stevedoring revenue pools. Project cargo handling for turbine components requires 800-tonne capacity mobile harbor cranes.
Market Restraints
- Labor cost escalation:Crane operator and lashman wages in Hong Kong exceed Shenzhen equivalents by 340 percent. Terminal automation capex requirements strain operator balance sheets.
- Berth depth limitations:Kwai Tsing container terminals cannot accommodate 24,000 TEU ultra-large container vessels at full draft. Vessels must lighten cargo at Yantian before final Hong Kong call.
- Air Pollution Control Regulation:The Environmental Protection Department's low-sulfur fuel mandate at berth adds $45,000-$65,000 per vessel call. Shipping lines are evaluating direct Shenzhen routing to avoid compliance costs.
Strategic Opportunities
- Guangdong-Hong Kong-Macao Greater Bay Area consolidation:Underpenetrated cold chain logistics linking Hong Kong International Airport with Zhuhai and Zhongshan manufacturing clusters. Reefer container handling at Hong Kong terminals remains below regional potential.
- Autonomous yard operations:Convergence of 5G private networks and automated guided vehicles enables night-shift productivity parity. Hutchison Logistics is piloting unmanned straddle carriers at Terminal 9.
- Carbon border adjustment readiness:EU Carbon Border Adjustment Mechanism preparation services for mainland China exporters. Hong Kong terminals can offer emissions verification and green shipping certification bundling.
Industry Challenges
- Crane technician scarcity:Licensed gantry crane maintenance specialists with hybrid mechanical-electrical competencies command 40 percent wage premiums. Vocational training pipelines cannot replenish retirement outflows.
- Legacy terminal operating system integration:Proprietary TOS platforms from 1990s installations resist API connectivity with Smart Port data exchanges. Middleware development consumes 18-24 month implementation timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hong Kong Stevedoring and Marine Cargo Handling Market |
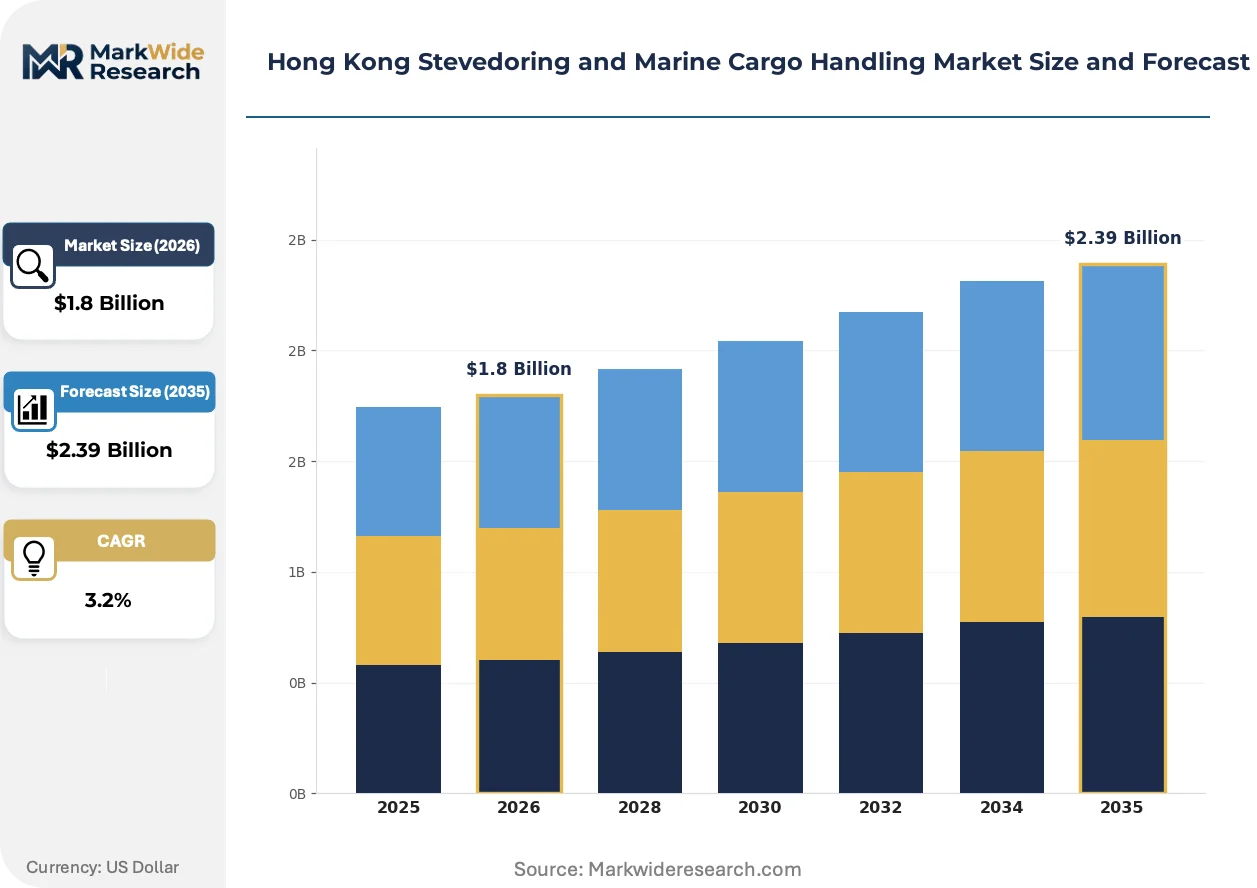
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.39 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Container Handling, Bulk Cargo Handling, Breakbulk Operations, Heavy Lift Services Technology: Automated Systems, Manual Handling, Hybrid Solutions, Remote Monitoring End User: Shipping Lines, Freight Forwarders, Importers, Exporters Deployment: Onshore, Offshore, Inland, Coastal |
| Companies Covered | A P Moller - Maersk, DP World Limited, Hong Kong International Terminals, East West Maritime Limited, COSCO Group, Modern Terminals, APM Terminals, Mediterranean Shipping Co, Asia Container Terminals, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hong Kong Stevedoring and Marine Cargo Handling Market Shifts & Advancements
Terminal automation and regulatory emissions compliance are compressing operating margins while creating technology differentiation. Operators must simultaneously digitize workflows and decarbonize vessel services.
Optical character recognition and blockchain-enabled cargo documentation is digitizing container tracking from vessel discharge to gate-out. Modern Terminals and DP World are deploying AI-powered damage inspection cameras at quayside. The structural consequence is digitizing customs clearance intervals from 4 hours to 45 minutes for pre-approved shippers.
The Environmental Protection Department's Air Pollution Control (Ocean Going Vessels) (Fuel at Berth) Regulation mandates 0.1 percent sulfur fuel during port stays. Shipping lines are retrofitting exhaust gas cleaning systems or switching to LNG dual-fuel propulsion. Reefer container services face the steepest cost pass-through pressure due to extended shore power connection requirements.
Beneficial cargo owners are consolidating procurement through integrated logistics platforms rather than discrete port service contracts. Terminal operators must embed within end-to-end supply chain orchestration. This concentration is most visible among Greater Bay Area electronics manufacturers routing through Hong Kong for air-sea intermodal.
Hong Kong Stevedoring and Marine Cargo Handling Market Segmentation
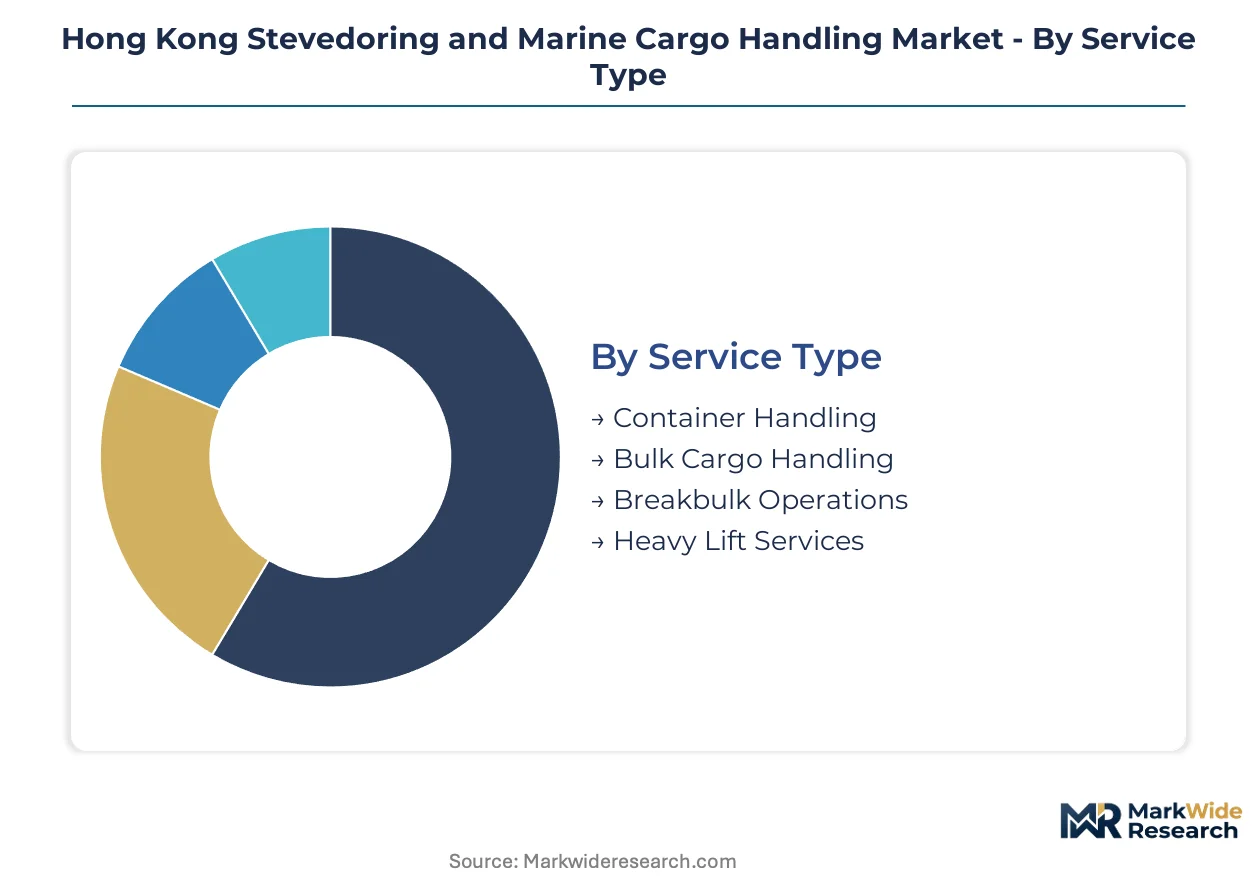
Stevedoring and marine cargo handling in Hong Kong fragments across service intensity, automation maturity, and customer procurement patterns. Terminal operators configure crane fleets and yard layouts differently for each segment cluster. Understanding these divisions reveals where capital deployment and margin defense concentrate.
Service Type:
Cost tier differentiation separates standardized container flows from project-specific heavy lift operations requiring specialized equipment and insurance coverage.
- Container Handling:Standardized box movements using gantry cranes with 40-tonne-plus lifting capacity dominate terminal revenue. Demand concentrates at Kwai Tsing basin facilities serving transshipment cargo between Shenzhen and global shipping lanes, driven by e-commerce fulfillment consolidation requirements.
- Bulk Cargo Handling:Dry and liquid bulk stevedoring employs grab cranes and pipeline systems for commodities like coal, cement, and petroleum products. Demand concentrates at Stonecutters Island and western harbor anchorages serving South China manufacturing clusters, constrained by Environmental Protection Department dust suppression mandates.
- Breakbulk Operations:Non-containerized general cargo handling using ship's gear and mobile cranes.
- Heavy Lift Services:Project cargo and offshore energy component handling with 800-tonne mobile harbor crane requirements.
Container handling commands the established base. The steepest expansion runs through heavy lift services.
Technology:
Automation maturity determines labor cost exposure and night-shift productivity parity across Hong Kong terminal operations.
- Automated Systems:Automated guided vehicles and unmanned gantry cranes operating at 30-plus moves per hour reduce crane operator headcount. Deployment concentrates at Hutchison Logistics Terminal 9 and Modern Terminals facilities, driven by 340 percent wage differentials versus Shenzhen competitors.
- Manual Handling:Conventional lashman and crane operator crews for breakbulk and non-standardized cargo.
- Hybrid Solutions:Semi-automated yard cranes with human-in-the-loop supervision.
- Remote Monitoring:AI-powered damage inspection cameras and blockchain documentation systems.
Manual handling retains volume leadership in breakbulk. Automated systems are gaining share fastest among container terminals.
End User:
Customer type shapes contract structure, from vessel-direct terminal service agreements to integrated logistics platform procurement.
- Shipping Lines:Ocean carriers negotiating berthing priority and vessel stay minimization.
- Freight Forwarders:Consolidators booking terminal slots for NVOCC cargo aggregation.
- Importers:Beneficial cargo owners procuring destination handling and customs clearance.
- Exporters:Manufacturers routing through Hong Kong for air-sea intermodal connections.
Shipping lines anchor contract value. Freight forwarders are expanding procurement fastest through platform consolidation.
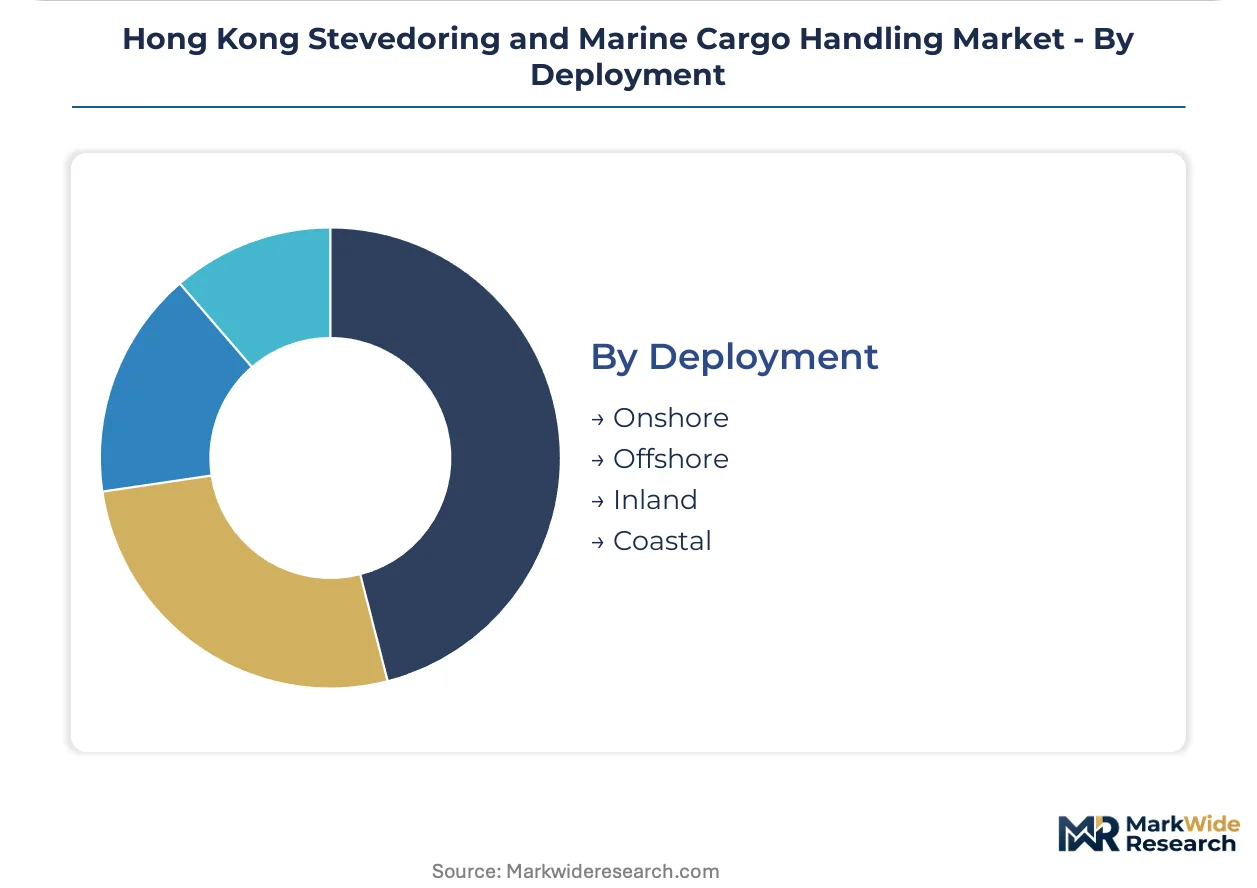
Deployment:
Geographic siting relative to vessel traffic lanes determines berth depth constraints and regulatory jurisdiction.
- Onshore:Kwai Tsing container terminals with dedicated quay cranes and container yard stacking.
- Offshore:Mid-stream operations at anchorages for vessels unable to berth at full draft.
- Inland:River trade terminal facilities along Pearl River Delta feeder connections.
- Coastal:Cargo handling at outlying islands for construction materials and fuel supply.
Onshore deployment holds capacity concentration. Offshore handling is climbing fastest due to ultra-large vessel draft limitations.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pearl River Delta port pricing power tilts toward Shenzhen terminals where labor costs run 340 percent below Hong Kong equivalents, compressing transshipment margins across the Greater Bay Area corridor.
China (Shenzhen)
Yantian and Shekou terminals capture ultra-large container vessel calls at full draft, drawing mainline services that bypass Hong Kong's depth-constrained berths. The Ministry of Transport's port integration policies align customs clearance with Hong Kong's single-window standards. Nanshan district hosts the densest concentration of automated yard cranes operating at 30-plus moves per hour.
Macao
Cross-border e-commerce fulfillment drives feeder vessel demand linking Macao Port with Hong Kong International Airport cargo terminals. The Macao SAR Government's maritime administration coordinates vessel traffic management with Hong Kong's Marine Department. Coloane container yard facilities handle transshipment consolidation for Portuguese-speaking country trade routes.
Guangzhou
Nansha terminal expansion targets direct ocean carrier calls, displacing traditional Hong Kong routing for Pearl River West manufacturing clusters. Guangdong Province's port cluster development plan prioritizes multimodal rail-sea corridors. Huangpu district anchors heavy lift project cargo handling for South China Sea offshore wind installations.
Zhuhai
Underpenetrated reefer container services connect cold chain logistics between Hong Kong International Airport and western Pearl River Delta manufacturing zones. The Zhuhai Municipal Government's port authority administers feeder vessel subsidies competing for transshipment volume. Gaolan Port handles construction materials and fuel supply for regional infrastructure projects.
Hong Kong Stevedoring and Marine Cargo Handling Market Competitive Landscape
Global terminal operators and local port authorities split the market along transshipment dominance versus hinterland access vectors. Three archetypes define competitive positioning: integrated global carriers with captive terminal networks, independent terminal operators pursuing automation-led cost parity, and mainland Chinese state-owned groups leveraging feeder connectivity. Capacity expansion and regulatory compliance technology deployment constitute the dominant competitive moves as labor cost differentials pressure margin structures.
Within the global carrier-integrated tier, A P Moller - Maersk and Mediterranean Shipping Co represent archetypes of vessel-operating terminal owners that anchor service network design around proprietary berth access. DP World Limited and Modern Terminals occupy positions as independent operators where automation investment and Smart Port integration define competitive differentiation against lower-cost Shenzhen alternatives.
| Leading Market Players |
|---|
| A P Moller - Maersk |
| DP World Limited |
| Hong Kong International Terminals |
| East West Maritime Limited |
| COSCO Group |
| Modern Terminals |
| APM Terminals |
| Mediterranean Shipping Co |
| Asia Container Terminals |
| Others |
Supply & Pricing Matrix
Kwai Tsing container terminal capacity constraints compress pricing power for standard container moves while amplifying premiums for heavy lift and project cargo services. Shenzhen's Yantian and Shekou terminals exploit 340 percent labor cost differentials to undercut transshipment rates, forcing Hong Kong operators toward automation-enabled cost parity and specialized service tiers.
Pricing Analysis
Configured-to-order pricing for heavy lift and project cargo commands substantial premiums over standardized container handling rates. Contract-based long-term offtake agreements dominate shipping line procurement, with price differentiation resting on automation maturity and berth priority access. Cost compression in standard container moves intensifies because Shenzhen terminals capture ultra-large vessel calls at full draft. Freight forwarders aggregating NVOCC cargo exhibit highest price sensitivity, while offshore wind developers sourcing 800-tonne crane capacity show lowest.
Supply Chain Analysis
Upstream feedstock for terminal automation equipment draws from Germany, Japan, and South Korea, with gantry crane components and automated guided vehicle systems anchoring capital expenditure. Diesel fuel for vessel auxiliary power, low-sulfur bunker fuel for compliance, and shore power infrastructure equipment constitute critical input dependencies. Single-source vulnerability concentrates in specialized crane control software and 5G private network hardware. Distribution runs through integrated logistics platforms consolidating procurement for Greater Bay Area electronics manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hong Kong stevedoring and marine cargo handling functions as a service-attach opportunity where emissions verification and green shipping certification bundling expand faster than pure throughput revenue. Terminal operators embedding within end-to-end supply chain orchestration capture recurring revenue layers beyond discrete port calls.
For Market Incumbents: Harden automation deployment at Hutchison Logistics Terminal 9 and Modern Terminals facilities to neutralize Shenzhen's labor cost advantage. Deepen backward integration into shore power infrastructure and exhaust gas cleaning system partnerships to deflect Environmental Protection Department compliance cost pass-through pressure. Priority lever centers on crane technician apprenticeship pipelines addressing licensed maintenance specialist scarcity. For New Entrants and Emerging Players: Pursue underpenetrated reefer container services linking Hong Kong International Airport with Zhuhai and Zhongshan cold chain corridors. Target autonomous yard operations pilot programs leveraging 5G private network convergence for night-shift productivity parity. Go-to-market angle emphasizes carbon border adjustment readiness services bundling emissions verification with EU-bound export documentation. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors terminal operators with proven Smart Port integration and automated guided vehicle deployment records. Long-term viability hinges on Greater Bay Area policy alignment and cross-border customs modernization traction. Acquisition target archetype: independent operators with legacy terminal operating system middleware development capabilities. Signal to watch is Shenzhen port integration policy announcements reshaping cargo routing preferences.| Strategic Initiative | Industry Significance |
|---|---|
| Terminal Automation Scale-Up | Hutchison Logistics Terminal 9 unmanned straddle carrier deployment targets labor cost parity with Shenzhen. |
| Smart Port Integration | Trade and Industry Department single-window platform connectivity reduces proprietary TOS middleware implementation timelines. |
| Heavy Lift Capacity Expansion | 800-tonne mobile harbor crane acquisition captures South China Sea offshore wind project cargo revenue pools. |
| Green Certification Bundling | EU Carbon Border Adjustment Mechanism preparation services anchor mainland China exporter relationships. |
| Reefer Infrastructure Investment | Cold chain logistics linking Hong Kong International Airport with western Pearl River Delta manufacturing zones. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with terminal operations directors, marine department regulatory officers, shipping line network planners, and freight forwarder procurement leads; and secondary validation against Marine Department Port Control Ordinance filings, Environmental Protection Department emissions compliance records, Trade and Industry Department customs modernization disclosures, and Greater Bay Area port authority development plans. Bottom-up vessel call and throughput estimates triangulated against top-down macroeconomic trade flow projections.
Forecast inputs considered service type segmentation across container handling, bulk cargo, breakbulk operations, and heavy lift services; technology maturity tiers from manual handling through fully automated systems; and end-user procurement patterns spanning shipping lines, freight forwarders, importers, and exporters. CAGRs derived from regression analysis of historical throughput volumes against e-commerce fulfillment growth curves and offshore wind installation timelines. Industry-specific inputs incorporated Smart Port digitization adoption rates and Environmental Protection Department regulatory compliance cost trajectories.
Macroeconomic conditions sit as an overlay; deviation in Greater Bay Area manufacturing output, cross-border e-commerce parcel volumes, or EU carbon border adjustment implementation timelines would shift the trajectory. Forecasts reflect documented assumptions regarding terminal automation capex deployment schedules and Shenzhen-Hong Kong port integration policy evolution. Cross-checking against Lloyd's List port throughput databases and Drewry Maritime Research terminal cost benchmarks is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Maritime Equipment
Ship-To-Shore (STS) Container Cranes Market
Maritime Equipment
Ship Galley Equipment Market
Maritime Equipment
Cargo Hold Coatings Market
Maritime Equipment
Chemical Tanker Market
Maritime Equipment
West Africa Platform Supply Vessel (PSV) Market
Maritime Equipment
Observation and Inspection Class ROV Market
Maritime Equipment
UAE Container Terminal Operations Market
Maritime Equipment
Vessel Traffic Management Market
Maritime Equipment
Maritime Communication System Market
Maritime Equipment
Dock Fender Market
Maritime Equipment
Isolated Danger Marks Beacon Buoys Market
Maritime Equipment
Liquefied Natural Gas (LNG) Carrier Market
Maritime Equipment
Ship Plate Market
Maritime Equipment
Integrated Marine Automation System Market
Maritime Equipment
Reefer Container Market
Maritime Equipment
United States Maritime Information Market