
 Ascorbyl Stearate Market | 2026-2036
Ascorbyl Stearate Market Size, Share, and Industry Trends Forecast 2026-2036
Ascorbyl Stearate Market Outlook
Multi-sourcing from specialty chemical suppliers is broadening as cosmetic formulators reduce reliance on single-feedstock vitamin C ester producers. DSM Nutritional Products AG leverages its integrated biotechnology platform to secure precursor supply chains for esterification outputs. Croda International Plc anchors its position through lipid chemistry expertise and sustained investment in emollient-active hybrids. Stepan Company competes on manufacturing scale across North American and European surfactant facilities.
Ascorbyl stearate is the esterification product of L-ascorbic acid and stearic acid, yielding a lipophilic vitamin C derivative with enhanced oxidative stability compared to free ascorbic acid, typically supplied at purity grades exceeding 95% for cosmetic and pharmaceutical applications. Its primary industrial purpose centers on antioxidant protection in oil-based formulations where water-soluble ascorbates demonstrate inadequate partitioning. Powder formats dominate current volume flows due to handling efficiency in compounding operations and extended shelf stability under ambient storage. Antioxidant applications within cosmetics command premium positioning as formulators replace conventional preservatives with multifunctional actives that satisfy clean-label procurement criteria.
REACH registration requirements in Europe, FDA cosmetic ingredient scrutiny under the Modernization of Cosmetics Regulation Act, and China's GB standards for cosmetic raw materials collectively elevate documentation burdens for cross-border suppliers. These frameworks accelerate demand for pre-validated, regulatory-compliant ascorbyl stearate grades that streamline downstream product registration. Stakeholders must monitor evolving preservative restriction schedules across major formulation markets to anticipate substitution-driven volume shifts.
Market Dynamics
Cosmetic formulators are pivoting toward lipid-soluble vitamin C derivatives as REACH-compliant alternatives to conventional preservatives, compressing substitution timelines across European and East Asian supply chains.
Growth Catalysts
- REACH compliance mandates:ECHA registration requirements for cosmetic raw materials are redirecting formulation chemistry toward pre-validated antioxidant alternatives that streamline downstream product registration.
- K-beauty functional active prioritization:South Korean domestic brands are concentrating procurement on ingredients with enhanced oxidative stability for stable emulsion formulations.
- Clean-label procurement criteria:Personal care manufacturers are replacing conventional preservatives with multifunctional actives that satisfy documentation burdens across FDA and GB standards jurisdictions.
Market Restraints
- L-ascorbic acid feedstock volatility:Esterification precursor costs fluctuate with agricultural commodity cycles, compressing margin predictability for specialty chemical producers.
- Single-feedstock producer concentration:Reliance on limited biotechnology platforms for precursor supply chains creates vulnerability in esterification output continuity.
- Water-soluble ascorbate substitution threat:Free ascorbic acid remains cost-competitive for aqueous formulations where partitioning requirements are less stringent.
Strategic Opportunities
- Pharmaceutical-grade certification expansion:Purity grades exceeding 95% for drug applications open adjacent revenue streams beyond cosmetic antioxidants.
- Emollient-active hybrid convergence:Lipid chemistry expertise enables dual-function ingredients that reduce formulation complexity for skin-care manufacturers.
- India personal care regulatory alignment:BIS and CDSCO cosmetic raw material standards are elevating documentation requirements that favor pre-validated import grades.
Industry Challenges
- Cross-border registration timeline compression:MFDS, FDA, and ECHA filing synchronization demands specialized regulatory affairs capacity that mid-tier suppliers struggle to staff.
- Legacy preservative system integration:Reformulating established oil-based products around ascorbyl stearate antioxidant protection requires extensive stability testing protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ascorbyl Stearate Market |
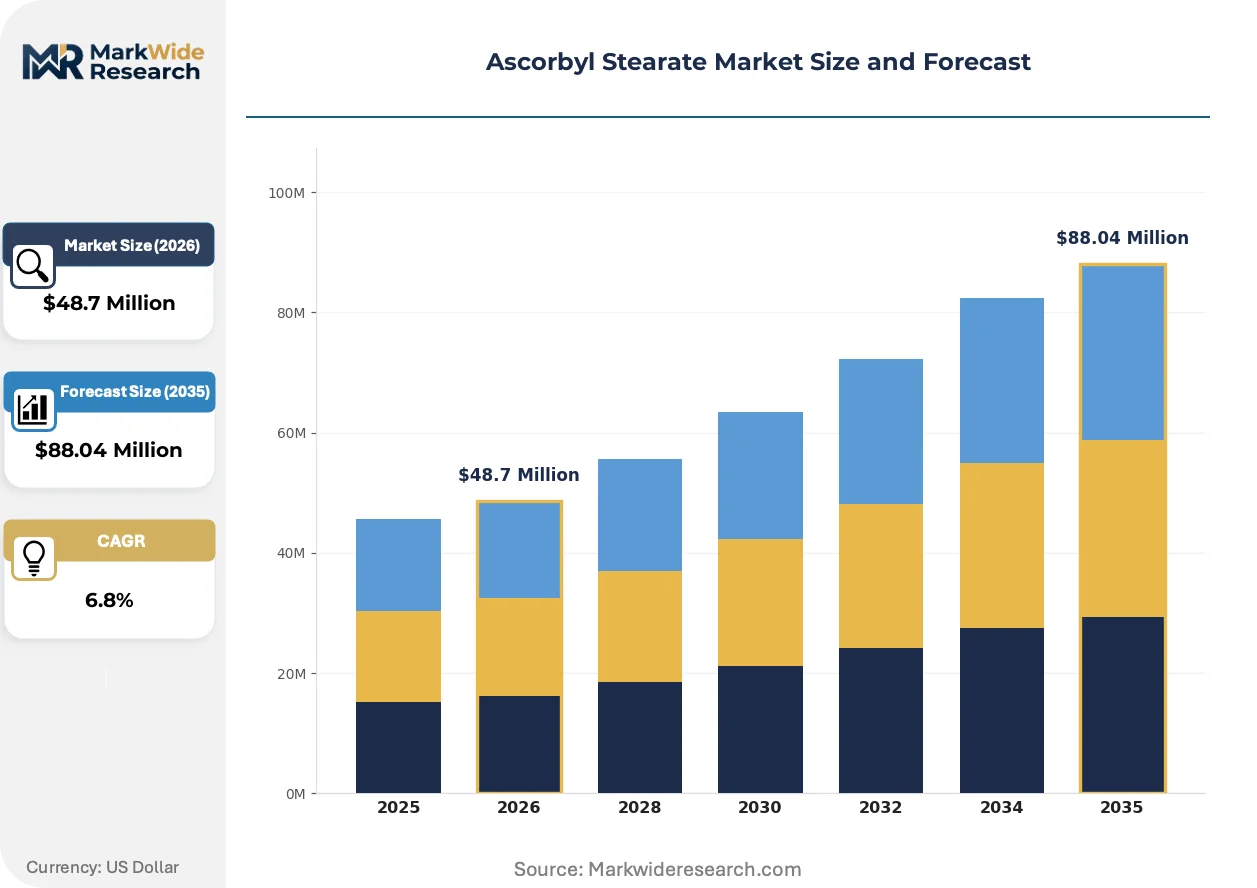
| Market Size in 2026 | $48.7 Million |
| Market Size in 2035 | $88.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Liquid, Paste End User: Cosmetics, Food & Beverage, Pharmaceuticals, Nutraceuticals Application: Emulsifier, Antioxidant, Thickening Agent, Preservative Distribution Channel: Online, Retail, Wholesalers, Direct Sales |
| Companies Covered | DSM Nutritional Products AG, BASF SE, Croda International Plc, Evonik Industries AG, Stepan Company, Ashland, Palsgaard A/S, Tate & Lyle PLC, DuPont de Nemours, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ascorbyl Stearate Market Strategic Shifts
Formulation chemistry is converging on multifunctional actives that satisfy simultaneous antioxidant, emollient, and regulatory compliance requirements, compressing single-purpose ingredient demand.
Encapsulation technologies for lipid-soluble vitamin C derivatives are rewriting stability performance benchmarks in cosmetic compounding. Premium skin-care manufacturers in South Korea and Japan are adopting powder-in-oil dispersion systems at accelerated procurement cycles. This technology is compressing traditional emulsion formulation timelines while extending finished-product shelf stability under ambient storage conditions.
REACH registration requirements in Europe are tightening documentation burdens for cross-border cosmetic raw material suppliers. ECHA pre-registration deadlines are forcing inventory reclassification and safety data sheet harmonization across formulation chemistry portfolios. Antioxidant applications within personal care command premium positioning as manufacturers prioritize regulatory-compliant grades that streamline downstream product registration.
Multi-sourcing strategies are displacing single-feedstock procurement relationships among cosmetic formulators. Specialty chemical distributors are consolidating purchasing across North American and Asian surfactant facilities to reduce concentration risk. This pattern is most visible in South Korea's K-beauty supply chain, where domestic brands are diversifying vendor bases for functional active ingredients.
Ascorbyl Stearate Market Segmentation
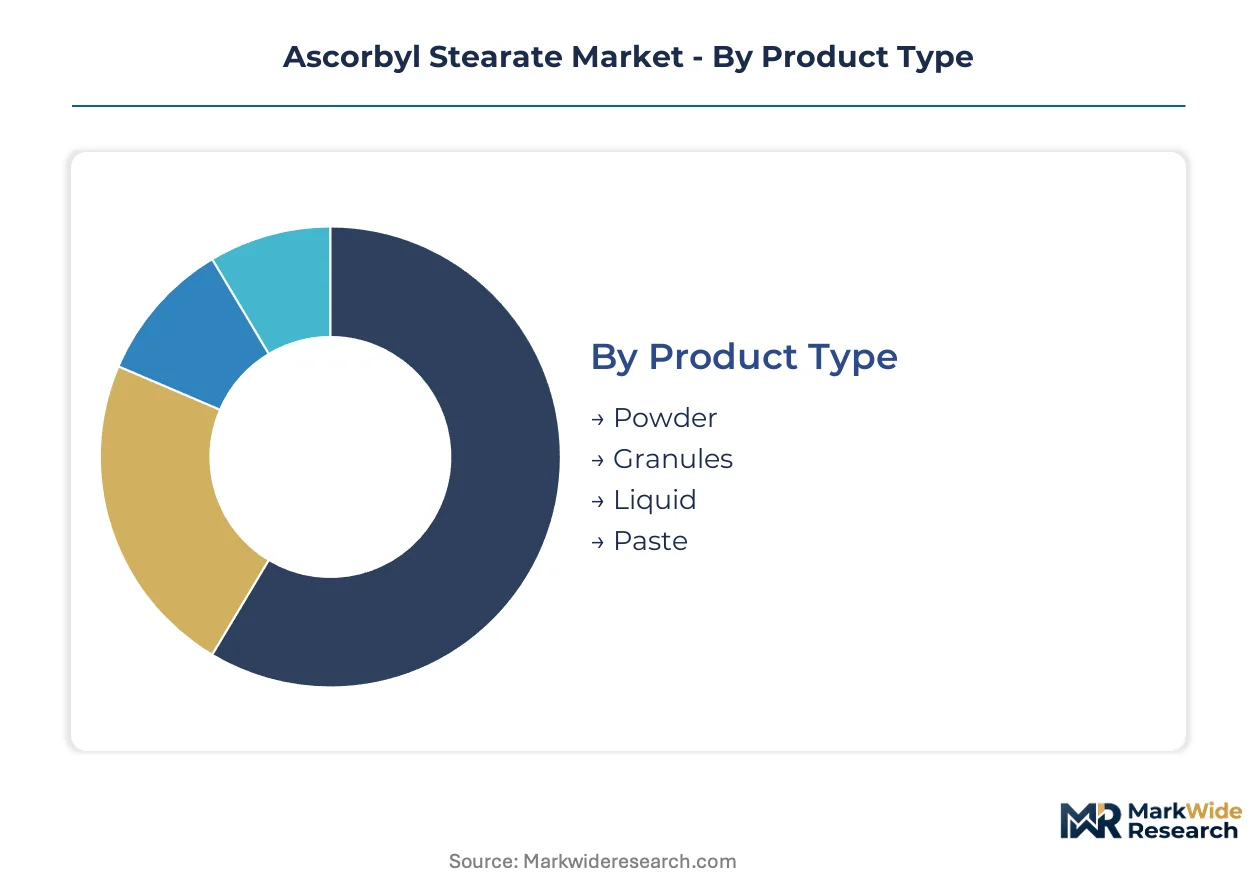
Ascorbyl stearate procurement patterns diverge sharply across physical formats and end-use specifications. Formulators prioritize oxidative stability grades for oil-based emulsions while food manufacturers emphasize thermal resistance for processing tolerance.
Product Type:
Cost tiers separate commodity handlers from precision compounders demanding flow-controlled specifications.
- Powder:Fine particulate format with 95%+ purity specification enables direct dispersion into anhydrous bases. Cosmetic manufacturers in South Korea specify powder grades for K-beauty emulsion stability requirements.
- Granules:Free-flowing agglomerated particles reduce dust exposure during high-volume food processing operations. Nutraceutical tablet producers favor this format for uniform blending with lipid carriers.
- Liquid:Pre-dissolved ester solutions eliminate dissolution steps for small-batch cosmetic formulators.
- Paste:Semi-solid concentrate suits specialized pharmaceutical ointment compounding with controlled rheology.
Powder leads volumes today; granules are gaining share fastest.
End User:
Application maturity determines margin capture and regulatory documentation intensity.
- Cosmetics:Antioxidant replacement for conventional preservatives in oil-based skin-care formulations. REACH-compliant grades command premium positioning as European formulators pivot from restricted biocides.
- Food & Beverage:Lipid-soluble vitamin C fortification for edible oils and fat-based products. Processors specify heat-stable ester grades that survive high-temperature manufacturing without degradation.
- Pharmaceuticals:Excipient and active ingredient applications requiring GMP certification and validated impurity profiles.
- Nutraceuticals:Dietary supplement formulations targeting enhanced bioavailability through lipophilic delivery systems.
Cosmetics anchors revenue concentration; nutraceuticals shows the steepest expansion trajectory.
Application:
Functional role dictates formulation compatibility and dosage precision requirements.
- Antioxidant:Primary function protecting oil-phase ingredients from rancidity and oxidative degradation. Clean-label positioning drives substitution of synthetic preservatives in European and East Asian personal care markets.
- Emulsifier:Surface-active properties stabilize water-in-oil dispersions for cosmetic cream architectures. Korean manufacturers specify emulsifier grades with defined HLB values for predictable formulation behavior.
- Thickening Agent:Viscosity modification in anhydrous systems through crystalline network formation.
- Preservative:Dual-function antimicrobial protection leveraging ascorbic acid release upon ester hydrolysis.
Antioxidant applications dominate current procurement; emulsifier demand is climbing the fastest.
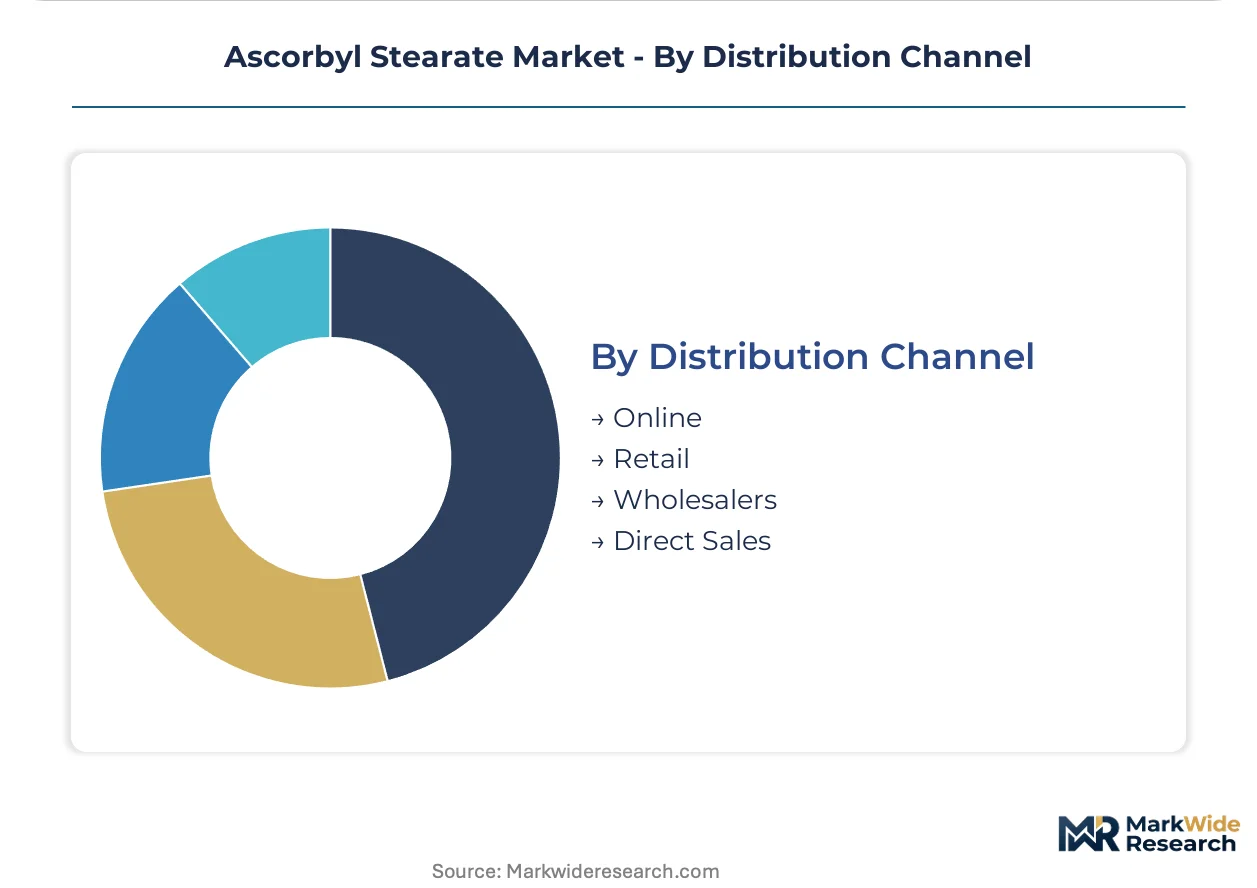
Distribution Channel:
Customer scale and technical service needs shape channel selection patterns.
- Direct Sales:Technical partnership model serving multinational cosmetic houses with customized specification development. DSM Nutritional Products and Croda International anchor relationships through dedicated account management for high-volume purchasers.
- Wholesalers:Consolidated purchasing for mid-tier formulators lacking direct supplier accreditation. Specialty chemical distributors buffer inventory across North American and Asian surfactant facilities.
- Online:Small-lot procurement for independent formulators and research laboratories requiring rapid sample access.
- Retail:Limited presence through specialty ingredient boutiques serving artisan cosmetic producers.
Direct sales captures the largest transaction values; online channels are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting ascorbyl stearate production toward jurisdictions with streamlined cosmetic raw material registration frameworks. Manufacturers are relocating esterification capacity to exploit compliance-cost differentials between REACH-heavy Europe and emerging markets with faster approval timelines.
South Korea
Domestic K-beauty brands concentrate procurement on lipid-soluble vitamin C derivatives with validated oxidative stability profiles. MFDS cosmetic ingredient documentation requirements favor pre-registered ascorbyl stearate grades that accelerate downstream product launches. Seoul Capital Area formulators are adopting powder-in-oil dispersion systems at compressed development cycles.
China
GB standards for cosmetic raw materials are elevating documentation burdens that favor import-grade ascorbyl stearate with established safety profiles. NMPA registration timelines for novel ingredients push formulators toward pre-validated ester derivatives. Yangtze River Delta cosmetic manufacturers are expanding procurement of REACH-compliant antioxidant alternatives.
United States
FDA scrutiny under the Modernization of Cosmetics Regulation Act is compressing substitution timelines for conventional preservatives in oil-based formulations. Personal care manufacturers prioritize multifunctional actives that satisfy clean-label procurement criteria. New Jersey and California formulation clusters are pivoting toward lipid-soluble vitamin C derivatives for stable emulsion architectures.
Germany
ECHA REACH registration requirements redirect formulation chemistry toward pre-validated antioxidant alternatives with harmonized safety data sheets. Specialty chemical producers leverage integrated biotechnology platforms to secure precursor supply chains for esterification outputs. North Rhine-Westphalia surfactant facilities anchor European manufacturing scale for cosmetic-grade ascorbyl stearate.
India
BIS and CDSCO cosmetic raw material standards are elevating documentation requirements that favor pre-validated import grades over unregistered domestic supply. Personal care manufacturers seek REACH-compliant ascorbyl stearate to streamline product registration. Maharashtra and Gujarat formulation hubs are diversifying vendor bases for functional active ingredients with enhanced stability specifications.
Ascorbyl Stearate Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and emollient-active hybrid convergence. The vendor base stratifies across integrated biotechnology platforms, lipid chemistry specialists, and surfactant-scale manufacturers. Three archetypes dominate: precursor-integrated biotech operators, emollient-chemistry hybrid developers, and multi-regional surfactant producers. Competitive moves center on backward integration into L-ascorbic acid supply chains and geographic expansion into India personal care regulatory alignment zones.
Within the integrated biotechnology tier, DSM Nutritional Products AG exemplifies precursor-secured esterification capacity. Croda International Plc occupies a position representing lipid chemistry expertise and emollient-active hybrid development. Stepan Company anchors the scale-driven segment with multi-regional surfactant manufacturing presence. These three entities collectively illustrate the competitive vectors shaping procurement relationships among cosmetic formulators reducing single-feedstock concentration risk.
| Leading Market Players |
|---|
| DSM Nutritional Products AG |
| BASF SE |
| Croda International Plc |
| Evonik Industries AG |
| Stepan Company |
| Ashland |
| Palsgaard A/S |
| Tate & Lyle PLC |
| DuPont de Nemours, Inc. |
| Others |
Value Chain & Pricing Dynamics
Encapsulation technology adoption in South Korean powder-in-oil dispersion systems is compressing formulation timelines while simultaneously concentrating procurement power among buyers with technical integration capabilities, reshaping both cost structures and supplier selection criteria across East Asian cosmetic chemical markets.
Pricing Analysis
Distributor margins for specialty chemical intermediates typically range 15-25% above direct-to-OEM contract rates. Pricing stratifies across pharmaceutical-grade, cosmetic-grade, and technical-grade tiers, with REACH-compliant documentation adding 8-12% premiums. Cost compression in standard cosmetic grades is intensifying because agricultural L-ascorbic acid feedstock volatility transmits directly to esterification outputs. Small-batch independent formulators exhibit highest price sensitivity, while multinational cosmetic houses with dedicated account management at DSM Nutritional Products and Croda International prioritize specification consistency over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale buyer demand from Seoul Capital Area K-beauty manufacturers and New Jersey formulation clusters. Production concentrates in Germany's North Rhine-Westphalia surfactant belt, China's Yangtze River Delta chemical parks, and India's Maharashtra-Gujarat industrial corridor. Raw material dependencies center on corn-derived L-ascorbic acid, palm and rapeseed stearic acid feedstocks, and catalytic esterification agents. Single-source vulnerability in biotechnology-platform precursor supply creates continuity risk for esterification output. Distribution runs through specialty chemical distributors consolidating inventory across North American and Asian facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in ascorbyl stearate derives from pharmaceutical-grade certification premiums and emollient-active hybrid convergence reducing formulation complexity for downstream skin-care manufacturers.
For Market Incumbents: Cement backward integration into L-ascorbic acid supply chains to buffer agricultural commodity cycle exposure. Expand GMP-certified capacity in India to capture BIS and CDSCO alignment-driven import substitution. Water-soluble ascorbate cost competition threatens standard cosmetic grade positioning; defend through emollient-active hybrid R&D investment. For New Entrants and Emerging Players: Specialty chemical distributors serving mid-tier formulators without direct supplier accreditation represent the most accessible channel entry point. Target nutraceutical tablet producers seeking granule format lipid carriers for uniform blending. Pursue pharmaceutical-grade certification as differentiation lever against established cosmetic-grade incumbents. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier surfactant manufacturers lacking biotechnology platform integration. Five-to-ten year viability favors precursor-integrated operators with REACH pre-registration completion. Monitor MFDS cosmetic ingredient documentation acceleration as inflection indicator for pre-validated grade demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive L-ascorbic acid production insulates margin from agricultural commodity volatility cycles. |
| Pharmaceutical-Grade Certification Expansion | GMP validation opens adjacent revenue streams beyond cosmetic antioxidant applications. |
| Emollient-Active Hybrid Development | Dual-function ingredients reduce formulation complexity for Korean skin-care manufacturers. |
| India Regulatory Alignment Investment | BIS and CDSCO pre-validation streamlines product registration for Maharashtra formulation hubs. |
| Encapsulation Technology Partnership | Powder-in-oil dispersion systems extend finished-product shelf stability under ambient storage. |
Study Parameters
Bottom-up cosmetic formulation modeling reconciled against top-down surfactant manufacturing tracking forms the analytical core of this study. Primary interviews with cosmetic R&D directors, procurement leads at K-beauty brands, specialty chemical distribution channel partners, and pharmaceutical excipient qualification managers combined with secondary validation from ECHA registration databases, FDA cosmetic ingredient filings, MFDS documentation repositories, and customs trade flow records. Top-down supply-side verification cross-checked against bottom-up demand aggregation from end-use segment procurement patterns.
Historical trendline analysis of esterification capacity expansion and antioxidant substitution timelines informed projection modeling across the forecast period. Segmentation dimensions modeled include physical format tier, end-use industry application, purity grade specification, and regional regulatory cluster. CAGRs derived from weighted average of capacity utilization trajectories and substitution elasticity coefficients for preservative replacement demand. Industry-specific forecast inputs incorporated REACH compliance deadline impacts and K-beauty functional active prioritization velocity.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to L-ascorbic acid feedstock price volatility and evolving preservative restriction schedules across major formulation markets. Projections reflect assumptions regarding sustained regulatory pressure toward antioxidant alternatives and stable emulsion technology adoption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Crosslinking Agents Market
Additives
Canada Water Enhancer Market
Additives
North America Potassium Nitrate Market
Additives
Lecithin and Phospholipids Market
Additives
Guanylic Acid Market
Additives
Ammonium Phosphatide Market
Additives
Performance Minerals Additives Market
Additives
Encapsulated Citric Acid Market
Additives
Global Peptone Market
Additives
Low Volatile Organic Compounds Coating Additives Market
Additives
Dry-Mix Mortar Additives and Chemicals Market
Additives
Green Polymer Additive Market
Additives
Fluid Loss Additives Market
Additives
Stabilizers Market
Additives
Tris Nonylphenyl Phosphite Market
Additives
Hydroxypropyl Distarch Phosphate Market