
 Texture Modifier Market | 2026-2036
Texture Modifier Market Size, Share, and Industry Trends Forecast 2026-2036
Texture Modifier Market Analytics
Modular ingredient bundles that pair thickeners with stabilizers in pre-blended systems is expanding choice for mid-sized food processors seeking formulation shortcuts. CP Kelco leverages its bacterial fermentation expertise to dominate marine-alternative gelling agents. ADM anchors North American supply through its soybean-derived lecithin and xanthan operations. Ingredion competes on clean-label starch modification, drawing reformulation contracts from major beverage brands.
Texture modifiers encompass hydrocolloids, starches, proteins, and emulsifiers that alter viscosity, mouthfeel, and structural integrity in finished goods, typically functioning at concentrations between 0.1% and 5% by weight. These additives serve primarily to standardize product consistency across variable raw material inputs and processing conditions. Stabilizers and thickeners lead volume demand as beverage and sauce manufacturers seek suspension and pour-control properties. Emulsifiers command premium positioning in cosmetics and pharmaceuticals where lamellar-phase stability determines shelf life. Powder formulations dominate industrial procurement for storage economy, though liquid dispersions are gaining traction in high-throughput dairy operations.
REACH in Europe mandates full toxicological dossiers for novel hydrocolloids, while the FDA GRAS notification pathway shapes U.S. market entry timelines for new microbial polysaccharides. The EU Green Deal pushes manufacturers toward bio-based feedstocks, directly influencing R&D allocation across the sector. Stakeholders must monitor evolving EFSA opinions on modified celluloses and align certification pipelines with divergent trans-Atlantic approval clocks.
Market Dynamics
Clean-label formulation mandates from the EU Green Deal are forcing texture modifier suppliers to abandon petrochemical-derived hydrocolloids and revalidate bio-based alternatives through EFSA toxicological pathways. This regulatory compression is restructuring R&D allocation and procurement specifications across European food processing.
Growth Catalysts
- EU Green Deal bio-based mandates:REACH compliance deadlines are accelerating reformulation timelines for bakery and dairy processors seeking marine-alternative gelling agents.
- Beverage suspension requirements:Clean-label starch modification is pulling adoption from major beverage brands seeking pour-control properties without synthetic additives.
- Germany ingredient cluster concentration:Hamburg and Frankfurt manufacturing hubs are standardizing pre-blended thickener-stabilizer systems for mid-sized food processors.
Market Restraints
- Guar gum price volatility:Indian monsoon dependency and speculative trading in Rajasthan commodity markets create input cost instability for hydrocolloid formulators.
- EFSA modified cellulose review uncertainty:Pending opinions on enzymatically treated celluloses are freezing new product launches across EU member states.
- Single-source fermentation capacity:Bacterial polysaccharide production concentrates in Danish and Dutch contract manufacturing organizations, creating supply concentration risk.
Strategic Opportunities
- India FSSAI clean-label recognition:Emerging domestic processed food sector is adopting international texture modifier standards ahead of regulatory harmonization.
- Cosmetic lamellar-phase emulsifiers:Pharmaceutical-grade mouthfeel systems are migrating into premium skincare formulations through K-beauty formulation houses.
- Liquid dispersion dairy adoption:High-throughput processing lines in Wisconsin and California are displacing powder procurement with pump-ready hydrocolloid slurries.
Industry Challenges
- Fermentation scale-up bioprocess engineering:Microbial polysaccharide producers face talent scarcity in downstream processing and sterile manufacturing operations.
- GRAS notification timeline variability:FDA pathway unpredictability for novel hydrocolloids is compressing capital planning horizons for US market entry strategies.
- Legacy starch modification equipment retrofit:Clean-label enzymatic processing requires reconfiguration of acid-thinning infrastructure still dominant in Midwest grain processing facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Texture Modifier Market |
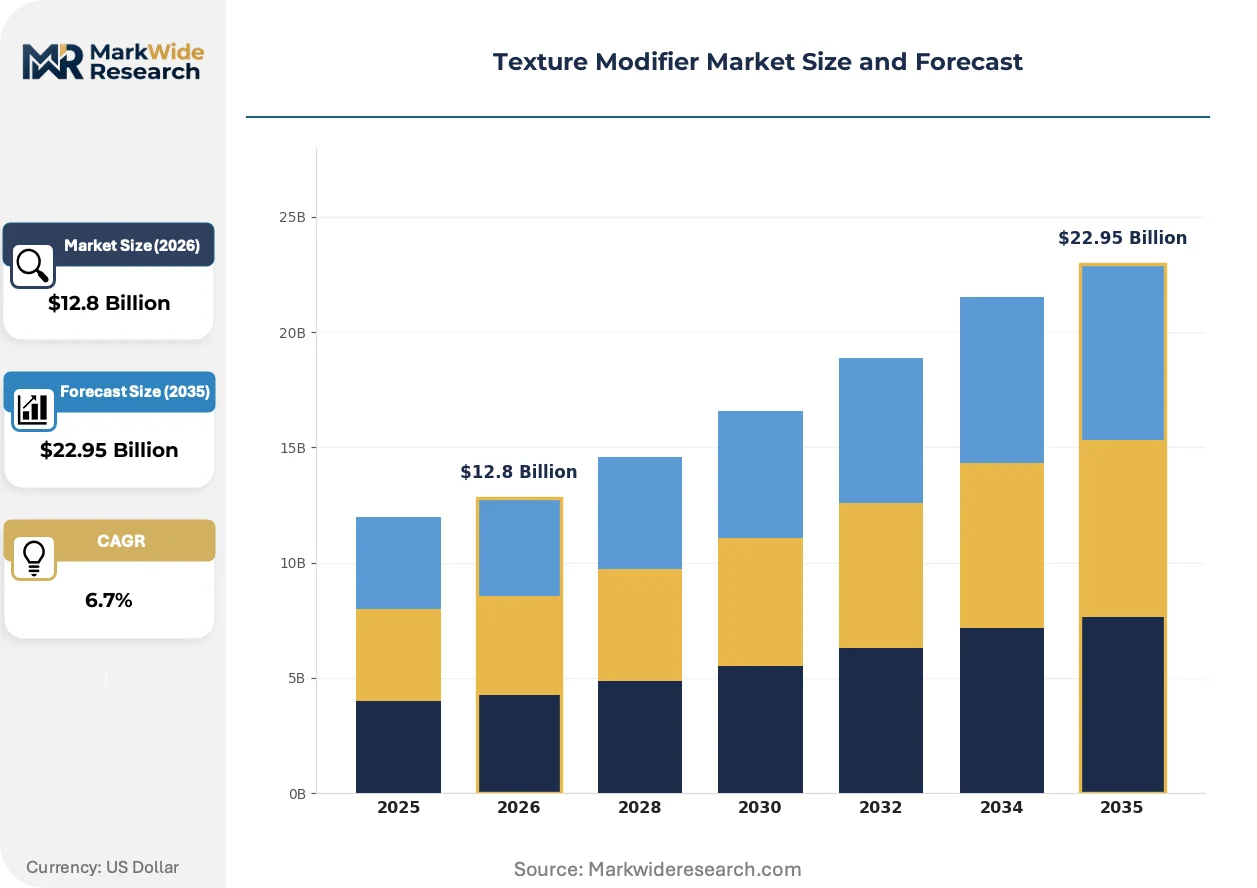
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $22.95 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stabilizers, Emulsifiers, Gels, Thickeners End Use Industry: Food & Beverage, Cosmetics, Pharmaceuticals, Personal Care Formulation Type: Liquid, Powder, Granule, Paste Sales Channel: Direct Sales, Distributors, Online Retail, Retail Stores |
| Companies Covered | CP Kelco, ADM, Ingredion, Tate & Lyle, Kerry Group, Cargill, DuPont, DSM, IFF, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Texture Modifier Market Evolving Landscape
Texture modifier supply is fragmenting into application-specific pre-blended systems that compress formulation cycles for mid-tier processors lacking in-house hydrocolloid expertise. This functional bundling is redrawing competitive boundaries between ingredient specialists and full-service solution providers.
Enzymatic starch modification is modularizing clean-label thickening solutions by enabling precise molecular weight control without chemical residue concerns. Major beverage brands are specifying these systems for suspension stability in plant-based milks. The technology is compressing traditional acid-thinning capacity investments and shifting procurement toward toll-manufactured enzyme-treated starches.
REACH authorization requirements for novel hydrocolloids are tightening toxicological dossier standards across EU member states. Full substance registration timelines now extend 18-24 months for microbial polysaccharides, forcing suppliers to front-load safety data generation. Modified cellulose producers are responding by accelerating EFSA opinion submissions ahead of anticipated restriction scenarios.
Specification-driven procurement is consolidating buyer power among multinational food processors who unbundle formulation services from ingredient supply. Mid-sized dairy operations in the Upper Midwest are shifting from spot-market hydrocolloid purchasing to annual framework agreements with technical support embedded. This contractual compression is squeezing regional distributors and favoring direct manufacturer relationships with documented application laboratories.
Texture Modifier Market Segmentation
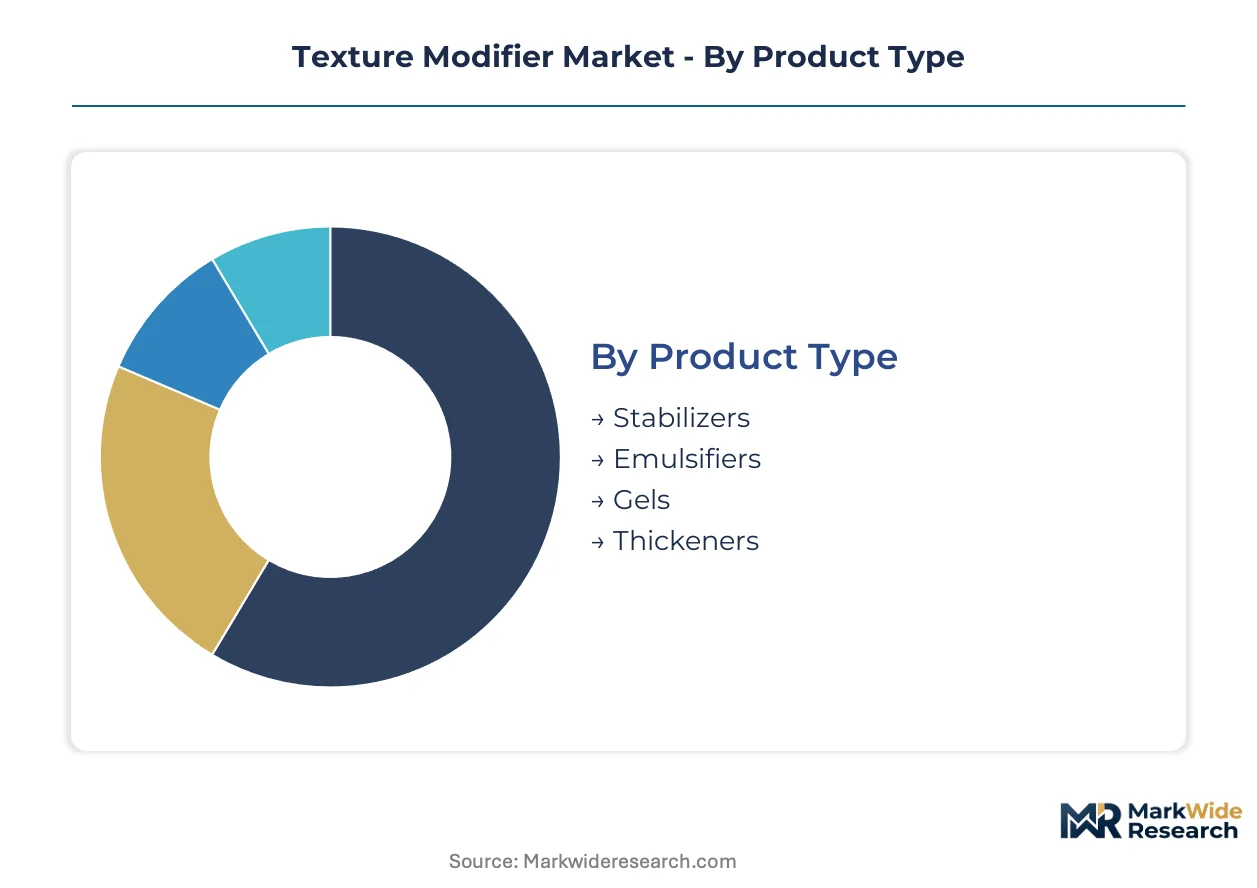
Texture modifier procurement diverges sharply by application environment and processing constraints. Formulators select product types based on shear tolerance requirements, while end-use industries dictate regulatory compliance burdens and shelf-life specifications.
Product Type:
Cost tier determines procurement volume and margin structure across hydrocolloid categories, with standard-grade thickeners commanding commodity-scale contracts versus premium emulsifiers priced on functional performance guarantees.
- Stabilizers:Hydrocolloid blends including xanthan, guar, and locust bean gum that maintain suspension and prevent phase separation in finished goods. Beverage manufacturers in Germany specify these for plant-based milk consistency standardization under EU Green Deal bio-based mandates.
- Emulsifiers:Surface-active agents such as lecithin, mono- and diglycerides, and polysorbates that reduce interfacial tension between immiscible phases. Cosmetics formulators in Hamburg pay premium positioning for lamellar-phase stability in premium skincare, migrating pharmaceutical-grade specifications into K-beauty channels.
- Gels:Three-dimensional network structures formed from agar, carrageenan, or pectin that provide solid-like mechanical properties at low concentrations. Marine-alternative variants from bacterial fermentation gain traction as CP Kelco dominates supply.
- Thickeners:Viscosity-building agents primarily starches and cellulosics that modify flow behavior without gelation. Clean-label enzymatic modification is displacing acid-thinning infrastructure in Midwest grain processing.
Thickeners lead on scale; emulsifiers lead on momentum.
End Use Industry:
Application-specific performance requirements reshape formulation priorities, with food processors prioritizing cost-per-unit functionality while pharmaceutical buyers demand batch-to-batch analytical reproducibility.
- Food & Beverage:Largest volume destination encompassing bakery, dairy, sauces, and beverages where texture modifiers standardize mouthfeel across variable raw material inputs. Clean-label starch modification pulls adoption from major beverage brands seeking pour-control without synthetic additives.
- Cosmetics:Premium positioning sector where lamellar-phase emulsifiers determine shelf-life stability in skincare and color cosmetics. K-beauty formulation houses drive specification migration from pharmaceutical-grade systems.
- Pharmaceuticals:Highest regulatory burden segment requiring full toxicological dossiers under EMA and FDA pathways. Modified cellulose producers accelerate EFSA opinion submissions ahead of anticipated restriction scenarios.
- Personal Care:Intermediate tier spanning hair care, oral care, and hygiene products where cost-performance optimization dominates procurement. Powder formulations prevail for storage economy in mass-market manufacturing.
Food & Beverage leads on scale; Cosmetics leads on momentum.
Formulation Type:
Customer processing infrastructure dictates physical form selection, with high-throughput liquid handling systems displacing traditional powder handling in continuous manufacturing environments.
- Liquid:Pre-hydrated hydrocolloid dispersions or emulsion concentrates that eliminate dust handling and hydration time in production. High-throughput dairy operations in Wisconsin and California are displacing powder procurement with pump-ready slurries.
- Powder:Dried, milled, or spray-dried forms offering storage economy and extended shelf stability. Dominates industrial procurement for bakery and dry-mix applications where on-site hydration is standard practice.
- Granule:Intermediate particle size formulations balancing dispersibility with reduced dust generation. Favored in mid-sized food processing where pneumatic conveying systems lack fine powder handling capability.
- Paste:High-solids semi-solid preparations for specialized applications requiring precise dosing without dust exposure. Limited to pharmaceutical compounding and artisan food production.
Powder leads on scale; Liquid leads on momentum.
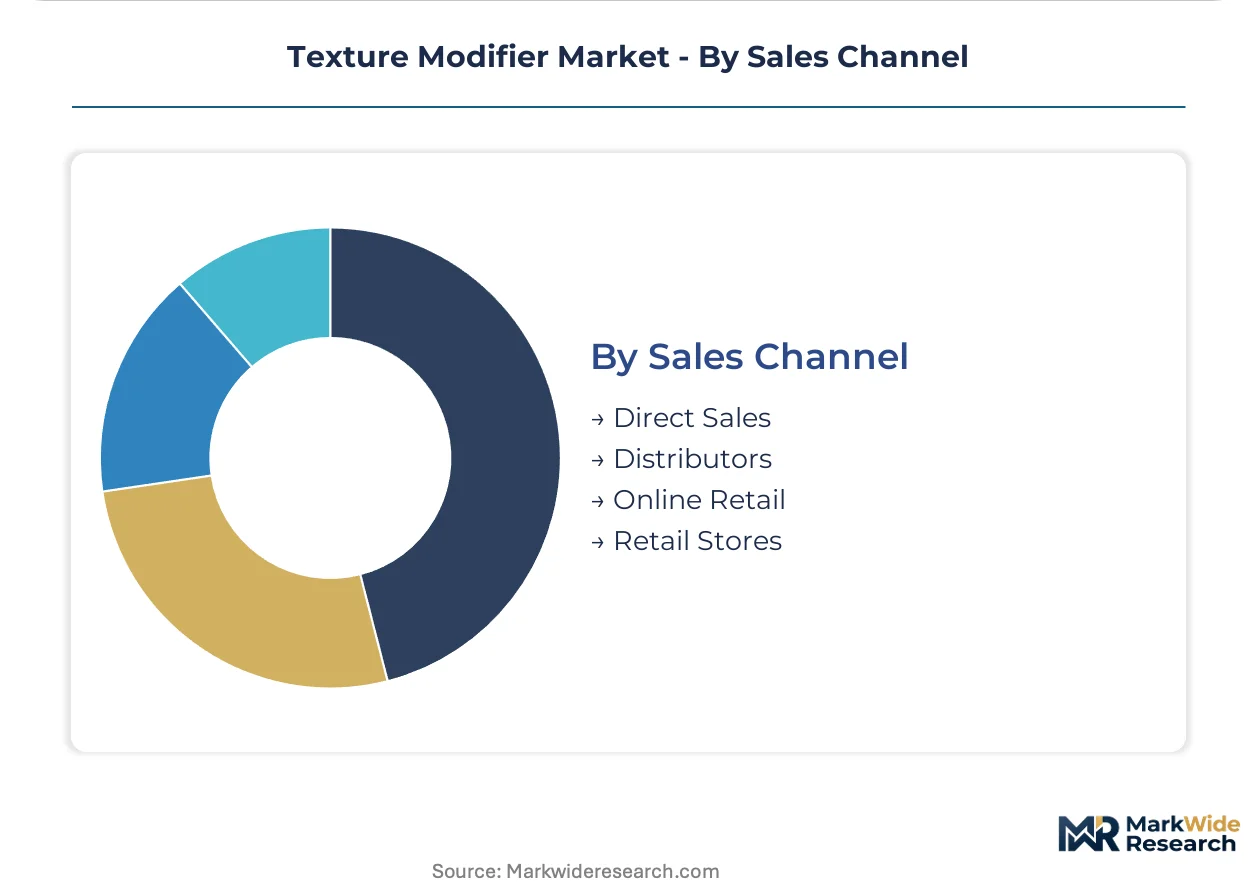
Sales Channel:
Procurement scale and technical support requirements determine channel selection, with multinational processors unbundling formulation services from ingredient supply while regional buyers rely on distributor inventory buffers.
- Direct Sales:Manufacturer-to-processor relationships with embedded technical service and application laboratory support. Mid-sized dairy operations in the Upper Midwest shift from spot-market purchasing to annual framework agreements.
- Distributors:Inventory-holding intermediaries providing regional availability and credit terms for smaller volume buyers. Regional distributors face margin compression as specification-driven procurement consolidates buyer power.
- Online Retail:Digital platforms serving artisan producers, research laboratories, and pilot-scale operations requiring small pack sizes. Growing traction in cosmetic formulation startups lacking established supplier relationships.
- Retail Stores:Point-of-sale availability for hobbyist and very small-scale food producers. Negligible commercial significance in industrial texture modifier procurement.
Direct Sales leads on scale; Online Retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial hydrocolloid production first achieved commercial scale in the United States during the 1950s, with bacterial fermentation platforms developed for food-grade polysaccharides. European regulators subsequently established the framework for bio-based ingredient validation that now governs cross-border trade.
United States
Beverage suspension requirements and clean-label starch modification pull procurement from major brands in Wisconsin and California dairy corridors. FDA GRAS notification timelines compress capital planning for novel microbial polysaccharides entering domestic formulation. Midwest grain processing clusters around Illinois and Iowa retrofit acid-thinning infrastructure for enzymatic clean-label systems.
Germany
EU Green Deal bio-based mandates accelerate reformulation timelines for Hamburg and Frankfurt ingredient manufacturers clustering around bacterial fermentation capacity. REACH compliance deadlines force toxicological dossier front-loading for hydrocolloid suppliers serving bakery and dairy processors. Standardized pre-blended thickener-stabilizer systems emerge from Rhine-Ruhr chemical engineering networks.
India
Guar gum price volatility from Rajasthan commodity markets destabilizes hydrocolloid input costs for domestic formulators. FSSAI clean-label recognition ahead of regulatory harmonization pulls international texture modifier standards into emerging processed food sectors. Maharashtra and Gujarat processing hubs adopt enzymatic starch modification for beverage and sauce applications.
China
Dual carbon goals push manufacturers toward bio-based feedstock validation for hydrocolloid production serving domestic dairy expansion. SAMR registration pathways for novel food additives extend approval timelines for microbial polysaccharide imports. Yangtze River Delta ingredient clusters concentrate toll-manufacturing capacity for enzyme-treated starches.
Netherlands
Single-source fermentation capacity concentrates bacterial polysaccharide production in Dutch contract manufacturing organizations serving EU-wide demand. EFSA modified cellulose review uncertainty freezes new product launches pending toxicological opinions. Rotterdam logistics hubs coordinate marine-alternative gelling agent distribution across North Sea processing corridors.
Texture Modifier Market Competitive Landscape
The competitive structure tilts toward fermentation-specialist incumbents with captive bacterial polysaccharide platforms. Tier-one ingredient conglomerates anchor North American and European supply through backward integration into soybean and grain processing feedstocks. Mid-sized solution providers compete on pre-blended formulation bundles that compress technical service cycles for processors lacking in-house hydrocolloid expertise. Dominant competitive moves include capacity expansion in bacterial fermentation and strategic partnerships between enzyme technology licensors and starch processors.
Among North American ingredient conglomerates, Cargill and ADM exemplify scale-driven archetypes with upstream control over oilseed and grain-derived feedstocks. CP Kelco occupies a specialist position representing bacterial fermentation expertise applied to marine-alternative gelling agents. Ingredion sits within the clean-label modification tier, anchoring enzymatic starch processing capabilities for beverage reformulation contracts.
| Leading Market Players |
|---|
| CP Kelco |
| ADM |
| Ingredion |
| Tate & Lyle |
| Kerry Group |
| Cargill |
| DuPont |
| DSM |
| IFF |
| Others |
Value Network & Pricing Analysis
Rajasthan guar gum commodity benchmarks cascade through hydrocolloid supply chains into three-tier pricing structures across premium pharmaceutical-grade, standard food-grade, and economy industrial-grade levels. Indian monsoon variability and speculative trading in desert-state commodity markets transmit cost volatility directly into European formulator procurement contracts.
Pricing Analysis
Contract-based long-term offtake with embedded technical service dominates procurement between multinational food processors and bacterial fermentation specialists. Price differentiation separates REACH-registered hydrocolloids with full EFSA dossiers from standard-grade alternatives lacking regulatory pre-validation. Cost compression in standard-grade thickeners is intensifying because Indian guar supply volatility and Midwest enzymatic starch processing retrofits squeeze margin structures. Mid-sized dairy operations in Wisconsin demonstrate highest price sensitivity through spot-market purchasing behavior, while pharmaceutical-grade emulsifier buyers in Hamburg exhibit lowest sensitivity due to lamellar-phase stability requirements.
Supply Chain Analysis
EU Green Deal domestic-content mandates and REACH authorization requirements are reshaping sourcing patterns toward bio-based feedstock validation within member-state borders. Bacterial polysaccharide production concentrates in Denmark, the Netherlands, and Germany, while enzymatic starch modification capacity clusters in Illinois and Iowa. Raw material dependencies draw from Indian guar gum harvests, Brazilian soybean lecithin crush, and marine biomass harvesting in Southeast Asian waters. Single-source fermentation vulnerability in Dutch contract manufacturing organizations creates supply concentration risk. Distribution runs through Rotterdam logistics hubs coordinating marine-alternative gelling agent allocation across North Sea processing corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU REACH compliance costs and FDA GRAS notification timelines create a geographic-arbitrage window favoring early investment in Indian FSSAI-aligned production ahead of regulatory harmonization. The cost differential between European toxicological dossier requirements and Indian domestic-content recognition offers margin capture potential for bio-based hydrocolloid manufacturing.
For Market Incumbents: Extend bacterial fermentation capacity in Danish and Dutch manufacturing clusters to defend against emerging Indian enzymatic starch specialists capturing FSSAI clean-label contracts. Deepen backward integration into Brazilian soybean lecithin supply and marine biomass sourcing to insulate margin structures from Rajasthan commodity volatility. Prioritize EFSA opinion acceleration for modified celluloses ahead of anticipated restriction scenarios.
For New Entrants and Emerging Players: The premium-economy price-point gap in cosmetic lamellar-phase emulsifiers offers white-space entry through K-beauty formulation house partnerships migrating pharmaceutical-grade specifications. Target liquid dispersion dairy adoption in Wisconsin and California high-throughput processing corridors where pump-ready hydrocolloid slurries displace legacy powder procurement. Pursue toll-manufacturing arrangements with Yangtze River Delta enzyme technology licensors to bypass capital-intensive fermentation scale-up barriers.
For Investors and Strategic Acquirers: Asymmetric upside sits with enzymatic starch modification specialists possessing clean-label enzymatic processing capabilities and established beverage brand reformulation contracts. Long-term viability over the projection horizon favors acquisition targets with dual EU-US regulatory pathway expertise and captive bacterial polysaccharide platforms. Watch EFSA modified cellulose opinion releases as inflection indicators for portfolio reallocation between traditional hydrocolloids and marine-alternative gelling agents.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Bacterial fermentation scale-up in Danish manufacturing clusters addresses EU Green Deal bio-based mandates. |
| Backward Integration | Upstream control over Brazilian soybean crush and Indian guar gum sourcing stabilizes input cost volatility. |
| Long-term Supply Agreement | Annual framework contracts with embedded technical service capture mid-sized dairy procurement shifts in Wisconsin. |
| Joint Venture | Partnerships between enzyme technology licensors and Midwest grain processors accelerate clean-label starch modification deployment. |
| Geographic Expansion | India FSSAI-aligned production ahead of regulatory harmonization captures emerging processed food sector demand. |
Research Methodology
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combined with secondary validation. Primary interviews engaged ingredient procurement managers at multinational food processors, bacterial fermentation plant engineers, enzymatic starch modification R&D directors, and hydrocolloid distribution channel partners. Secondary sources included customs and trade flow databases, EFSA opinion registers, FDA GRAS notification filings, and SEC 10-K disclosures from publicly traded ingredient conglomerates. Bottom-up volume modeling triangulated against top-down market sizing across product type, end-use industry, and formulation dimensions.
Segmentation granularity modeled product type at the hydrocolloid category level, end-use industry at application-specific resolution, formulation type by physical state, and regional production hub by country-cluster. CAGRs derived from historical trajectory analysis adjusted for regulatory pathway timelines and raw material cost cycle positioning. Industry-specific forecast inputs incorporated EU Green Deal implementation schedules, EFSA modified cellulose review progressions, and Indian FSSAI harmonization milestones.
Caveats apply where EFSA regulatory opinion delays, Indian monsoon failure patterns, or fermentation capacity bottlenecks could materially shift the outlook. Forecasts reflect assumptions on bio-based feedstock substitution rates and clean-label reformulation adoption curves. A small set of named triggers—EFSA modified cellulose restrictions, REACH authorization expansions, and FSSAI international standard recognition—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Lubricating Oil Additives Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Cetane Improver Additives Market
Additives
China Sodium Reduction Ingredient Market
Additives
Global UV Absorbers Market
Additives
Antiknock Agents Market
Additives
Global Caprylhydroxamic Acid Market
Additives
Isobutyl Acetate Market
Additives
Hydroxyethyl Cellulose Market
Additives
Sodium Citrate Anhydrous Market
Additives
Global Feed Acidulants Market
Additives
Coating Additives Market
Additives
Global Asphalt Additives Market
Additives
Zinc Dialkyldithiophosphates Additive Market
Additives
Biosaccharide Gum Market