
 Natural Chelating Agents Market | 2026-2036
Natural Chelating Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Chelating Agents Market Analysis
European biorefinery expansion is rebalancing feedstock availability for natural chelating agent producers. BASF SE leverages its Ludwigshafen integrated complex to sustain captive citric acid supply chains. Clariant competes through specialty tartaric acid derivatives aimed at high-purity pharmaceutical grades. Jungbunzlauer Suisse AG anchors Swiss fermentation expertise to dominate food-grade lactic acid chelates across Continental Europe.
Natural chelating agents are biobased organic compounds—primarily hydroxycarboxylic acids such as citric, tartaric, lactic, and malic acid—that form stable soluble complexes with metal ions through multidentate coordination bonds, typically at pH ranges between 3 and 11. These compounds sequester calcium, magnesium, iron, and heavy metals to prevent precipitation, oxidation, or catalytic degradation in industrial and consumer formulations. Citric acid holds the largest volume share among product types due to its cost-efficient fermentation production and broad regulatory acceptance, while lactic acid chelates represent the fastest-expanding margin pool as personal care brands reformulate around biobased credentials. Powder and granular forms command premium positioning in agricultural micronutrient delivery, whereas liquid formulations dominate food and beverage processing lines where dosing precision matters.
The EU Green Deal and REACH restrictions on persistent phosphonate chelators are forcing reformulation across European industrial cleaning and water treatment sectors. ECHA hazard classifications for EDTA derivatives are redirecting procurement budgets toward biodegradable alternatives certified under OECD 301B ready biodegradability protocols. Stakeholders must monitor regulatory divergence between EU member state enforcement practices and anticipate which national regulators will accelerate compliance deadlines for chelating agent substitution in cooling tower and boiler applications.
Market Dynamics
REACH restrictions on synthetic phosphonates and EDTA derivatives are forcing immediate substitution cycles across European industrial cleaning and water treatment sectors, compressing reformulation timelines from years to months.
Growth Catalysts
- EU Green Deal enforcement:Binding biodegradability mandates under OECD 301B protocols are redirecting procurement budgets toward plant-derived alternatives in cooling tower applications.
- Personal care reformulation:Cosmetic brands are eliminating petroleum-derived chelators from rinse-off products ahead of ECHA hazard reclassifications.
- Fermentation capacity expansion:Biorefinery investments in the Netherlands and Germany are securing captive feedstock supply for citric and lactic acid producers.
Market Restraints
- Molasses price volatility:Sugar beet crop failures in France and Germany are squeezing fermentation input costs for organic acid manufacturers.
- Technical performance gaps:Natural chelates exhibit lower thermal stability above 80°C, limiting adoption in high-temperature boiler water treatment.
- Substitution threat from polysaccharide complexes:Modified starch derivatives are capturing share in low-performance agricultural micronutrient applications.
Strategic Opportunities
- Pharmaceutical-grade tartaric acid:High-purity specifications for parenteral nutrition solutions command 3-4x standard industrial pricing.
- Swiss biotech cluster proximity:Jungbunzlauer's fermentation expertise anchors food-grade lactic acid chelate supply to Continental European buyers.
- Rotterdam chemical hub logistics:Tank storage and blending infrastructure enables just-in-time delivery to Northern European industrial formulators.
Industry Challenges
- Fermentation microbiologist scarcity:Specialized strain development expertise concentrates at Basel and Ludwigshafen research centers, constraining new entrant scale-up.
- OECD 301B certification timelines:Six-to-twelve month biodegradability testing protocols delay product launches for reformulated industrial cleaners.
- Legacy phosphonate inventory:Water treatment utilities face stranded asset risk from bulk EDTA stockpiles as substitution deadlines accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Chelating Agents Market |
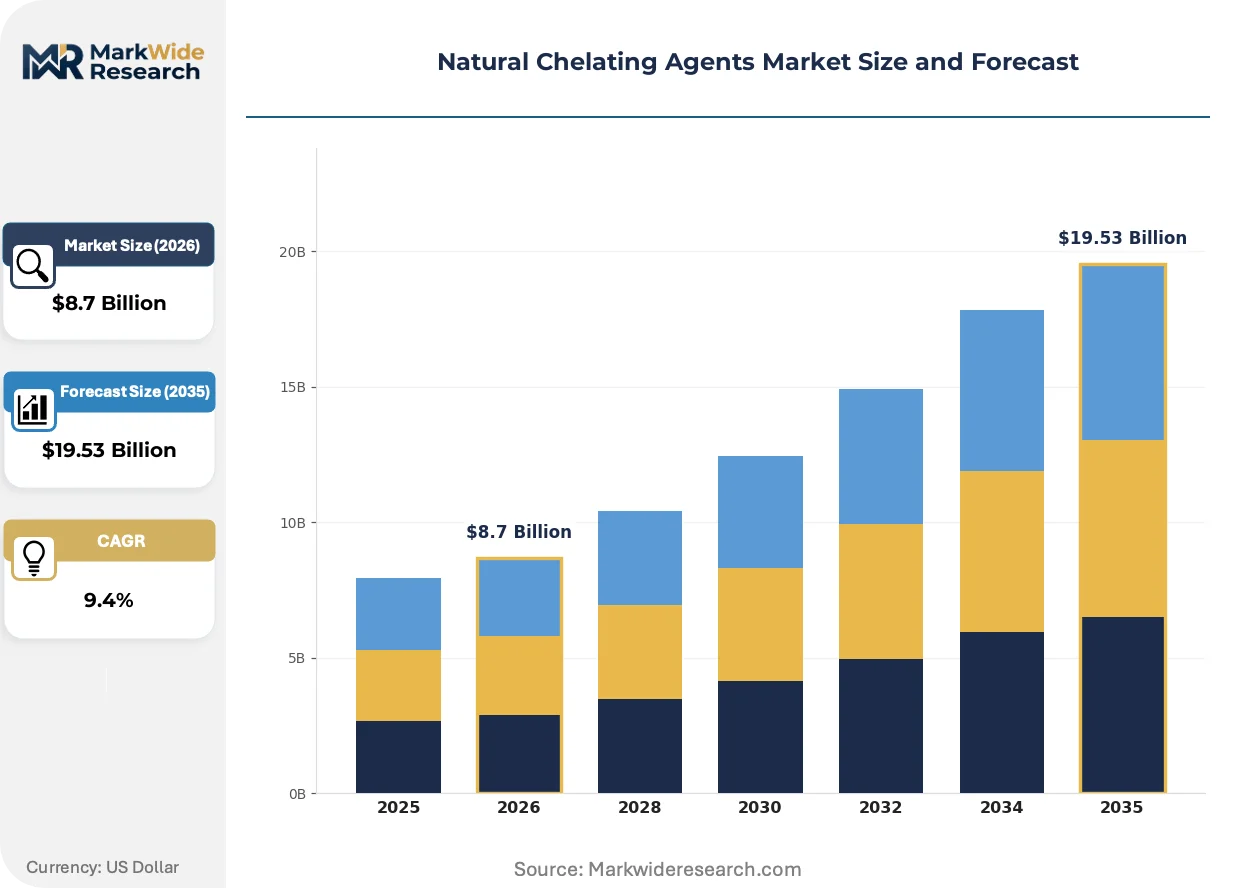
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Tartaric Acid, Lactic Acid, Malic Acid End Use Industry: Food & Beverage, Pharmaceuticals, Agriculture, Cosmetics Form: Liquid, Powder, Granular, Tablet Distribution Channel: Online, Retail Stores, Wholesalers, Direct Sales |
| Companies Covered | Dow Inc., Clariant, Nouryon, Jungbunzlauer Suisse AG, Arkema, BASF SE, Solvay, Ava Chemicals Private Limited, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Chelating Agents Market Emerging Trajectories
Bioprocess intensification and regulatory hazard reclassification are compressing product development cycles while opening margin pools in pharmaceutical and food-grade certification tiers.
Enzymatic esterification of citric acid derivatives is overtaking traditional chemical synthesis for high-purity chelate production. Personal care formulators in France and Germany are adopting enzymatic routes to meet ECHA purity specifications for leave-on cosmetics. This shift is compressing capital requirements for mid-scale producers while raising technical barriers for commodity manufacturers.
REACH Annex XIV authorization requirements for EDTA and DTPA are forcing immediate substitution in industrial cleaning concentrates. ECHA's 2024 hazard classification update triggered reformulation mandates across metal finishing and textile processing sectors. Water treatment operators in the Netherlands are accelerating phosphonate phase-out ahead of national enforcement deadlines.
Direct procurement from biorefinery clusters is displacing distributor-mediated supply chains for large-volume industrial buyers. Agricultural micronutrient blenders in Northern Europe are contracting directly with Rotterdam-based formulation facilities. This channel compression is most visible in the Netherlands, where chemical cluster proximity enables tank-to-tank transfer and quality assurance integration.
Natural Chelating Agents Market Segmentation
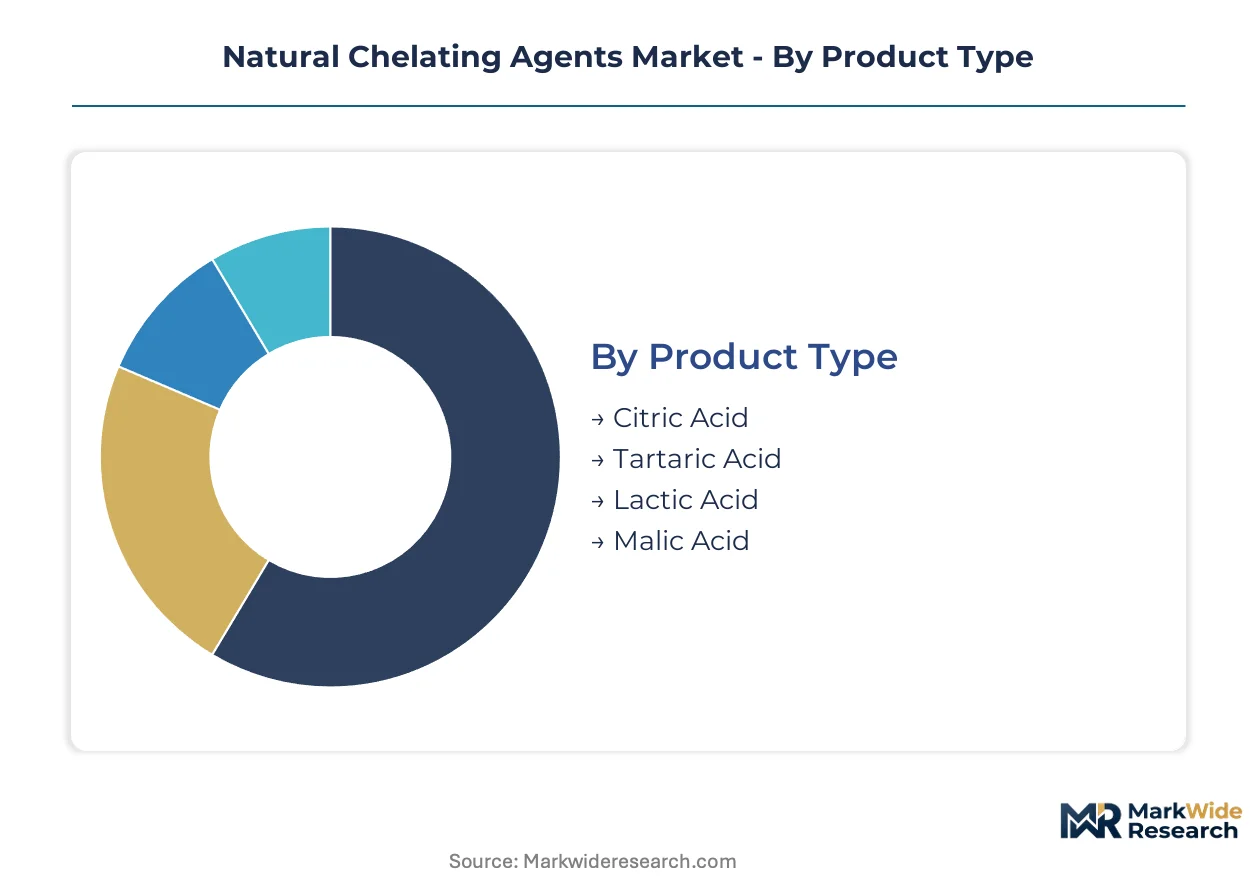
Segmentation in natural chelating agents reflects divergent technical specifications across end-use industries. Food-grade citric acid demands fermentation purity certifications that industrial boiler treatments ignore. Pharmaceutical buyers impose heavy metal limits below agricultural micronutrient standards.
Product Type:
Cost tier differentiation separates commodity fermentation outputs from specialty acid derivatives commanding certification premiums.
- Citric Acid:Fermentation-derived tricarboxylic acid with broad pH stability between 3 and 11. BASF's Ludwigshafen complex ships food-grade volumes to German beverage processors while industrial grades supply Rotterdam water treatment formulators. REACH biodegradability mandates are accelerating citric substitution for phosphonate boiler treatments.
- Lactic Acid:Alpha-hydroxy acid produced via carbohydrate fermentation with superior metal sequestration at neutral pH. Jungbunzlauer's Swiss facilities dominate pharmaceutical-grade supply for parenteral nutrition across Continental Europe. Personal care brands in France are eliminating petroleum-derived chelators in favor of lactic acid credentials.
- Tartaric Acid:Dicarboxylic acid derived from grape processing byproducts, concentrated in Italian and Spanish wine regions.
- Malic Acid:Hydroxycarboxylic acid with intermediate chelation strength, finding niche use in fruit-derived cosmetic formulations.
Volume sits with citric acid; growth tilts toward lactic acid.
End Use Industry:
Application maturity determines whether buyers accept performance trade-offs for biobased certification.
- Food & Beverage:Acidulants and preservation systems requiring EFSA-approved fermentation sources. German dairy processors specify citric acid for calcium sequestration in UHT milk stabilization. OECD 301B biodegradability protocols are becoming standard in Dutch beverage manufacturing.
- Pharmaceuticals:Parenteral and oral dosage forms demanding USP-grade purity with heavy metal content below 10 ppm. Swissmedic inspections of Jungbunzlauer facilities enforce batch-level traceability for Continental European hospital suppliers. Tartaric acid derivatives command 3-4x industrial pricing for intravenous applications.
- Agriculture:Micronutrient delivery systems for foliar feeds and soil amendments, price-sensitive to commodity acid inputs.
- Cosmetics:Rinse-off and leave-on formulations navigating ECHA hazard reclassifications ahead of enforcement deadlines.
Food and beverage commands current volume; pharmaceuticals deliver steepest expansion trajectory.
Form:
Customer handling infrastructure dictates physical specification requirements across processing environments.
- Liquid:Aqueous solutions enabling precision dosing in continuous processing lines. Dutch dairy cooperatives specify liquid citric acid for automated pH adjustment in cheese manufacturing. Tank-to-tank transfer from Rotterdam chemical clusters reduces handling costs for high-volume buyers.
- Powder:Spray-dried crystals with extended shelf stability for distributed agricultural blending operations.
- Granular:Controlled dissolution rates for soil-applied micronutrient fertilizers in Northern European arable farming.
- Tablet:Pre-weighed units for small-scale cosmetic formulation and laboratory applications.
Liquid dominates food processing throughput; powder and granular formats capture agricultural volume.
Distribution Channel:
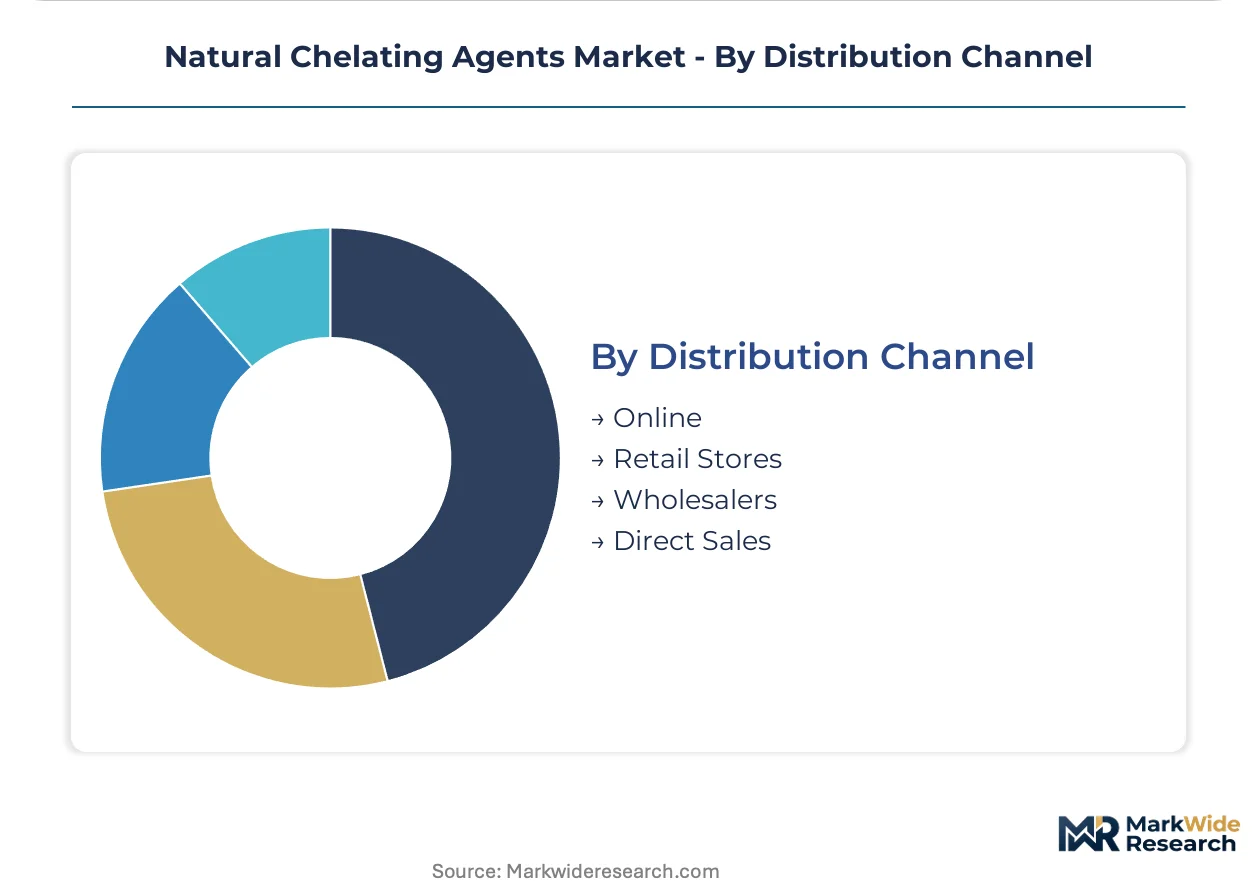
Supply chain compression is eliminating intermediary margins for qualified industrial buyers.
- Direct Sales:Long-term contracts linking biorefinery output to formulation facilities. Agricultural micronutrient blenders in the Netherlands are contracting directly with Rotterdam-based producers, bypassing chemical distributors. Quality assurance integration through shared tank storage enables just-in-time delivery.
- Wholesalers:Regional chemical distributors serving mid-scale industrial cleaners and metal finishers with mixed acid portfolios.
- Retail Stores:Small-package sales to artisan food producers and independent cosmetic formulators.
- Online:Specification sheets and certificate-of-analysis access for research procurement and sample ordering.
Direct sales anchor industrial volume; online channels are expanding most quickly for sample-to-scale purchasing workflows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Sugar beet cultivation zones in northern France and the Rhineland anchor fermentation feedstock supply for European natural chelating agent production. Biorefinery clustering around Rotterdam and Ludwigshafen shapes continental distribution patterns. Regulatory enforcement timelines vary across member states, creating procurement urgency differentials.
Germany
Water treatment utilities in the Ruhr industrial corridor are accelerating phosphonate substitution ahead of national REACH enforcement deadlines. The Federal Environment Agency has tightened biodegradability certification requirements for cooling tower chemicals under OECD 301B protocols. BASF SE's Ludwigshafen complex ships captive citric acid volumes to regional beverage processors and industrial formulators.
France
Personal care manufacturers in the Île-de-France region are eliminating petroleum-derived chelators from rinse-off formulations ahead of ECHA hazard reclassifications. ANSM inspections of cosmetic facilities have elevated documentation requirements for biobased ingredient sourcing. The Champagne-Ardenne sugar beet belt supplies molasses feedstock to fermentation plants serving northern European organic acid demand.
Netherlands
Rotterdam's chemical cluster hosts multiple biobased formulation facilities supplying agricultural micronutrient blenders across Northern Europe. The Dutch National Institute for Public Health and the Environment has accelerated phosphonate phase-out timelines for municipal water treatment operators. Tank-to-tank transfer infrastructure enables just-in-time delivery to industrial buyers in the Randstad manufacturing zone.
Switzerland
Pharmaceutical-grade lactic acid chelate demand from Continental European hospital suppliers concentrates around Jungbunzlauer's Swiss fermentation facilities. Swissmedic batch-level traceability requirements enforce purity standards for parenteral nutrition applications. The Basel biotech research cluster concentrates specialized microbiologist expertise for strain development.
Italy
Tartaric acid extraction from grape processing byproducts sustains specialty chelate production in Piedmont and Veneto wine regions. Italian cosmetic formulators in Lombardy are adopting enzymatic esterification routes to meet ECHA purity specifications for leave-on products. The Emilia-Romagna food processing belt generates steady citric acid demand for dairy stabilization applications.
Natural Chelating Agents Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue pharmaceutical-grade certification and enzymatic process differentiation. The market structures around three archetypes: integrated chemical conglomerates with captive fermentation capacity, specialty biotech firms focused on high-purity acid derivatives, and regional distributors blending commodity formulations. Dominant competitive moves include backward integration into sugar beet supply contracts and strategic partnerships with Rotterdam storage terminal operators.
Within the integrated chemical tier, BASF SE and Clariant exemplify divergent positioning strategies. BASF anchors its Ludwigshafen complex around food-grade citric acid scale, while Clariant occupies specialty tartaric acid territory aimed at pharmaceutical specifications. Jungbunzlauer Suisse AG represents the dedicated biotech archetype, leveraging Swiss fermentation expertise to dominate Continental European lactic acid chelate supply.
| Leading Market Players |
|---|
| Dow Inc. |
| Clariant |
| Nouryon |
| Jungbunzlauer Suisse AG |
| Arkema |
| BASF SE |
| Solvay |
| Ava Chemicals Private Limited |
| LANXESS |
| Others |
Supply Flow & Price Mechanics
OECD 301B biodegradability certification gates both qualified supply and premium-tier pricing access, as industrial buyers in Germany and France now require documented environmental compliance before contract eligibility. Water treatment utilities face stranded asset risk from legacy phosphonate inventories while fermentation-derived alternatives command certification premiums.
Pricing Analysis
Certificate-of-analysis bundling separates quoted prices from unbundled commodity acid transactions. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade levels reflects purity certification investment and heavy metal testing depth. Price differentiation hinges on USP-grade traceability and OECD biodegradability validation. Cost compression in industrial citric acid is intensifying because sugar beet molasses volatility squeezes fermentation margins. Agricultural micronutrient blenders exhibit highest price sensitivity; parenteral nutrition suppliers accept 3-4x premiums for Swissmedic-insured batch documentation.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping sourcing toward captive biorefinery supply within member state borders. Production gravity centers on Germany, the Netherlands, and Switzerland for fermentation capacity and formulation infrastructure. Raw material dependencies draw from French and German sugar beet cultivation, Swiss pharmaceutical-grade packaging, and Rotterdam tank storage terminals. Single-source vulnerability concentrates in specialized fermentation microbiologist expertise anchored at Basel and Ludwigshafen research clusters. Distribution runs through direct long-term contracts linking biorefinery output to Northern European industrial formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzymatic esterification technology is displacing traditional chemical synthesis routes, compressing capital requirements for mid-scale producers while raising technical barriers for commodity manufacturers.
For Market Incumbents: Hedge against phosphonate substitution acceleration by securing backward integration into sugar beet supply contracts in Champagne-Ardenne and Rhineland cultivation zones. Expand pharmaceutical-grade certification capacity at Swiss facilities before ECHA hazard reclassifications tighten purity specifications. Clariant's specialty tartaric acid positioning demonstrates margin defense through high-purity intravenous applications. For New Entrants and Emerging Players: Small-scale cosmetic formulators in Lombardy represent an underserved buyer archetype seeking enzymatic-process credentials without minimum order thresholds. White-space targets include pharmaceutical-grade malic acid derivatives for fruit-derived cosmetic formulations and direct-to-blender supply contracts bypassing Rotterdam distributor margins. Go-to-market execution should emphasize tank-to-tank quality assurance integration for agricultural micronutrient blenders. For Investors and Strategic Acquirers: Jungbunzlauer's Swiss fermentation facility expansion is the leading indicator that pharmaceutical-grade lactic acid chelate supply will tighten before demand saturation. Long-term viability favors vertically integrated biorefinery operators with captive organic acid fermentation and OECD 301B certification infrastructure. Acquisition targets should display strain development expertise and existing EFSA or USP-grade regulatory dossiers. Monitor ANSM inspection timelines for cosmetic facility documentation requirements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sugar Beet Supply | French and German molasses contracts secure fermentation input cost stability against crop failure volatility. |
| Pharmaceutical-Grade Certification Investment | Swissmedic batch-level traceability commands 3-4x pricing premiums for parenteral nutrition applications. |
| Enzymatic Process Technology Adoption | ECHA purity specifications for leave-on cosmetics favor enzymatic esterification over chemical synthesis routes. |
| Direct Sales Channel Expansion | Tank-to-tank transfer from Rotterdam chemical clusters eliminates distributor margins for agricultural blenders. |
| Biorefinery Cluster Proximity Partnerships | Ludwigshafen and Basel research center access concentrates scarce fermentation microbiologist expertise. |
Methodological Framework
Document review covered EU REACH regulatory filings, ECHA hazard classification updates, and OECD biodegradability test protocols, complemented by interviews with fermentation plant managers, water treatment procurement leads, pharmaceutical formulation scientists, and Rotterdam chemical terminal operators. Secondary validation drew from customs trade data for organic acid imports, SEC filings of integrated chemical conglomerates, and Cefic industry reports. Bottom-up volume estimates from biorefinery capacity announcements were triangulated against top-down demand projections from end-use industry consumption patterns.
Segment-level outputs across the projection horizon reflect modeled interactions between product type, purity grade tier, end-use industry application, and regional production hub concentration. CAGRs were derived from elasticity-adjusted demand curves incorporating REACH enforcement timeline scenarios and sugar beet yield volatility. Industry-specific forecast inputs included EFSA approval status for fermentation sources and Swissmedic inspection frequency for pharmaceutical-grade facilities.
Revisions become necessary when ECHA accelerates EDTA derivative hazard reclassifications, sugar beet crop failures exceed historical yield variance bands, or enzymatic process technology achieves cost parity with chemical synthesis at commercial scale. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Palmitoyl Chloride Market
Chemical Intermediates
Fungal Staining Reagent Market
Chemical Intermediates
Dimethyl Dicarbonate Market
Chemical Intermediates
Dental Etching Agents Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Acetoacetanilide Market
Chemical Intermediates
Tertiary Butylhydroquinone Acids Market
Chemical Intermediates
Methacrylic Ester Market
Chemical Intermediates
Global Iron Chelates Market
Chemical Intermediates
Ethylene Diamine Tetra Acetic Acid (EDTA) Market
Chemical Intermediates
Global Electrophoresis Reagents Market
Chemical Intermediates
Leather Chemicals Market
Chemical Intermediates
Copper Chemicals Market
Chemical Intermediates
Epoxy Silanes Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market