
 Sodium Caprylate Market | 2026-2036
Sodium Caprylate Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Caprylate Market Outlook
Market Overview
The sodium caprylate market is decoupling into two distinct supply tiers. Pharmaceutical-grade material commands stringent purity certifications and dedicated manufacturing lines, while commodity-grade product serves food and industrial applications with looser specifications. Merck KGaA leverages its European manufacturing base to dominate high-purity pharmaceutical supply. Thermo Fisher Scientific anchors North American distribution through its extensive life sciences channel network. Jost Chemical Co. specializes in USP-grade mineral salts and competes aggressively on custom synthesis capabilities for drug developers.
Product Definition and Segmentation
Sodium caprylate is the sodium salt of caprylic acid (C8H16NaO2), a medium-chain fatty acid derivative produced via saponification of coconut or palm kernel oil, functioning primarily as an emulsifier, solubilizer, and antimicrobial agent across pharmaceutical, nutritional, and cosmetic formulations. Powder formulations lead volume shipments due to superior stability and ease of handling in bulk pharmaceutical manufacturing, while liquid variants capture fastest growth in parenteral and topical drug delivery where rapid dispersion matters. The dietary supplements application sits at the margin-rich intersection of sports nutrition and ketogenic diet trends, whereas food additives represent a mature, price-sensitive segment with limited differentiation.
Regulatory Environment and Outlook
FDA enforces USP-NF monograph compliance for sodium caprylate used in drug products, while EMA through its quality guidelines mandates nitrosamine impurity screening for fatty acid salts in pharmaceutical applications. ISO 9001 and EXCiPACT certification increasingly determine supplier qualification for multinational pharmaceutical procurement. Stakeholders must monitor evolving pharmacopeial harmonization between USP, EP, and JP standards, as divergence in heavy metal limits and microbial specifications threatens to fragment qualified supplier pools and reshape sourcing geography.
Market Dynamics
Pharmaceutical-grade sodium caprylate supply is consolidating around manufacturers capable of simultaneously meeting USP-NF monograph compliance and EMA nitrosamine screening protocols, creating a bifurcation where certified suppliers capture formulation partnerships while uncertified producers retreat to commodity applications.
Growth Catalysts
- Biologics manufacturing expansion:Monoclonal antibody formulators in the United States require high-purity emulsifiers for protein stabilization, pulling pharmaceutical-grade sodium caprylate into mAb production workflows.
- REACH purity escalation:ECHA's tightening benchmarks for fatty acid salt impurities are disqualifying legacy suppliers and redirecting procurement toward EXCiPACT-certified manufacturers.
- Ketogenic nutrition formulation:Sports nutrition brands are incorporating medium-chain fatty acid salts into exogenous ketone products, opening a margin-rich channel beyond traditional pharmaceutical demand.
Market Restraints
- Coconut oil feedstock volatility:Weather disruptions in Southeast Asian palm and coconut plantations transmit directly to caprylic acid input costs, compressing margin predictability for saponification-based producers.
- European supply concentration:High-purity pharmaceutical manufacturing clusters disproportionately in Germany and Switzerland, exposing buyers to single-source risk during regulatory inspections or force majeure events.
- Synthetic caprylate substitution:Petrochemical-derived sodium octanoate from Asian producers competes on price in industrial emulsifier applications, eroding volume for natural-origin suppliers.
Strategic Opportunities
- Indian pharmaceutical manufacturing:CDSCO's alignment with ICH Q3D guidelines creates a compliance pathway for USP-grade suppliers to capture formulation outsourcing from Mumbai and Hyderabad API clusters.
- Continuous manufacturing integration:Direct compression and hot-melt extrusion adoption by oral solid dose producers enables real-time sodium caprylate incorporation as a solubility enhancer, bypassing traditional batch processing.
- Japan PMDA harmonization:METI's push for pharmacopeial convergence with USP standards reduces dual-testing burdens, lowering market entry costs for Western-certified suppliers.
Industry Challenges
- Analytical chemistry talent scarcity:Nitrosamine and elemental impurity testing at ppb levels requires specialized chromatography expertise that outpaces current training pipeline output in contract manufacturing organizations.
- Multi-pharmacopeial certification timelines:Simultaneous USP, EP, and JP validation for a single sodium caprylate SKU extends qualification cycles to 18-24 months, freezing working capital and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Caprylate Market |
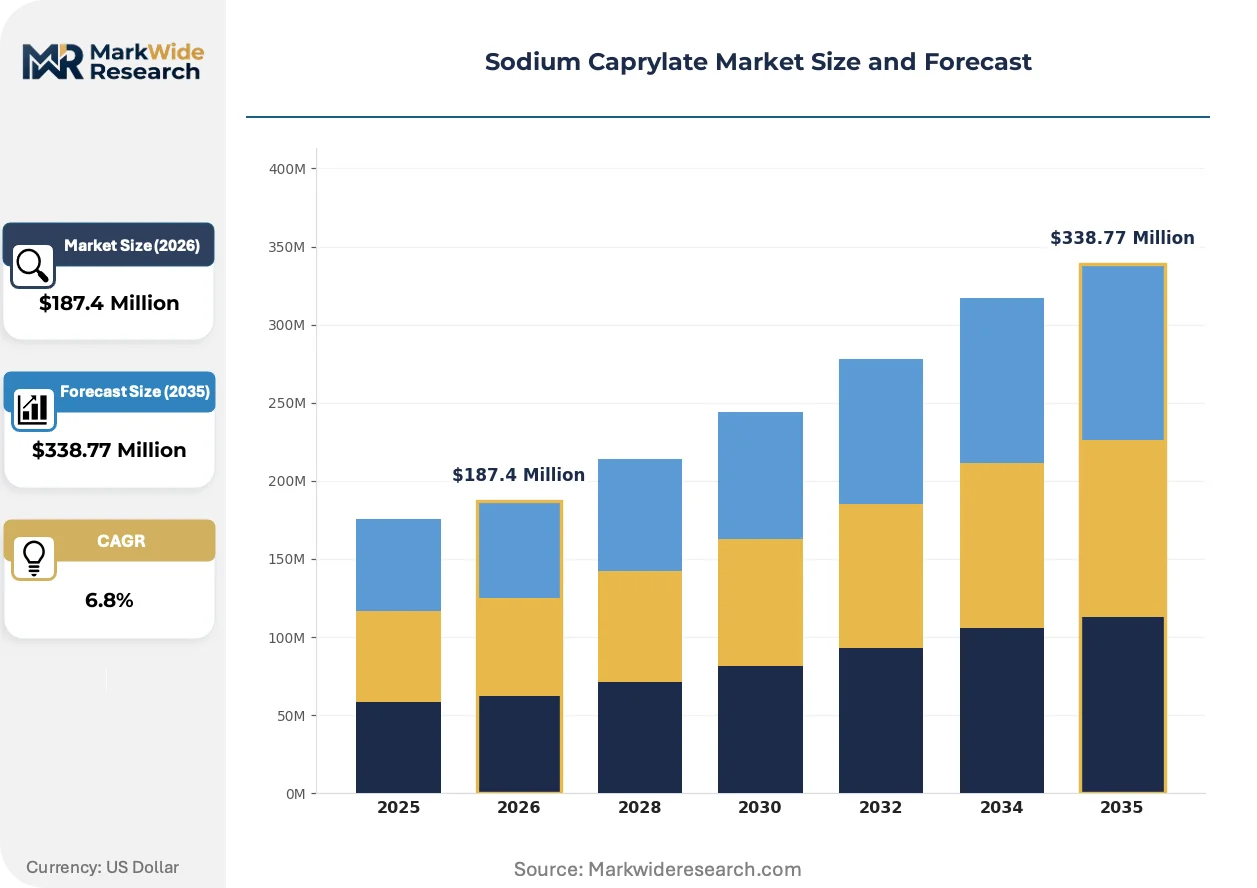
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Capsule, Tablet Application: Pharmaceuticals, Dietary Supplements, Food Additives, Cosmetics End User: Hospitals, Pharmacies, Nutraceuticals, Personal Care Distribution Channel: Online, Retail, Distributors, Direct Sales |
| Companies Covered | Glentham Life Science, Tokyo Chemical Industry Co., Ltd. (TCI), Merck KGaA, Beantown Chemical Corporation, Penta Manufacturing Company, Thermo Fisher Scientific, Spectrum Chemical Mfg. Corp., Jost Chemical Co., Acme Synthetic Chemicals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Caprylate Market Strategic Shifts
Formulation science and regulatory analytics are converging to redefine how sodium caprylate suppliers demonstrate value, with purity certification becoming a competitive weapon rather than a baseline requirement. Three developments are reshaping technical and commercial positioning.
Continuous manufacturing equipment for oral solid dose production is absorbing sodium caprylate as an inline solubilizer rather than a batch additive. Pfizer and Novartis manufacturing divisions are retrofitting legacy tablet lines with twin-screw extruders that meter caprylate salts directly into molten drug matrices. This equipment shift is compressing batch release timelines from weeks to days while demanding powder grades with tighter particle size distribution specifications.
EMA's 2023 revision to its nitrosamine risk assessment guideline for chemically synthesized APIs is forcing fatty acid salt suppliers to implement LC-MS/MS screening protocols. The industrial consequence is a capital equipment arms race among European manufacturers to install dedicated impurity testing suites. Parenteral-grade sodium caprylate, used in biologic stabilization buffers, faces the steepest compliance burden and is seeing supplier consolidation accelerate fastest in Germany.
Biopharma procurement teams are consolidating excipient suppliers to reduce audit burden, replacing fragmented multi-source strategies with single or dual-source partnerships under long-term quality agreements. This behavior shift is displacing spot-market purchasing in North American monoclonal antibody manufacturing. The trend is most visible in Massachusetts and North Carolina biotech clusters, where procurement directors now prioritize supplier quality system maturity over unit price in caprylate sourcing decisions.
Sodium Caprylate Market Segmentation
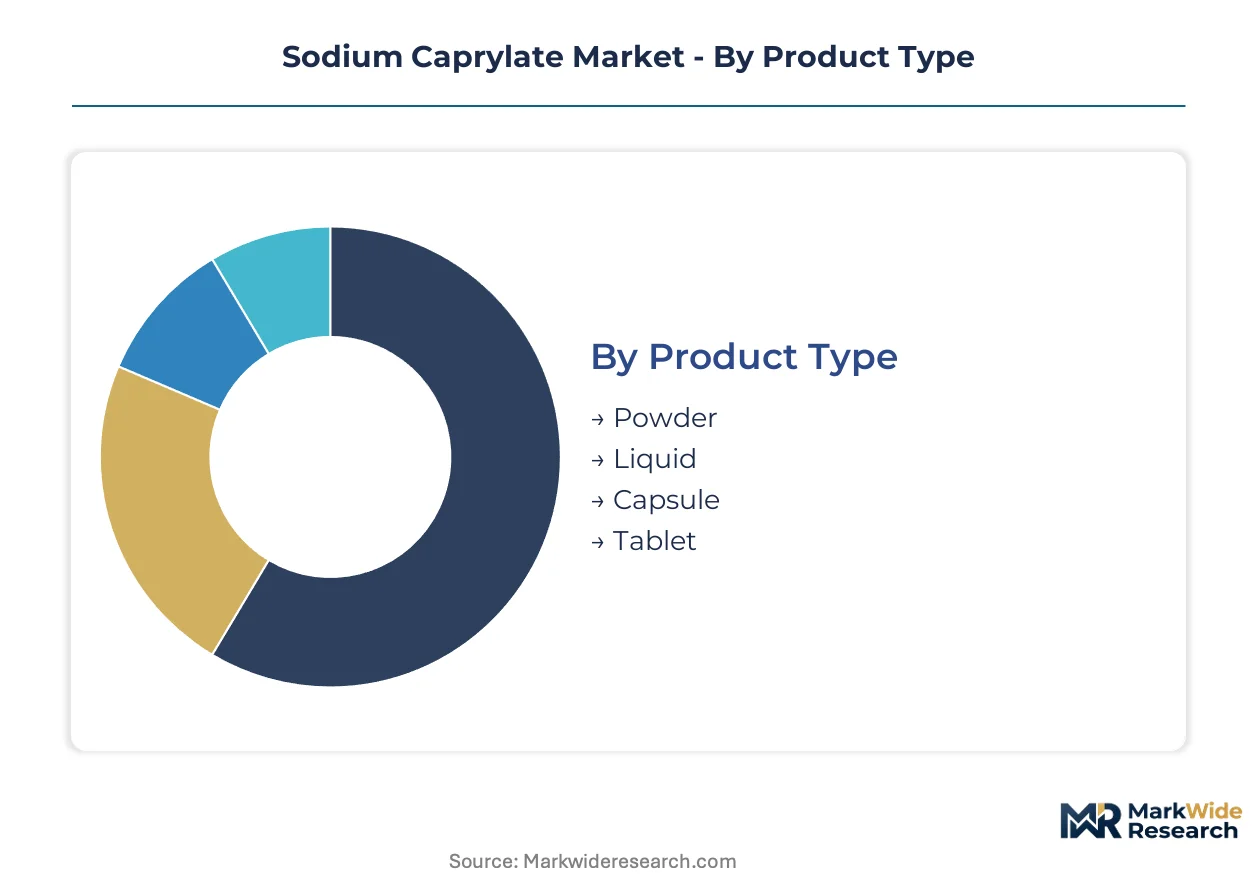
Sodium caprylate segmentation reflects a bifurcation between high-purity pharmaceutical grades commanding certification premiums and commodity grades competing on feedstock efficiency. Formulators select product types based on processing equipment compatibility, while application segments diverge sharply in regulatory burden and margin structure.
Product Type:
Powder formulations dominate bulk pharmaceutical procurement for their stability and handling efficiency, while liquid variants capture premium positioning in specialized delivery systems.
- Powder:Anhydrous crystalline grades with defined particle size distributions serve oral solid dose manufacturing and hot-melt extrusion processes. Thermo Fisher Scientific channels this material through North American life sciences distribution to monoclonal antibody formulators in Massachusetts and North Carolina. The segment anchors volume shipments but faces compression from continuous manufacturing equipment demanding tighter PSD specifications.
- Liquid:Aqueous solutions and concentrated suspensions enable rapid dispersion in parenteral buffers and topical formulations. Biologics manufacturers in the United States specify liquid caprylate for protein stabilization workflows where batch dissolution time directly impacts release schedules. This configuration gains share fastest in parenteral applications despite higher shipping costs and shorter shelf stability.
- Capsule:Pre-metered gelatin or HPMC shells containing sodium caprylate powder target sports nutrition and exogenous ketone products. Direct-to-consumer brands in the dietary supplements channel favor this format for dosing convenience.
- Tablet:Compressed caprylate salts with binders and disintegrants serve niche pharmaceutical applications requiring precise unit dosing. Limited adoption reflects competition from powder-in-capsule alternatives.
Today's leader: Powder. Tomorrow's challenger: Liquid.
Application:
Application segmentation tracks the divergence between regulated pharmaceutical pathways and consumer-facing nutrition markets, with compliance costs fragmenting supplier qualification pools.
- Pharmaceuticals:USP-NF grade material functions as solubility enhancers, emulsifiers, and antimicrobial agents in oral and parenteral drug products. EMA nitrosamine screening protocols and FDA monograph compliance create dual-certification barriers that consolidate procurement around EXCiPACT-certified manufacturers in Germany and Switzerland. This segment commands the steepest purity premiums and longest qualification cycles.
- Dietary Supplements:Medium-chain fatty acid salts serve ketogenic nutrition and sports performance formulations with lighter regulatory burdens than pharmaceutical grades. The intersection of sports nutrition trends and exogenous ketone demand creates margin-rich opportunities outside traditional drug channels, though FDA cGMP for supplements still mandates identity testing and contaminant screening.
- Food Additives:Emulsifier applications in processed foods operate under EFSA and FDA GRAS frameworks with mature, price-sensitive demand. Coconut oil feedstock volatility transmits directly to margin pressure in this specification-loose segment.
- Cosmetics:Surfactant and preservative functions in personal care formulations leverage caprylate's antimicrobial properties against skin flora. REACH registration requirements in Europe and MoCRA implementation in the United States are elevating documentation burdens for cosmetic-grade suppliers.
Pharmaceuticals capture the dominant revenue share. Dietary supplements are climbing the fastest as ketogenic formulation expands.
End User:
End user segmentation reveals how procurement authority concentrates in institutional healthcare versus fragmenting across direct-to-consumer channels.
- Hospitals:Pharmacy and therapeutics committees specify parenteral-grade sodium caprylate for compounded biologic stabilization buffers. USP compliance and lot traceability requirements favor contracted supply agreements over spot purchasing.
- Pharmacies:Retail and specialty pharmacies procure pharmaceutical-grade material for extemporaneous compounding and approved drug product distribution. Consolidation among national chains in the United States is reducing supplier count per formulary.
- Nutraceuticals:Contract manufacturers and branded supplement houses source food-grade or USP-grade caprylate for encapsulation and tableting. CDSCO-aligned manufacturers in India are emerging as cost-competitive suppliers to this segment.
- Personal Care:Cosmetic formulators and contract manufacturers specify cosmetic-grade material for emulsion stability and preservation. ECHA REACH compliance and emerging MoCRA obligations in the United States are tightening supplier documentation requirements.
Institutional procurement dominates volume. Direct-to-consumer channels are fragmenting supplier relationships fastest.
Distribution Channel:
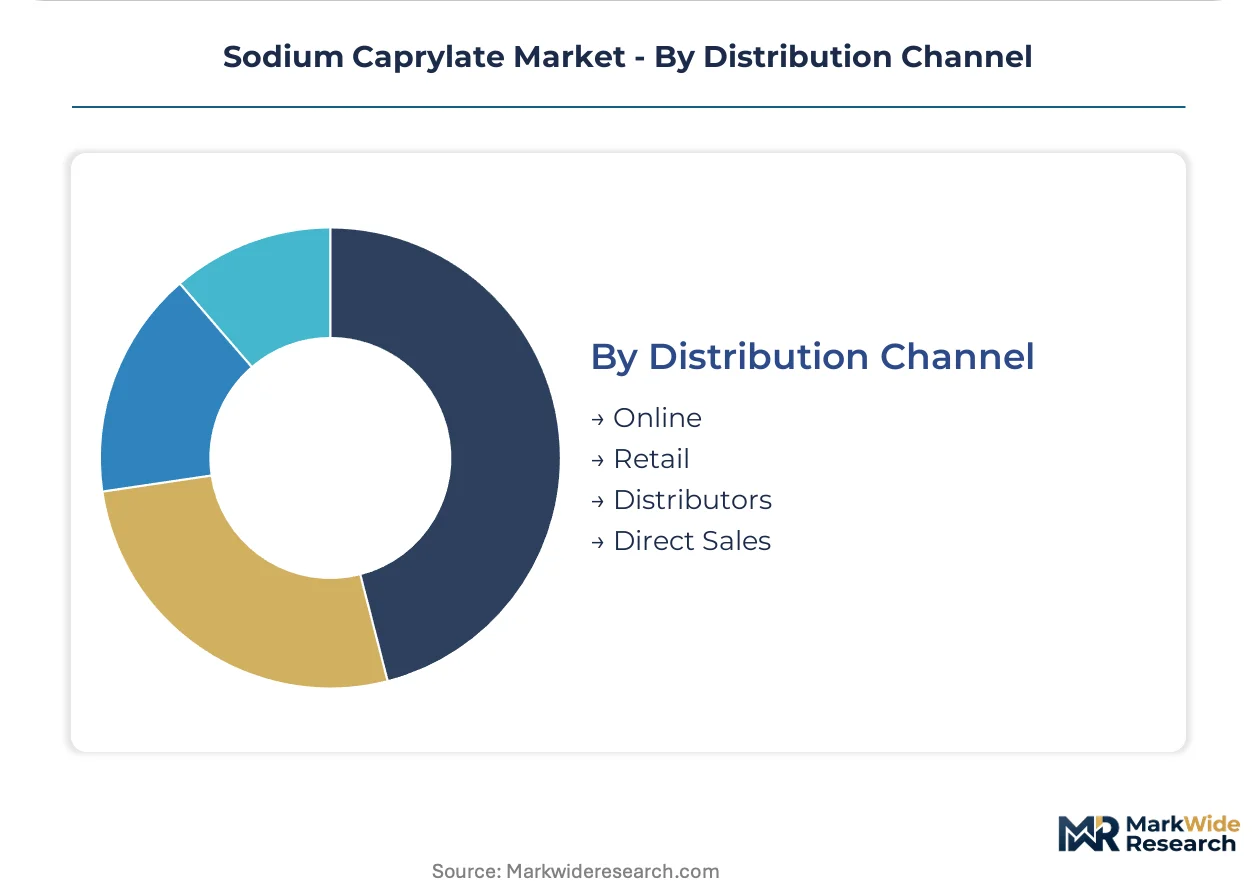
Channel segmentation tracks the shift from relationship-based direct sales toward digital procurement platforms in commodity grades, while pharmaceutical grades remain locked in quality agreement structures.
- Online:E-commerce platforms and B2B marketplaces serve small-batch nutraceutical and cosmetic formulators with credit-card purchasing and rapid fulfillment. This channel expands fastest among startups lacking established supplier relationships.
- Retail:Brick-and-mortar chemical supply houses and pharmacy wholesalers distribute packaged quantities to regional compounders and independent formulators. Geographic coverage limitations constrain growth in this legacy channel.
- Distributors:Authorized distributors like Thermo Fisher Scientific's life sciences network provide inventory buffering, technical support, and regulatory documentation to pharmaceutical and biotechnology manufacturers. Multi-year distribution agreements with exclusive territories characterize this channel.
- Direct Sales:Manufacturer-direct relationships dominate pharmaceutical-grade procurement, with Merck KGaA and Jost Chemical Co. maintaining field technical service for qualified accounts. Audit requirements and quality agreements create high switching costs in this channel.
Distributor relationships anchor pharmaceutical supply. Online channels are gaining share fastest in nutraceutical and cosmetic segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized analytical chemists and pharmaceutical formulation scientists concentrate in Germany, the United States, and Switzerland, anchoring high-purity sodium caprylate manufacturing and quality validation capabilities.
United States
Monoclonal antibody formulators in Massachusetts and North Carolina drive pharmaceutical-grade demand for protein stabilization buffers. FDA enforces USP-NF monograph compliance with nitrosamine screening protocols for all fatty acid salt excipients. The Greater Boston biotech cluster sources EXCiPACT-certified material through dedicated distribution agreements with life sciences channel partners.
Germany
EMA quality guidelines and REACH purity benchmarks disqualify legacy suppliers from pharmaceutical procurement pools. ECHA's tightening impurity thresholds for fatty acid salts redirect formulation partnerships toward certified manufacturers. The Rhine-Main manufacturing corridor hosts dedicated production lines serving European biologics producers with parenteral-grade material.
Switzerland
Swissmedic's alignment with ICH Q3D elemental impurity guidelines creates compliance pathways for USP-grade suppliers targeting biopharma clusters. The Basel pharmaceutical hub demands lot traceability and dedicated manufacturing lines for monoclonal antibody excipients. Swiss manufacturers leverage proximity to German chemical infrastructure while maintaining independent pharmacopeial certifications.
India
CDSCO's adoption of ICH Q3D guidelines enables USP-grade suppliers to capture formulation outsourcing from Mumbai and Hyderabad API manufacturers. The country's national pharmaceutical regulator mandates identity testing and contaminant screening for all excipient imports. Maharashtra's contract manufacturing organizations are expanding analytical chemistry capabilities to meet Western certification standards.
Japan
METI's push for pharmacopeial convergence with USP standards reduces dual-testing burdens for Western-certified suppliers entering the market. PMDA's quality guidelines for chemically synthesized APIs incorporate nitrosamine risk assessment protocols. The Kanto region's pharmaceutical manufacturers are consolidating excipient suppliers to reduce audit burden and simplify procurement workflows.
Sodium Caprylate Market Competitive Environment
Top-tier vendors anchor pharmaceutical-grade supply through dedicated manufacturing lines and multi-pharmacopeial certifications, while commodity-grade producers compete on feedstock efficiency and regional distribution reach. The market structure bifurcates around purity tiers, with certified suppliers capturing formulation partnerships and uncertified producers retreating to food and industrial applications. Two strategic archetypes dominate: European chemical conglomerates with integrated life sciences divisions, and specialized mineral salt manufacturers with custom synthesis capabilities. Competitive moves center on multi-year quality agreements with biopharma procurement teams and backward integration into coconut oil feedstock sourcing.
Within the European chemical conglomerate tier, Merck KGaA and Thermo Fisher Scientific exemplify the integrated life sciences model, leveraging extensive distribution networks and regulatory documentation capabilities to anchor pharmaceutical-grade supply. Jost Chemical Co. occupies a distinct position among USP-grade mineral salt specialists, competing on custom synthesis capabilities and dedicated manufacturing lines for drug developers. These three companies represent the concentration of certified manufacturing capacity serving monoclonal antibody formulators and parenteral drug producers.
| Leading Market Players |
|---|
| Glentham Life Science |
| Tokyo Chemical Industry Co., Ltd. (TCI) |
| Merck KGaA |
| Beantown Chemical Corporation |
| Penta Manufacturing Company |
| Thermo Fisher Scientific |
| Spectrum Chemical Mfg. Corp. |
| Jost Chemical Co. |
| Acme Synthetic Chemicals |
| Others |
Value Chain & Pricing Dynamics
Backward integration into coconut oil feedstock sourcing anchors both supply security and margin control for sodium caprylate manufacturers competing across pharmaceutical and commodity tiers. German and Swiss producers leveraging captive supply chains command pricing power in USP-grade segments where EMA nitrosamine protocols disqualify spot-market sourcing.
Pricing Analysis
Bundled certification-plus-testing services separate pharmaceutical-grade quotations from unbundled commodity transactions. Three-tier pricing structure across pharmaceutical, food-grade, and industrial levels reflects USP-NF compliance costs and EXCiPACT audit investments. Pricing pressure stems from synthetic sodium octanoate substitution in Asian industrial markets. Food additive buyers exhibit highest price sensitivity; monoclonal antibody formulators prioritize quality system maturity over unit cost.
Supply Chain Analysis
Domestic-content mandates in India's pharmaceutical sector redirect excipient procurement toward CDSCO-aligned local manufacturers. Supply concentrates in Germany, Switzerland, and the United States for pharmaceutical grades, with Southeast Asian plantations anchoring coconut oil feedstock. Saponification inputs draw from palm kernel and coconut oil derivatives exposed to weather volatility. Single-source vulnerability concentrates in the Rhine-Main corridor where EMA-certified production clusters. Distribution runs through life sciences channel partners for pharmaceutical tiers and B2B platforms for commodity grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Sodium caprylate functions as a stable compounder anchored by biologics manufacturing expansion and tightening pharmacopeial purity mandates that sustain premium pricing power.
For Market Incumbents: Cement multi-year quality agreements with Massachusetts and North Carolina biotech clusters before synthetic substitution erodes industrial-tier margins. Expand EXCiPACT-certified capacity in the Rhine-Main corridor to capture EMA-driven supplier consolidation. Prioritize nitrosamine testing infrastructure investments over commodity-grade volume expansion. For New Entrants and Emerging Players: The gap between pharmaceutical-grade premiums and food-grade commodity pricing creates entry space for USP-certified specialists targeting Indian CDSCO-aligned contract manufacturers. Penetrate Mumbai and Hyderabad API clusters with custom synthesis capabilities. Lead with analytical chemistry services bundled with material supply to differentiate from established distributors. For Investors and Strategic Acquirers: Consolidation pressure builds where multi-pharmacopeial certification timelines stretch to 18-24 months and freeze working capital for sub-scale producers. Position for 5-10 year holding periods centered on quality system maturity rather than feedstock scale. Target mineral salt specialists with USP-grade capabilities and established FDA inspection histories. Watch EMA nitrosamine guideline revisions as inflection signals for accelerated supplier disqualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive coconut oil sourcing insulates margin volatility from Southeast Asian weather disruptions. |
| Multi-Pharmacopeial Certification Investment | Simultaneous USP-EP-JP validation opens procurement pathways to Japanese PMDA-aligned manufacturers. |
| Continuous Manufacturing Partnership | Inline solubilizer specifications for twin-screw extruders capture Pfizer and Novartis retrofit demand. |
| Analytical Chemistry Capability Buildout | LC-MS/MS nitrosamine screening suites qualify supply for parenteral-grade biologic stabilization buffers. |
| Indian Distribution Channel Expansion | CDSCO-aligned local presence captures formulation outsourcing from Maharashtra contract manufacturers. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary conversations engaged pharmaceutical formulators, biologics manufacturing directors, excipient procurement leads at monoclonal antibody producers, and regulatory affairs specialists at CDSCO and PMDA. Secondary validation drew from FDA USP-NF monographs, EMA quality guidelines, EXCiPACT certification databases, and customs trade records for caprylic acid derivatives. Bottom-up volume modeling and top-down value triangulation cross-checked segment outputs.
Segment-weighting across product type, application, and end-user dimensions shaped the analytical framework. Pharmaceutical-grade, dietary supplement, food additive, and cosmetic tiers were modeled separately with grade-specific purity benchmarks. Powder, liquid, capsule, and tablet configurations tracked divergent processing equipment compatibility. CAGRs derived from elasticity-adjusted demand projections incorporating biologics capacity expansion and ketogenic nutrition trend adoption. Nitrosamine regulatory timeline assumptions and coconut oil feedstock price scenarios fed sensitivity testing.
Caveats apply where EMA guideline revisions, force majeure events in Southeast Asian plantations, or synthetic substitution breakthroughs could materially shift the outlook. Forecasts embed assumptions about pharmacopeial harmonization progress and continuous manufacturing equipment adoption rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Conditioning Agent Market
Additives
Electrolyte Additives for Lithium Ion Battery Market
Additives
Antiscalants/Scale Inhibitors Market
Additives
Polyols and Sorbitols Products Market
Additives
Cold Flow Improvers Market
Additives
Maltitol Based on Corn Starch Market
Additives
PVC Plasticizers and Stabilizers Market
Additives
Global Acidulants Market
Additives
Glycyrrhizic Acid Glycosides Market
Additives
Low VOC Coating Additives Market
Additives
Anti Crystallizing Agents Market
Additives
Sodium Benzoate Market
Additives
Polymeric Plasticizer Market
Additives
Biofuel Additives Market
Additives
Anti-Redeposition Polymer Additives for Short-Wash Cycles Market
Additives
United States Citric Acid Market