
 North and Latin America Weatherization Services Market | 2026-2036
North and Latin America Weatherization Services Market Size, Share, and Industry Trends Forecast 2026-2036
North and Latin America Weatherization Services Market Analytics
Spray foam insulation is displacing traditional fiberglass batts across commercial retrofit applications and is realigning material cost structures for regional contractors. TopBuild Corp leverages its national distribution network to sustain pricing advantages in the southeastern United States. Installed Building Products anchors its competitive position through specialized labor training programs that reduce installation variability. Builders FirstSource differentiates by controlling upstream sourcing of weatherization materials across its branch network.
Weatherization services encompass building envelope assessment, thermal barrier installation, air infiltration mitigation, and moisture control interventions designed to reduce HVAC load and energy consumption. These services typically target achieving specified R-values, ACH50 airtightness thresholds, and thermal bridging elimination to meet regional energy codes. Insulation services currently dominate revenue within the service type dimension, while air sealing represents the fastest-expanding category as blower-door testing becomes standard pre-retrofit protocol. The funding model segment shows utility incentives capturing disproportionate margin pools as ratepayer-funded programs expand eligibility criteria across state jurisdictions.
The EPA administers WAP (Weatherization Assistance Program) income-eligibility standards that shape contractor participation requirements across U.S. states. Health Canada enforces the EnerGuide rating system and National Building Code energy efficiency provisions that dictate retrofit specifications for Canadian properties. Mexico's CONUEE (National Commission for the Efficient Use of Energy) implements building energy certification that creates compliance-driven demand in industrial zones. Stakeholders must monitor how evolving federal funding allocations interact with state-level implementation timelines to capture program-driven project pipelines.
Market Dynamics
Spray foam insulation technology is compressing installation timelines and reshaping contractor capability requirements across commercial retrofit segments. The Inflation Reduction Act's residential efficiency tax credits are accelerating certification demands throughout the service chain.
Growth Catalysts
- IRA Tax Credits:The Inflation Reduction Act's residential efficiency incentives are expanding household eligibility for weatherization subsidies across U.S. states. Contractors are scaling training programs to capture this program-driven demand.
- Maquiladora Retrofits:Industrial facilities in Mexico's northern corridor are retrofitting aging building envelopes to meet cross-border energy compliance standards. CONUEE certification requirements are mandating thermal barrier upgrades.
- Blower-Door Protocol Standardization:Air sealing is displacing insulation as the default entry service as ACH50 testing becomes mandatory pre-retrofit. This protocol shift is expanding project scopes and contractor revenue per job.
Market Restraints
- Polyurethane Feedstock Volatility:Spray foam raw material costs fluctuate with petrochemical pricing, squeezing contractor margins on fixed-bid commercial projects. Regional distributors struggle to pass through cost swings.
- Certified Installer Scarcity:The pool of technicians qualified for ENERGY STAR-compliant air sealing remains concentrated in southeastern U.S. metropolitan areas. Rural markets face 6-12 week project backlogs.
- Utility Incentive Fragmentation:Ratepayer-funded program eligibility criteria vary across state jurisdictions, forcing contractors to maintain multiple compliance workflows. This administrative burden favors larger regional players.
Strategic Opportunities
- Multi-Family Housing Penetration:Southern U.S. apartment complexes represent underpenetrated demand for comprehensive weatherization packages. Property managers are bundling energy upgrades with HVAC replacement cycles.
- Building-Integrated Photovoltaics Convergence:Weatherization contractors are partnering with solar installers to deliver combined envelope-and-generation retrofits. This service bundling captures whole-building energy compliance budgets.
- Canadian EnerGuide Deep Retrofits:Health Canada's rating system revisions are creating demand for thermal bridging elimination in existing housing stock. Contractors with blower-door certification are entering this adjacent market.
Industry Challenges
- Diagnostic Technician Shortage:Qualified thermographers and blower-door operators command wage premiums that erode project economics. Training pipelines have not kept pace with protocol standardization.
- Moisture Control Integration:Contractors struggle to coordinate vapor barrier installation with existing HVAC ductwork in humid southern climates. Callback rates spike where envelope and mechanical trades remain siloed.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North and Latin America Weatherization Services Market |
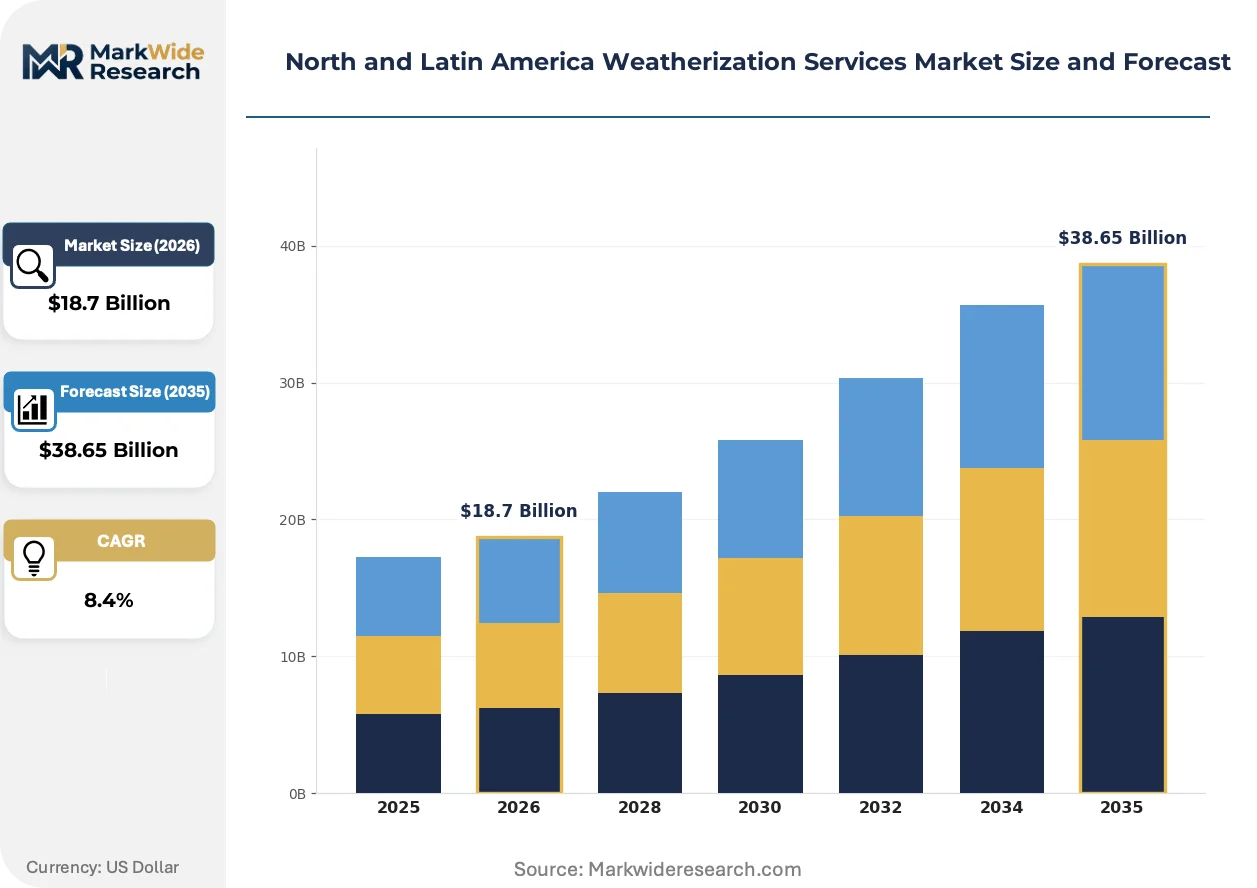
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Energy Audits, Insulation Services, Air Sealing, Window Installation Building Type: Residential, Commercial, Industrial, Multi-Family Project Size: Small Scale, Medium Scale, Large Scale, Retrofit Funding Model: Government Grants, Private Investment, Utility Incentives, Out-of-Pocket |
| Companies Covered | TopBuild Corp, Installed Building Products, Inc., Builders FirstSource, Inc., HomeWorks Energy, Inc., Dyson Energy Services Ltd, USA Insulation, Banker Insulation, Anderson Insulation, Tripolymer Inc., Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North and Latin America Weatherization Services Market Evolving Landscape
Digital diagnostic tools and prefabricated insulation systems are compressing project timelines and reshaping contractor labor models. Material science advances are enabling thinner thermal barriers with equivalent R-values.
Hybrid spray-foam systems combining open-cell and closed-cell layers in single application passes are modularizing retrofit workflows for multi-family housing projects. Property managers in Texas and Florida are specifying these systems to minimize tenant displacement. The technology is modularizing contractor crew structures by reducing specialized trade coordination.
EPA's ENERGY STAR certification requirements are tightening blower-door testing protocols for residential retrofits. Contractors must now achieve 15% tighter ACH50 thresholds to qualify for program incentives. The southeastern United States is responding fastest, with Georgia and North Carolina contractors investing in automated air-sealing equipment.
Building owners are unbundling weatherization from general maintenance contracts and awarding discrete envelope projects to certified specialists. Multi-family housing operators are leading this procurement shift, using utility incentive eligibility as vendor selection criteria. Mexico's industrial corridor shows similar patterns as maquiladora facilities separate energy compliance from facilities management.
North and Latin America Weatherization Services Market Segmentation
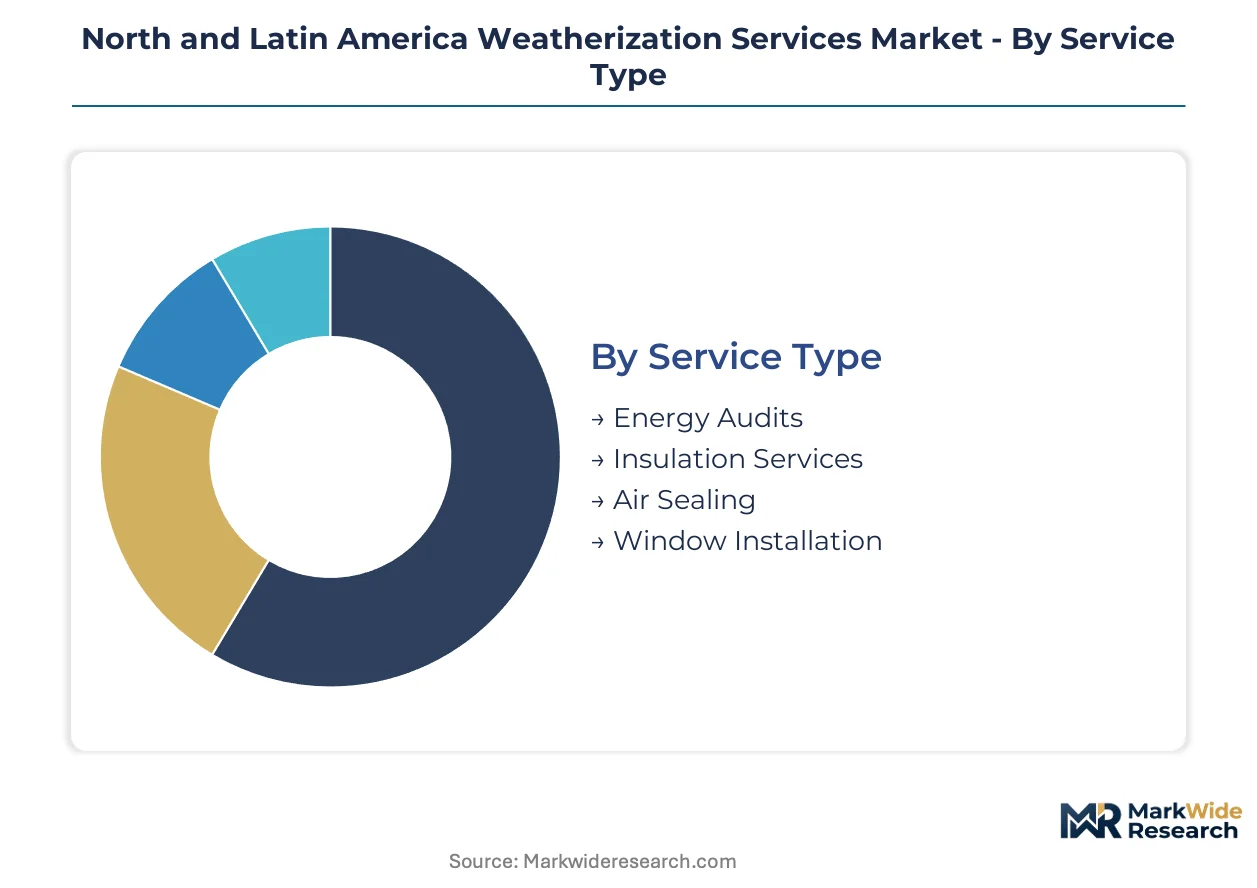
Weatherization contractors configure their equipment fleets and labor certifications around distinct service categories. Segmentation reveals where capital deployment concentrates and which project types generate recurring revenue streams across North and Latin America.
Service Type:
Capital intensity varies sharply across these services, with insulation requiring the heaviest equipment investment and air sealing demanding specialized diagnostic instrumentation.
- Insulation Services:Spray foam rigs and blower-door systems represent the largest fixed-asset category for regional contractors. Demand clusters in Texas and Florida multi-family retrofits where R-value upgrades trigger IRA tax credit eligibility. Polyurethane feedstock volatility squeezes margins on fixed-bid commercial work.
- Air Sealing:Thermographic cameras and automated sealing equipment require moderate capital outlay but command technician wage premiums. The southeastern United States shows fastest adoption as Georgia and North Carolina contractors invest in ACH50 compliance infrastructure. EPA ENERGY STAR protocol tightening is expanding project scopes.
- Energy Audits:Diagnostic software and blower-door kits form the entry-level capital threshold for contractor market entry. Health Canada EnerGuide assessments in Ontario and Quebec create cross-border certification demand.
- Window Installation:Crew scaling and logistics coordination dominate capital allocation rather than specialized machinery. Mexico's northern industrial corridor shows rising specification of high-performance glazing for maquiladora energy compliance.
Most installed capacity flows through Insulation Services. Expansion is steepest in Air Sealing.
Building Type:
Customer acquisition costs and project repeatability diverge significantly across these segments, shaping contractor marketing spend and crew specialization.
- Multi-Family:Property managers bundle envelope upgrades with HVAC replacement cycles across southern U.S. apartment complexes. Scale economies allow standardized material procurement and compressed mobilization costs per unit.
- Industrial:Maquiladora facilities in Mexico's northern corridor retrofit aging envelopes to meet CONUEE certification and cross-border energy standards. Single projects absorb substantial crew capacity but generate limited repeat business.
- Residential:Single-family retrofits dominate absolute project volume but suffer from customer education burdens and fragmented demand across suburban geographies. IRA residential efficiency tax credits are concentrating contractor marketing spend here.
- Commercial:Office and retail properties show procurement unbundling from general maintenance contracts, with utility incentive eligibility driving vendor selection. Blower-door protocol standardization is slower to penetrate this segment.
Project volume concentrates in Residential. Margin expansion is strongest in Multi-Family.
Project Size:
Crew structure and equipment utilization rates vary with project scale, determining contractor bidding strategies and backlog management.
- Retrofit:Existing building envelope upgrades dominate contractor revenue across North America. Diagnostic-driven scopes and phased execution accommodate occupied structures, extending project timelines but reducing customer disruption premiums.
- Large Scale:Industrial and multi-family complexes require coordinated trade management and extended mobilization periods. Mexico's northern corridor maquiladora projects exemplify this category's capital and coordination demands.
- Medium Scale:Small commercial and multi-family properties balance crew efficiency against administrative overhead. Utility incentive program eligibility thresholds often segment this category from smaller projects.
- Small Scale:Single-family residential work fills crew gaps between larger contracts but suffers from disproportionate travel and setup costs. Rural southeastern U.S. markets face backlogs due to certified installer scarcity.
Revenue generation tilts toward Retrofit. Capacity addition is fastest in Large Scale.
Funding Model:
Cash flow timing and customer credit risk profiles differ markedly across these mechanisms, influencing contractor working capital requirements.
- Utility Incentives:Ratepayer-funded programs capture disproportionate margin pools as eligibility criteria expand across U.S. state jurisdictions. Administrative fragmentation forces contractors to maintain multiple compliance workflows, favoring larger regional players.
- Government Grants:EPA WAP income-eligibility standards shape contractor participation requirements and project pipeline predictability. Federal funding allocation timing creates boom-bust cycles in program-dependent markets.
- Out-of-Pocket:Direct customer payment eliminates reimbursement delays but requires substantial marketing investment and financing partnerships. IRA tax credit complexity is extending sales cycles in this segment.
- Private Investment:Energy service companies and property aggregators deploy capital for guaranteed savings contracts. Scale requirements exclude smaller contractors from this procurement channel.
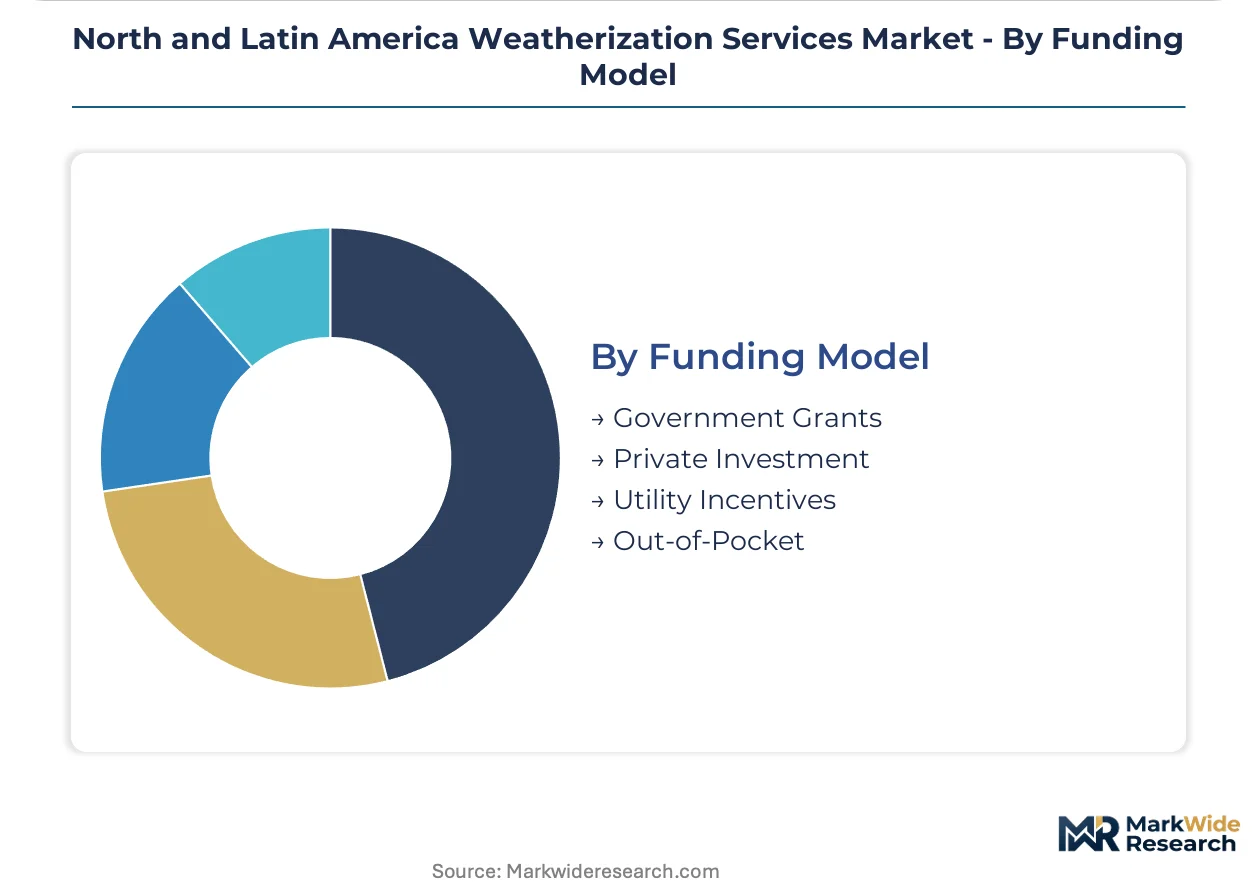
Transaction volume concentrates in Utility Incentives. Growth acceleration is sharpest in Government Grants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico's northern industrial corridor anchors weatherization demand across North and Latin America, with maquiladora facilities driving envelope retrofit volumes to meet cross-border energy compliance standards.
United States
The southeastern states concentrate contractor capacity expansion, with Georgia and North Carolina crews investing in automated air-sealing equipment. EPA's ENERGY STAR certification tightening to 15% tighter ACH50 thresholds is reshaping project scopes. Dallas-Fort Worth and Houston multi-family housing complexes are bundling envelope upgrades with HVAC replacement cycles at scale.
Canada
Ontario and Quebec residential retrofits are accelerating under Health Canada's EnerGuide rating system revisions. The National Building Code energy efficiency provisions are mandating thermal bridging elimination in existing housing stock. Toronto and Montreal contractors with blower-door certification are capturing deep retrofit demand from single-family homeowners.
Mexico
CONUEE building energy certification is mandating thermal barrier upgrades across industrial facilities. The northern border states of Nuevo León and Chihuahua host concentrated maquiladora retrofit activity. Monterrey industrial parks are separating energy compliance procurement from facilities management contracts.
Brazil
São Paulo commercial property managers are unbundling weatherization from general maintenance agreements. ANVISA-adjacent energy efficiency protocols in pharmaceutical manufacturing facilities are creating specialized envelope compliance demand. The São Paulo metro corridor leads certification-driven contractor selection.
North and Latin America Weatherization Services Market Competitive Landscape
Global majors compete with regional champions across distribution network coverage and labor certification depth. The market structure tilts toward scale advantages in material procurement and program eligibility navigation. Three archetypes dominate: national distributors controlling upstream sourcing, specialized installers with certified technician pipelines, and integrated service providers bundling diagnostics with execution. Consolidation pressure is intensifying through distributor-branch acquisitions and cross-regional labor training partnerships.
Within the national distribution tier, TopBuild Corp and Builders FirstSource, Inc. occupy positions defined by branch network density and captive material sourcing. Installed Building Products, Inc. exemplifies the specialized installation archetype, with workforce development programs reducing field variability. These three entities collectively represent the competitive spectrum from supply-chain control through execution standardization.
| Leading Market Players |
|---|
| TopBuild Corp |
| Installed Building Products, Inc. |
| Builders FirstSource, Inc. |
| HomeWorks Energy, Inc. |
| Dyson Energy Services Ltd |
| USA Insulation |
| Banker Insulation |
| Anderson Insulation |
| Tripolymer Inc. |
| Others |
Value Network & Pricing Analysis
EPA ENERGY STAR certification mandates gate both qualified contractor supply and premium-tier pricing access across the North and Latin America weatherization services market, compressing margins for uncertified operators while rewarding technicians with blower-door credentials.
Pricing Analysis
Polyurethane feedstock volatility passes through to project bids unevenly across contractor tiers. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified crews from basic insulation installers from uncertified labor pools. Cost compression in the economy tier is intensifying because rural southeastern markets face 6-12 week backlogs from certified installer scarcity. Single-family residential buyers exhibit highest price sensitivity, while maquiladora facilities in Mexico's northern corridor prioritize compliance over unit cost.
Supply Chain Analysis
Regional distribution centers in Texas, Florida, and Georgia anchor hub-and-spoke patterns for spray foam rigs and blower-door equipment. Raw material flows draw from U.S. Gulf Coast petrochemical producers, Canadian resin suppliers, and Mexican manufacturing inputs. Single-source vulnerability concentrates in polyurethane precursor supply during feedstock allocation cycles. Distribution runs through national distributors with captive branch networks and specialized installer procurement channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North and Latin America weatherization services market functions as a stable compounder, with IRA residential efficiency tax credits embedding recurring demand through decade-long incentive windows.
For Market Incumbents: Anticipate spray foam technology displacement of fiberglass batts by securing exclusive distribution agreements with polyurethane suppliers and investing in automated air-sealing equipment before EPA protocol tightening accelerates. Certification depth serves as the priority lever against emerging regional specialists with shallower program eligibility expertise. For New Entrants and Emerging Players: Rural multi-family property managers in the southeastern United States represent an underserved buyer archetype with compressed customer acquisition costs and bundled HVAC replacement cycles. CONUEE-driven maquiladora retrofits in Chihuahua and Nuevo León offer the most penetrable geography for cross-border compliance specialization. Lead with utility incentive navigation as the core go-to-market angle. For Investors and Strategic Acquirers: Roll-up economics work for regional specialists with certified technician pipelines because program eligibility fragmentation across state jurisdictions favors scaled compliance infrastructure. The five-to-ten-year viability window rests on IRA funding continuity and CONUEE enforcement intensity. Target contractors with blower-door certification density in Georgia and North Carolina. Watch federal WAP allocation timing as the inflection indicator for program-dependent revenue streams.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | EPA ENERGY STAR blower-door credentials unlock premium-tier project eligibility and IRA tax credit access. |
| Backward Integration | Captive polyurethane sourcing insulates margins from feedstock volatility in fixed-bid commercial work. |
| Geographic Expansion | Canadian EnerGuide deep retrofits in Ontario and Quebec extend certified crew utilization across seasonal demand cycles. |
| Technology Licensing | Hybrid spray-foam systems reduce tenant displacement in Texas and Florida multi-family properties. |
| Joint Venture | Solar installer partnerships capture whole-building energy compliance budgets through envelope-and-generation bundling. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with weatherization contractors, utility program administrators, property management executives, and CONUEE compliance officers with secondary validation from EPA WAP filings, Health Canada EnerGuide databases, U.S. EIA state energy profiles, and utility incentive program records. Bottom-up project pipeline estimates triangulated against top-down regional construction spending data.
Segment-weighting approaches distributed volume and value across service type, building category, project scale, and funding model dimensions throughout the forecast period. CAGRs derived from fitted growth curves applied to utility incentive expansion trajectories, IRA tax credit uptake curves, and maquiladora retrofit compliance deadlines. Forecast inputs incorporated polyurethane feedstock price indices and certified technician training pipeline data.
Inputs from EPA program filings and utility ratepayer-funded program administrators were available through the study window; gaps in real-time CONUEE enforcement intensity and state-level WAP allocation timing introduce uncertainty bands around Mexico and government grant segment projections. Forecasts reflect documented assumptions regarding IRA continuity and petrochemical supply stability. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Services
North America Fire Sprinkler Systems Market
Construction Services
Heavy Equipment Training Simulator Market
Construction Services
Work Order Management Market
Construction Services
Middle East and Africa Industrial Maintenance Services in Operational Improvement and Operational Maintenance Market
Construction Services
Facade Cleaning and Maintenance Service Market
Construction Services
Remote Construction Market
Construction Services
Grease Trap Service Market
Construction Services
Construction Equipment Repair and Maintenance Services Market
Construction Services
Global Industrial Services Market
Construction Services
North America Testing and Commissioning Market
Construction Services
Dust Suppression Control Market
Construction Services
Testing, Inspection, and Certification for Construction Market
Construction Services
Industrial Maintenance Services Market
Construction Services
NDT and Inspection Market
Construction Services
Excavating Contractor Market
Construction Services
Global Pipeline Maintenance Services Market