
 Industrial Kiln Market | 2026-2036
Industrial Kiln Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Kiln Market Insights
ISO 14001 certification is reorganizing supplier eligibility across the industrial kiln sector, pushing smaller fabricators toward environmental management investments or exit. FLSmidth leverages its cement kiln heritage to dominate large rotary installations in emerging markets. Nabertherm sustains engineering density in precision thermal processing for European ceramics and laboratory applications. Nutec Bickley anchors North American demand through heavy industrial furnace integration for steel and aluminum heat treatment.
An industrial kiln is a thermally insulated chamber engineered to sustain controlled temperatures exceeding 1,000°C for material transformation through calcination, sintering, or vitrification. Rotary kilns constitute the dominant product category by installed value, reflecting their indispensability in clinker production where continuous throughput and fuel flexibility determine operational economics. Tunnel kilns represent the fastest-expanding segment structurally, driven by ceramics manufacturers seeking uniform firing profiles and reduced thermal cycling losses in high-volume sanitary ware and tile operations. Natural gas retains primacy in fuel type segmentation across OECD markets, though biomass conversions are accelerating where carbon pricing mechanisms intensify operating cost differentials.
EPA emissions standards in the United States and EU ETS carbon pricing under the EU Green Deal are reshaping kiln fuel economics and refractory specifications across OECD manufacturing bases. China's MEE enforces increasingly stringent particulate and NOx limits that compel domestic producers toward electric and hybrid combustion architectures. Stakeholders must monitor regulatory divergence between carbon-border-adjustment regimes and local air-quality mandates to anticipate where capital deployment for kiln modernization will yield protected returns.
Market Dynamics
Dual carbon mandates from Beijing and Brussels are compressing the payback period for electric kiln retrofits while cement overcapacity in China redirects vendor attention toward India and Southeast Asian infrastructure buildouts.
Growth Catalysts
- EU ETS carbon pricing:German and Polish cement producers accelerate fuel-switching investments to avoid escalating permit costs, triggering rotary kiln modernization cycles.
- Sanitary ware demand:Indian ceramics manufacturers expand tunnel kiln deployments to serve housing infrastructure targets under the country's urban mission programs.
- Biomass co-firing:Nordic pulp and paper integrated producers retrofit lime kilns for forest residue combustion, cutting fossil exposure under national carbon neutrality frameworks.
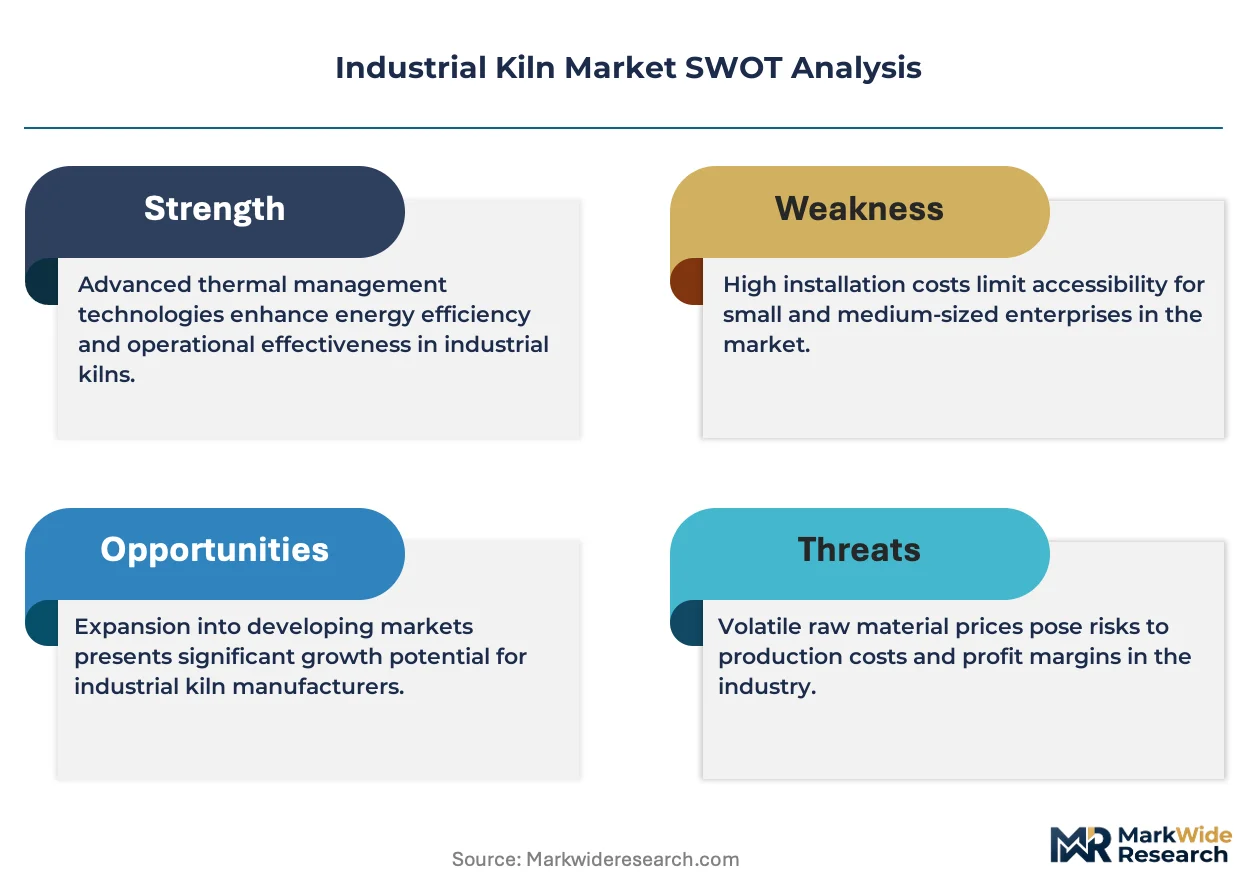
Market Restraints
- Refractory supply concentration:High-purity magnesia for kiln linings concentrates in Chinese state-controlled mining zones, exposing European fabricators to export quota volatility.
- Natural gas price spreads:CCGT-linked kiln operations in Germany and Italy face margin compression when TTF benchmarks disconnect from long-term supply contracts.
- Clinker substitution:Supplementary cementitious materials from steel slag and fly ash displace calcination demand in blended cement formulations.
Strategic Opportunities
- Vietnam infrastructure corridor:Northern provinces from Hai Phong to Quang Ninh attract greenfield cement capacity where domestic kiln engineering lags demand.
- Hydrogen combustion pilots:Dutch industrial clusters test H2-fired rotary kilns under national hydrogen roadmap subsidies, creating reference architectures for carbon-border-adjusted exports.
- Digital twin integration:AI-driven thermal modeling converges with IoT sensor networks to enable predictive refractory maintenance contracts.
Industry Challenges
- Refractory installation specialization:Shortage of certified bricklayers for hot kiln relining compresses turnaround windows and extends unplanned downtime.
- Legacy DCS integration:Brownfield sites running 1990s distributed control systems face protocol incompatibilities with modern emissions monitoring and fuel optimization modules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Kiln Market |
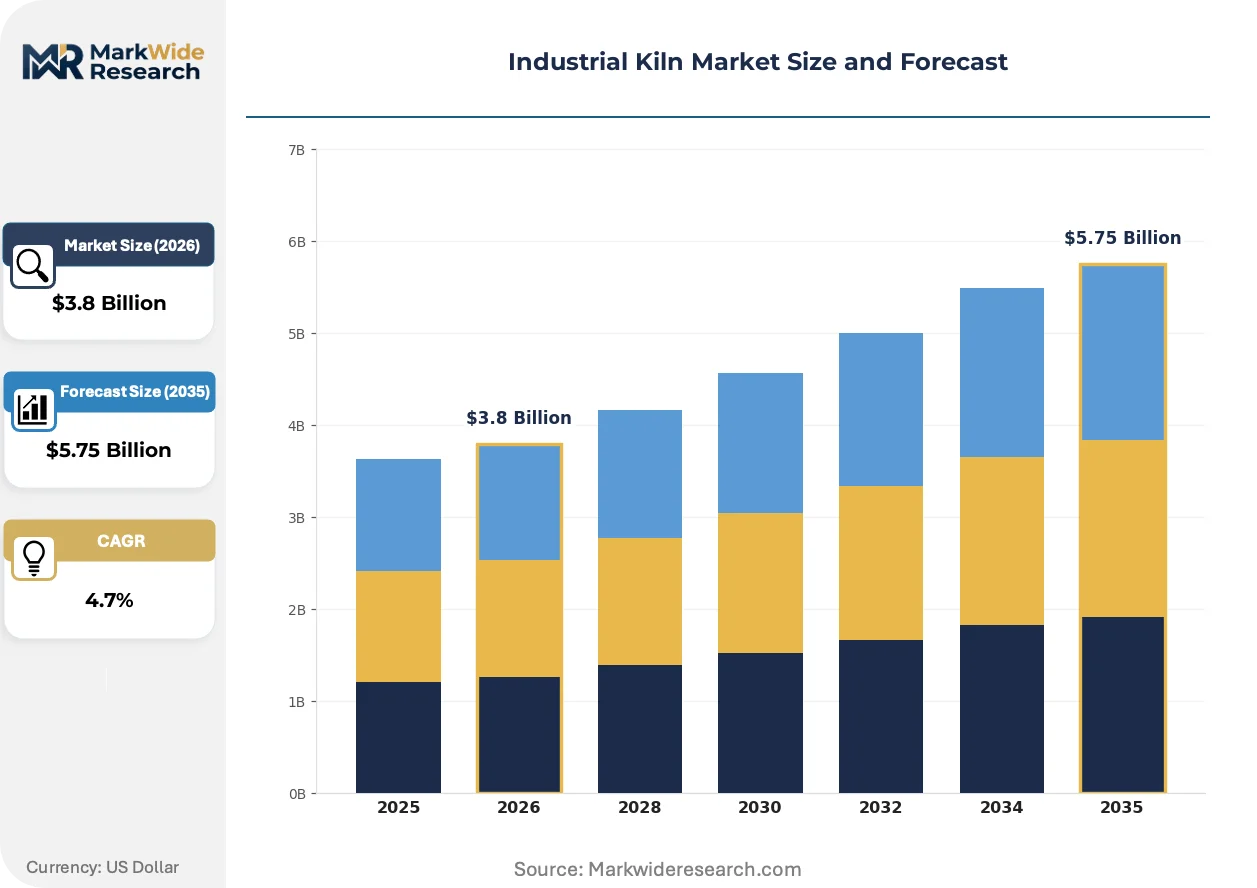
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rotary Kilns, Tunnel Kilns, Shuttle Kilns, Continuous Kilns, Batch Kilns Fuel Type: Natural Gas, Coal, Electricity, Oil, Biomass Application: Cement Production, Metallurgical Processing, Ceramics Manufacturing, Waste Treatment, Chemical Processing End User: Cement Plants, Metal Fabricators, Ceramic Producers, Environmental Agencies, Chemical Factories |
| Companies Covered | FLSmidth, Nabertherm, CM Furnaces, Nutec Bickley, L&L Special Furnace, Paragon Industries, Therser, Tetlow Kilns and Furnaces, Wellons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Kiln Market Trends and Innovations
Electrification of thermal processes is intersecting with digital process control to reconfigure kiln economics across energy-intensive manufacturing verticals.
Plasma-assisted ignition systems are displacing conventional fuel-oil preheating in cement rotary kilns. Mexican and Turkish cement groups pilot these installations to eliminate startup emissions spikes. The technology is displacing multi-hour thermal ramp cycles, cutting fuel waste and permitting frequency under local air quality enforcement.
China's MEE enforcement of GB 4915-2013 particulate and NOx limits tightens annually, forcing domestic producers toward SNCR-SCR hybrid architectures. Compliance costs now exceed 8% of kiln CAPEX for retrofits in Shandong and Hebei provinces. Smaller independents without captive technical teams outsource operations to environmental service platforms, fragmenting the traditional integrated kiln supply model.
Performance-based refractory contracting is compressing traditional spare-parts procurement. Brazilian and Indonesian cement groups now pay per ton of clinker produced rather than purchasing bricks outright. This transfers refractory risk to suppliers, concentrating procurement authority among three global service platforms and squeezing regional distributors from the value chain.
Industrial Kiln Market Segmentation
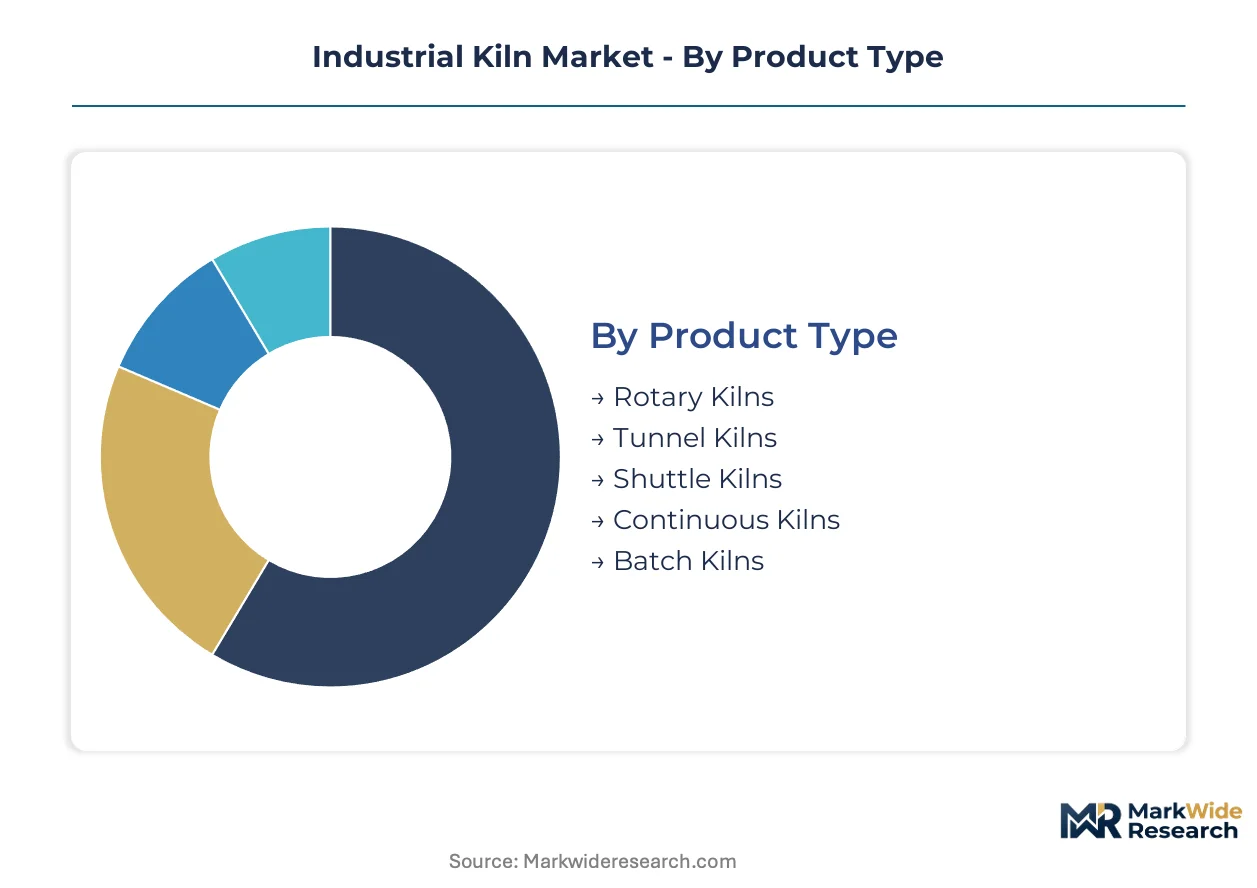
Kiln procurement channels diverge sharply by segment scale and technical complexity. Large rotary installations flow through engineering-procurement-construction consortia, while precision batch units distribute through regional equipment dealers.
Product Type:
Channel economics split between project-based EPC contracting for heavy rotary units and distributor networks for standardized thermal equipment.
- Rotary Kilns:Cylindrical refractory-lined vessels rotating on trunnion bearings to enable continuous material tumbling through temperature gradients. Cement producers in India and Vietnam deploy these for clinker calcination where hourly throughput determines plant economics.
- Tunnel Kilns:Linear chambers with automated car systems moving product through controlled firing zones. Sanitary ware manufacturers in Morbi, India favor these for uniform thermal profiles that reduce defect rates in high-volume tile production.
- Shuttle Kilns:Intermittent firing chambers with movable car platforms serving specialty ceramics producers.
- Continuous Kilns:Non-stop thermal processing architecture for brick and heavy clay manufacturers.
- Batch Kilns:Cyclic operation chambers for laboratory and artisan ceramic applications.
Rotary kilns dominate installed base. Tunnel kilns are where expansion concentrates.
Fuel Type:
Energy sourcing strategies track carbon pricing exposure and feedstock availability across manufacturing geographies.
- Natural Gas:Clean combustion profile with precise temperature control through modulated burner staging. German cement producers under EU ETS pressure accelerate conversions from coal to gas to reduce permit exposure.
- Electricity:Resistance and induction heating architectures eliminating on-site combustion emissions. Dutch industrial clusters pilot grid-powered rotary designs under national hydrogen roadmap subsidies.
- Coal:Lowest fuel cost for captive mine operations in emerging markets.
- Oil:Backup fuel for ignition and emergency operation in multi-fuel installations.
- Biomass:Forest residue and agricultural waste combustion for pulp-integrated lime kilns in Nordic markets.
Natural gas retains primacy in OECD procurement. Electricity is gaining share fastest where carbon border adjustments intensify.
Application:
End-use concentration determines refractory specification, emissions control investment, and maintenance contracting models.
- Cement Production:Clinker calcination at 1,450°C requiring alkali-resistant refractory linings and SNCR-SCR hybrid architectures. Chinese producers in Shandong province face MEE enforcement driving 8%-plus CAPEX compliance burdens.
- Metallurgical Processing:Heat treatment and sintering for ferrous and non-ferrous metals. Steel fabricators in Germany's Ruhr region retrofit tunnel designs for aluminum billet homogenization.
- Ceramics Manufacturing:Vitrification of sanitary ware, tableware, and technical ceramics.
- Waste Treatment:Hazardous material destruction and medical waste incineration.
- Chemical Processing:Calcination of specialty minerals and catalyst activation.
Cement production anchors global kiln demand. Ceramics manufacturing shows steepest expansion trajectory in urbanizing Asian markets.
End User:
Customer scale and technical capability shape procurement authority and service contracting structures.
- Cement Plants:Integrated producers with captive engineering teams managing multi-kiln complexes. Indian infrastructure buildouts drive greenfield capacity where domestic fabrication lags demand.
- Metal Fabricators:Heat treatment shops and foundries requiring precision temperature uniformity. Aluminum extruders in Mexico's Bajio automotive corridor expand batch and continuous furnace deployments.
- Ceramic Producers:Tile, sanitary ware, and refractory manufacturers with varying automation levels.
- Environmental Agencies:Municipal and hazardous waste destruction facilities under tightening emissions mandates.
- Chemical Factories:Specialty mineral processors with custom thermal profile requirements.
Cement plants command largest unit scale. Metal fabricators are where technology refresh concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cement producers and ceramics manufacturers concentrate procurement authority across five national markets where infrastructure buildouts and emissions retrofit cycles overlap.
China
Clinker overcapacity in Shandong and Hebei provinces redirects vendor attention toward environmental compliance retrofits under MEE enforcement of GB 4915-2013 standards. Domestic producers face CAPEX burdens exceeding eight percent of kiln investment for SNCR-SCR hybrid architectures. Smaller independents in the Yangtze River Delta outsource operations to environmental service platforms.
India
Housing infrastructure targets under urban mission programs drive tunnel kiln deployments for sanitary ware manufacturers in Morbi, Gujarat. Cement producers expand rotary capacity in northern states where domestic fabrication lags demand. BIS certification requirements reorganize supplier eligibility toward ISO 14001-compliant fabricators.
Germany
Ruhr region steel fabricators retrofit tunnel designs for aluminum billet homogenization while cement producers accelerate fuel-switching investments. EU ETS carbon pricing under the EU Green Deal compresses payback periods for electric kiln retrofits. Polish and German producers avoid escalating permit costs through rotary modernization cycles.
United States
EPA emissions standards reshape refractory specifications and fuel economics across OECD manufacturing bases. Mexican cement groups in the Bajio automotive corridor pilot plasma-assisted ignition systems to eliminate startup emissions spikes. Nutec Bickley anchors North American demand through heavy industrial furnace integration.
Vietnam
Northern provinces from Hai Phong to Quang Ninh attract greenfield cement capacity where domestic kiln engineering lags infrastructure corridor demand. Tunnel kiln adoption accelerates for ceramics serving ASEAN export markets. Biomass co-firing trials emerge where carbon pricing exposure intensifies through EU trade linkages.
Industrial Kiln Market Competitive Landscape
Player mix skews toward engineering-procurement-construction consortia for heavy rotary units alongside precision thermal specialists for batch applications. Market structure consolidates around three global service platforms controlling performance-based refractory contracting while regional distributors face procurement authority compression. Strategic archetypes span cement heritage multinationals, European precision engineering density, and North American heavy industrial integration. Competitive moves concentrate on geographic expansion into Vietnamese and Indian infrastructure corridors alongside digital twin integration for predictive maintenance contracts.
Within the cement heritage tier, FLSmidth leverages its rotary installation legacy to dominate large-scale deployments in emerging markets. Nabertherm exemplifies European precision engineering density through sustained focus on ceramics and laboratory thermal processing. Nutec Bickley anchors North American positioning through heavy industrial furnace integration for steel and aluminum heat treatment applications. These three fabricators occupy distinct competitive spaces without direct overlap in customer scale or technical specification.
| Leading Market Players |
|---|
| FLSmidth |
| Nabertherm |
| CM Furnaces |
| Nutec Bickley |
| L&L Special Furnace |
| Paragon Industries |
| Therser |
| Tetlow Kilns and Furnaces |
| Wellons |
| Others |
Pricing and Supply Chain Analysis
Rotary kiln capacity utilization above 85 percent in Indian cement corridors compresses per-unit fixed costs and enables aggressive project bidding that regional fabricators cannot match. This scale asymmetry concentrates procurement authority among three global service platforms while compressing margins for mid-tier suppliers dependent on spot refractory purchases.
Pricing Analysis
Cost-plus contracts indexed to TTF natural gas benchmarks and high-purity magnesia spot prices dominate rotary kiln procurement for cement producers under EU ETS pressure. Three-tier pricing structure across premium, standard, and economy levels separates ISO 14001-certified EPC consortia from regional distributors and used-equipment brokers. Pricing pressure stems from clinker substitution trends in blended cement formulations that displace calcination capacity. Cement plants with captive engineering teams exhibit lowest price sensitivity; independent ceramics manufacturers in Morbi negotiate hardest on tunnel kiln packages.
Supply Chain Analysis
Port congestion at Shanghai and Ningbo elevates inbound logistics costs for European refractory fabricators sourcing magnesia clinker from Liaoning province. High-purity magnesia concentrates in Chinese state-controlled mining zones; alumina-silica bricks draw from Indian bauxite corridors and German engineered ceramic feedstocks. Single-source vulnerability in magnesia supply exposes kiln lining contractors to export quota volatility. Distribution runs through engineering-procurement-construction consortia for heavy rotary units and regional equipment dealers for standardized batch kilns.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial kiln demand sits in early-cycle expansion as EU carbon border adjustments and China's dual carbon mandates force replacement investments ahead of natural depreciation schedules. Infrastructure buildouts in Vietnam and India extend the runway for capacity additions.
For Market Incumbents: Fortify refractory service platform control through performance-based contracting that transfers operational risk from cement producers. Deepen captive magnesia supply relationships in Liaoning to offset export quota volatility. Accelerate digital twin integration for predictive maintenance contracts that lock in multi-year service revenue. For New Entrants and Emerging Players: Lead with hydrogen combustion pilot partnerships in Dutch industrial clusters where national subsidy frameworks de-risk technology adoption. Target tunnel kiln deployments for Indian sanitary ware manufacturers in Morbi where domestic fabrication lags housing infrastructure targets. Pursue EPC subcontractor relationships with established cement heritage multinationals to bypass direct procurement authority barriers. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision thermal engineering specialists with ISO 14001 certification and ceramics segment exposure over commodity rotary fabricators facing clinker substitution headwinds. Long-term viability rests on digital service platform integration and refractory risk-transfer contracting capabilities. Watch EU ETS permit price trajectories as inflection indicator for fuel-switching retrofit acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnesia Supply | Liaoning mining zone partnerships insulate European fabricators from Chinese export quota volatility. |
| Digital Twin Platform Deployment | AI-driven thermal modeling enables predictive refractory maintenance contracts with cement producers. |
| Hydrogen Combustion Pilot Partnership | Dutch industrial cluster subsidies create reference architectures for carbon-border-adjusted kiln exports. |
| Tunnel Kiln Capacity Expansion | Morbi ceramics corridor deployments capture Indian housing infrastructure buildout demand. |
| Performance-Based Refractory Contracting | Per-ton clinker pricing transfers operational risk and concentrates procurement authority. |
Research Methodology
A spread of perspectives from cement plant engineering directors, refractory procurement managers, EPC consortium project leads, and aftermarket service heads converged on the working assumptions for kiln demand trajectories. Primary fieldwork combined structured interviews with secondary validation through customs trade data, EU ETS permit registries, SEC filings of publicly listed cement producers, and Chinese MEE emissions disclosure databases. Bottom-up unit deployment counts triangulated against top-down cement capacity expansion forecasts.
Segmentation dimensions modeled encompass kiln product type, fuel architecture, application vertical, end-user scale tier, and regional regulatory cluster across the projection horizon. CAGRs derived from installed base replacement cycles, greenfield capacity announcements, and emissions retrofit compliance deadlines. Industry-specific forecast inputs include clinker substitution rates in blended cement formulations and EU carbon border adjustment implementation timelines.
Forecasts assume regulatory continuity in EU ETS carbon pricing and China's MEE enforcement regimes; material policy shifts would require re-modeling. Refractory supply disruptions, natural price volatility, or accelerated hydrogen combustion adoption could revise trajectory assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
High Speed Steels Market
Industrial Materials
United States Engineering Plastics Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Industrial Seals Market
Industrial Materials
Metal Based Safety Gratings Market
Industrial Materials
Global Industrial Chain Market
Industrial Materials
Southeast Asia Industrial Flooring Market
Industrial Materials
Steel Bar Magnet Market
Industrial Materials
Ribbed Smoke Sheet Market
Industrial Materials
Industrial Brushes Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Industrial Strainers Market
Industrial Materials
Injection Mold Hot Runners Market
Industrial Materials
Paint Knife Market
Industrial Materials
Flat Scroll Spring Market