
 Mineral Wool Market | 2026-2036
Mineral Wool Market Size, Share, and Industry Trends Forecast 2026-2036
Mineral Wool Market Intelligence
Capital-intensity divergence between integrated slag processors and commodity glass wool producers is rotating competitive advantage toward upstream raw material control. Rockwool International A/S leverages volcanic rock sourcing networks across Scandinavia to sustain margin stability. Owens Corning anchors its position through captive glass fiber supply chains that dominate North American residential construction specifications.
Mineral wool comprises inorganic fibrous materials manufactured from molten rock, slag, or glass at temperatures exceeding 1,400°C, then spun into fibers and bound with phenolic or bio-based resins to achieve thermal conductivity values typically ranging from 0.030 to 0.045 W/m·K. The material primarily serves as non-combustible thermal and acoustic insulation in building envelopes, industrial equipment, and transportation systems where fire resistance ratings are mandatory. Stone wool occupies the premium tier in commercial and industrial applications where hydrophobicity and dimensional stability under load command price premiums. Glass wool competes aggressively in residential markets where cost sensitivity and ease of installation drive specification, while slag wool segments face raw material availability constraints tied to steel production cycles.
The EU Green Deal and REACH frameworks mandate progressive reductions in embodied carbon and formaldehyde emissions from insulation products, pushing manufacturers toward bio-based binder chemistries and recycled content verification. The EPA's Toxic Substances Control Act oversight and evolving OSHA permissible exposure limits for respirable crystalline silica shape workplace safety investments and product labeling requirements across American manufacturing facilities. Stakeholders must monitor regulatory divergence between European ecodesign requirements and American performance-based codes when configuring regional product portfolios and certification strategies.
Market Dynamics
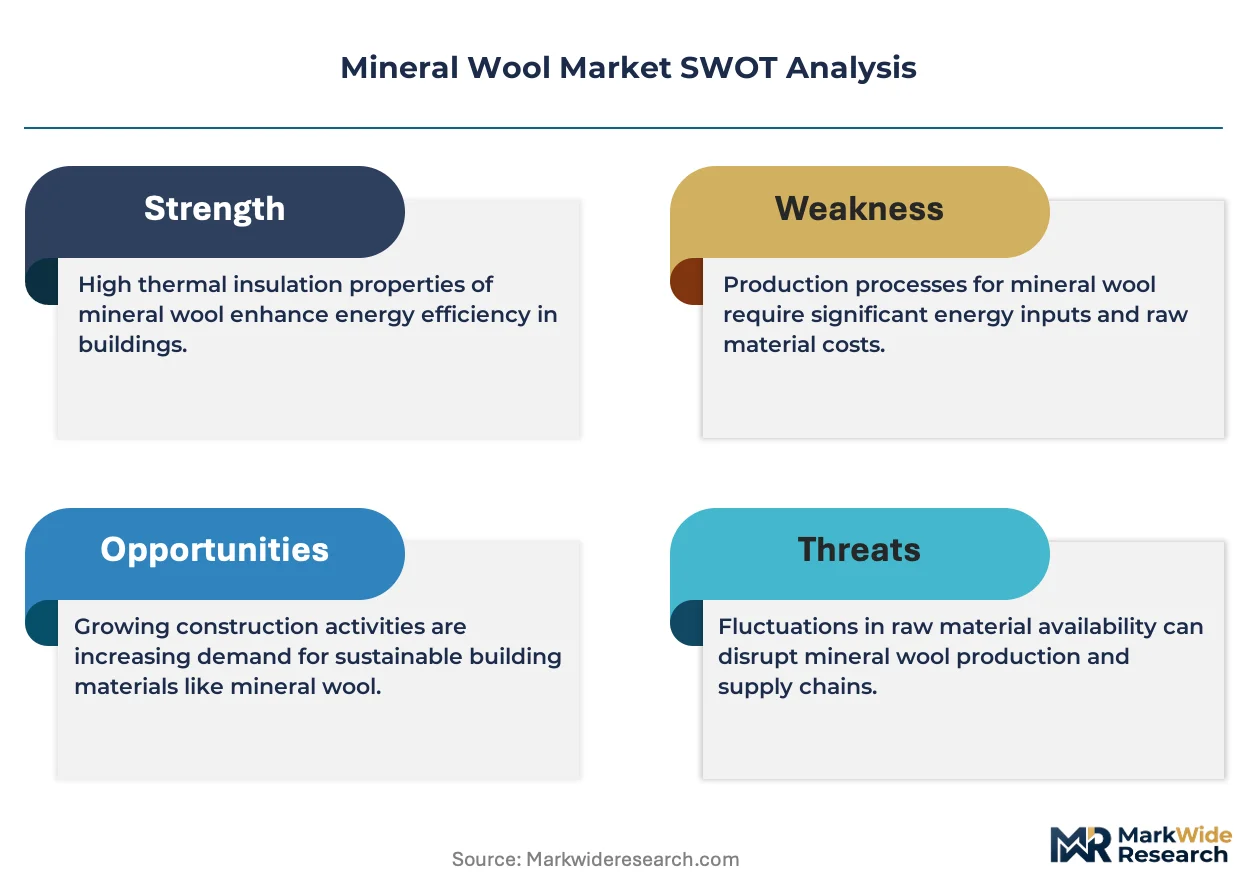
Building energy code stringency under the EU Green Deal and evolving ASHRAE standards are forcing specification upgrades across commercial envelopes, compressing demand toward high-performance stone wool while glass wool faces margin pressure from embodied carbon audits.
Growth Catalysts
- EU Green Deal thermal mandates:Progressive envelope performance requirements under the EU Green Deal are mandating non-combustible insulation in retrofit and new commercial construction across Germany, France, and the Netherlands.
- Industrial process intensity:Petrochemical corridor expansions along the US Gulf Coast are specifying stone wool for high-temperature equipment insulation where hydrophobicity and dimensional stability command specification premiums.
- Slag valorization networks:Integrated steel producers in Scandinavia are securing long-term slag supply agreements with mineral wool manufacturers, locking in raw material access for cost-competitive production.
Market Restraints
- Raw material cyclicality:Slag wool production depends on blast furnace output from steel manufacturing, tying capacity utilization to volatile steel production cycles in China and India.
- Respirable silica exposure limits:OSHA permissible exposure limits for respirable crystalline silica are elevating workplace safety investments and compliance costs across American manufacturing facilities.
- Formaldehyde emission scrutiny:REACH frameworks and evolving EPA Toxic Substances Control Act oversight are constraining traditional phenolic binder chemistries and requiring costly reformulation.
Strategic Opportunities
- Bio-based binder chemistry:Manufacturers developing formaldehyde-free bio-resin formulations can capture specification share in Nordic markets where environmental product declarations carry procurement weight.
- Data center thermal management:Hyperscale data center construction in Ireland and the Netherlands is creating demand for fire-rated acoustic insulation in mechanical infrastructure.
- Direct-to-contractor digital channels:Specialized distributors are launching digital specification platforms that bypass traditional merchant intermediaries in residential renovation markets.
Industry Challenges
- Furnace engineering talent scarcity:The specialized skill set required for cupola furnace operation and fiber spinning optimization is concentrating among aging workforces in traditional manufacturing regions.
- EPD verification timelines:Third-party verification of environmental product declarations for LEED and BREEAM compliance is extending sales cycles by 4-6 months in commercial specification markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mineral Wool Market |
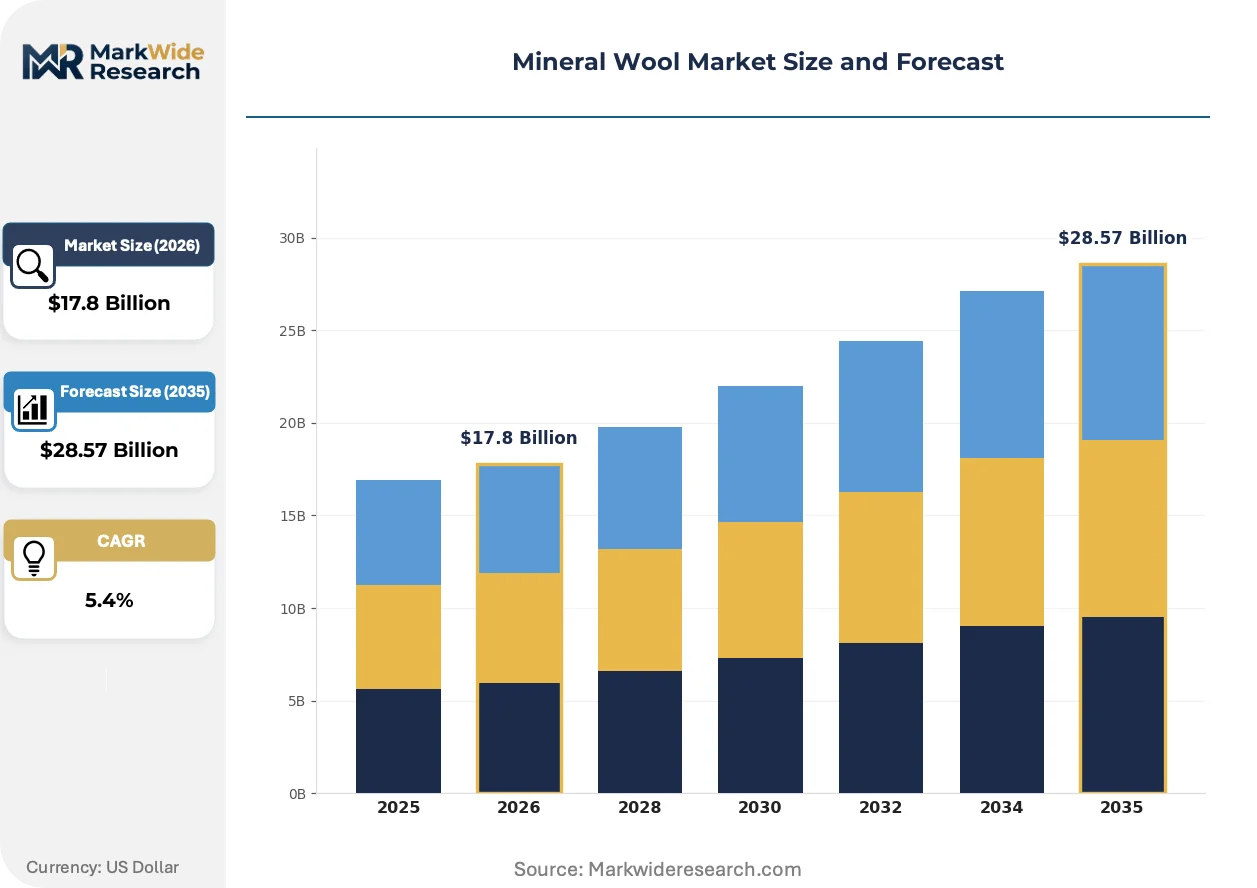
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $28.57 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Stone Wool, Glass Wool, Slag Wool, Others Application: Insulation, Acoustics, Fire Protection, Soundproofing End User: Construction, Automotive, Industrial, Marine Form: Board, Blanket, Pipe, Loose Fill |
| Companies Covered | Rockwool International A/S, Owens Corning, Saint-Gobain, Knauf Insulation, Johns Manville, Paroc Group, Isover, Kingspan Group, Armacell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mineral Wool Market Strategic Shifts & Innovations
Bio-based binder technologies and digital specification platforms are restructuring how mineral wool products reach end-users, while regulatory pressure on embodied carbon is compressing the viable chemistry set for conventional formulations.
Formaldehyde-free bio-resin formulations are decomposing the traditional phenolic binder dominance in premium specification segments. Commercial contractors in Germany and the Netherlands are mandating environmental product declarations that disqualify conventional chemistries. This transition is decomposing margin structures for commodity glass wool producers lacking reformulation capability.
REACH progressive restrictions on substance of very high concern classifications are forcing systematic chemical inventory audits across European manufacturing. The EU Green Deal's embodied carbon tracking requirements are extending downstream to insulation procurement in public infrastructure. Stone wool producers with verified recycled content and low-carbon process heat are capturing specification preference in Nordic commercial tendering.
Specification decisions are migrating from general contractors to envelope consultants and energy modelers who prioritize thermal bridging calculations over unit cost. This shift elevates technical documentation and simulation support as competitive differentiators. The Netherlands and Denmark exhibit the most advanced procurement sophistication, with model-driven specification now standard in commercial retrofit tendering.
Mineral Wool Market Segmentation
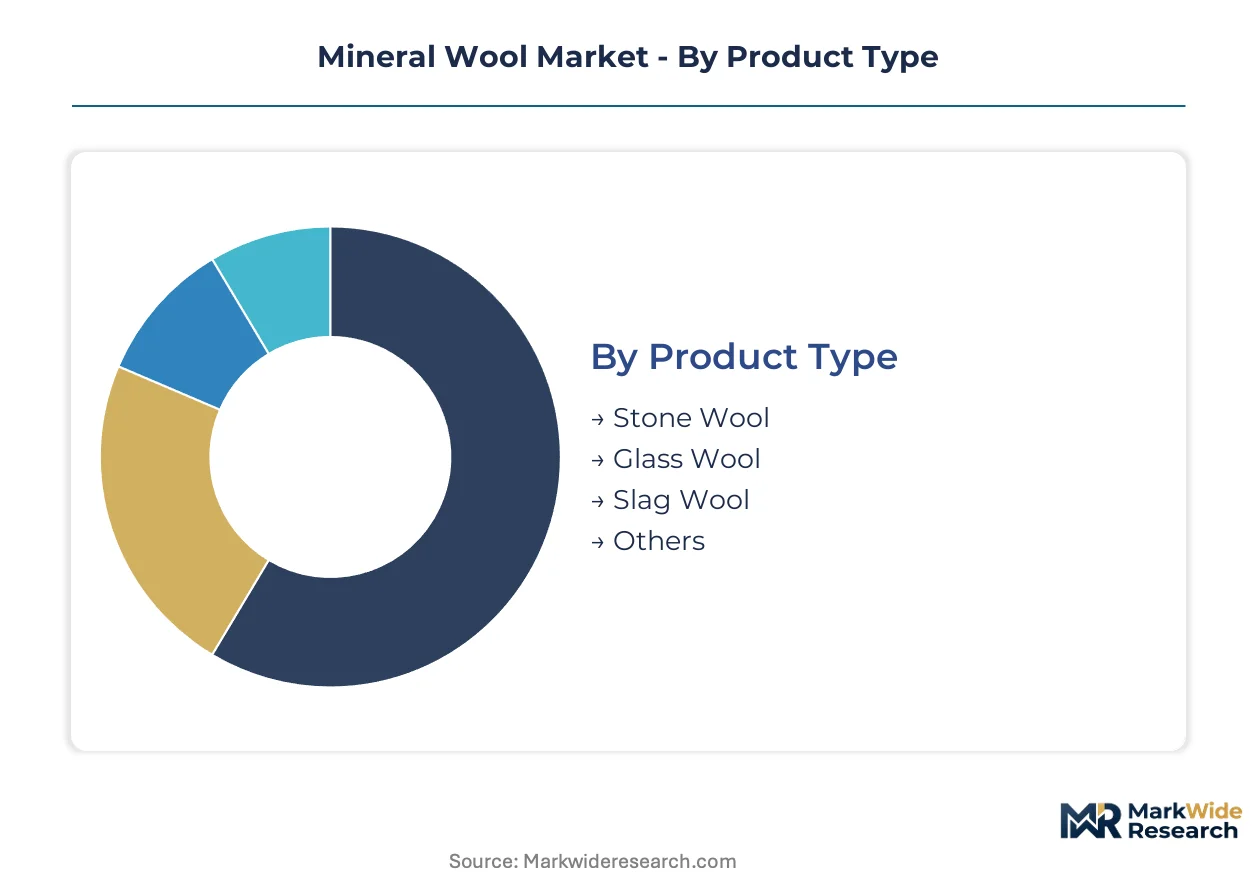
Segmentation in mineral wool reveals how substitution pressure from polymer foams and natural fibers reshapes competitive boundaries across chemistry, form factor, and end-use specification. Understanding where segments face displacement versus where they command irreplaceable performance premiums guides portfolio configuration and R&D prioritization.
Product Type:
Glass wool confronts the most acute substitution threat from spray polyurethane foam in residential attic applications, while stone wool's fire resistance ratings protect it from displacement in commercial envelopes.
- Stone Wool:Manufactured from molten basalt or diabase at temperatures exceeding 1,400°C, yielding fibers with superior compressive strength and hydrophobicity. Demand concentrates in Germany's commercial retrofit sector where the EU Green Deal mandates non-combustible envelope materials meeting stringent reaction-to-fire classifications.
- Glass Wool:Produced from recycled glass cullet and sand, offering lower thermal conductivity but reduced dimensional stability under mechanical load. North American residential construction specifications favor this chemistry for cost-sensitive batt insulation in wood-framed walls, though embodied carbon audits are eroding its specification share.
- Slag Wool:Derived from blast furnace slag co-production with steel manufacturing, creating supply vulnerability tied to volatile steel output cycles in China and India.
- Others:Specialty formulations including refractory ceramic fibers for extreme temperature industrial applications above 1,000°C operating environments.
Stone wool retains volume leadership; glass wool holds the steepest expansion curve as residential renovation activity accelerates in cost-sensitive markets.
Application:
Cost tier stratification separates specification-grade fire protection systems from commodity thermal insulation where price-per-R-value dominates procurement.
- Insulation:Thermal envelope applications in commercial and residential buildings, representing the foundational demand driver across all product chemistries and geographies.
- Acoustics:Sound absorption in commercial interiors, transportation infrastructure, and mechanical equipment enclosures where NRC ratings determine specification.
- Fire Protection:Passive fire stopping in compartmentation systems, structural steel protection, and penetration sealing where EI ratings are legally mandated and product substitution is severely restricted.
- Soundproofing:High-density boards and mats for home theaters, recording studios, and luxury residential applications where STC improvement justifies material cost premiums.
Insulation commands absolute volume dominance; fire protection delivers the most defensible margin structure against substitute encroachment.
End User:
Customer type concentration determines whether procurement flows through specification consultants, OEM engineering teams, or merchant distribution channels.
- Construction:Building envelope and interior systems across commercial, residential, and infrastructure projects, absorbing the majority of industry output through contractor and developer procurement.
- Automotive:Underhood thermal management, exhaust system insulation, and NVH reduction in passenger and commercial vehicles where weight and space constraints favor high-performance fiber mats.
- Industrial:Process equipment, piping, and vessel insulation in petrochemical, power generation, and manufacturing facilities where combined thermal and fire performance requirements prevail.
- Marine:Shipbuilding and offshore platform applications governed by IMO SOLAS fire safety regulations and classification society rules demanding non-combustible materials.
Construction absorbs the largest volume share; industrial end-use exhibits the most rapid specification upgrading toward premium stone wool systems.
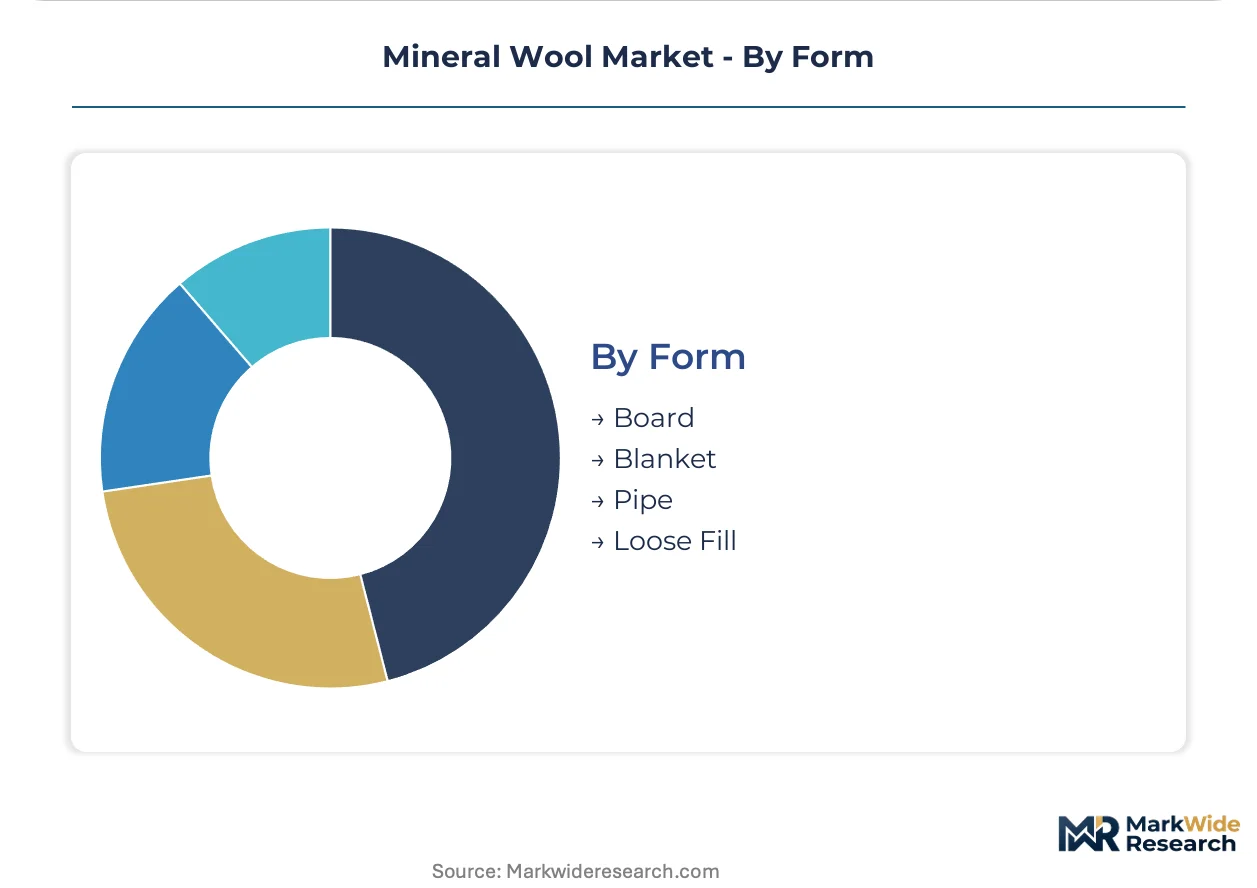
Form:
Supply concentration in continuous fiber production technology favors manufacturers with integrated forming and cutting capabilities.
- Board:Rigid panels for exterior wall insulation, roofing systems, and industrial equipment where compressive strength and dimensional stability under load are critical performance attributes.
- Blanket:Flexible rolls and batts for cavity wall, attic, and metal building insulation where ease of handling and installation speed reduce labor costs.
- Pipe:Pre-formed cylindrical sections for industrial piping and HVAC ductwork, requiring precise fabrication to minimize thermal bridging at joints and supports.
- Loose Fill:Blown-in fibers for irregular cavities and retrofit applications where complete coverage of complex geometries outweighs settling concerns over service life.
Blanket form retains volume leadership; board configurations gain share fastest as continuous exterior insulation requirements proliferate under advancing energy codes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between geographies: European markets prioritize fire-rated stone wool for commercial retrofit mandates, while North American residential construction favors cost-optimized glass wool batt insulation.
Germany
The EU Green Deal's building energy performance standards are accelerating commercial envelope retrofits in Berlin and Munich. REACH frameworks mandate progressive reductions in embodied carbon and formaldehyde emissions from insulation products. Industrial clusters in the Ruhr Valley are specifying stone wool for high-temperature equipment insulation where hydrophobicity commands price premiums.
United States
ASHRAE standard evolution is forcing thermal performance upgrades across commercial building envelopes in Chicago and New York. OSHA permissible exposure limits for respirable crystalline silica are elevating workplace safety investments across American manufacturing facilities. The Gulf Coast petrochemical corridor from Houston to New Orleans is expanding procurement of non-combustible insulation materials for process equipment.
Netherlands
Hyperscale data center construction in Amsterdam and Eindhoven is creating demand for fire-rated acoustic insulation in mechanical infrastructure. The EU Green Deal's embodied carbon tracking requirements extend downstream to public infrastructure procurement. Model-driven specification is now standard in commercial retrofit tendering across the Randstad region.
France
Progressive envelope performance requirements under the EU Green Deal are mandating non-combustible insulation in new commercial construction across Paris and Lyon. ECHA oversight of substance classifications is forcing systematic chemical inventory audits across French manufacturing. The country's national building regulator is tightening reaction-to-fire classifications for high-rise residential towers.
China
Blast furnace output volatility from steel manufacturing is constraining slag wool production capacity in Hebei and Shandong provinces. The country's national environmental regulator is enforcing dual carbon goals that elevate process heat efficiency requirements. Industrial retrofit activity in the Yangtze River Delta is concentrating demand for premium stone wool systems.
Mineral Wool Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier, with raw material access and furnace engineering capability determining competitive position. The market structure rewards backward integration into volcanic rock sourcing networks and captive glass fiber supply chains. Three archetypes dominate: Scandinavian stone wool specialists with slag valorization agreements, North American residential glass wool producers with distribution scale, and diversified building materials conglomerates with cross-selling leverage. Capacity expansion and bio-based binder reformulation represent the dominant competitive moves as regulatory pressure intensifies.
Within the integrated stone wool tier, Rockwool International A/S and Paroc Group exemplify producers leveraging Nordic volcanic rock access to sustain margin stability. Owens Corning anchors the North American residential vector through scale advantages in glass fiber supply chains. Saint-Gobain occupies a diversified position spanning multiple insulation chemistries and geographic markets. These three entities represent distinct strategic postures: raw material sovereignty, distribution channel dominance, and portfolio breadth respectively.
| Leading Market Players |
|---|
| Rockwool International A/S |
| Owens Corning |
| Saint-Gobain |
| Knauf Insulation |
| Johns Manville |
| Paroc Group |
| Isover |
| Kingspan Group |
| Armacell International |
| Others |
Cost & Logistics Intelligence
Long-term offtake agreements between Scandinavian slag processors and integrated steel mills lock in raw material access while providing price visibility for stone wool manufacturers facing volatile blast furnace output cycles. These contract structures insulate producers from spot-market swings in slag availability while embedding cost pass-through mechanisms tied to energy and resin indices.
Pricing Analysis
After-sales service revenue from fire-protection system certification and maintenance contracts drives lifetime value for stone wool producers serving commercial specification markets. Three-tier pricing structure across premium, standard, and economy levels segments buyers by fire-rating requirements and project scale. Cost compression in residential glass wool batt insulation is intensifying because embodied carbon audits erode specification share. Residential renovation contractors exhibit highest price sensitivity, while petrochemical facility engineers prioritize performance over unit cost.
Supply Chain Analysis
Port congestion on Baltic Sea routes and container availability constraints from Rotterdam to Hamburg elevate inbound logistics costs for volcanic rock imports serving Central European furnace operations. Supply concentrates in Germany, Denmark, and the United States, with raw material sourcing drawing from Nordic volcanic deposits, recycled glass cullet streams, and blast furnace slag co-production. Single-source vulnerability in phenolic resin feedstocks from specialized chemical producers creates formulation risk. Distribution runs through specialized building materials merchants and direct-to-contractor digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized furnace engineering expertise and cupola operation skills are aging out of traditional manufacturing regions faster than training pipelines replenish them, concentrating capability among a shrinking workforce cohort.
For Market Incumbents: Fortify raw material sovereignty through slag valorization agreements with integrated steel producers in Scandinavia and captive volcanic rock sourcing networks. Lock in specification preference by accelerating bio-based binder certification investments ahead of REACH progressive restrictions. Deepen channel control via digital specification platforms that bypass merchant intermediaries in residential retrofit markets. For New Entrants and Emerging Players: Anchor in data center thermal management segments across Ireland and the Netherlands where fire-rated acoustic insulation demand outpaces established supplier capacity. Target industrial process equipment insulation along the US Gulf Coast petrochemical corridor where hydrophobicity requirements create specification premiums. Pursue white-label manufacturing partnerships with distributors launching private-label mineral wool lines. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among stone wool specialists with verified environmental product declarations and long-term service contracts for fire-protection system maintenance. Five-to-ten year viability favors producers with backward integration into raw material networks and reformulation capability for bio-based binders. Monitor blast furnace output volatility in China and India as inflection indicator for slag wool supply constraints and price spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Raw Material Networks | Scandinavian volcanic rock sourcing agreements insulate margin stability against slag cyclicality. |
| Bio-based Binder Reformulation | Formaldehyde-free resin certification captures Nordic procurement preference under REACH frameworks. |
| Digital Specification Platform Launch | Direct-to-contractor channels bypass merchant intermediaries in residential renovation markets. |
| Capacity Expansion in Data Center Corridors | Amsterdam and Dublin hyperscale construction creates fire-rated acoustic insulation demand pull. |
| Environmental Product Declaration Investment | Third-party EPD verification accelerates LEED and BREEAM compliance in commercial tendering. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with building envelope consultants, commercial contractor procurement leads, industrial facility maintenance directors, and specialized building materials distributors. Secondary validation drew from EU Green Deal implementation documents, ECHA substance classification databases, OSHA permissible exposure limit rulings, customs trade data for mineral wool imports, and SEC filings from publicly traded insulation manufacturers. Bottom-up volume estimates by product chemistry and application were triangulated against top-down construction spending forecasts across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including product chemistry tier, end-use specification intensity, form factor configuration, and regional regulatory cluster. CAGRs were derived through regression analysis of historical shipment data against building code stringency indices and industrial capital expenditure cycles. Key forecast inputs included EU Green Deal thermal mandate implementation schedules and ASHRAE standard evolution timelines.
Material uncertainties — blast furnace output volatility, REACH substance reclassification timelines, and bio-resin feedstock scaling bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about regulatory implementation pace and substitution elasticity from polymer foam competitors. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Materials
Foam Insulation Market
Industrial Materials
Polyurethane Insulation Board Market
Industrial Materials
Plastics in Electrical and Electronics Market
Industrial Materials
Colored Hard PU Foam Market
Industrial Materials
Industrial Wax Market
Industrial Materials
Warehouse Drums and Barrels Market
Industrial Materials
Extruders and Compounding Machines Market
Industrial Materials
Welding Consumables Market
Industrial Materials
North America Phenolic Insulation Market
Industrial Materials
Global Plastic Fasteners Market
Industrial Materials
Portable Magnetizer Market
Industrial Materials
Global Friction Materials Market
Industrial Materials
Global High Pressure Seals Market
Industrial Materials
North America Medical Plastics Extrusion Market
Industrial Materials
Diamond Wire Market
Industrial Materials
Industrial Furnaces Market