
 Asia-Pacific Red Meat Market | 2026-2036
Asia-Pacific Red Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Red Meat Market Outlook
Subscription-based cold-chain monitoring services is broadening what processors and distributors sell beyond carcass weight. WH Group Limited leverages integrated hog farming and processing networks across China to sustain cost advantages at scale. NH Foods Ltd anchors premium beef exports from Japan through controlled aging protocols and breed certification. Tyson Foods Inc. competes in value-added portioned cuts for Asia-Pacific food service accounts, differentiating through consistent specification delivery.
Asia-Pacific red meat comprises muscle tissue from cattle, swine, sheep, and goats, processed under temperature-controlled conditions to preserve myoglobin integrity and extend shelf life through chilling, freezing, or modified atmosphere packaging. The category serves protein procurement for retail butchery, restaurant chains, and industrial food manufacturing across the region. Beef dominates value pools due to longer finishing cycles and grain-input intensity, while pork sustains volume leadership across China and Southeast Asia. Modified atmosphere packaging is expanding fastest among packaging formats as retailers push case-ready presentation and reduced store-level labor.
China's SAMR enforces national food safety standards for fresh and frozen meat circulation, while Australia's Department of Agriculture administers export registration and residue monitoring for chilled beef access across Northeast Asia. Japan's MAFF import quotas and BSE-age restrictions continue shaping supply eligibility for foreign processors. Stakeholders must track how carbon accounting requirements and methane mitigation protocols alter feedlot operations and export market access conditions across the region.
Market Dynamics
Chilled beef cold-chain logistics is concentrating procurement power among Southeast Asian food service operators with direct Australian export relationships, compressing traditional wholesale intermediary margins across the region.
Growth Catalysts
- Japan's MAFF import quota relaxation for grain-fed beef under 30 months:Australian processors gain expanded eligibility for premium chilled cuts into Tokyo's restaurant supply chains.
- Modified atmosphere packaging adoption by Vietnam's supermarket retail sector:Extended shelf life enables centralized processing and reduced store-level butchery labor costs.
- China's SAMR national food safety traceability mandates:Cold-chain digitization investments unlock subscription monitoring revenue streams for logistics providers serving urban wholesale markets.
Market Restraints
- Feed grain price volatility:Australian feedlot operators face margin compression from drought-driven sorghum and barley input cost swings.
- Single-origin supply concentration:Northeast Asian chilled beef dependence on Queensland and New South Wales export-registered plants creates port congestion vulnerability.
- Japan's BSE-age restrictions:Cattle over 30 months remain excluded from food-grade eligibility, culling eligible supply pools for specialty importers.
Strategic Opportunities
- Indonesia's underpenetrated premium retail segment:Jakarta's modern trade expansion creates first-mover positioning for controlled-aging beef programs.
- South Korea's carbon-neutral livestock procurement incentives:Methane-reduction certified feedlot supply qualifies for preferential tariff treatment under KORUS-aligned frameworks.
- Blockchain-IoT convergence in cross-border certification:Real-time temperature and origin verification enables direct processor-to-hotel procurement bypassing layered distribution.
Industry Challenges
- Veterinary residue testing capacity bottlenecks:Australia's export registration backlog delays new plant approvals for China-bound chilled certification.
- Cold-chain capex intensity for last-mile delivery:Refrigerated vehicle fleet expansion strains regional distributor balance sheets across Southeast Asian archipelago logistics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Red Meat Market |
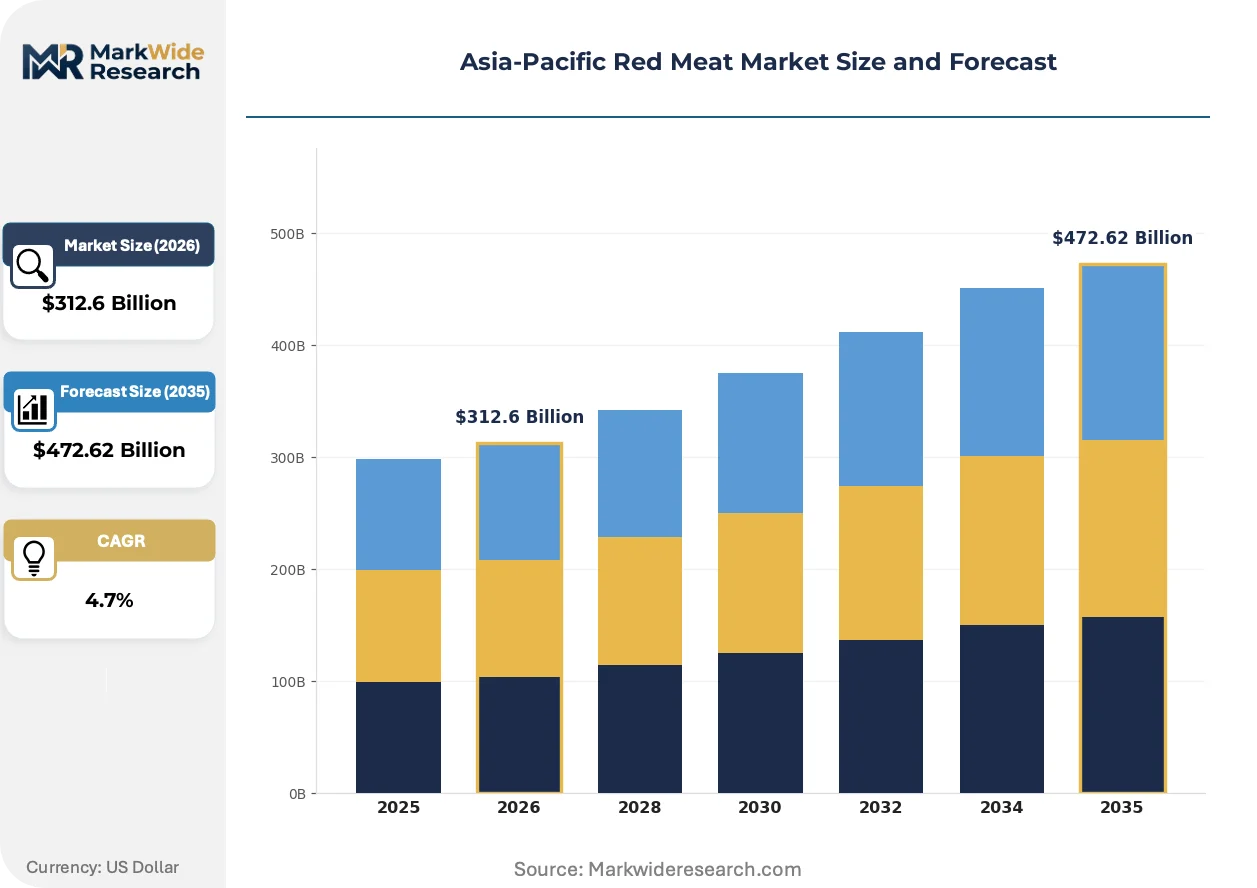
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Lamb, Goat End User: Retail, Food Service, Direct Consumption, Export Distribution Channel: Supermarkets, Online Retail, Wholesalers, Specialty Stores Packaging Type: Vacuum Pack, Modified Atmosphere, Canned, Fresh |
| Companies Covered | COFCO Corporation, NH Foods Ltd, WH Group Limited, Charoen Pokphand Foods Public Co Ltd, Muyuan Foods Co Ltd, New Hope Liuhe Co Ltd, JBS S.A., Tyson Foods Inc., Cargill Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Red Meat Market Strategic Shifts
Digital traceability infrastructure is compressing information asymmetry between Australian processors and Asian end-users, enabling specification-based procurement contracts that bypass traditional quality-assurance intermediaries.
Blockchain-enabled provenance verification is integrating shipment-level temperature data with breed and feed documentation. Major hotel chains in Singapore and Hong Kong now mandate this transparency for premium grain-fed procurement. The technology is integrating previously siloed cold-chain monitoring with financial settlement systems, reducing documentary credit processing delays.
China's SAMR is tightening residue monitoring protocols for beta-agonist and hormone detection in imported chilled beef. Australian Department of Agriculture export registration audits now incorporate expanded sampling frequencies. Korean importers are accelerating third-party laboratory pre-shipment verification to preempt customs detention risks at Busan and Incheon entry points.
Food service operators across Thailand and Vietnam are consolidating procurement through integrated protein distributors with captive cold-chain assets. Independent restaurant groups are losing direct Australian supplier relationships as volume thresholds rise. This concentration is most visible in Bangkok's central business district, where hotel procurement departments now contract exclusively with regional logistics platforms.
Asia-Pacific Red Meat Market Segmentation
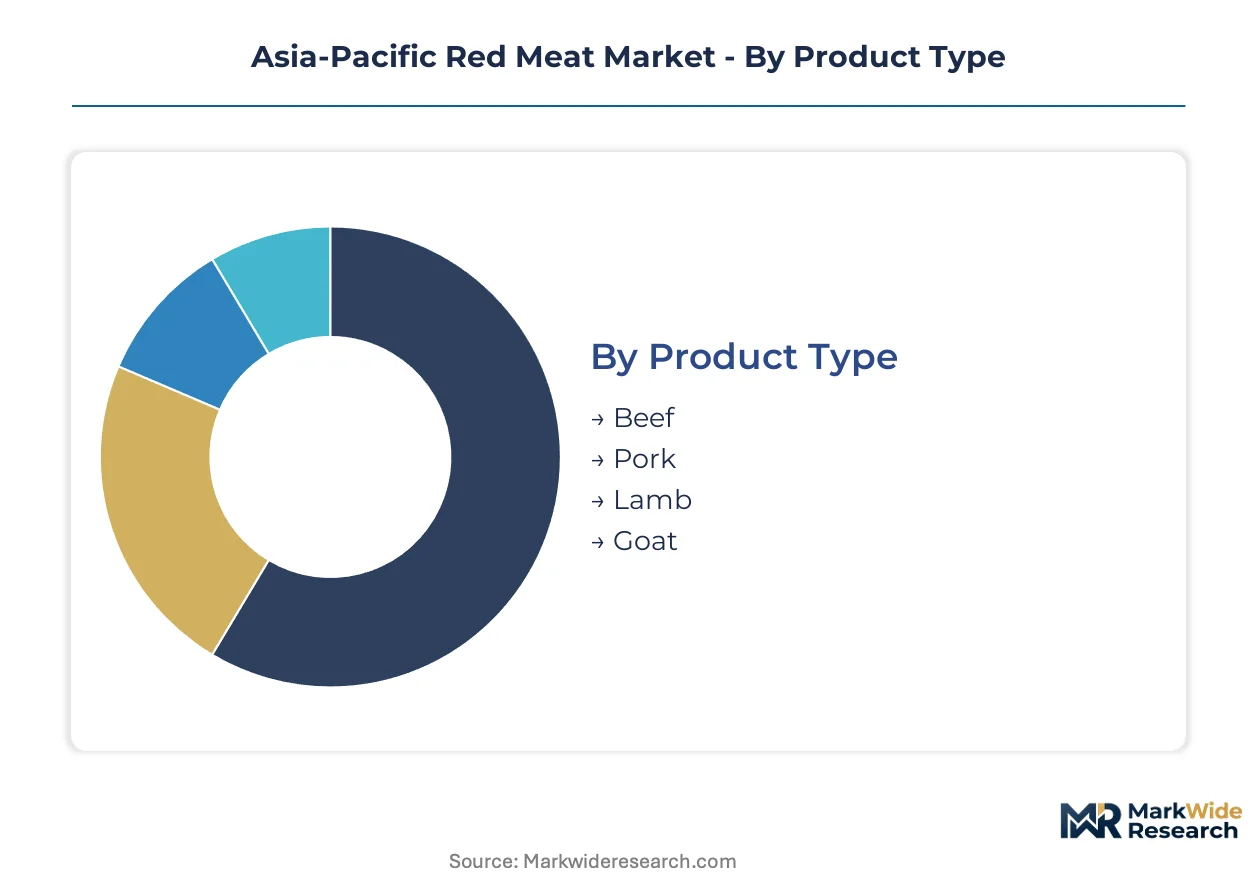
Segmentation reveals how regulatory burdens and cold-chain requirements concentrate margin pools across the Asia-Pacific red meat value chain. Certification complexity varies sharply by product type and end-use channel, determining which processors capture premium positioning.
Product Type:
Beef and pork carry the heaviest certification overhead, requiring Australia's Department of Agriculture export registration and Japan's MAFF import quota compliance for chilled access.
- Beef:Grain-fed and grass-fed varieties demand distinct aging protocols and BSE-age verification under Japanese regulations. Australian feedlot operators dominate premium chilled supply into Tokyo's restaurant chains, where grain-fed cuts command sustained buyer interest despite longer finishing cycles.
- Pork:Integrated farming networks across China sustain volume leadership through WH Group's captive processing infrastructure. WH Group leverages scale advantages in hog farming to compress per-unit costs while meeting China's SAMR national food safety traceability mandates for domestic circulation.
- Lamb:New Zealand and Australian processors target Middle Eastern export corridors and Southeast Asian halal-certified food service accounts.
- Goat:Niche positioning in South Asian and Middle Eastern ethnic retail channels with limited cold-chain infrastructure requirements.
Pork sits at the top of the volume ranking, with beef climbing the fastest on value expansion in Northeast Asian premium channels.
End User:
Food service operators now consolidate procurement through direct Australian export relationships, bypassing traditional wholesale intermediaries.
- Retail:Supermarket chains across Vietnam and Thailand are adopting modified atmosphere packaging to reduce store-level butchery labor. Centralized processing investments unlock case-ready presentation standards previously limited to developed Northeast Asian markets.
- Food Service:Hotel procurement departments in Bangkok's central business district contract exclusively with regional logistics platforms possessing captive cold-chain assets. Volume thresholds for direct Australian supplier relationships have risen sharply, displacing independent restaurant groups.
- Direct Consumption:Wet market trade persists across Indonesia and Philippines with minimal packaging and traceability infrastructure.
- Export:Australian and New Zealand processors dominate cross-border chilled certification, with residue testing backlogs delaying new plant approvals for China-bound shipments.
Food service captures the steepest margin expansion, with retail gaining share fastest on modern trade format conversion.
Distribution Channel:
Channel selection determines cold-chain capex intensity and last-mile delivery economics across Southeast Asian archipelago logistics.
- Supermarkets:Vietnam's retail sector is expanding modified atmosphere packaging adoption to enable centralized processing and extended shelf life. This format shift compresses traditional wholesale intermediary margins by reducing store-level labor requirements.
- Online Retail:Subscription-based cold-chain monitoring services are broadening what processors and distributors sell beyond carcass weight. Digital traceability infrastructure enables specification-based procurement contracts that bypass quality-assurance intermediaries.
- Wholesalers:Traditional layered distribution faces margin compression as food service operators develop direct Australian export relationships.
- Specialty Stores:Premium grain-fed beef programs target Jakarta's modern trade expansion with controlled-aging positioning.
Supermarkets anchor volume throughput, with online retail expanding most quickly on cold-chain digitization investments.
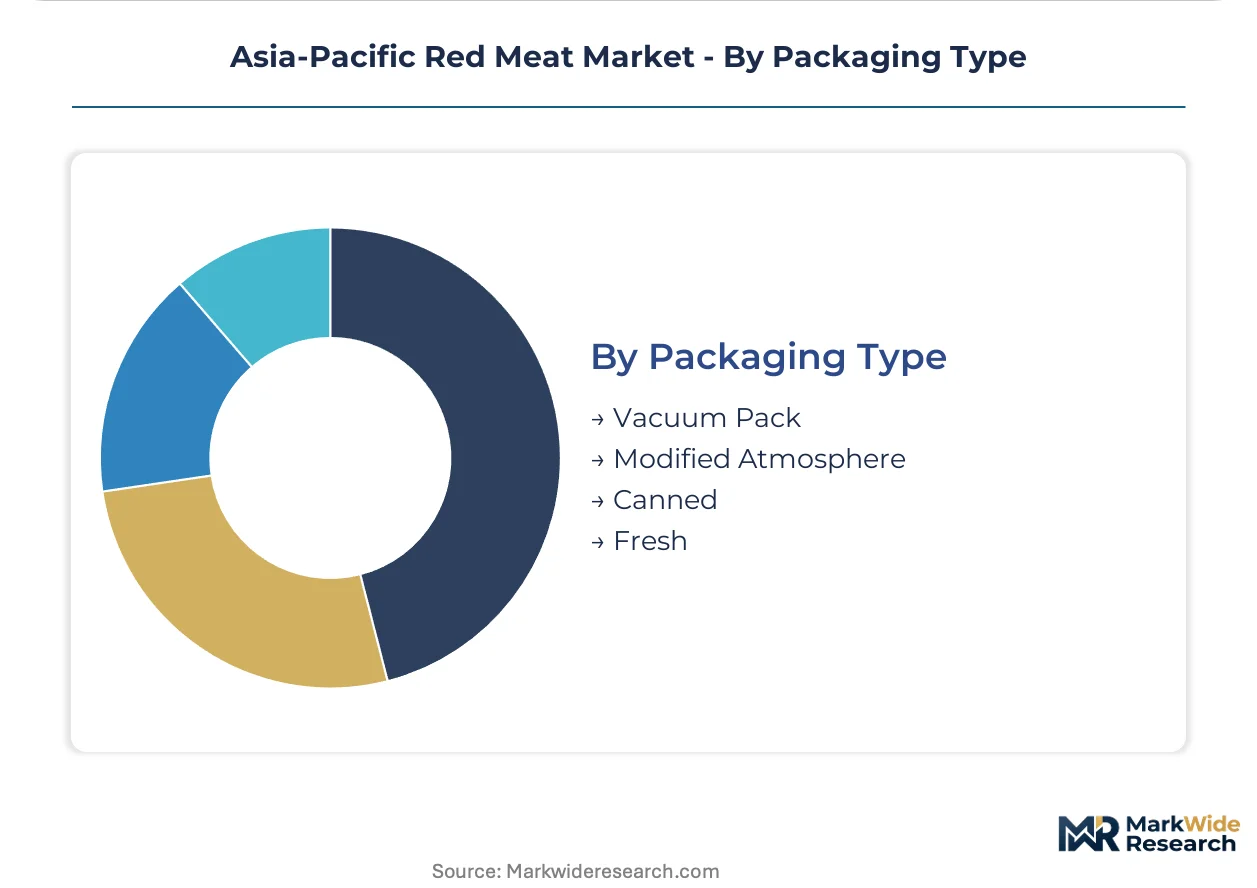
Packaging Type:
Packaging selection directly impacts shelf-life extension and regulatory compliance for cross-border chilled certification.
- Vacuum Pack:Standard format for frozen bulk shipments with established cost structures and limited differentiation potential.
- Modified Atmosphere:Expanding fastest among packaging formats as retailers push case-ready presentation. Extended shelf life enables centralized processing and reduced store-level butchery labor costs across Vietnam's supermarket sector.
- Canned:Preserved protein for emergency stockpiling and military procurement with minimal cold-chain dependency.
- Fresh:Unpackaged trade dominates wet markets across Indonesia and Philippines with same-day consumption patterns.
Modified atmosphere packaging leads value growth, with vacuum pack retaining volume dominance in frozen commodity trade.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands premium grain-fed beef procurement volumes while Australia dominates chilled export certification infrastructure, creating divergent supply chain configurations across the region.
China
Urban wholesale markets in Shanghai and Beijing sustain concentrated demand for Australian grain-fed chilled cuts. SAMR's national food safety traceability mandates accelerate cold-chain digitization investments by logistics providers. The Yangtze River Delta cluster hosts the largest concentration of temperature-controlled distribution facilities serving restaurant chains.
Japan
Tokyo's restaurant supply chains maintain sustained buyer interest in premium grain-fed beef under 30 months. MAFF import quotas and BSE-age restrictions filter eligible supply pools from Australian export-registered plants. The Kanto metropolitan area anchors specialized chilled beef distribution with direct processor relationships.
Australia
Queensland and New South Wales feedlots supply the bulk of Northeast Asian chilled beef certification. The Department of Agriculture's export registration audits and residue monitoring protocols shape regional trade eligibility. Port infrastructure concentration around Brisbane and Sydney creates congestion vulnerability during peak shipment windows.
South Korea
Seoul's hotel and restaurant procurement departments prioritize methane-reduction certified feedlot supply for preferential tariff positioning. MFDS import protocols and carbon-neutral livestock procurement incentives reshape supplier qualification criteria. The Busan-Ulsan corridor handles pre-shipment laboratory verification to preempt customs detention risks.
Vietnam
Supermarket retail expansion in Ho Chi Minh City drives modified atmosphere packaging adoption for case-ready beef presentation. Centralized processing investments reduce store-level butchery labor costs across modern trade formats. Cold-chain infrastructure gaps persist in last-mile delivery to secondary cities.
Asia-Pacific Red Meat Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated protein conglomerates commanding volume leadership while boutique aging programs capture premium positioning. The vendor base concentrates around three strategic archetypes: captive farming-processing networks, export-certified chilled beef specialists, and value-added portioning operators. Geographic expansion through direct food service relationships and backward integration into feedlot operations represent the dominant competitive moves reshaping procurement patterns.
Among Asia-Pacific headquartered conglomerates, WH Group Limited and NH Foods Ltd occupy positions at opposite ends of the integration spectrum. WH Group exemplifies scale-driven captive supply structures spanning hog farming through processing. NH Foods Ltd represents export-certified premium positioning anchored in controlled-aging protocols and breed documentation. Tyson Foods Inc. sits within the value-added tier, competing on consistent specification delivery for food service accounts. These three anchors illustrate how certification depth and cold-chain control determine margin capture across the regional value chain.
| Leading Market Players |
|---|
| COFCO Corporation |
| NH Foods Ltd |
| WH Group Limited |
| Charoen Pokphand Foods Public Co Ltd |
| Muyuan Foods Co Ltd |
| New Hope Liuhe Co Ltd |
| JBS S.A. |
| Tyson Foods Inc. |
| Cargill Inc. |
| Others |
Value Chain & Pricing Dynamics
Captive feedlot-to-processor integration across Queensland and New South Wales anchors both supply security and premium pricing power for Australian chilled beef exporters serving Northeast Asian markets. This vertical control over grain-input sourcing and export certification enables processors to sustain margin capture despite drought-driven feed cost volatility.
Pricing Analysis
Capacity additions in Vietnam's supermarket retail sector are reshaping price floors for case-ready beef presentation as centralized processing investments reduce per-unit labor costs. Three-tier pricing structure across premium grain-fed, standard chilled, and economy frozen levels stratifies buyer segments, with grain-fed cuts commanding sustained interest from Tokyo restaurant chains. Pricing pressure stems from Australian sorghum and barley input cost swings compressing feedlot margins. Independent restaurant groups across Bangkok exhibit highest price sensitivity as volume thresholds for direct supplier relationships rise sharply.
Supply Chain Analysis
Workforce availability constraints in Australian export-registered processing plants and Vietnamese centralized cutting facilities are tightening operational flexibility across the chilled beef value chain. Supply concentrates in Australian feedlots, Chinese domestic hog farming networks, and New Zealand lamb processing corridors. Raw material flows draw from Queensland cattle stations, Brazilian soybean meal imports for feed rations, and New Zealand pastoral grazing systems. Single-origin dependence on Brisbane and Sydney port infrastructure creates congestion vulnerability during peak shipment windows. Distribution runs through layered wholesaler networks in Southeast Asia and direct processor relationships in Northeast Asia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
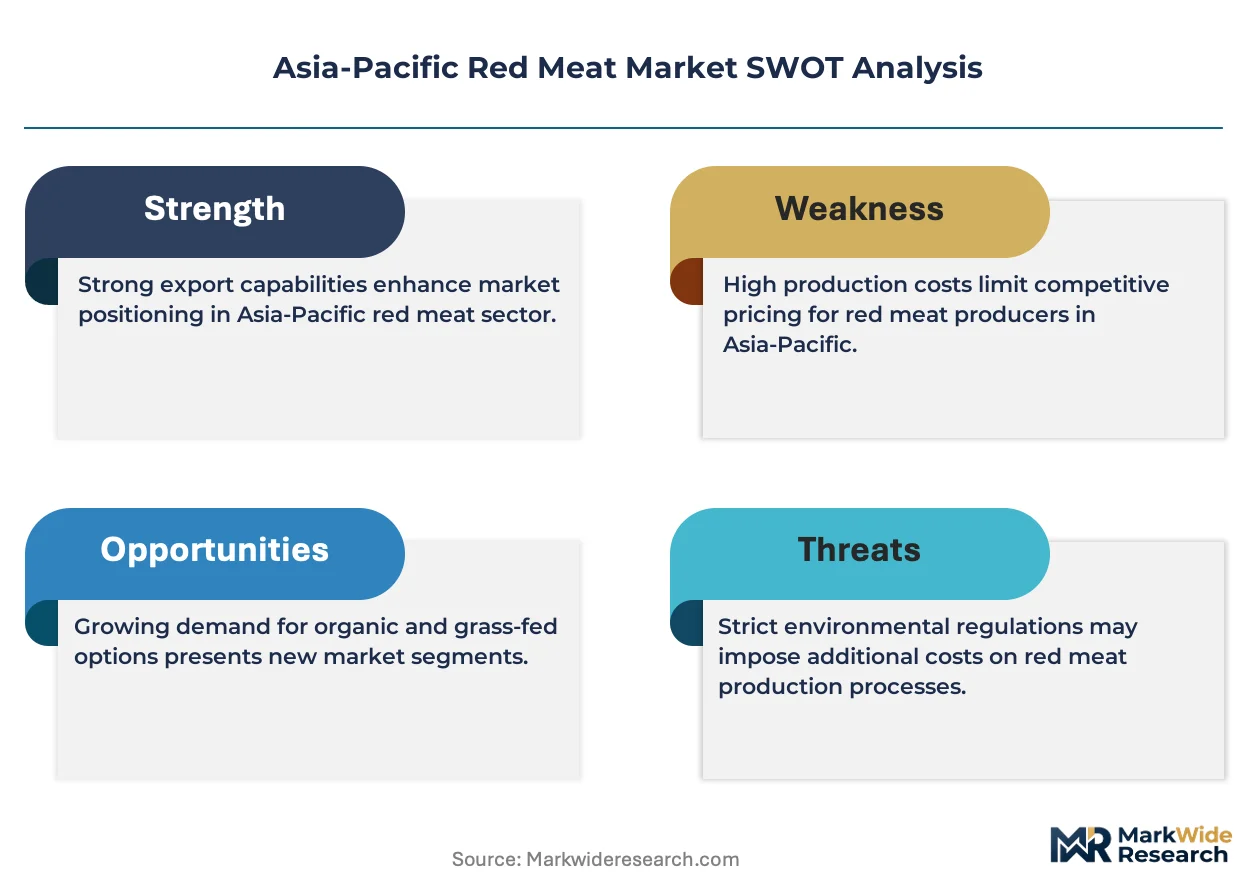
This market functions as a geographic-arbitrage play where Australian processors capture premium positioning from Japan's MAFF import quota restrictions while Chinese domestic producers exploit lower regulatory compliance costs for volume leadership.
For Market Incumbents: Anticipate margin compression from rising feed grain price volatility by securing long-term offtake agreements with Queensland sorghum suppliers. Invest in blockchain-enabled provenance verification to defend positioning against emerging logistics platforms consolidating Bangkok hotel procurement. Certification depth in Japan's BSE-age compliance protocols remains the critical defensive lever.
For New Entrants and Emerging Players: Launch via direct food service relationships in Jakarta's underpenetrated premium retail segment, bypassing traditional layered distribution. Target controlled-aging beef programs for modern trade expansion where first-mover positioning remains available. Pursue methane-reduction certification to qualify for South Korea's carbon-neutral livestock procurement incentives.
For Investors and Strategic Acquirers: Roll-up economics work for regional cold-chain logistics platforms because food service procurement consolidation is displacing independent distributors across Southeast Asian archipelago markets. Long-term viability hinges on captive infrastructure ownership rather than asset-light brokerage models. Watch for Australian Department of Agriculture export registration backlog resolution as inflection signal for new plant approval velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedlot Operations | Queensland grain-input control insulates margin from drought-driven sorghum price swings. |
| Blockchain-IoT Certification Deployment | Singapore hotel chains now mandate real-time temperature verification for premium procurement. |
| Methane-Reduction Feedlot Certification | South Korea's MFDS protocols qualify certified supply for preferential tariff treatment. |
| Centralized Processing Investment | Vietnam's supermarket expansion enables case-ready presentation with reduced store labor. |
| Direct Processor-to-Hotel Contracting | Bangkok central business district procurement now bypasses traditional wholesale intermediaries. |
Study Parameters
Direct dialogue with Australian feedlot operators, Japanese import procurement managers, Vietnamese supermarket category buyers, and Singapore hotel supply chain directors grounded qualitative insights in operational reality. Secondary validation drew from Australia's Department of Agriculture export registration databases, Japan's MAFF import quota filings, China's SAMR food safety traceability protocols, and Vietnam retail sector customs records. Bottom-up segment sizing and top-down macroeconomic triangulation ensured cross-verified outputs.
Bottom-up modeling of feedlot capacity, processing throughput, and channel-specific pricing combined with top-down GDP-protein consumption elasticity checks across the projection horizon. Segmentation dimensions spanned product type, end-user channel, distribution format, and packaging technology. CAGRs derived from trend extrapolation of cold-chain infrastructure investment cycles and regulatory quota relaxation trajectories. Feed grain price volatility indices and carbon certification adoption curves served as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including abrupt Australian drought recurrence, Japan's MAFF quota policy reversal, and China's SAMR residue protocol tightening. Forecasts reflect documented assumptions about continued cold-chain capex deployment and stable bilateral trade frameworks. Material deviation in feed grain input costs or export registration approval velocity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Europe Animal Protein Market
Meat Products
Germany Meat Products Market
Meat Products
Pepperoni Foods Market
Meat Products
Middle East Poultry Meat Market
Meat Products
Chicken Fat Market
Meat Products
United States Red Meat Market
Meat Products
Middle-East and Africa Animal-Based Meat and Dairy Products Market
Meat Products
Global Duck Meats Market
Meat Products
North America Bacon Market
Meat Products
North America Red Meat Market
Meat Products
Beef Tallow Market
Meat Products
United States Animal Protein Market
Meat Products
Pork Meat Market
Meat Products
Meat Emulsions Market
Meat Products
Organic Halal Meat Market
Meat Products
Canned Beef Market