
 Middle East Red Meat Market | 2026-2036
Middle East Red Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Red Meat Market Foresight
Subscription-based cold-chain monitoring and predictive maintenance contracts for refrigerated transport fleets is rebalancing how processors and distributors monetize freshness guarantees. JBS SA leverages its integrated South American supply base to secure consistent cattle flows into Middle East ports. Siniora Food Industries anchors its position through processed meat specialization that extends shelf life for institutional buyers. Almarai Company dominates Saudi retail channels with controlled distribution networks spanning its dairy and protein portfolios.
Red meat encompasses muscle tissue from cattle, sheep, goats, and young bovines, typically processed under temperatures below seven degrees Celsius to inhibit microbial proliferation and preserve myoglobin color stability for consumer acceptance. The product serves as a primary protein source for household consumption, restaurant preparation, and large-scale catering operations across Middle Eastern cuisines. Beef occupies the largest volume share among product types due to its centrality in Gulf dietary preferences and its versatility across grilling and slow-cooking traditions. Chilled packaging formats command margin premiums over frozen alternatives in supermarket channels where consumers perceive freshness as a quality signal. Wholesale distribution channels sustain the highest throughput volumes, particularly for restaurant and food service procurement in Riyadh, Jeddah, and Dubai.
Saudi Food and Drug Authority standards, UAE Ministry of Climate Change and Environment halal protocols, and GCC-wide technical regulations for meat imports collectively determine market access thresholds for foreign suppliers. These frameworks mandate slaughterhouse accreditation, veterinary health certificates, and cold-chain documentation that raise compliance costs for non-integrated exporters. Stakeholders must monitor evolving national self-sufficiency targets and local livestock subsidy programs that could redirect procurement patterns toward domestic or near-regional origins.
Market Dynamics
Halal certification protocols enforced by Gulf food regulators are tightening traceability requirements and reshaping supplier qualification criteria across chilled and frozen beef supply chains.
Growth Catalysts
- Food service expansion:Hotel and restaurant chains across Saudi Arabia are absorbing larger protein volumes as tourism infrastructure scales, pulling chilled beef through wholesale distribution channels.
- SFDA accreditation mandates:Saudi Food and Drug Authority slaughterhouse certification requirements are filtering out non-compliant exporters and consolidating procurement around accredited suppliers.
- Free-zone cold storage capacity:Dubai's logistics infrastructure attracts regional re-export activity, positioning the UAE as a redistribution hub for Gulf markets.
Market Restraints
- Feed input volatility:Brazilian and Australian cattle grain costs fluctuate with commodity cycles, compressing processor margins on imported beef.
- Supply concentration risk:South American integrated packers dominate frozen beef flows, creating dependency on single-origin supply bases.
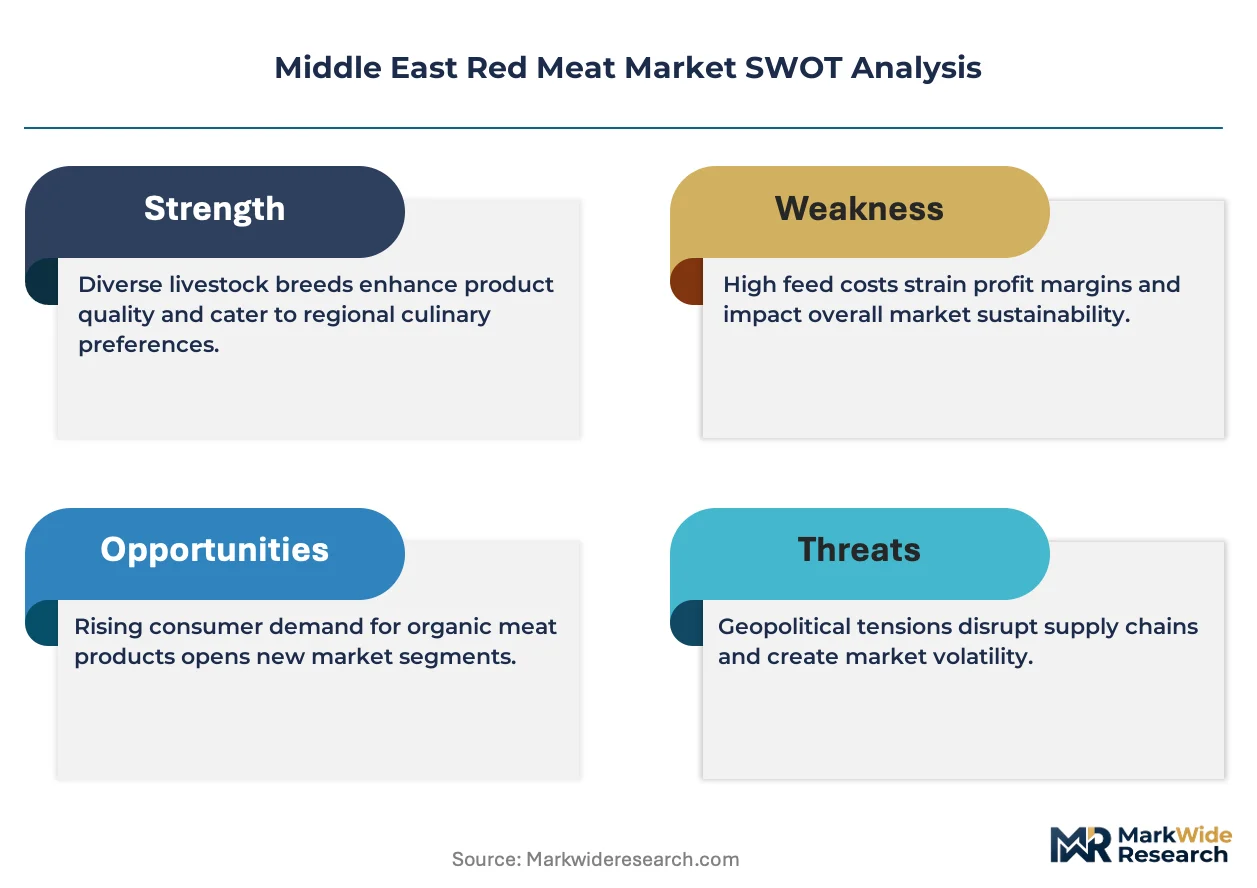
- Substitution pressure:Poultry protein from domestic Saudi farms competes on price in institutional catering contracts.
Strategic Opportunities
- Processed meat specialization:Extended-shelf-life product formats for institutional buyers remain underdeveloped outside established regional brands.
- Subscription monitoring services:Predictive maintenance contracts for refrigerated transport fleets offer recurring revenue models beyond commodity sales.
- MOHAP traceability alignment:UAE Ministry of Health and Prevention digital halal verification systems reward early-compliant suppliers with faster customs clearance.
Industry Challenges
- Veterinary certification timelines:GCC-wide health certificate documentation creates port delays for non-integrated exporters lacking in-house compliance teams.
- Cold-chain capex intensity:Controlled-atmosphere container fleets and port-side blast freezing capacity demand capital deployment that mid-scale distributors struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Red Meat Market |
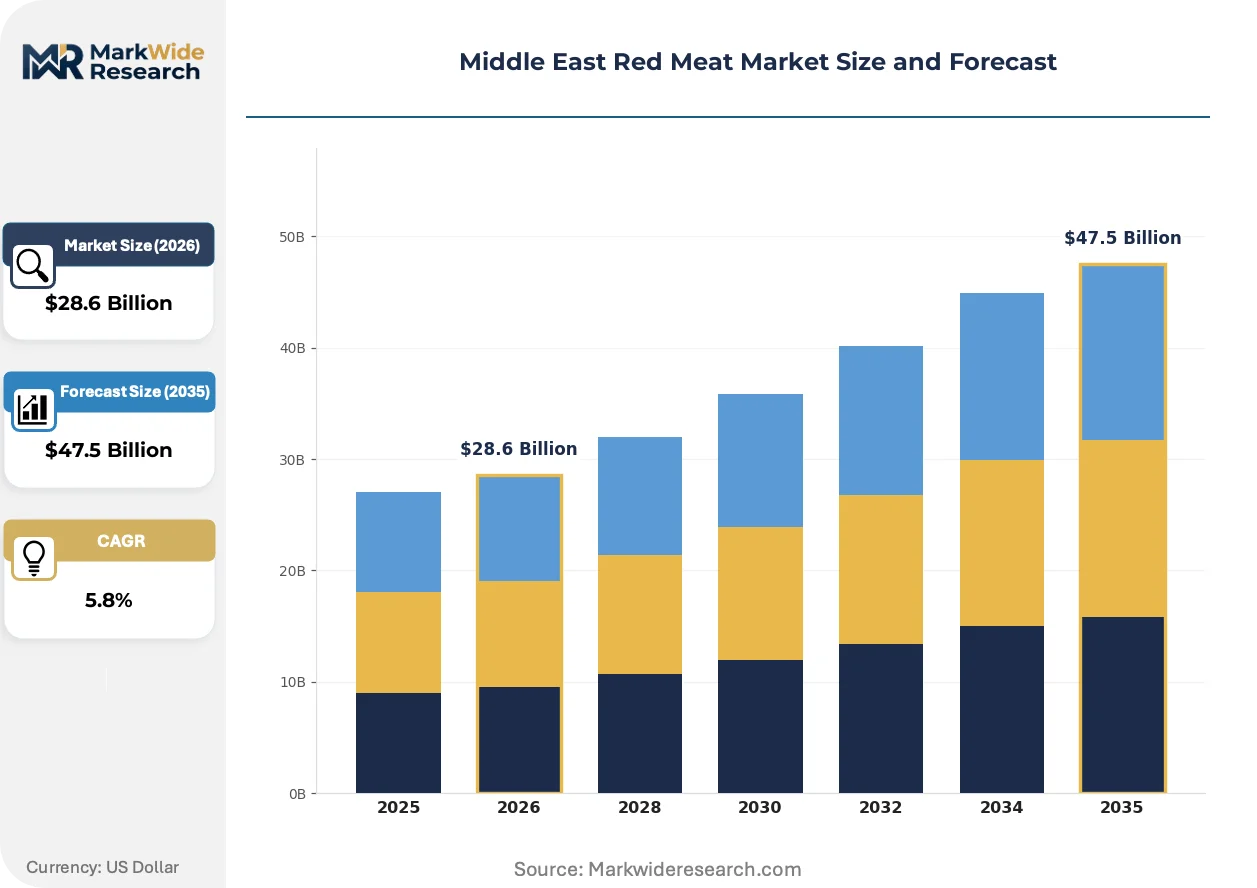
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $47.5 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
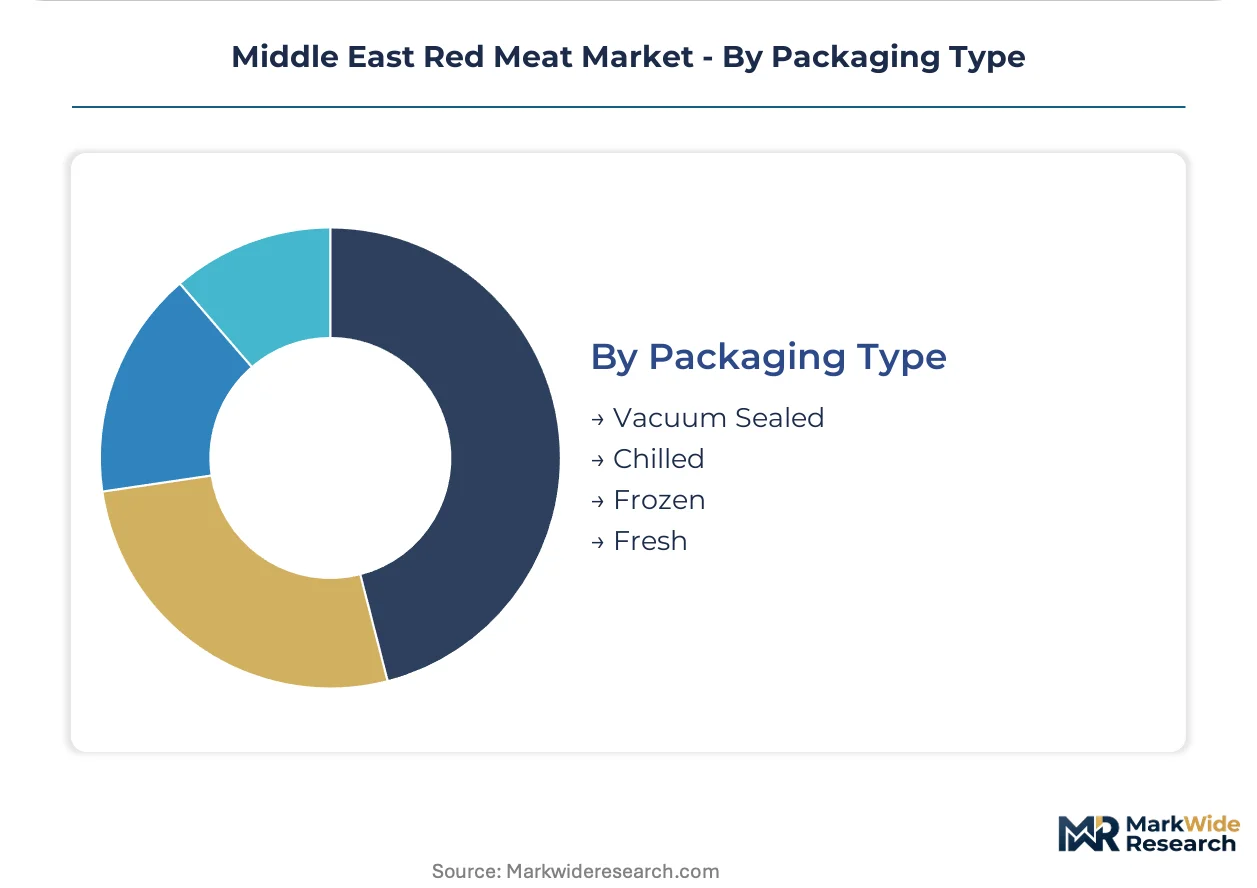
| Segmentation | Product Type: Beef, Lamb, Goat, Veal Distribution Channel: Supermarkets, Butcher Shops, Online Stores, Wholesale End User: Households, Restaurants, Food Service, Catering Packaging Type: Vacuum Sealed, Chilled, Frozen, Fresh |
| Companies Covered | JBS SA, Siniora Food Industries, Almarai Company, The Organic Meat Company Ltd, Almunajem Foods, Tanmiah Food Company, The Savola Group, Sunbulah Group, BRF S.A., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Red Meat Market Shifts & Advancements
Digital traceability platforms and sensor-based freshness verification are compressing information asymmetries between Gulf importers and distant slaughterhouses, restructuring how quality premiums are priced and captured.
Blockchain-enabled provenance tracking is converging with mobile-enabled halal verification apps to create auditable cattle-to-retail records. Major supermarket chains in the UAE and Saudi Arabia are piloting these systems for premium chilled beef SKUs. This convergence is compressing the documentation burden that previously delayed customs clearance and eroded shelf life.
SFDA and MOHAP are harmonizing electronic veterinary health certificate formats to reduce paperwork duplication at Gulf ports. The industrial consequence is accelerated clearance for pre-registered suppliers and extended detention for non-compliant shipments. Frozen beef containers from non-accredited origins face the longest processing delays under the new protocols.
Food service procurement teams in Riyadh and Dubai are consolidating supplier relationships around integrated packers offering guaranteed freshness windows. Long-tail distributors with inconsistent cold-chain documentation are losing share to accredited partners. This concentration is most visible in hotel chain tender processes where liability exposure drives vendor rationalization.
Middle East Red Meat Market Segmentation
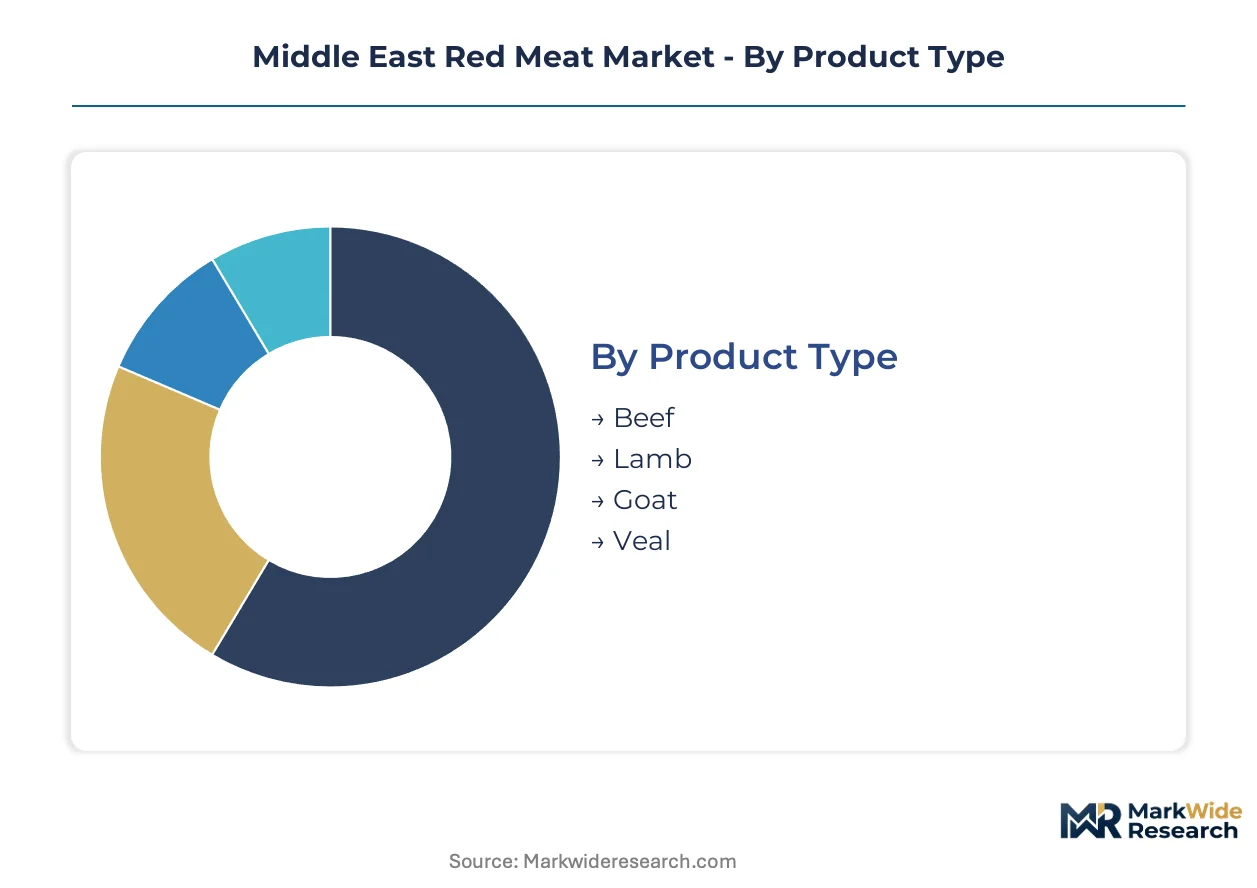
Segmentation in Middle Eastern red meat markets determines which suppliers qualify for which procurement tiers. SFDA slaughterhouse accreditation, MOHAP halal protocols, and GCC cold-chain documentation requirements apply unevenly across product formats and distribution channels, creating distinct compliance cost structures.
Product Type:
SFDA mandates veterinary health certificates and slaughterhouse accreditation for all imported red meat, though enforcement intensity varies by species-specific consumption patterns and religious dietary specifications.
- Beef:Muscle tissue from mature cattle dominates volume flows through Saudi and UAE ports. Hotel chains in Riyadh and Dubai specify chilled hindquarter cuts for premium grilling menus, pulling accredited Brazilian and Australian packers into long-term supply contracts.
- Lamb:Young sheep meat carries higher per-kilogram value in Gulf retail, particularly during religious observance periods. Australian live-export trade routes and chilled carcass air freight serve immediate consumption windows in Jeddah and Abu Dhabi hospitality sectors.
- Goat:Narrower commercial footprint concentrated in ethnic restaurant procurement and specific household preparation traditions across the Levant and Arabian Peninsula.
- Veal:Young bovine meat occupies specialty positioning in fine-dining channels where tenderness commands menu price premiums.
Leading the category by volume: Beef. Growing fastest: Lamb.
Distribution Channel:
Channel selection dictates cold-chain infrastructure requirements and margin capture potential, with wholesale and supermarket formats demanding divergent freshness verification systems.
- Wholesale:Institutional procurement through Riyadh, Jeddah, and Dubai distribution centers sustains the highest throughput volumes. Restaurant groups and catering operators consolidate purchases around accredited suppliers offering guaranteed freshness windows and batch-traceable documentation.
- Supermarkets:Retail chains in Saudi Arabia and the UAE stock chilled beef in modified-atmosphere packaging where myoglobin color stability signals quality to consumers. Margin premiums over frozen alternatives reflect shorter shelf life and higher spoilage risk.
- Butcher Shops:Traditional counter-service retail persists in older urban districts and religiously conservative consumer segments preferring visual carcass inspection before purchase.
- Online Stores:E-commerce penetration remains limited by temperature-controlled last-mile delivery costs and consumer preference for physical freshness verification.
Wholesale channels dominate absolute volume. Online stores are expanding most quickly from a low base.
End User:
User category determines portion specification, delivery frequency, and liability exposure in supplier contracts.
- Restaurants:Full-service dining establishments in Dubai and Riyadh specify primal cuts with consistent marbling for standardized menu execution. Tender processes increasingly require blockchain-traceable provenance documentation.
- Food Service:Institutional feeding operations including corporate cafeterias and airline catering prioritize portion-controlled frozen products with extended shelf life and predictable yield.
- Households:Retail purchasing decisions in Saudi supermarkets favor chilled over frozen formats where price sensitivity permits, with freshness perception driving brand selection.
- Catering:Large-event provisioning demands volume scalability and halal certification batch consistency for wedding and corporate functions across Gulf urban centers.
Restaurants command the steepest margin premiums. Food service sustains the largest absolute offtake.
Packaging Type:
Packaging technology selection governs shelf life extension, transport mode economics, and consumer quality signaling.
- Chilled:Temperature-controlled distribution between zero and seven degrees Celsius preserves myoglobin chemistry for color-stable retail presentation. Dubai's free-zone cold storage capacity enables regional redistribution of chilled beef with minimal shelf life erosion.
- Frozen:Blast-frozen product at minus eighteen degrees enables ocean freight economics from South American packers. Port-side freezing investments in Jeddah and Dubai support import substitution buffering.
- Vacuum Sealed:Oxygen-excluded packaging extends chilled shelf life for supermarket premium tiers and export-ready portion cuts.
- Fresh:Unmodified atmospheric packaging serves immediate-consumption butcher shop trade with same-day slaughter-to-sale cycles.
Frozen packaging leads by volume throughput. Chilled formats are gaining share fastest in supermarket premium tiers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's Jebel Ali Free Zone anchors regional redistribution through temperature-controlled warehousing and bonded cold storage capacity that enables rapid customs clearance for re-export to Gulf Cooperation Council markets.
Saudi Arabia
Riyadh and Jeddah hospitality sectors drive chilled beef absorption as hotel chains expand protein sourcing for tourism infrastructure. SFDA slaughterhouse accreditation mandates filter procurement toward certified Brazilian and Australian packers. The Eastern Province industrial corridor hosts port-side blast freezing investments that buffer import substitution.
United Arab Emirates
Dubai's logistics infrastructure attracts regional re-export volumes while Abu Dhabi scales institutional catering procurement. MOHAP digital halal verification systems reward early-compliant suppliers with accelerated customs processing. Jebel Ali port concentration enables redistribution across Kuwait, Qatar, and Bahrain markets.
Qatar
Doha's hospitality procurement teams consolidate supplier relationships around integrated packers offering guaranteed freshness windows. The Ministry of Public Health enforces veterinary health certificate standards that mirror SFDA protocols. Lusail development corridors concentrate new hotel and restaurant chain openings.
Kuwait
Food service operators in Kuwait City prioritize portion-controlled frozen products with extended shelf life for institutional contracts. The Public Authority for Food and Nutrition aligns import documentation with GCC-wide technical regulations. Shuwaikh industrial zone cold storage capacity supports wholesale distribution throughput.
Oman
Muscat restaurant groups specify primal cuts with consistent marbling for standardized menu execution across expanding tourism zones. The Ministry of Agriculture and Fisheries enforces halal slaughterhouse accreditation for all imported red meat. Sohar port investments target regional transshipment positioning.
Middle East Red Meat Market Competitive Landscape
Capital-heavy integrated packers compete with asset-light distributors for margin capture across cold-chain infrastructure. The market structures around three tiers: South American-origin integrated producers, Gulf-based processors with domestic distribution networks, and regional trading houses specializing in re-export logistics. Strategic moves concentrate on slaughterhouse accreditation acquisition and controlled-atmosphere fleet deployment.
Within the integrated producer tier, JBS SA anchors supply security through captive South American cattle flows. Siniora Food Industries exemplifies processed meat specialization that extends shelf life for institutional buyers. Almarai Company occupies a position spanning controlled retail distribution networks across dairy and protein portfolios.
| Leading Market Players |
|---|
| JBS SA |
| Siniora Food Industries |
| Almarai Company |
| The Organic Meat Company Ltd |
| Almunajem Foods |
| Tanmiah Food Company |
| The Savola Group |
| Sunbulah Group |
| BRF S.A. |
| Others |
Supply & Pricing Matrix
Brazilian cattle feed grain costs cascade through frozen beef export pricing tiers before reaching Saudi hotel procurement teams and UAE supermarket buyers, with South American packers capturing upstream margin while Gulf distributors absorb logistics volatility.
Pricing Analysis
Freshness-window guarantees anchor value-based pricing for chilled beef contracts serving Riyadh and Dubai hospitality chains. Three-tier pricing structure across premium chilled hindquarters, standard frozen primal cuts, and economy-grade commodity frozen beef separates certification-grade product from volume-tier alternatives. Pricing pressure stems from Australian grain-fed cattle input cost compression competing with Brazilian grass-fed alternatives. Food service operators exhibit highest price sensitivity due to institutional tender processes, while premium hotel chains prioritize traceability documentation over unit cost.
Supply Chain Analysis
Breeding stock and feed grain supply rests on Brazilian pasturelands and Australian grain finishing operations, with chilled carcass air freight capacity concentrated in Australian export infrastructure. Live cattle flows, veterinary health certificate processing capacity, and controlled-atmosphere container fleets constitute critical input dependencies. Single-source vulnerability concentrates around Brazilian integrated packers dominating frozen beef ocean freight volumes. Distribution runs through Dubai's Jebel Ali Free Zone cold storage for regional re-export redistribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Slaughterhouse accreditation capacity constraints prop pricing premiums for pre-certified suppliers, as SFDA and MOHAP processing backlogs create artificial scarcity in compliant supply tiers.
For Market Incumbents: Extend cold-chain monitoring subscription services to capture recurring revenue beyond commodity margins, while securing additional SFDA-accredited slaughterhouse partnerships to buffer against Brazilian supply concentration risk. Certification investment in MOHAP digital halal verification systems accelerates customs clearance and defends position against emerging re-export specialists.
For New Entrants and Emerging Players: Begin with processed meat specialization targeting institutional food service contracts where extended shelf life requirements favor technical formulation capabilities over raw sourcing scale. White-space opportunity concentrates in vacuum-sealed premium chilled formats for UAE supermarket private label programs, with go-to-market execution through Dubai free-zone logistics partnerships.
For Investors and Strategic Acquirers: MOHAP blockchain-traceability pilot program expansion is the leading indicator that digital verification infrastructure will consolidate procurement around early-compliant integrated packers. Long-term viability favors backward-integrated assets with captive cattle supply and in-house cold-chain fleet deployment. Acquisition target archetype: mid-scale distributors with established SFDA relationships but underutilized blast-freezing capacity.
| Strategic Initiative | Industry Significance |
|---|---|
| Slaughterhouse Accreditation Acquisition | SFDA certification scarcity filters market access toward pre-qualified suppliers with documented veterinary protocols. |
| Controlled-Atmosphere Fleet Deployment | Temperature-controlled container investments preserve myoglobin stability for chilled beef premium-tier positioning. |
| Blockchain Traceability Integration | Digital provenance systems align with MOHAP verification requirements and compress Gulf port clearance timelines. |
| Processed Meat Formulation Expansion | Extended-shelf-life product development captures institutional food service contracts beyond raw commodity competition. |
| Free-Zone Cold Storage Partnership | Jebel Ali bonded warehousing enables regional re-export economics without repeated customs processing. |
Research Methodology
Multi-period observation of slaughterhouse accreditation timelines, cold-chain fleet deployment rates, and halal certification processing backlogs anchored the trend analysis, supplemented by interviews with livestock procurement directors at Saudi hotel chains, UAE supermarket category managers, Brazilian packer export sales teams, Dubai free-zone logistics operators, and SFDA compliance consultants. Secondary validation drew from GCC customs trade databases, SFDA regulatory filings, MOHAP digital transformation disclosures, and livestock industry association statistics. Bottom-up channel volume estimates triangulated against top-down protein consumption benchmarks.
Segment-weighting across product type, packaging format, distribution channel, and end-user category structured the analytical framework across the projection horizon. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-segment consistency checks enforcing coherence. Industry-specific forecast inputs incorporated tourism infrastructure pipeline data for Saudi Arabia and UAE, plus livestock self-sufficiency target announcements from Gulf agricultural ministries.
Underlying measurement precision varies by segment; wholesale channel throughput estimates carry tighter precision than online store penetration projections given data availability. Forecasts reflect documented assumptions about accreditation processing efficiency and cold-chain infrastructure investment continuity. Regulatory enforcement intensity shifts, feed grain commodity cycles, and domestic poultry substitution acceleration warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Global Red Meat Market
Meat Products
Chicken Fat Market
Meat Products
Meat Packaging Market
Meat Products
Brazil Meat Products Market
Meat Products
Beef Fat Powder Market
Meat Products
France Meat Products Market
Meat Products
Smokehouse Market
Meat Products
Germany Meat Products Market
Meat Products
Organic Lamb Market
Meat Products
Beef Bouillon Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Raw Chicken Feet Market
Meat Products
United Arab Emirates Red Meat Market
Meat Products
Low-Fat Ham Market
Meat Products
Europe Bacon Market
Meat Products
Asia-Pacific Low Fat Sausage Market