
 Hot Dog and Sausages Market | 2026-2036
Hot Dog and Sausages Market Size, Share, and Industry Trends Forecast 2026-2036
Hot Dog and Sausages Market Analysis
Convenience store foodservice is repositioning hot dogs from commodity grab-and-go items to premium prepared-meal offerings. Tyson Foods leverages its integrated poultry supply chain to dominate chicken sausage production at scale. Hormel Foods anchors its portfolio in branded retail presence through Spam and Natural Choice extensions. Smithfield Foods controls pork raw material flows across multiple processing tiers, sustaining margin capture from farm to packaged goods.
Hot dogs and sausages comprise emulsified or coarsely ground meat mixtures stuffed into casings, typically containing 60-80% meat protein with fat, water, and seasoning binders, then thermally processed to achieve specific pH and water activity targets for shelf stability and food safety. The product type dimension shows pork sausages occupying the largest volume share due to cost-efficient raw material availability, while chicken sausages represent the fastest-growing margin pool as health-positioned consumers shift toward lower-fat protein formats. Distribution channel dynamics reveal supermarkets defending their core position through private-label expansion, even as online retailers capture incremental growth in subscription-based meat box deliveries.
USDA FSIS inspection protocols and HACCP mandates govern slaughter-to-package traceability, while FDA oversight of ingredient labeling and sodium disclosure rules shapes front-of-package marketing claims. The EU Hygiene Regulation and CE marking requirements for meat processing equipment create compliance thresholds that filter export market access for non-European producers. Stakeholders must monitor evolving sodium reduction mandates and alternative protein labeling classifications as regulatory divergence between jurisdictions intensifies formulation complexity.
Market Dynamics
Clean-label reformulation mandates from the FDA and USDA are compressing formulation timelines while raw material concentration in Midwest pork processing clusters creates procurement bottlenecks for mid-tier sausage manufacturers.
Growth Catalysts
- USDA HACCP modernization:Updated pathogen reduction standards are forcing automation upgrades that simultaneously cut labor costs and expand production capacity for compliant processors.
- Convenience store foodservice expansion:C-store chains are installing roller-grill equipment and dedicated hot dog preparation stations, creating incremental prepared-meal revenue streams.
- Plant protein extrusion advances:High-moisture extrusion technology is improving the fibrous texture of alternative sausages, narrowing the sensory gap with animal-based products.
Market Restraints
- Feed grain price volatility:Corn and soybean meal input costs swing with drought cycles in the US Corn Belt, compressing processor margins unpredictably.
- Midwest slaughter capacity concentration:Four states control over sixty percent of US pork processing volume, creating single-point failure risks during plant disruptions.
- Natural casing supply constraints:Sheep intestine availability from New Zealand and Australia faces herd-size limitations and export quota restrictions.
Strategic Opportunities
- Brazilian retail modernization:São Paulo and Rio de Janeiro supermarket chains are expanding refrigerated deli sections, opening branded premium sausage placement.
- Cell-cultured collagen casings:Precision fermentation-derived casing materials eliminate religious slaughter restrictions and supply seasonality.
- Subscription meat box channels:Direct-to-consumer refrigerated logistics now sustain recurring revenue models for artisanal sausage producers.
Industry Challenges
- FSIS label approval timelines:USDA front-of-package claim reviews now stretch sixteen to twenty-four months, delaying product launches.
- Legacy equipment retrofit costs:Sodium reduction targets require reformulation that jams existing stuffing and linking machinery calibrated for traditional binders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hot Dog and Sausages Market |
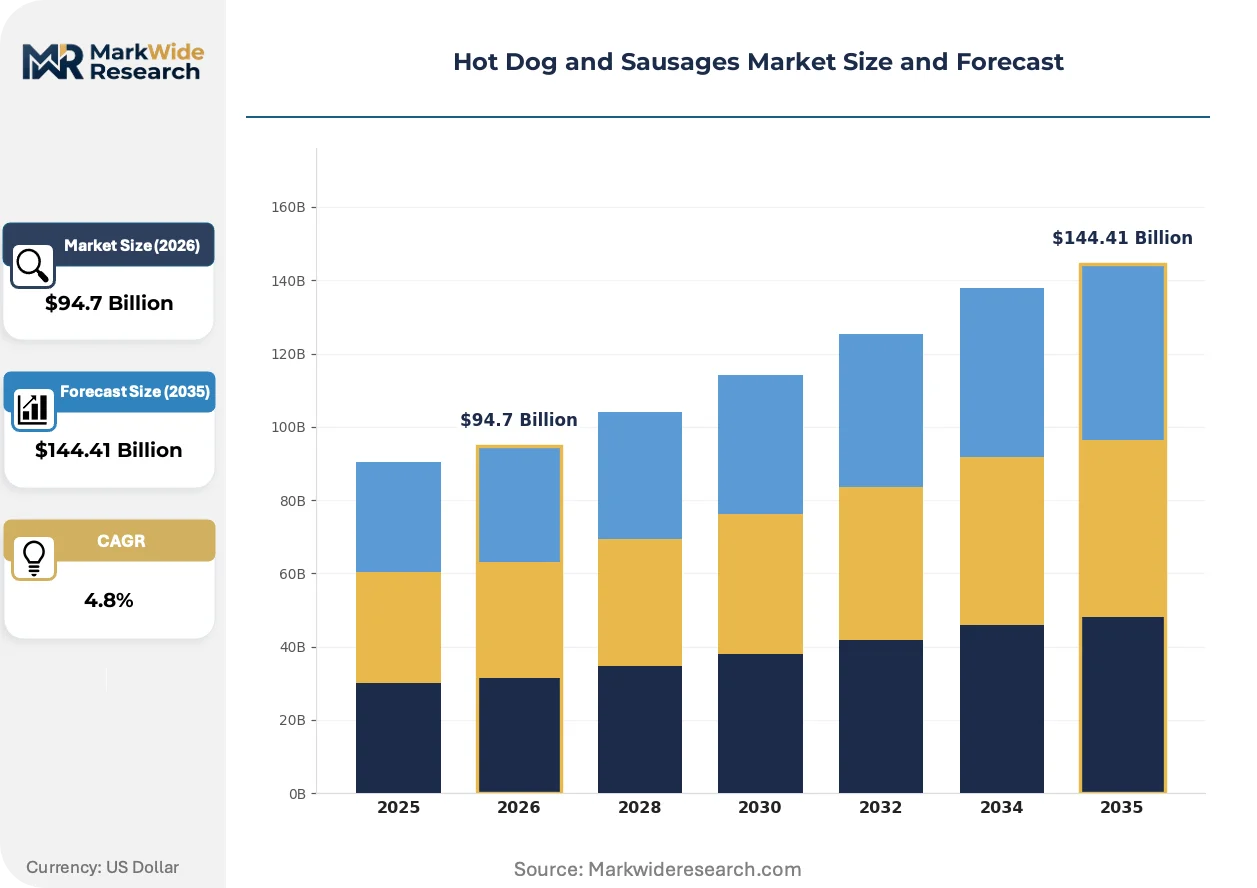
| Market Size in 2026 | $94.7 Billion |
| Market Size in 2035 | $144.41 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pork Sausages, Beef Sausages, Chicken Sausages, Turkey Sausages Flavor Profile: Spicy, Mild, BBQ, Garlic Distribution Channel: Supermarkets, Convenience Stores, Online Retailers, Specialty Stores Preparation Type: Grilled, Boiled, Fried, Smoked |
| Companies Covered | Nathan's Famous, Hormel Foods, Tyson Foods, Ball Park, Hebrew National, Smithfield Foods, Johnsonville, Applegate, Oscar Mayer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hot Dog and Sausages Market Emerging Trajectories
Reformulation chemistry and thermal processing controls are converging to enable sodium reduction without sacrificing shelf stability or eating quality.
High-pressure processing equipment is absorbing validation work previously handled by thermal pasteurization alone. Regional processors in Texas and North Carolina are installing HPP lines to extend refrigerated shelf life for clean-label products. This shift is absorbing capital that would otherwise flow into conventional smokehouse expansion.
EU F-Gas Regulation phase-down schedules are accelerating ammonia refrigeration adoption in European meat processing plants. German and Danish sausage manufacturers face retrofit deadlines that compress equipment replacement cycles. Pork bratwurst and Weisswurst production lines in Bavaria are most affected, with processors sourcing ammonia-compatible chilling tunnels.
Foodservice operators are consolidating protein suppliers to reduce vendor management overhead. Casino and stadium concessionaires now specify single-source contracts for hot dog and sausage categories. This concentration is most visible in Nevada and New Jersey gaming corridors, where procurement teams negotiate multi-year supply agreements with penalty clauses for microbiological failures.
Hot Dog and Sausages Market Segmentation
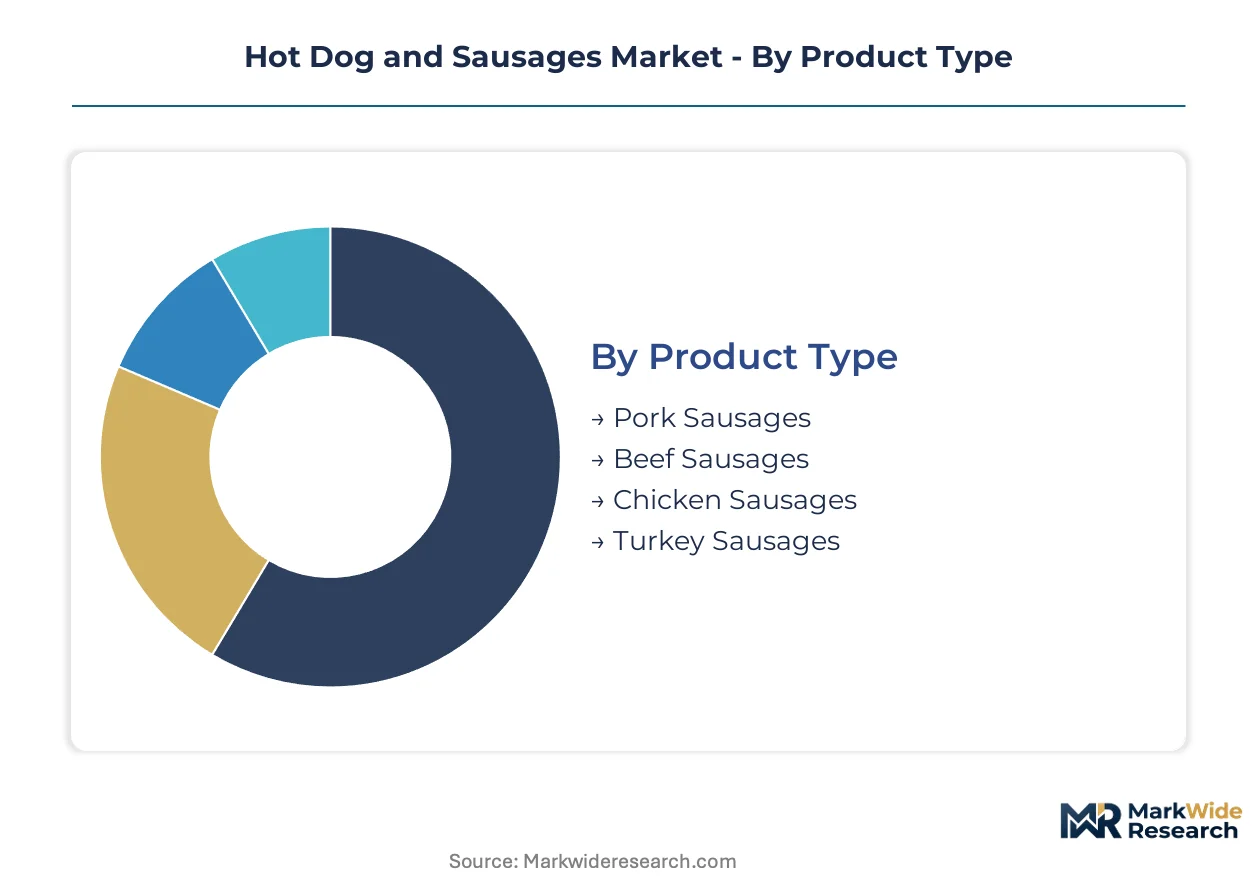
Segmentation in hot dogs and sausages reveals how protein sourcing, thermal processing, and channel access determine margin capture. Buyers prioritize different attributes across foodservice, retail, and direct-to-consumer contexts, forcing manufacturers to align formulation and packaging with specific consumption occasions.
Product Type:
Raw material cost and fat content specifications differentiate buyer priorities across foodservice and retail channels.
- Pork Sausages:Ground pork shoulder and trim formulations with 25-30% fat content deliver cost-efficient emulsion stability for mass-market production. C-store roller-grill programs in the United States and bratwurst consumption in Germany concentrate demand here, though African swine fever outbreaks in Europe periodically disrupt raw material flows.
- Chicken Sausages:Leaner protein profiles with 10-15% fat meet USDA labeling thresholds for "reduced fat" claims. Health-positioned consumers in California and New York metro areas drive refrigerated case placement expansion, with Tyson Foods and Perdue Farms controlling integrated supply chains that compress delivered costs.
- Beef Sausages:Coarse-ground chuck and brisket blends command premium positioning in Texas barbecue culture and Argentine immigrant communities.
- Turkey Sausages:Seasonally concentrated demand peaks around Thanksgiving, with year-round breakfast patty applications sustaining Minnesota and North Carolina processing lines.
Pork sausages lead volumes today; chicken sausages are expanding most quickly.
Flavor Profile:
Application context and regional palate preferences shape procurement decisions across foodservice and retail.
- Spicy:Capsaicin-forward formulations with cayenne or jalapeño puree target Hispanic consumer concentrations in Texas, Arizona, and Florida. QSR breakfast sandwich programs specify Scoville-calibrated heat levels for menu consistency.
- Mild:Neutral seasoning bases with minimal black pepper accommodate children's palates and institutional feeding programs. School nutrition directors in Ohio and Pennsylvania specify mild profiles for compliance with sodium reduction mandates.
- BBQ:Molasses and hickory smoke flavor systems align with summer grilling occasions and regional sauce preferences in Kansas City and Memphis.
- Garlic:European-style fresh sausage demand in Polish and Italian ethnic retail channels sustains niche production runs in Chicago and New Jersey.
Mild formulations dominate current production volumes; spicy profiles show the steepest expansion trajectory.
Distribution Channel:
Cold chain infrastructure requirements and margin structures separate buyer capabilities and scale thresholds.
- Supermarkets:Full-service deli counters and refrigerated meat cases demand case-ready packaging with seven-day shelf life. Kroger and Albertsons private-label programs in the Midwest negotiate annual volume commitments that lock up processor capacity.
- Convenience Stores:Roller-grill equipment and ambient holding capabilities favor skinless, pre-cooked formats with extended stability. 7-Eleven and Circle K expansion into prepared foodservice is repositioning hot dogs from commodity impulse to meal-replacement occasions.
- Online Retailers:Subscription meat box models require insulated shipper validation and dry ice logistics that mid-tier processors struggle to execute profitably.
- Specialty Stores:Artisanal butcher counters and farmers market stalls sustain small-batch production with natural casing and heritage breed sourcing claims.
Supermarkets retain the largest volume position; online retailers are gaining share fastest.
Preparation Type:
Equipment capital requirements and labor intensity determine operator adoption across foodservice segments.
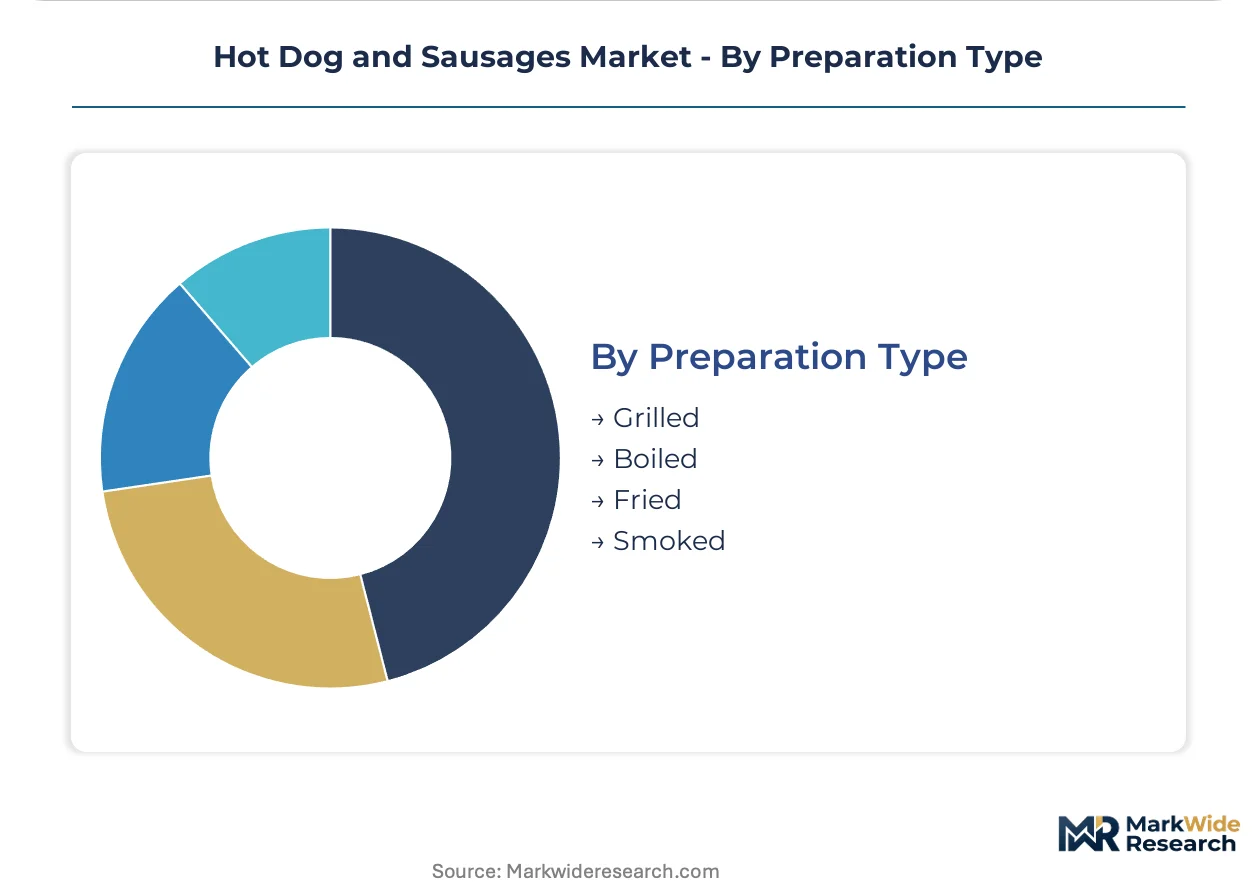
- Grilled:Direct flame or flat-top contact heating develops Maillard browning and char marks valued in outdoor cooking contexts. Home improvement retailers in the United States bundle propane grill sales with branded sausage promotions during Memorial Day and July 4th periods.
- Smoked:Hardwood smokehouse exposure over six to twelve hours delivers shelf stability and flavor complexity for regional styles like Andouille and Kielbasa. North Carolina and Texas processors maintain traditional smokehouse infrastructure that limits throughput scalability.
- Boiled:Simmering in flavored broth or beer serves stadium concessionaires and Oktoberfest vendors requiring batch efficiency and food safety simplicity.
- Fried:Deep-fat immersion produces crisp casings for corn dog applications and county fair foodservice operators.
Grilled preparations anchor current consumption; smoked formats are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are shifting production toward jurisdictions with streamlined food safety approvals and lower compliance costs, while consumer taste localization forces regional formulation adjustments.
United States
Midwest pork processing clusters in Iowa and Illinois supply raw material at scale, though plant concentration creates disruption vulnerabilities. USDA FSIS inspection protocols and HACCP mandates govern slaughter-to-package traceability, with sodium disclosure rules tightening front-of-package marketing constraints. Tyson Foods leverages its Arkansas-based poultry supply chain to dominate chicken sausage production.
Germany
Bratwurst and Weisswurst consumption anchors premium pork sausage demand across Bavaria and Baden-Württemberg. EU F-Gas Regulation phase-down schedules accelerate ammonia refrigeration retrofits in meat processing plants, compressing equipment replacement cycles for Bavarian processors. Munich and Nuremberg maintain traditional smokehouse infrastructure for regional specialty production.
Brazil
São Paulo and Rio de Janeiro supermarket chains expand refrigerated deli sections, opening branded premium sausage placement for both domestic and imported products. ANVISA oversees ingredient labeling and food safety standards, with compliance thresholds filtering market access for non-Brazilian producers. Southern Brazil's pork production belt around Santa Catarina feeds industrial processing capacity.
China
Urban middle-class expansion in Shanghai and Beijing drives demand for Western-style sausage formats alongside traditional cured pork products. SAMR and GB standards govern meat processing equipment certification and food safety protocols. Yangtze River Delta processors are adopting high-pressure processing lines to extend shelf life for clean-label retail products.
Australia
Natural casing supply from sheep intestine faces herd-size limitations and export quota restrictions, compressing availability for premium sausage producers. TGA-equivalent food standards and biosecurity protocols regulate import flows. Victorian and New South Wales processors are piloting cell-cultured collagen casings to circumvent religious slaughter restrictions and supply seasonality.
Hot Dog and Sausages Market Vendor Landscape
Capacity expansion dominates the current landscape as processors automate to meet USDA HACCP modernization requirements. The market structure consolidates around integrated protein conglomerates controlling upstream raw material flows, mid-tier regional specialists with smokehouse differentiation, and emerging alternative protein entrants. Strategic archetypes include scale-driven integrators, heritage-brand regionalists, and technology-forward reformulators. M&A activity and vertical integration into captive supply chains represent the dominant competitive moves as margin pressure intensifies.
Among US-based protein conglomerates, Tyson Foods and Hormel Foods exemplify scale-driven integration archetypes, while Smithfield Foods anchors the pork-specialist tier. Johnsonville occupies a position within the heritage-brand regionalist category. These entities represent competitive positioning patterns rather than specific strategic commitments, with each archetype facing distinct pressures from clean-label reformulation mandates and alternative protein displacement.
| Leading Market Players |
|---|
| Nathan's Famous |
| Hormel Foods |
| Tyson Foods |
| Ball Park |
| Hebrew National |
| Smithfield Foods |
| Johnsonville |
| Applegate |
| Oscar Mayer |
| Others |
Supply Flow & Price Mechanics
Family-owned mid-cap processors in Bavaria and the American Midwest anchor supply discipline through generational capital allocation, insulating pricing power from quarterly earnings pressure while concentrating procurement leverage over sheep intestine suppliers and feed grain elevators.
Pricing Analysis
Distributor margin capture dominates the channel stack, with broadline foodservice distributors extracting 18-25 points before retailer markup. Three-tier pricing structure across premium, standard, and economy levels separates natural-casing artisanal products from skinless roller-grill formats and private-label commodity cases. Cost compression in the economy tier is intensifying because corn and soybean meal input volatility transmits directly to processor quotes. Institutional feeding programs in Ohio and Pennsylvania exhibit the highest price sensitivity, while casino concessionaires in Nevada negotiate multi-year contracts with microbiological penalty clauses that prioritize supply assurance over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with New Zealand and Australian sheep intestine harvesters, where herd-size limitations and export quota restrictions compress natural casing availability for premium sausage producers. Iowa, Illinois, and Santa Catarina anchor global pork raw material flows, with four US states controlling over sixty percent of domestic slaughter volume. Midwest concentration creates single-point failure risks during plant disruptions or disease outbreaks. Distribution runs through temperature-controlled broadline networks serving supermarket deli counters and convenience store foodservice operations, with direct-to-consumer subscription channels requiring insulated shipper validation that mid-tier processors struggle to execute profitably.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Health-positioned consumers in California and New York metro areas are shifting demand toward reduced-fat chicken sausages with clean-label ingredient declarations.
For Market Incumbents: Cement backward integration into captive poultry supply chains to match Tyson Foods' cost structure and defend share against alternative protein displacement. Invest in high-pressure processing equipment to extend refrigerated shelf life for clean-label products without sodium-dependent thermal pasteurization. Prioritize ammonia-compatible chilling tunnel retrofits ahead of EU F-Gas Regulation deadlines affecting German and Danish competitors. For New Entrants and Emerging Players: Launch via subscription meat box channels targeting artisanal sausage segments where incumbent logistics capabilities lag. São Paulo and Rio de Janeiro supermarket chains expanding refrigerated deli sections offer the most penetrable white-space for branded premium placement. Lead with cell-cultured collagen casing technology to circumvent religious slaughter restrictions and natural casing supply seasonality. For Investors and Strategic Acquirers: Valuations sit cheapest among heritage-brand regionalists with smokehouse differentiation but limited national distribution infrastructure. The five-to-ten year viability window favors processors with USDA HACCP modernization compliance already deployed. Target acquisition archetypes include Bavarian bratwurst specialists facing ammonia refrigeration retrofit deadlines and Texas barbecue-culture beef sausage producers with authentic smokehouse assets. Watch for inflection when FSIS label approval timelines compress from current sixteen-to-twenty-four month stretches.| Strategic Initiative | Industry Significance |
|---|---|
| High-Pressure Processing Equipment Installation | Extends refrigerated shelf life for clean-label products without sodium-dependent binders. |
| Cell-Cultured Collagen Casing Development | Eliminates religious slaughter restrictions and New Zealand sheep intestine supply seasonality. |
| Ammonia Refrigeration Retrofit | Ensures EU F-Gas Regulation compliance for Bavarian and Danish processing facilities. |
| Subscription Meat Box Channel Launch | Captures recurring revenue from health-positioned consumers in coastal metro markets. |
| Backward Integration into Poultry Supply | Matches Tyson Foods' integrated cost structure in chicken sausage production. |
Methodological Framework
Bottom-up foodservice and retail channel modeling reconciled against top-down slaughter capacity and raw material flow tracking forms the analytical core. Primary interviews with sausage plant managers, supermarket category buyers, convenience store foodservice directors, USDA FSIS compliance officers, and natural casing importers combined with secondary validation from FDA labeling guidance documents, USDA HACCP modernization directives, EU F-Gas Regulation schedules, ANVISA standards, and customs trade data. Triangulation across these sources calibrated volume and value estimates.
Input-output matrices mapped protein sourcing through thermal processing to channel placement across the projection horizon. Segmentation dimensions modeled include protein type, flavor profile, preparation method, and distribution channel, with regional regulatory clusters capturing FDA, USDA, EU Hygiene Regulation, and ANVISA compliance thresholds. CAGRs derived from elasticity-adjusted demand curves and capacity expansion pipelines, incorporating feed grain price volatility and clean-label reformulation adoption curves as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under African swine fever resurgence in Europe or Midwest plant disruption scenarios. Forecasts reflect assumptions about HACCP modernization adoption rates and alternative protein sensory parity achievement. Regulatory divergence between FDA and EU labeling standards, feed grain drought cycles, and natural casing export quota revisions constitute primary revision risks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Global Duck Meats Market
Meat Products
Grass-Fed Meat Market
Meat Products
Low-Fat Chorizo Market
Meat Products
Middle East Red Meat Market
Meat Products
Canned Pork Market
Meat Products
India Poultry Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Organic Lamb Market
Meat Products
Reduced Fat Meat Market
Meat Products
Global Processed Pork Meat Market
Meat Products
US Meat Market
Meat Products
Meat Paste Market
Meat Products
Rendered Poultry Products Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Beef Extract Market