
 North America Edible Meat Market | 2026-2036
North America Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
North America Edible Meat Market Analytics
Asset-light contract processing and third-party cold-chain leasing is reshaping capital deployment across the North America edible meat value chain, allowing mid-scale entrants to bypass legacy plant ownership burdens. Tyson Foods Inc. leverages vertical integration from feedlot to case-ready retail to sustain margin capture through volatile cattle cycles. JBS USA Holdings Inc. anchors its competitive position through massive beef and pork slaughter capacity concentrated in the High Plains and Midwest. Cargill Inc. differentiates via protein diversification and food-service formulation expertise that extends beyond commodity cuts into value-added ingredients.
Edible meat comprises skeletal muscle tissue and associated fat suitable for human consumption, typically processed through slaughter, chilling, aging, and fabrication into primal and sub-primal cuts with moisture content, pH levels, and marbling scores determining functional performance in cooking applications. The product type dimension shows beef occupying the highest value tier due to Prime and Choice grade premiums, while chicken sustains volume leadership through breast and wing demand from quick-service restaurant chains. Distribution channel dynamics reveal supermarkets defending share through private-label case-ready programs, though online retail represents the fastest-growing outlet as direct-to-consumer subscription models gain traction among households seeking transparency in sourcing and handling protocols.
USDA Agricultural Marketing Service grading standards and Food Safety and Inspection Service pathogen reduction mandates shape product specifications and plant certification requirements across the United States, while CFIA oversight in Canada enforces parallel but distinct safety verification systems that suppliers must navigate for cross-border trade. State-level environmental discharge permits and odor regulations in Nebraska, Kansas, and North Carolina further constrain greenfield processing expansion. Stakeholders must monitor evolving cultured-meat labeling battles and methane-emission disclosure rules that could redefine competitive boundaries between conventional and alternative protein platforms.
Market Dynamics
Capital-light processing models and third-party cold-chain infrastructure are compressing barriers to entry across the North America edible meat value chain, enabling regional packers to challenge legacy integrated processors without owning slaughter capacity.
Growth Catalysts
- FSIS Modernized Inspection:The USDA Food Safety and Inspection Service updated swine slaughter inspection protocols, allowing plant-level innovation in food safety technologies that accelerates line speeds while maintaining pathogen control standards.
- Quick-service protein demand:Major restaurant chains in the United States are expanding chicken wing and breast formulations, pulling volume through dedicated further-processing lines and contract grower arrangements.
- Texas-Oklahoma cattle corridor concentration:Feedlot density in this region creates procurement efficiencies and captive supply relationships that stabilize input costs for beef processors operating nearby plants.
Market Restraints
- Feed grain cost volatility:Corn and soybean meal price swings in the Midwest directly compress margins for integrated poultry and pork operations that lack long-term grain hedging programs.
- Slaughter capacity concentration:Four firms control the majority of federally inspected beef slaughter in the United States, creating bottleneck risks during plant disruptions or labor stoppages.
- Cultured meat substitution:Laboratory-grown protein alternatives are capturing venture funding and regulatory attention, threatening conventional meat's share in premium consumer segments.
Strategic Opportunities
- Direct-to-consumer subscription channels:Online retail platforms are enabling ranchers and small processors to bypass traditional distribution, capturing margin through branded boxed beef programs with transparent sourcing claims.
- Value-added ingredient formulations:Food-service operators are demanding pre-cooked, pre-seasoned protein components that extend meat processors into prepared foods beyond commodity primal cuts.
- Canadian cross-border expansion:CFIA equivalency agreements with USDA create pathways for U.S. processors to serve Canadian retail and food-service accounts with minimal additional certification burden.
Industry Challenges
- HACCP validation timelines:New plant startups face extended USDA approval cycles for Hazard Analysis Critical Control Point plans, delaying revenue generation and stretching working capital.
- Skilled maintenance technician scarcity:Automated slaughter and fabrication equipment requires specialized repair expertise that rural processing communities struggle to attract and retain.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Edible Meat Market |
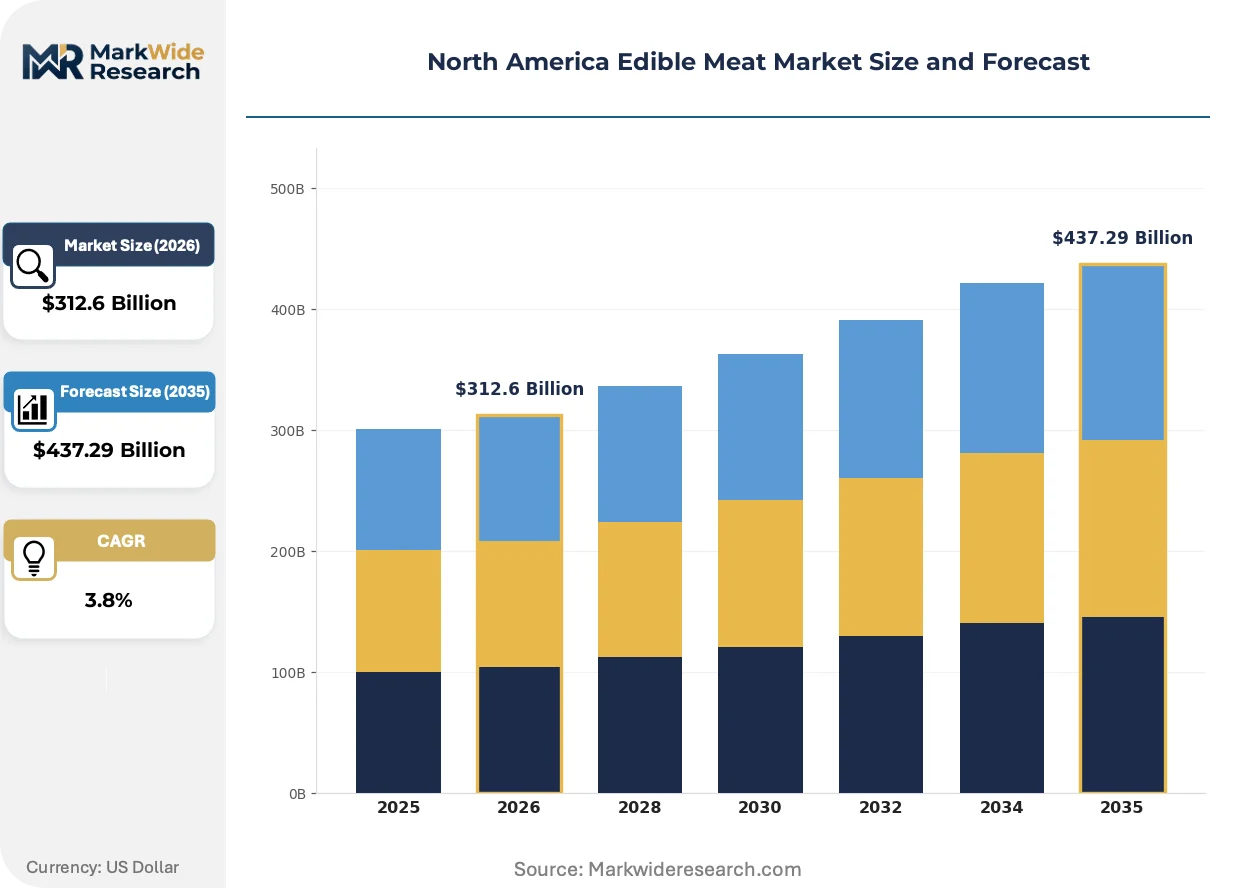
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $437.29 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Pork, Chicken, Turkey Distribution Channel: Supermarkets, Convenience Stores, Online Retail, Restaurants End User: Households, Food Service, Retailers, Processors Quality Grade: Prime, Choice, Select, Standard |
| Companies Covered | Tyson Foods Inc., JBS USA Holdings Inc., Cargill Inc., Smithfield Foods Inc., Hormel Foods Corporation, National Beef Packing Company, Conagra Brands Inc., Perdue Farms, OSI Group, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Edible Meat Market Evolving Landscape
Automation and data-capture technologies are transforming how carcasses move through North American plants, while regulatory disclosure requirements and shifting procurement patterns reshape competitive positioning.
Computer vision systems integrated with robotic carcass splitting and primal fabrication are rendering obsolete manual knife-work stations that dominated beef and pork processing for decades. Mid-scale packers in Nebraska and Kansas are deploying these systems to achieve yield consistency matching larger competitors. The technology compresses labor requirements while improving cut accuracy for case-ready retail programs.
USDA Agricultural Marketing Service is mandating enhanced country-of-origin labeling enforcement and electronic traceability integration for ground beef products. This policy forces processors to reconfigure lot-tracking systems and supplier documentation protocols. Smaller grinding operations in the Southeast face disproportionate compliance costs relative to integrated chains with existing ERP infrastructure.
Food-service distributors are consolidating procurement into fewer, larger protein suppliers capable of delivering multi-species, specification-grade consistency across national account footprints. This concentration displaces fragmented regional meat vendors that historically served independent restaurants. The shift is most visible in the Southwest, where casino and hospitality chains demand single-source accountability for beef, pork, and poultry programs.
North America Edible Meat Market Segmentation
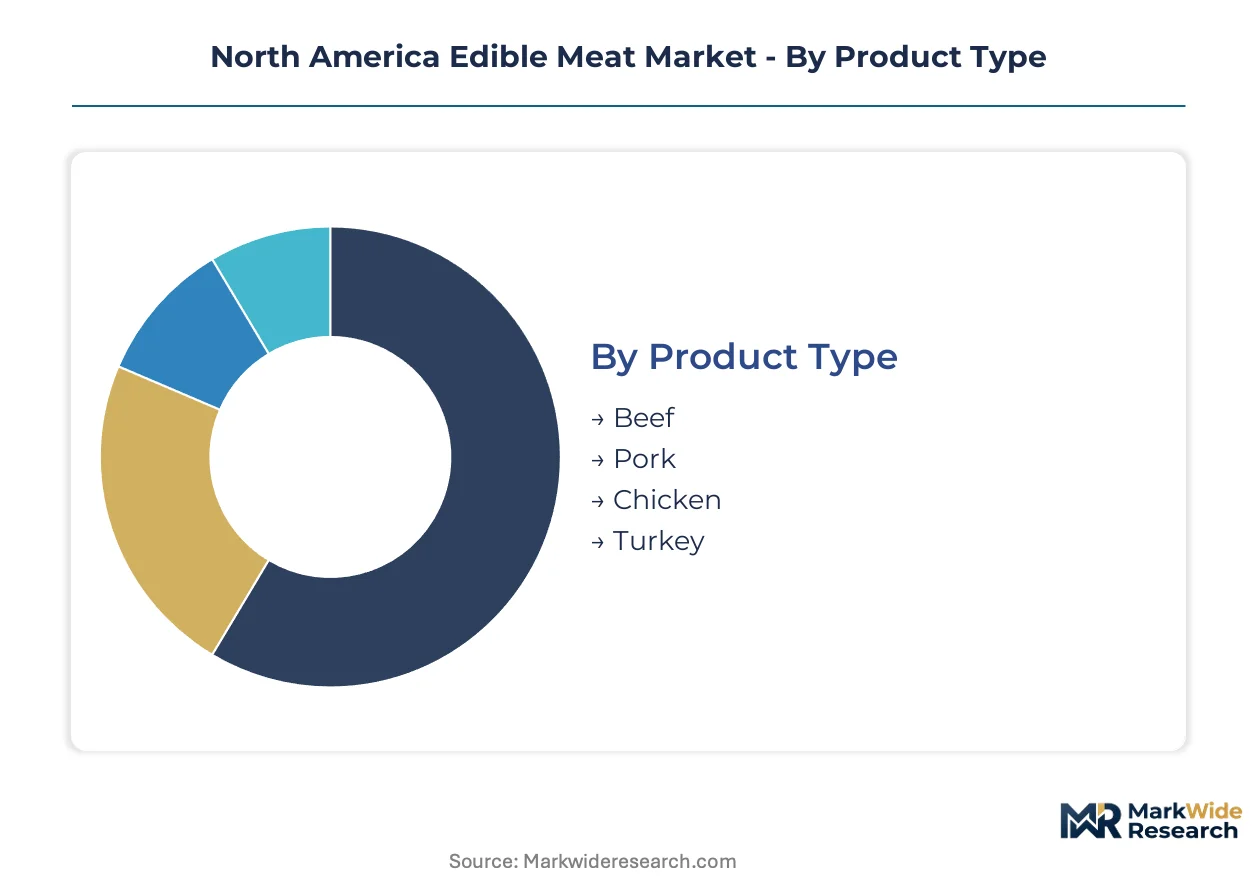
Edible meat segmentation in North America reflects divergent procurement economics across species, channel control points, and USDA grading tiers that determine margin capture. Understanding these divisions reveals where capital deployment concentrates and which specifications command pricing power.
Product Type:
Species selection spans commodity cycles, feed conversion efficiency, and quick-service menu formulation requirements.
- Beef:Skeletal muscle from cattle graded by USDA Agricultural Marketing Service marbling scores and maturity indices. Demand concentrates in the Texas-Oklahoma feedlot corridor where captive supply agreements with major packers stabilize input costs for Prime and Choice programs.
- Chicken:Broiler breast and wing cuts dominate quick-service restaurant procurement, with further-processing lines in Georgia and Arkansas pulling volume through dedicated grower contracts. White meat yield efficiency and line-speed automation sustain margin compression tolerance unmatched by red meat alternatives.
- Pork:Carcass fabrication into primal cuts centers on Iowa-Minnesota processing belt density, with loin and belly demand driven by bacon-forward menu engineering across casual dining chains.
- Turkey:Ground and whole-bird categories serve seasonal retail windows and prepared foods ingredient supply, with Minnesota and North Carolina housing vertically integrated production clusters.
The dominant share belongs to Chicken, while Beef is closing the gap fastest through premium grade segmentation.
Distribution Channel:
Channel economics vary by inventory turnover velocity, cold-chain infrastructure requirements, and private-label penetration depth.
- Supermarkets:Case-ready retail programs and private-label grinding operations defend volume through centralized distribution centers. Chains in the Midwest and Northeast leverage direct packer relationships to bypass wholesale markup layers.
- Restaurants:Food-service distributors consolidate procurement into specification-grade, multi-species suppliers capable of national account consistency. Casino and hospitality chains in the Southwest demand single-source accountability across protein categories.
- Online Retail:Direct-to-consumer subscription platforms enable ranchers and small processors to capture margin through branded boxed beef with transparent sourcing claims. Cold-chain last-mile infrastructure constraints limit geographic reach.
- Convenience Stores:Grab-and-go prepared protein and roller-grill items drive turn velocity, with limited refrigeration footprint favoring shelf-stable or short-dated inventory models.
Supermarkets retain volume leadership, though Online Retail is expanding most quickly through subscription loyalty models.
End User:
User categories reflect divergent specification complexity, volume scale, and supplier relationship intensity.
- Food Service:Operators demand pre-cooked, pre-seasoned protein components that extend processors into prepared foods beyond commodity primal cuts. National account consolidation favors suppliers with multi-species capability.
- Households:Direct purchasing through retail and subscription channels prioritizes transparency in sourcing, handling protocols, and animal welfare claims. Premium grade willingness varies by income geography.
- Retailers:Supermarket and club store buyers negotiate case-ready specifications, private-label development, and promotional calendar alignment with packer production schedules.
- Processors:Further-processing facilities purchase primal and sub-primal inputs for conversion into value-added ingredients, requiring consistent specification-grade supply for formulation stability.
Food Service commands the highest specification intensity, while Households are gaining purchasing autonomy fastest through disintermediation.
Quality Grade:
USDA grading tiers stratify pricing power through measurable carcass characteristics and consumer willingness to pay for eating quality.
- Prime:Highest marbling scores deliver tenderness and flavor premiums for white-tablecloth restaurants and specialty retail. Limited supply concentration in corn-finished Midwest feedlots sustains scarcity positioning.
- Choice:Moderate marbling balances quality and accessibility, anchoring supermarket premium tiers and casual dining menu engineering. Volume availability supports promotional flexibility.
- Select:Leaner profiles serve health-positioned retail programs and institutional procurement with cost constraints. Requires mechanical tenderization or marinade intervention for acceptable eating quality.
- Standard:Ungraded or utility-tier product enters manufacturing, pet food, and export commodity channels with minimal value-added capture.
Choice holds the volume advantage, while Prime is climbing the fastest through experience-driven dining segmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
USDA grading protocol updates and FSIS modernization programs are redirecting capital toward compliant processing infrastructure. CFIA equivalency frameworks enable cross-border supply continuity. State-level environmental discharge rules constrain greenfield expansion in key producing regions.
United States
Quick-service restaurant chains pull chicken breast and wing volume through dedicated Georgia and Arkansas grower contracts. The USDA Food Safety and Inspection Service mandates enhanced electronic traceability for ground beef lot-tracking. The Texas-Oklahoma feedlot corridor concentrates Prime and Choice grade supply for major packer procurement.
Canada
Canadian retail and food-service accounts seek multi-species suppliers under CFIA equivalency agreements with USDA. Health Canada and the Canadian Food Inspection Agency enforce parallel pathogen reduction mandates that mirror FSIS standards. Alberta and Manitoba house beef processing clusters serving both domestic distribution and U.S. export channels.
Mexico
Northern Mexico cattle feeders supply cross-border beef fabrication to U.S. Southwest processors. The country's federal sanitary regulator oversees slaughter facility certification for export eligibility. Sonora and Chihuahua concentrate feedlot density supporting integrated supply chains.
North America Edible Meat Market Competitive Landscape
On the supply side, the industry is consolidating around four dominant packers controlling federally inspected beef slaughter capacity, with mid-scale regional entrants challenging through asset-light contract processing models. Strategic archetypes include vertically integrated feedlot-to-retail operators, diversified protein conglomerates spanning beef-pork-poultry, and specialized further-processing ingredient suppliers. Competitive moves center on captive supply relationships with feedlot operators and cold-chain infrastructure partnerships that bypass legacy plant ownership.
Among U.S.-based integrated processors, Tyson Foods Inc., JBS USA Holdings Inc., and Cargill Inc. occupy positions reflecting distinct strategic emphases: Tyson exemplifies vertical control from feedlot operations through case-ready retail distribution; JBS anchors massive slaughter capacity concentration in the High Plains and Midwest; Cargill represents protein diversification extending into food-service formulation expertise. These three entities collectively illustrate how scale, integration depth, and product breadth define competitive positioning in North American meat processing.
| Leading Market Players |
|---|
| Tyson Foods Inc. |
| JBS USA Holdings Inc. |
| Cargill Inc. |
| Smithfield Foods Inc. |
| Hormel Foods Corporation |
| National Beef Packing Company |
| Conagra Brands Inc. |
| Perdue Farms |
| OSI Group |
| Others |
Value Network & Pricing Analysis
The I-35 freight corridor connecting Texas feedlots to Midwest processing plants shapes cost dynamics across the North America edible meat value chain, concentrating pricing power among packers with captive supply agreements while forcing downstream differentiation through USDA grade premiums.
Pricing Analysis
USDA quality grade certification creates the primary spread between Prime, Choice, and Select tiers, with marbling scores determining contract premiums in food-service procurement. Three-tier pricing structure across premium, standard, and economy levels governs spot and contract markets, though feed grain cost volatility is compressing margins in poultry operations lacking long-term hedging programs. Quick-service restaurant chains exhibit highest price sensitivity through volume-driven breast and wing contracts, while white-tablecloth operators absorb Prime grade premiums with minimal elasticity.
Supply Chain Analysis
Contract processing concentration among Tyson Foods, JBS USA, and Cargill controls federally inspected beef slaughter capacity across the United States. Geographic supply concentration centers on the Texas-Oklahoma cattle corridor, the Iowa-Minnesota pork belt, and Georgia-Arkansas poultry clusters. Raw material dependencies rest on corn and soybean meal from Midwest grain elevators, live cattle from captive feedlot arrangements, and specialized packaging films. Single-source vulnerability around four-firm slaughter concentration creates bottleneck exposure during plant disruptions. Distribution runs through food-service distributors, supermarket centralized distribution centers, and emerging direct-to-consumer cold-chain platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America edible meat market sits in early-cycle expansion as direct-to-consumer subscription models penetrate household procurement and asset-light processing enables regional packer entry.
For Market Incumbents: Insulate margin capture through backward integration into feedlot operations and case-ready retail distribution, countering mid-scale entrants leveraging third-party cold-chain leasing. Deepen captive supply relationships in the Texas-Oklahoma corridor to stabilize input costs against commodity volatility. Prioritize FSIS-compliant automation investments to defend throughput advantages as labor scarcity intensifies. For New Entrants and Emerging Players: Canadian cross-border food-service accounts under USDA-CFIA equivalency agreements represent the most penetrable white-space opportunity, requiring minimal incremental certification burden. Target direct-to-consumer subscription channels in underserved metropolitan markets with transparent sourcing claims and branded boxed beef programs. Deploy asset-light contract processing models to bypass legacy plant capital requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized further-processing ingredient suppliers with food-service formulation expertise beyond commodity cuts. Long-term viability hinges on protein diversification capability and regulatory compliance infrastructure across species. Watch cultured-meat labeling battles and methane-emission disclosure rules as inflection indicators for conventional versus alternative protein competitive boundaries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedlot Operations | Tyson Foods leverages captive cattle supply to stabilize Prime grade input costs through volatile cycles. |
| Direct-to-Consumer Subscription Launch | Regional packers capture margin through branded boxed beef with transparent sourcing claims bypassing wholesale markup. |
| FSIS-Compliant Automation Deployment | Computer vision and robotic fabrication compress labor requirements while improving yield consistency for case-ready retail. |
| Canadian Cross-Border Expansion | USDA-CFIA equivalency agreements enable multi-species supply to Canadian retail accounts with minimal certification burden. |
| Value-Added Ingredient Formulation | Pre-cooked protein components extend processors into prepared foods beyond commodity primal cuts for food-service distributors. |
Research Methodology
The analysis maps beef, pork, poultry, and turkey sub-sectors, each validated through plant operations managers, food-service procurement directors, feedlot operators, and supermarket category buyers. Primary interviews with these stakeholders combined secondary validation through USDA Agricultural Marketing Service grading data, FSIS inspection records, CFIA equivalency documentation, and SEC filings from publicly traded processors. Bottom-up volume triangulation across feedlot capacity, slaughter plant throughput, and retail scanner data converged with top-down value estimation from trade flow analysis and channel margin structures.
Forecast assumptions held feed grain price volatility within historical bands and regulatory enforcement intensity at current levels across the projection horizon. Segmentation dimensions modeled include species type, USDA quality grade tier, distribution channel, and end-user specification intensity. CAGRs derived from elasticity-adjusted volume projections and price pass-through coefficients incorporating feed cost transmission lags. Industry-specific inputs encompassed quick-service restaurant menu engineering cycles and captive supply contract renewal patterns.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by mid-scale regional packers or rapid cultured-meat regulatory approval would shift outcomes substantially. Cross-checking against USDA National Agricultural Statistics Service cattle inventory reports and restaurant industry protein procurement surveys is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Non-Veg Rte and Rtc Market
Meat Products
Organic Meat Market
Meat Products
Organic Lamb Market
Meat Products
Emulsified Meat Market
Meat Products
Shark Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Europe Edible Meat Market
Meat Products
Edible Offal Market
Meat Products
Antibiotic Free Meat Market
Meat Products
India Poultry Meat Market
Meat Products
Qatar Poultry Meat Market
Meat Products
United States Red Meat Market
Meat Products
Meat Ingredients Market
Meat Products
Beef Jerky Market
Meat Products
Fresh Organic Chicken Market
Meat Products
North America Processed Pork Meat Market