
 Meat-Based FPP Market | 2026-2036
Meat-Based FPP Market Size, Share, and Industry Trends Forecast 2026-2036
Meat-Based FPP Market Intelligence
Premium-grade clean-label specifications is redrawing competitive boundaries in meat-based further processed products. JBS SA leverages its integrated cattle-to-case-ready supply chain to dominate high-margin retail programs across North America and Brazil. Tyson Foods, Inc. anchors its position through R&D intensity in antibiotic-free and no-antibiotics-ever product lines. WH Group Limited specializes in scale manufacturing of standardized sausage and patty formats for European and Asian quick-service accounts.
Meat-based further processed products encompass animal-derived proteins that undergo secondary manufacturing—grinding, emulsifying, smoking, curing, or forming—into value-added formats with defined fat-to-lean ratios, water-holding capacities, and shelf-life parameters intended for commercial food preparation or direct consumer sale. Sausages and meat patties represent mature volume categories where margin compression from commodity input costs has intensified, while marinated ready-to-cook cuts and jerky occupy faster-growing premium positions driven by convenience-seeking households and protein-snacking trends. Vacuum packaging and freezing techniques sustain extended distribution reach, though fermented and smoked formats command higher price realization due to artisan positioning and shorter ingredient declarations.
FDA inspection mandates and USDA-FSIS pathogen performance standards shape product safety protocols and lot-release testing burdens for US-based processors, while EFSA additive authorizations and EU MDR-derived labeling requirements govern market access across European member states. Saudi Arabia's SFDA halal certification protocols and MOHAP import specifications in the UAE create dual compliance thresholds for Middle East-bound exports. Stakeholders must monitor how ammonia refrigeration retrofits interact with existing plant layouts and whether clean-label reformulation investments translate into sustained price premiums versus private-label alternatives.
Market Dynamics
Quick Service Restaurants are driving procurement of marinated and smoked meat formats as labor costs in commercial kitchens compress operating margins and force automation of preparation steps.
Growth Catalysts
- EU F-Gas Regulation:The phasedown of hydrofluorocarbon cooling systems is pushing processors toward ammonia-based refrigeration retrofits, creating equipment upgrade cycles across European facilities.
- Protein-snacking household behavior:Convenience-seeking consumers are pulling marinated ready-to-cook cuts and jerky into faster-growing premium positions within retail assortments.
- Saudi Arabia production scaling:Tanmiah Food Company and Almunajem Foods are expanding domestic value-added poultry and red meat capacity to capture import substitution demand.
Market Restraints
- Commodity input cost volatility:Fat-to-lean ratio specifications and water-holding capacity requirements tie processor margins to live cattle and feed grain price swings.
- Dual compliance thresholds:Saudi SFDA halal certification protocols layered with UAE MOHAP import specifications create redundant testing burdens for Middle East-bound exports.
- Clean-label reformulation cost:Shorter ingredient declarations and antibiotic-free positioning require R&D intensity that compresses returns against private-label alternatives.
Strategic Opportunities
- Ammonia refrigeration convergence:Ammonia-based cooling retrofits intersect with plant layout optimization to unlock energy efficiency gains in legacy facilities.
- Vacuum packaging channel expansion:Extended distribution reach through advanced freezing techniques opens foodservice accounts previously limited by shelf-life constraints.
- Artisan smoked format premiumization:Fermented and smoked products with defined curing parameters command price realization gaps in specialty retail.
Industry Challenges
- Lot-release testing capacity:FDA inspection mandates and USDA-FSIS pathogen performance standards strain laboratory throughput and extend batch clearance timelines.
- EFSA additive authorization navigation:European member state labeling requirements derived from EU MDR create formulation lock-in effects that delay product line refreshes.
- Halal certification audit complexity:Multi-jurisdictional religious compliance documentation requires dedicated quality assurance functions that smaller processors struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Meat-Based FPP Market |
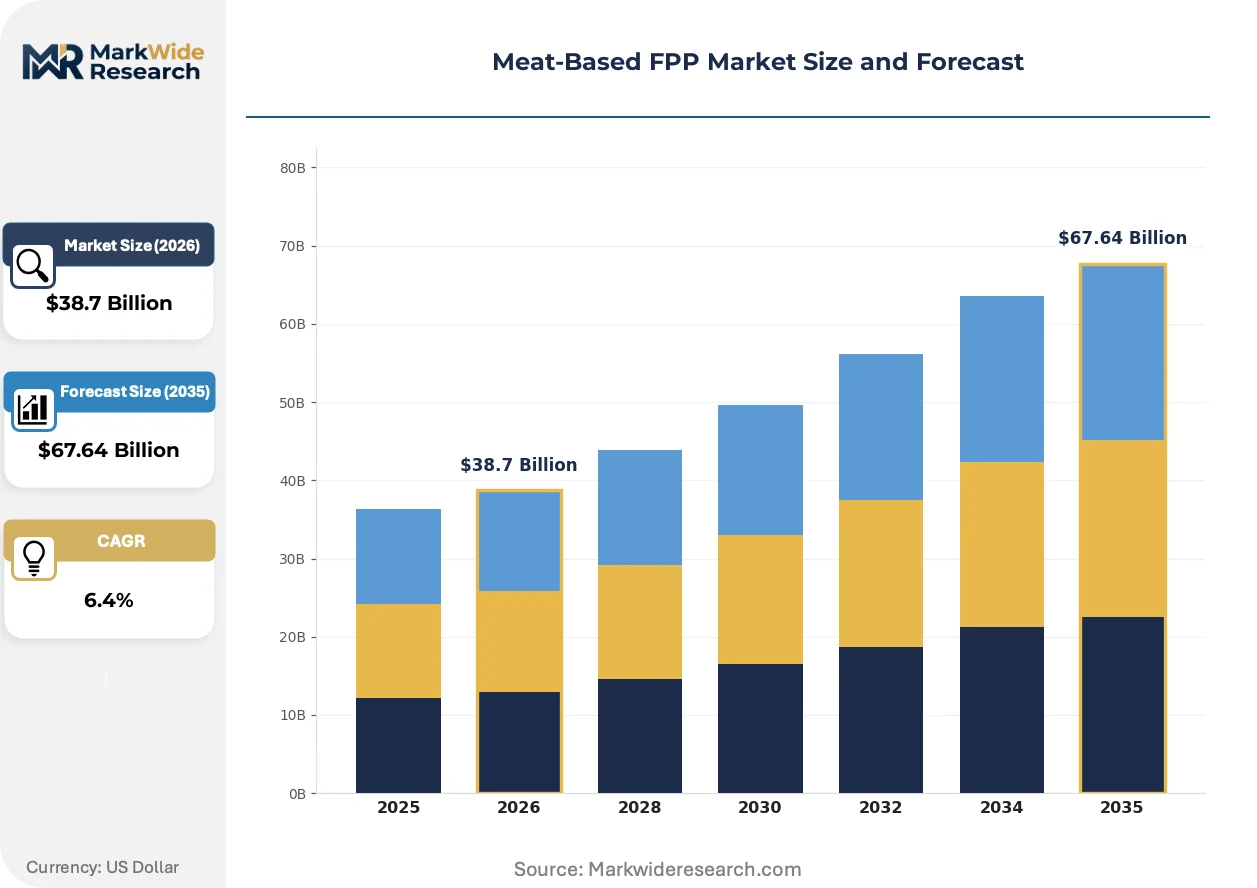
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $67.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Minced Meat, Sausages, Meat Patties, Meatballs, Ready-to-Cook Cuts, Jerky Processing Technique: Smoking, Curing, Fermentation, Freezing, Vacuum Packaging, Marinating Application: Foodservice Outlets, Retail Supermarkets, Quick Service Restaurants, Institutional Catering, Home Consumption End User: Butcher Shops, Delicatessens, Frozen Food Specialists, Specialty Meat Retailers |
| Companies Covered | JBS SA, Tyson Foods, Inc., WH Group Limited, The Kraft Heinz Company, Hormel Foods Corporation, Perdue Farms Inc., Almunajem Foods, Tanmiah Food Company, Cargill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Meat-Based FPP Market Strategic Shifts & Innovations
Automation in meat preparation is compressing labor dependency while refrigeration chemistry shifts and procurement centralization reshape how value-added products reach end-users.
High-pressure processing technology is fragmenting traditional thermal pasteurization dominance in ready-to-eat meat categories. Quick Service Restaurants and contract foodservice operators are adopting cold-pasteurized formats at accelerating rates to extend refrigerated shelf life without flavor degradation. This fragmentation is enabling regional processors to compete against national brands on distribution reach rather than scale economies alone.
The EU F-Gas Regulation is mandating hydrofluorocarbon phase-down timelines that force refrigeration asset replacement across processing plants. Industrial consequence includes ammonia system engineering shortages and extended retrofit project durations. European sausage and patty manufacturers with aged cooling infrastructure face the steepest compliance cliffs and are consolidating production into fewer facilities to amortize capital costs.
Centralized procurement by Quick Service Restaurant chains is displacing fragmented distributor relationships with direct processor contracts. Foodservice operators are unbundling specification-setting from logistics execution, retaining quality control in-house while outsourcing cold-chain delivery. This concentration is most visible in North American and Brazilian markets where JBS SA and Tyson Foods anchor high-margin retail programs through captive supply arrangements.
Meat-Based FPP Market Segmentation
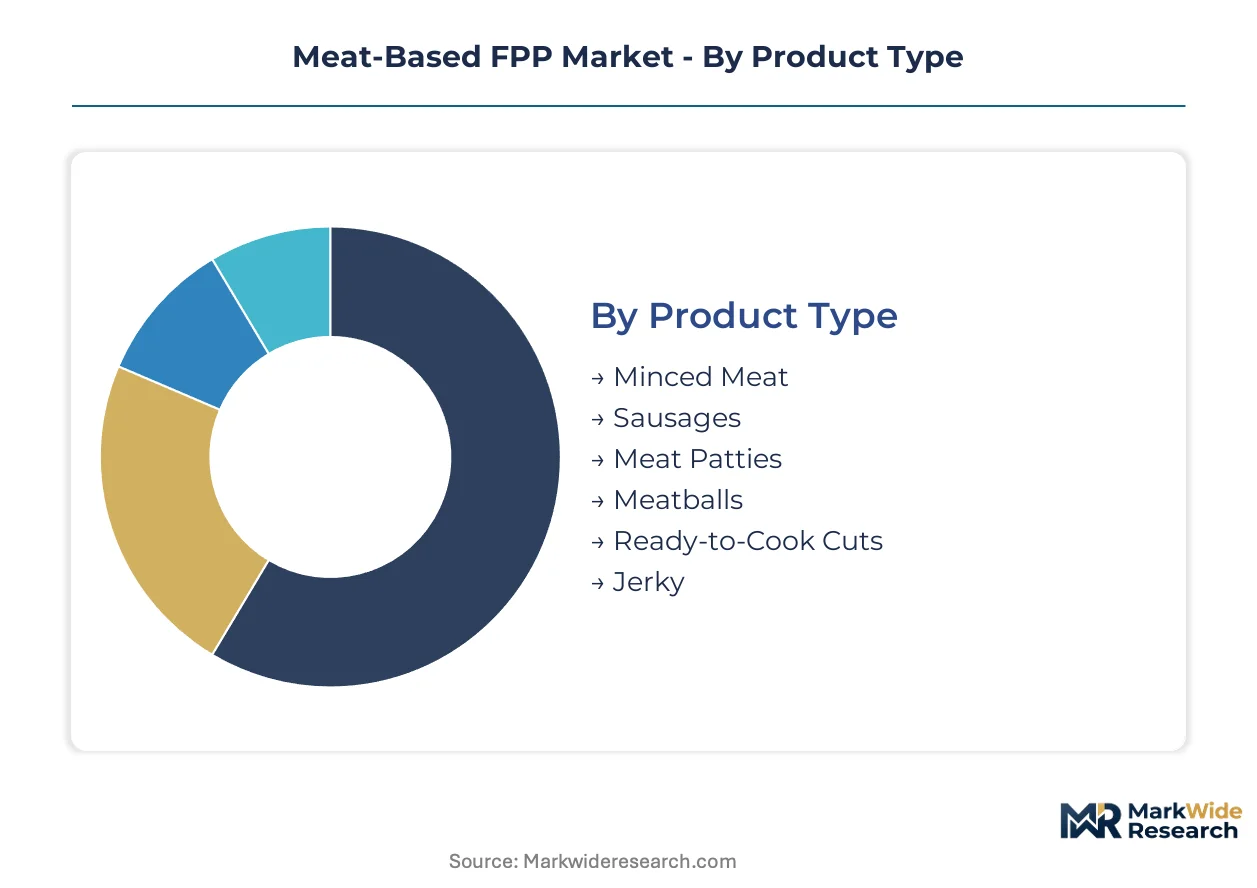
Segmentation in meat-based further processed products determines margin architecture and capital allocation priorities. Processors configure equipment lines and cold-chain investments around specific format specifications, while regulatory compliance burdens vary sharply across processing techniques and end-use channels.
Product Type:
Minced meat and sausages face the most intense plant-based protein substitution pressure, forcing conventional processors to defend shelf space through clean-label reformulation and price repositioning.
- Minced Meat:Ground beef and pork blends with defined fat-to-lean ratios serve as input stock for multiple downstream formats. Quick Service Restaurants in Brazil and the United States are consolidating procurement of coarse-ground 80/20 blends to standardize patty production across franchise networks.
- Sausages:Emulsified or coarse-ground products in natural or synthetic casings span fresh, smoked, and dried variants. German and Polish retail chains are expanding private-label fresh sausage programs that compress branded margin realization.
- Meat Patties:Pre-formed ground meat discs with uniform weight and thickness specifications target foodservice griddles and home grilling. Saudi Arabia's Tanmiah Food Company is scaling domestic patty capacity to displace frozen imports.
- Meatballs:Spherical formed products combining ground meat with breadcrumb extenders and seasoning matrices. Swedish and Italian retail formats dominate European chilled and frozen case space.
- Ready-to-Cook Cuts:Marinated or seasoned whole-muscle portions requiring minimal kitchen preparation. UAE MOHAP import specifications create compliance complexity for marinated poultry shipments from Brazilian processors.
- Jerky:Dried, salted, and seasoned whole-muscle strips with extended ambient shelf life. Protein-snacking households in the United States are pulling jerky into convenience store and online subscription channels.
Minced meat anchors the volume base while jerky gains share at the steepest rate.
Processing Technique:
Cost tier differentiation separates commodity thermal processing from premium-positioned traditional methods that command ingredient transparency premiums.
- Smoking:Exposure to hardwood-derived compounds imparts flavor, color, and preservative effects through cold or hot methods. Artisan smokehouses in Denmark and the Netherlands are capturing specialty retail placement through defined curing parameters.
- Curing:Salt, nitrite, and ascorbate application inhibits microbial growth while developing characteristic texture and flavor profiles. Italian and Spanish ham curing traditions face EFSA additive authorization constraints on nitrite levels.
- Fermentation:Controlled microbial acidification reduces pH and water activity for shelf-stable dried products. Central and Eastern European sausage traditions maintain geographic indication protections that limit competitive entry.
- Freezing:Blast or cryogenic temperature reduction preserves raw or partially processed products for extended distribution. Ammonia-based system retrofits under EU F-Gas Regulation are extending project timelines for French and German facilities.
- Vacuum Packaging:Oxygen exclusion within barrier films extends refrigerated shelf life and enables case-ready retail presentation. Quick Service Restaurant chains are adopting vacuum-packed marinated formats to compress in-store labor requirements.
- Marinating:Immersion or injection of acidic, enzymatic, or seasoned solutions to tenderize and flavor raw cuts. Saudi SFDA halal certification protocols require dedicated marinade ingredient verification that adds documentation burden.
Vacuum packaging holds the largest installed equipment base while fermentation commands the highest price realization per kilogram.
Application:
Customer type concentration determines specification complexity and contract structure, with direct foodservice accounts demanding tighter lot-traceability than fragmented retail channels.
- Foodservice Outlets:Independent restaurants and contract caterers purchasing portion-controlled formats for on-premise preparation. Brazilian churrascaria chains are standardizing procurement of wet-aged beef cuts to reduce per-location butchery labor.
- Retail Supermarkets:Branded and private-label products for consumer self-selection in chilled, frozen, and ambient aisles. German discounters are consolidating sausage supplier bases to capture scale rebates.
- Quick Service Restaurants:High-volume chains with exacting specification control and direct processor relationships. Tyson Foods anchors North American QSR patty supply through captive grinding and forming operations.
- Institutional Catering:Schools, hospitals, and military facilities procuring cost-optimized formats under nutritional compliance frameworks. USDA-FSIS pathogen performance standards drive lot-release testing capacity requirements for US military suppliers.
- Home Consumption:Direct-to-consumer channels including e-commerce subscriptions and meal-kit assembly. Dutch and Belgian online meat specialists are building cold-chain density in urban corridors.
Retail supermarkets move the highest tonnage while Quick Service Restaurants are expanding most quickly in value terms.
End User:
Supply concentration varies sharply across channels, with frozen food specialists consolidating purchasing power faster than fragmented traditional butchery.
- Butcher Shops:Independent meat retailers performing limited on-site processing of primal cuts into ground and formed products. Italian macellerie traditions face margin compression from supermarket private-label expansion.
- Delicatessens:Prepared food counters within grocery or standalone operations selling sliced, seasoned, and ready-to-eat formats. German Feinkost chains are centralizing production to reduce in-store labor.
- Frozen Food Specialists:Dedicated retail formats with extended frozen case space and temperature-controlled logistics. Iceland and the United Kingdom host the densest specialist network penetration.
- Specialty Meat Retailers:Premium-positioned outlets emphasizing provenance, breed, and processing transparency. Halal-certified specialists in London and Paris are capturing Muslim consumer segments underserved by mainstream chains.
Frozen food specialists are consolidating supplier relationships fastest while specialty meat retailers sustain the widest price premiums.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters in the United States, Brazil, Germany, Saudi Arabia, and China, where distinct regulatory frameworks and end-user demand patterns shape facility investment decisions.
United States
Quick Service Restaurants drive marinated and smoked meat procurement as labor costs compress commercial kitchen margins. USDA-FSIS pathogen performance standards and FDA inspection mandates strain lot-release testing capacity for domestic processors. Chicago and Omaha host dense grinding and forming operations serving national foodservice accounts.
Brazil
Export-oriented beef and poultry processing anchors value-added capacity expansion for Middle East and Asian markets. ANVISA sanitary certification requirements intersect with destination-country halal protocols for Saudi-bound shipments. São Paulo state concentrates smokehouse and patty-forming facilities serving both domestic churrascaria chains and international buyers.
Germany
Retail private-label sausage programs compress branded margin realization across fresh and smoked categories. EU F-Gas Regulation mandates ammonia-based refrigeration retrofits that extend project timelines for aged cooling infrastructure. Lower Saxony and Bavaria maintain artisan smokehouse clusters capturing specialty placement through defined curing parameters.
Saudi Arabia
Import substitution policies accelerate domestic value-added poultry and red meat capacity buildout. SFDA halal certification protocols require dedicated marinade ingredient verification that adds documentation burden for processors. Riyadh and Dammam industrial zones concentrate Tanmiah and Almunajem production facilities scaling patty and marinated cut output.
China
Urban convenience-seeking households pull ready-to-cook and frozen meat formats into faster-growing retail positions. SAMR food safety supervision and GB standards govern additive use and labeling requirements for domestic distribution. Shandong and Henan provinces host integrated slaughter-to-forming operations supplying quick-service and retail channels.
Meat-Based FPP Market Key Industry Players
Concentration sits with integrated protein conglomerates controlling captive supply chains from live animal procurement through case-ready distribution. Mid-scale regional processors compete on format specialization and religious certification agility rather than volume scale. Three archetypes dominate: vertically integrated multinationals with global slaughter capacity; domestic champions leveraging proximity to emerging market demand; and specialty smokehouses commanding artisan premiums through geographic indication protections. Competitive moves center on backward integration into feed and genetics to secure input cost stability, and direct contracting with Quick Service Restaurant chains to displace fragmented distributor relationships.
Within the integrated multinational tier, JBS SA anchors high-margin retail programs across North America and Brazil through cattle-to-case-ready supply chain control. Tyson Foods, Inc. occupies a position defined by R&D intensity in antibiotic-free product lines. WH Group Limited exemplifies scale manufacturing of standardized formats for European and Asian quick-service accounts. These three entities represent distinct strategic postures: South American beef dominance, North American poultry and pork innovation, and cross-continental sausage and patty standardization.
| Leading Market Players |
|---|
| JBS SA |
| Tyson Foods, Inc. |
| WH Group Limited |
| The Kraft Heinz Company |
| Hormel Foods Corporation |
| Perdue Farms Inc. |
| Almunajem Foods |
| Tanmiah Food Company |
| Cargill |
| Others |
Cost & Logistics Intelligence
Scale economies in patty-forming and grinding operations concentrate margin control among processors running multi-line facilities across Brazil and the United States. This capacity utilization advantage shapes price floors for commodity formats while creating entry barriers for regional competitors lacking volume throughput.
Pricing Analysis
EU F-Gas Regulation dictates the pricing tier structure by imposing capital recovery requirements on ammonia refrigeration retrofits that processors pass through to contract customers. Three-tier pricing structure across premium, standard, and economy levels separates artisan smoked products with geographic indication protection from private-label fresh sausages and commodity frozen patties. Pricing pressure stems from plant-based protein substitution in minced meat and sausage categories that forces conventional processors into defensive price repositioning. Quick Service Restaurant chains exhibit the highest price sensitivity due to centralized procurement leverage, while specialty meat retailers absorb premium tier increases with minimal volume elasticity.
Supply Chain Analysis
Brazil and the United States anchor live cattle procurement and slaughter capacity, with Germany and Saudi Arabia building downstream forming and marinating operations. Raw material flows draw from feed grain markets in the United States and Argentina, packaging films from petrochemical suppliers, and hardwood derivatives for smoking applications. Single-source vulnerability concentrates in Brazilian beef export corridors subject to ANVISA certification delays and destination-country halal audit backlogs. Distribution runs through cold-chain logistics providers serving Quick Service Restaurant direct contracts and retail supermarket case-ready programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plant-based protein substitutes are capturing shelf space in European and North American retail, forcing conventional meat processors into defensive innovation cycles that strain R&D budgets and compress timeline-to-market for clean-label reformulations.
For Market Incumbents: Secure backward integration into feed and genetics operations to stabilize input cost volatility that currently erodes margin predictability in commodity patty and sausage production. Anchor direct contracting relationships with Quick Service Restaurant chains to displace fragmented distributor intermediaries and capture specification-setting authority. Prioritize ammonia refrigeration retrofit completion ahead of EU F-Gas Regulation compliance cliffs to avoid production consolidation penalties.
For New Entrants and Emerging Players: Lead with halal-certified marinated ready-to-cook formats targeting Saudi Arabia and UAE foodservice accounts where SFDA and MOHAP compliance complexity deters established Western processors. Capture white space in artisan smoked segments protected by Danish and Dutch geographic indication traditions that limit scale competitor entry. Deploy subscription-based direct-to-consumer channels in Dutch and Belgian urban corridors to build cold-chain density without retail slotting fee burdens.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among processors holding captive Quick Service Restaurant supply contracts with multi-year pricing mechanisms and volume commitments. Target acquisition archetypes include mid-scale regional smokehouses with established curing parameter documentation and halal-certified facilities with dedicated quality assurance functions. Monitor EU EFSA additive authorization timelines as inflection indicators for formulation lock-in effects that could strand legacy product lines.
| Strategic Initiative | Industry Significance |
|---|---|
| Ammonia Refrigeration Retrofit | EU F-Gas Regulation compliance preserves facility operating licenses and avoids production consolidation. |
| Halal Certification Investment | SFDA and MOHAP protocols unlock Saudi and UAE market access for export-oriented processors. |
| Direct QSR Contracting | Centralized procurement relationships with chains like Tyson Foods' captive accounts displace distributor intermediaries. |
| Clean-Label Reformulation | Antibiotic-free and no-antibiotics-ever positioning defends shelf space against plant-based substitutes. |
| Vacuum Packaging Expansion | Extended shelf-life formats open foodservice accounts previously constrained by distribution reach limitations. |
Research Approach
A spread of perspectives from plant operations managers, Quick Service Restaurant procurement directors, cold-chain logistics coordinators, and regulatory affairs specialists converged on the working assumptions underlying volume and value projections. Primary fieldwork combined structured interviews with secondary validation through USDA-FSIS inspection data, EU EFSA additive authorization registers, Saudi SFDA halal certification documentation, and customs trade records for beef and poultry flows. Bottom-up capacity assessments at facility level were triangulated against top-down demand modeling across foodservice and retail channels.
Product type, processing technique, application channel, and end-user concentration dimensions structured the analytical framework across the projection horizon. CAGRs were derived from segment-level growth rate blending weighted by current value contribution. Forecast inputs incorporated live cattle price volatility assumptions, EU F-Gas Regulation compliance timelines, and Quick Service Restaurant procurement centralization trajectories.
Forecasts assume regulatory continuity in USDA-FSIS pathogen standards, EU MDR-derived labeling requirements, and Saudi SFDA halal protocols; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Nitrate-Free Bacon Market
Meat Products
Edible Offal Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Middle East Edible Meat Market
Meat Products
Vegan Meatball Market
Meat Products
Asia-Pacific Red Meat Market
Meat Products
North America Low Fat Sausage Market
Meat Products
Global Red Meat Market
Meat Products
Mechanically Separated Meat Market
Meat Products
Global Canned Meat Market
Meat Products
Pork Belly Meat Market
Meat Products
China Processed Meat Market
Meat Products
Kosher Beef Market
Meat Products
Meat, Poultry and Seafood Market
Meat Products
Global Edible Meat Market
Meat Products
Beef Jerky Market