
 3D Printed Meat Market | 2026-2036
3D Printed Meat Market Size, Share, and Industry Trends Forecast 2026-2036
3D Printed Meat Market Analytics
Plant-based scaffolding materials are expanding the texture fidelity of 3D printed meat, narrowing the sensory gap with conventional cuts. Steakholder Foods leverages multi-material extrusion to sustain texture complexity across beef and fish analogues. Aleph Farms anchors its position through cultivated steak platforms that compete on structural marbling fidelity. Redefine Meat specializes in whole-muscle constructs that dominate European foodservice channels.
3D printed meat denotes protein constructs assembled through additive manufacturing, wherein bioinks containing cultivated animal cells, plant proteins, or hybrid formulations deposit layer-by-layer at resolutions between 100-500 microns to replicate muscle fiber orientation and fat distribution. The process serves industrial and commercial purposes by enabling precise control over nutritional profiles, eliminating slaughterhouse dependencies, and reducing land use per kilogram of protein output. Extrusion-based technology currently leads deployment scale due to lower capital requirements and established supply chains for nozzle and pump components. Beef captures the largest addressable segment among product types, reflecting consumer familiarity and higher unit economics in premium channels. Foodservice end users absorb the majority of early volume, as centralized kitchen equipment and trained culinary staff reduce per-portion production complexity.
The Singapore Food Agency and Israel's Ministry of Health both operate dedicated novel food frameworks that shape market access timelines for cultivated and 3D printed proteins. FDA and USDA joint oversight in the United States imposes dual-labeling and facility inspection requirements that influence go-to-market sequencing for domestic producers. EFSA's evolving stance on cellular agriculture under the EU Novel Food Regulation creates uncertainty for European commercialization timelines. Stakeholders must monitor which regulatory pathway achieves procedural clarity first, as this jurisdiction will likely attract disproportionate capital allocation and manufacturing investment.
Market Dynamics
Multi-material extrusion systems are compressing production costs for texture-complex protein constructs, while Singapore's SFA novel food pathway accelerates regulatory clearance timelines for cultivated-meat entrants.
Growth Catalysts
- Singapore Food Agency framework:The SFA's dedicated novel food regulatory pathway compresses commercialization timelines for cultivated protein producers seeking market access.
- Plant-based scaffolding materials:Advanced scaffolding bioinks enable muscle fiber orientation fidelity that narrows sensory gaps with conventional cuts.
- Israel cellular agriculture cluster:Concentrated R&D infrastructure and talent pools in Rehovot accelerate technology transfer from laboratory to pilot scale.
Market Restraints
- Capital intensity of bioreactor infrastructure:Stainless-steel fermentation systems and cleanroom facilities demand eight-figure upfront investment per production line.
- EFSA regulatory uncertainty:Evolving EU Novel Food Regulation interpretations create timeline opacity for European market entry sequencing.
- Input cost volatility:Growth factor and cell culture media prices remain sensitive to pharmaceutical-grade reagent supply chains.
Strategic Opportunities
- UAE food-tech positioning:Dubai's high-end foodservice channel offers premium pricing acceptance for tasting-menu protein constructs.
- Hybrid formulation convergence:Integration of cultivated cells with plant protein matrices reduces unit costs while maintaining structural integrity.
- Centralized kitchen channel innovation:Foodservice operators with trained culinary staff reduce per-portion production complexity versus retail distribution.
Industry Challenges
- Tissue engineering talent scarcity:Shortage of specialists spanning bioprocessing, materials science, and food technology slows scale-up execution.
- Dual-agency compliance complexity:FDA and USDA joint oversight in the United States imposes overlapping facility inspection and labeling requirements.
- Standardization protocol gaps:Absence of unified ISO benchmarks for 3D printed meat texture and nutritional equivalence creates certification friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 3D Printed Meat Market |
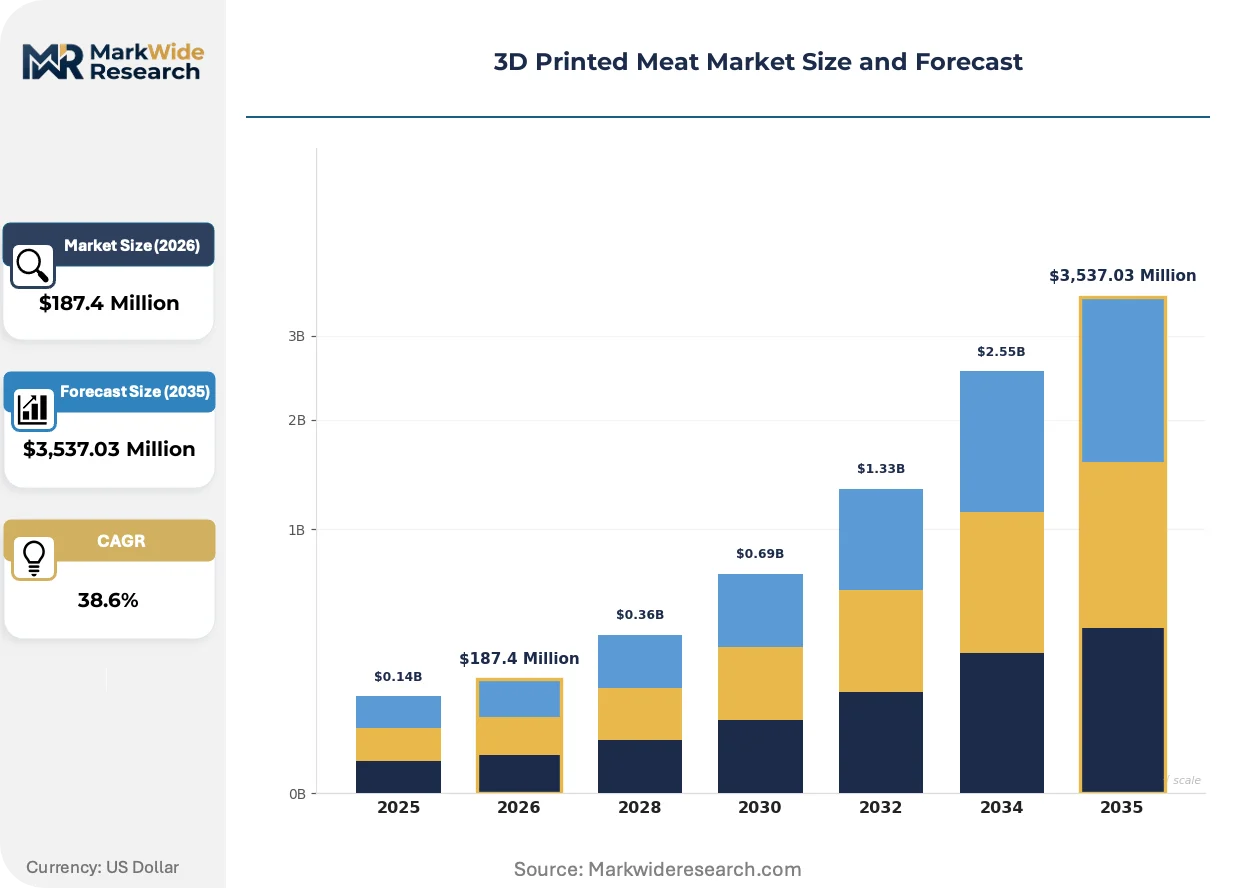
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $3,537.03 Million |
| CAGR (2026 – 2036) | 38.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Beef, Chicken, Fish, Pork Technology: Droplet-Based, Extrusion-Based, Laser Sintering, Sheet-Based End User: Restaurants, Retailers, Foodservice, Households Distribution Channel: Online, Offline, Direct Sales, Third-Party Retailers |
| Companies Covered | Steakholder Foods, Aleph Farms, BlueNalu, GOOD Meat, BELIEVER Meats, Shiok Meats, CellX, Umami Bioworks, Redefine Meat, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
3D Printed Meat Market Evolving Landscape
Extrusion-based additive manufacturing is consolidating its position as the dominant production modality, while regulatory pathway clarity in select jurisdictions is reshaping capital allocation patterns.
Multi-material extrusion technology is consolidating control over texture complexity in beef and seafood analogues. High-end restaurant chains in Singapore and Dubai deploy these systems for tasting-menu applications requiring precise fat distribution and muscle fiber orientation. The technology is consolidating market position by reducing capital requirements relative to alternative additive methods.
EU Novel Food Regulation interpretations under EFSA review are creating compliance uncertainty for cultivated protein entrants. European producers face extended safety assessment timelines compared to jurisdictions with dedicated novel food frameworks. Beef analogue developers targeting EU foodservice channels are sequencing market entry around regulatory clarity timelines.
Buyer concentration in centralized foodservice kitchens is compressing distribution complexity for 3D printed protein constructs. Restaurant groups with in-house culinary R&D capabilities absorb early volume through direct equipment partnerships. This procurement pattern concentrates demand visibility in Israel's cellular agriculture cluster and the Netherlands' Wageningen corridor.
3D Printed Meat Market Segmentation
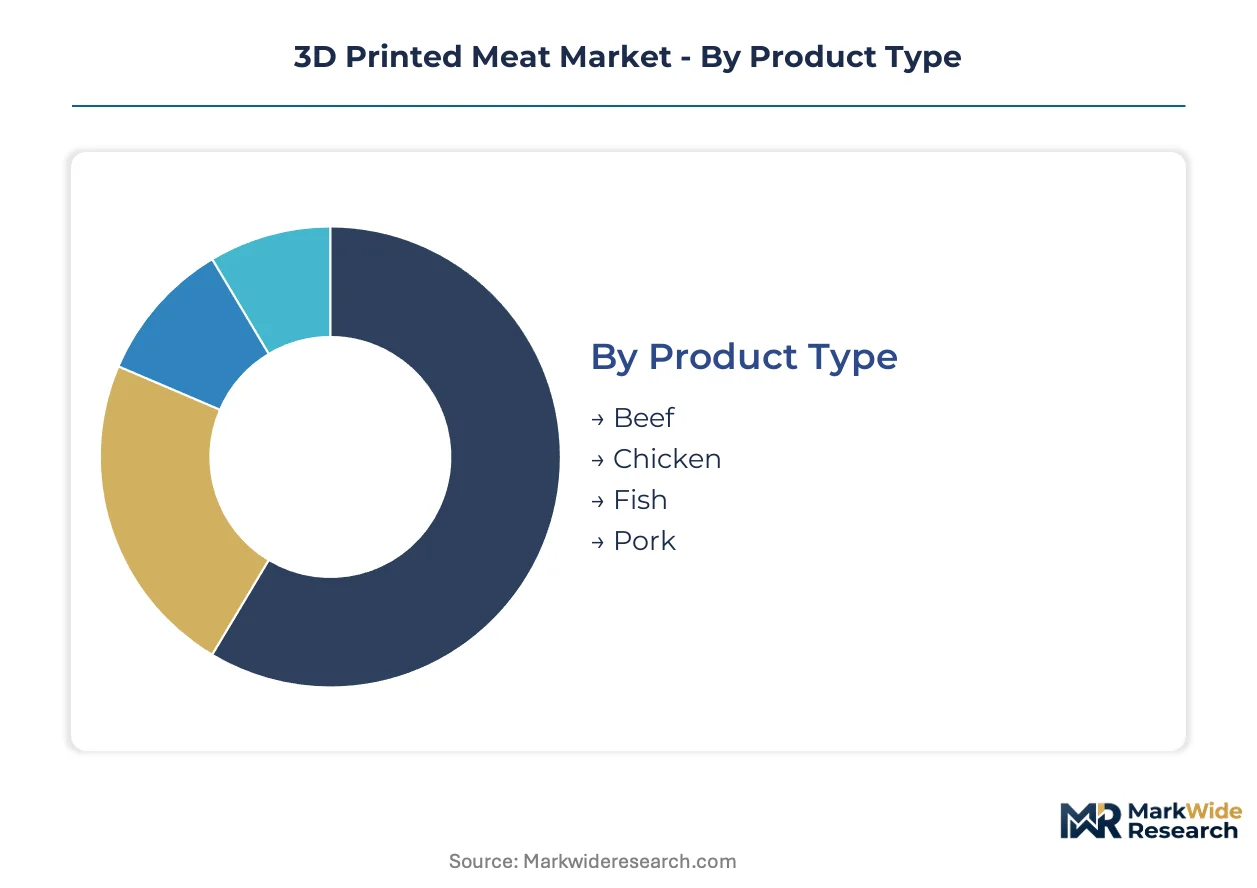
Segmentation in 3D printed meat reveals how production economics and regulatory access concentrate commercial activity. Product type and technology choices determine capital requirements, while end-user targeting shapes go-to-market complexity and margin structure.
Product Type:
Beef commands premium positioning through marbling fidelity demands, while fish and poultry segments split between cost-driven and texture-priority applications.
- Beef:Structural complexity requiring precise fat-muscle fiber orientation drives extrusion system investments. Singapore's high-end restaurant channel absorbs early volume through tasting-menu premiums. FDA and USDA dual oversight in the United States shapes labeling compliance costs for domestic entrants.
- Fish:Layered collagen deposition replicates flaky texture signatures of conventional seafood. Dubai's foodservice operators pilot salmon and tuna analogues for premium hospitality contracts. EFSA's evolving novel food stance creates timeline uncertainty for European commercialization.
- Chicken:Lower scaffolding complexity reduces unit production costs versus beef constructs.
- Pork:Fat distribution requirements mirror beef specifications but face narrower regulatory pathway clarity in key markets.
Mature deployment sits with beef. Newer deployment is concentrated in fish.
Technology:
Capital efficiency separates scalable production modalities from precision-focused alternatives, with extrusion systems dominating foodservice integration.
- Extrusion-Based:Multi-material nozzle systems deposit bioinks at 100-500 micron resolution for muscle fiber fidelity. Israel's cellular agriculture cluster in Rehovot concentrates pilot-scale deployment through technology transfer partnerships. Lower capital requirements versus bioprinting alternatives accelerate foodservice channel penetration.
- Droplet-Based:Inkjet-style cell deposition enables precise spatial control over fat distribution patterns. Netherlands Wageningen corridor researchers advance droplet protocols for hybrid cultivated-plant formulations. Pharmaceutical-grade reagent supply chain sensitivity constrains media cost predictability.
- Laser Sintering:Powder-bed fusion of protein matrices remains confined to research-scale applications.
- Sheet-Based:Stacked tissue layers achieve thickness without continuous deposition systems.
Volume concentration favors extrusion-based systems. Laser sintering remains pre-commercial.
End User:
Centralized production capacity and trained culinary staff determine which buyer categories absorb early supply.
- Restaurants:High-end tasting menus in Singapore and Dubai justify equipment partnerships and per-portion premiums. SFA's novel food pathway compresses regulatory clearance timelines for cultivated protein menu integration. Direct supplier relationships reduce distribution margin stacking.
- Foodservice:Institutional catering and hospitality groups leverage centralized kitchen infrastructure for batch consistency. UAE's food-tech positioning attracts premium pricing acceptance for protein constructs in luxury hotel channels. Standardized portion control aligns with 3D printing's dimensional precision.
- Retailers:Cold-chain and packaging requirements extend go-to-market complexity versus foodservice.
- Households:Consumer-grade equipment availability and price points remain prohibitive for mass adoption.
Revenue concentration sits with restaurants. Steepest expansion trajectory is emerging in foodservice.
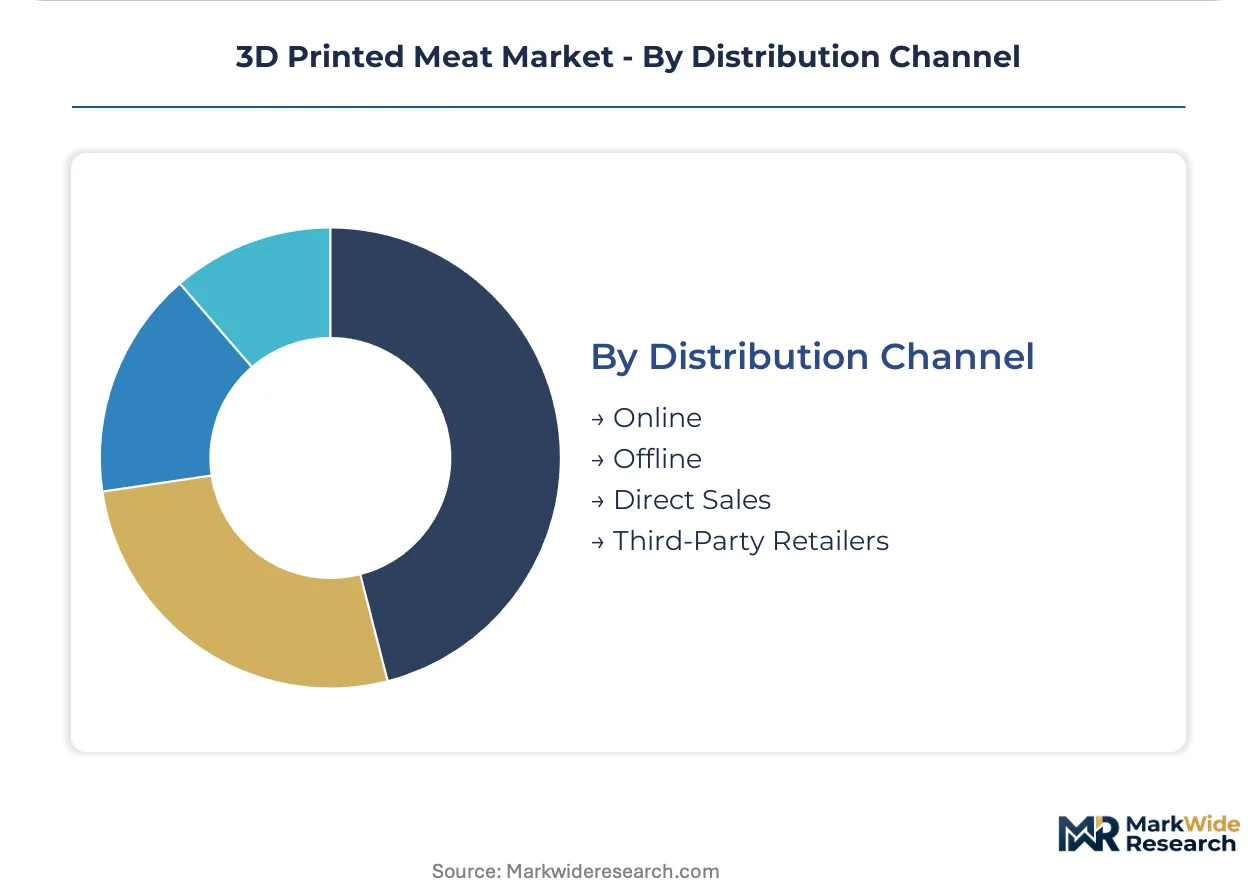
Distribution Channel:
Equipment-heavy production favors direct relationships over retail margin structures.
- Direct Sales:Equipment-integrated supply agreements with restaurant groups and foodservice operators bypass retail markup. Singapore's SFA framework enables faster contractual closure for novel food partnerships. Technical training and maintenance bundling locks in recurring revenue streams.
- Third-Party Retailers:Specialty food distributors extend reach to mid-tier foodservice accounts lacking direct procurement capability. European channels face extended timeline opacity from EFSA regulatory uncertainty. Margin compression versus direct sales limits prioritization.
- Online:E-commerce platforms serve research institutions and pilot-scale buyers with configurable bioink formulations.
- Offline:Traditional wholesale routes remain underdeveloped for perishable protein constructs.
Established volume flows through direct sales. Online channels are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Biopolis and one-north precincts concentrate cultivated protein R&D through tax-advantaged zones that offset bioreactor facility costs. Israel's Rehovot corridor and the Netherlands' Wageningen food-tech belt generate comparable clustering effects through dedicated grant programs.
United States
Foodservice operators in New York and Los Angeles pilot 3D printed beef constructs for premium hospitality contracts. FDA and USDA joint oversight imposes dual-labeling requirements that extend commercialization timelines for domestic producers. The Greater Boston biotech corridor anchors pilot-scale bioreactor deployment through proximity to tissue engineering talent pools.
Singapore
High-end restaurant groups absorb early volume through tasting-menu premiums that justify equipment partnerships. The Singapore Food Agency's novel food regulatory pathway compresses safety assessment timelines relative to jurisdictions with evolving frameworks. The one-north precinct concentrates technology transfer partnerships between cultivated meat startups and extrusion system manufacturers.
Israel
Cellular agriculture clusters in Rehovot leverage Weizmann Institute proximity for muscle fiber orientation research. The Ministry of Health operates a dedicated novel food framework that accelerates regulatory clearance for cultivated protein entrants. Tel Aviv-area foodservice operators integrate hybrid cultivated-plant constructs into centralized kitchen operations.
Netherlands
Wageningen University & Research anchors Europe's densest food-tech corridor through pilot-scale droplet-based deposition facilities. EFSA's evolving stance on cellular agriculture under EU Novel Food Regulation creates timeline opacity for commercialization sequencing. Foodservice distributors in Rotterdam and Amsterdam test salmon analogue batches for hospitality channel acceptance.
United Arab Emirates
Dubai's luxury hotel groups offer premium pricing acceptance for protein constructs in high-end catering channels. MOHAP's regulatory framework for novel foods remains less codified than Singapore's pathway, creating entry timing uncertainty. The Dubai Future District attracts equipment-integrated supply agreements through zero-duty import structures for food-tech hardware.
3D Printed Meat Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with technology-integrated protein developers commanding premium positioning in foodservice channels while equipment suppliers capture recurring revenue through maintenance bundling. The vendor base concentrates around three strategic archetypes: cultivated-cell platform operators, multi-material extrusion system providers, and hybrid formulation specialists. M&A activity targets bioreactor capacity and scaffolding IP portfolios. Geographic expansion sequences around regulatory pathway clarity rather than demand density alone.
Among Israel-based cultivated-cell developers, Aleph Farms and Steakholder Foods exemplify the structural-marbling fidelity tier, while Redefine Meat occupies a position within the European whole-muscle construct segment. These three entities represent divergent technology bets—cultivated steak platforms, multi-species extrusion systems, and plant-cultivated hybrid matrices—each anchoring distinct competitive vectors without overlapping core positioning.
| Leading Market Players |
|---|
| Steakholder Foods |
| Aleph Farms |
| BlueNalu |
| GOOD Meat |
| BELIEVER Meats |
| Shiok Meats |
| CellX |
| Umami Bioworks |
| Redefine Meat |
| Others |
Value Network & Pricing Analysis
Foodservice procurement consolidation in Singapore and Dubai is compressing supplier margins while demanding shorter lead times for tasting-menu protein constructs, forcing 3D printed meat producers to co-locate extrusion systems near high-end restaurant clusters and absorb bioreactor facility depreciation into long-term equipment-lease pricing.
Pricing Analysis
Lead-time premiums dominate contract negotiations, with restaurant groups paying 15-25% above base rates for 48-hour turnaround on custom marbling specifications. Three-tier pricing structure across premium cultivated-steak, standard hybrid formulations, and economy plant-based tiers differentiates by cell density and scaffolding complexity. Cost compression in the economy tier is intensifying because pharmaceutical-grade growth factor supply chains remain concentrated among three specialty chemical producers. Foodservice operators with centralized kitchen infrastructure exhibit lowest price sensitivity, while mid-tier restaurant chains without in-house culinary R&D drive hardest bargain negotiations.
Supply Chain Analysis
Bioreactor-grade stainless steel fabrication rests on German and Japanese precision engineering suppliers, while growth factor production concentrates in Swiss and South Korean pharmaceutical facilities. Scaffolding bioink formulations draw from Netherlands-based plant protein processors and Israeli collagen engineering specialists. Single-source vulnerability in pharmaceutical-grade cell culture media creates exposure to reagent batch variability. Distribution runs through direct equipment-integrated supply agreements with restaurant groups, bypassing traditional wholesale margin structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Multi-material extrusion technology is displacing legacy tissue-engineering approaches in commercial-scale protein production, compressing unit economics while elevating texture fidelity requirements for market viability.
For Market Incumbents: Extend cultivated-cell platform investments into hybrid formulation capabilities before plant-protein matrix specialists capture mid-market foodservice contracts. Bioreactor capacity expansion in Singapore's one-north precinct offsets regulatory timeline advantages from emerging UAE entrants. Backward integration into scaffolding bioink production reduces exposure to Netherlands plant-protein supply volatility. For New Entrants and Emerging Players: Enter via Dubai's luxury hospitality channel, where premium pricing acceptance for tasting-menu applications exceeds Singapore's saturated early-adopter segment. White-space concentration sits in fish analogue production for Middle Eastern hotel groups, with lower scaffolding complexity than beef constructs. Co-development partnerships with existing extrusion system manufacturers accelerate technical validation without captive equipment investment. For Investors and Strategic Acquirers: The window for entry favors hybrid-formulation specialists with demonstrated foodservice channel traction over pure-play cultivated-cell developers facing capital intensity headwinds. Long-term viability hinges on regulatory pathway clarity in at least two jurisdictions with dedicated novel food frameworks. Monitor EFSA's EU Novel Food Regulation interpretation timeline as the critical inflection signal for European manufacturing investment decisions.| Strategic Initiative | Industry Significance |
|---|---|
| Bioreactor Capacity Expansion | Singapore's SFA pathway accelerates depreciation recovery through faster revenue recognition. |
| Scaffolding IP Acquisition | Plant-based matrix patents from Wageningen corridor reduce cultivated-cell dependency costs. |
| Foodservice Equipment Partnership | Dubai hotel group contracts lock in five-year offtake visibility with maintenance bundling. |
| Hybrid Formulation Launch | Israeli cellular agriculture cluster enables rapid pilot-to-scale technology transfer. |
| Novel Food Regulatory Approval | MOHAP framework completion in UAE would unlock Gulf Cooperation Council market access. |
Research Methodology
Document review covered SEC filings from protein technology developers, Singapore Food Agency novel food approval dockets, and EFSA cellular agriculture consultation papers, complemented by interviews with cultivated meat R&D directors, foodservice procurement managers at Dubai luxury hotel groups, bioreactor engineering specialists, and regulatory affairs leads at hybrid-formulation startups. Secondary validation drew from Israel Innovation Authority grant disbursement records, Netherlands Enterprise Agency food-tech corridor reports, and UAE Ministry of Economy foreign investment filings. Bottom-up unit economics modeling triangulated against top-down addressable market sizing from protein consumption databases.
Segmented outputs across product type, technology modality, end-user category, and geographic regulatory cluster were generated across the analysis window. CAGRs were derived from logistic diffusion curves fitted to early-adopter penetration rates in Singapore and Israel foodservice channels, with sensitivity testing against EFSA timeline uncertainty and growth factor cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EU Novel Food Regulation opacity or pharmaceutical-grade reagent supply disruption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Meat Market
Meat Products
Mexico Meat Products Market
Meat Products
Bacon Flavors Market
Meat Products
Bacon Market
Meat Products
Hot Dog and Sausages Market
Meat Products
Europe Bacon Market
Meat Products
Saudi Arabia Red Meat Market
Meat Products
Asia-Pacific Edible Meat Market
Meat Products
Brazil Meat Products Market
Meat Products
Canned Pork Market
Meat Products
Vegan Meatball Market
Meat Products
North America Edible Meat Market
Meat Products
Europe Edible Meat Market
Meat Products
Reconstituted Meat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Organic Meat Market