

Copper (II) Carbonate Basic Market Size, Share, and Industry Trends Forecast 2026-2036
Copper (II) Carbonate Basic Market Insights
ISO 9001 qualification cycles is reorganizing supplier eligibility across the Copper (II) Carbonate Basic value chain, forcing smaller manufacturers to upgrade quality systems or exit contract relationships. American Elements leverages its vertically integrated rare and advanced materials platform to sustain specification-grade output for pharmaceutical and electronics clients. Merck KGaA anchors European supply through its stringent analytical standards and controlled-substance distribution networks. Jiangxi Jiangnan New Materials Technology dominates cost-competitive technical-grade production, competing primarily on volume pricing into Asian agrochemical formulators.
Copper (II) carbonate basic, Cu₂CO₃(OH)₂, is a green crystalline salt typically manufactured through precipitation of copper sulfate with sodium carbonate at controlled pH, yielding a material with 55-57% copper content used primarily as a precursor for other copper compounds, agricultural fungicide active ingredient, and ceramic pigment feedstock. Powder form occupies the largest volume share due to its ease of dispersion in wettable fungicide formulations and paint systems, though pharmaceutical-grade crystals command the highest unit margins given compendial testing burdens. Technical grade sustains the broadest application footprint across catalyst and pigment manufacturing, while food and pharmaceutical grades face tightening heavy-metal specification limits that concentrate margin pools with certified producers.
EPA tolerance reassessments under the Federal Insecticide, Fungicide, and Rodenticide Act shape allowable copper residues in agricultural commodities, directly influencing formulation concentrations and application rates. REACH registration requirements and the EU Green Deal's sustainable chemistry directives constrain import pathways for non-European manufacturers lacking full substance dossiers. China's Ministry of Ecology and Environment enforces discharge limits on copper-containing wastewater from carbonate production facilities, raising compliance capital requirements for domestic producers. Stakeholders must monitor evolving maximum residue limits across importing jurisdictions and assess backward integration into copper sourcing to secure supply continuity against concentrate market volatility.
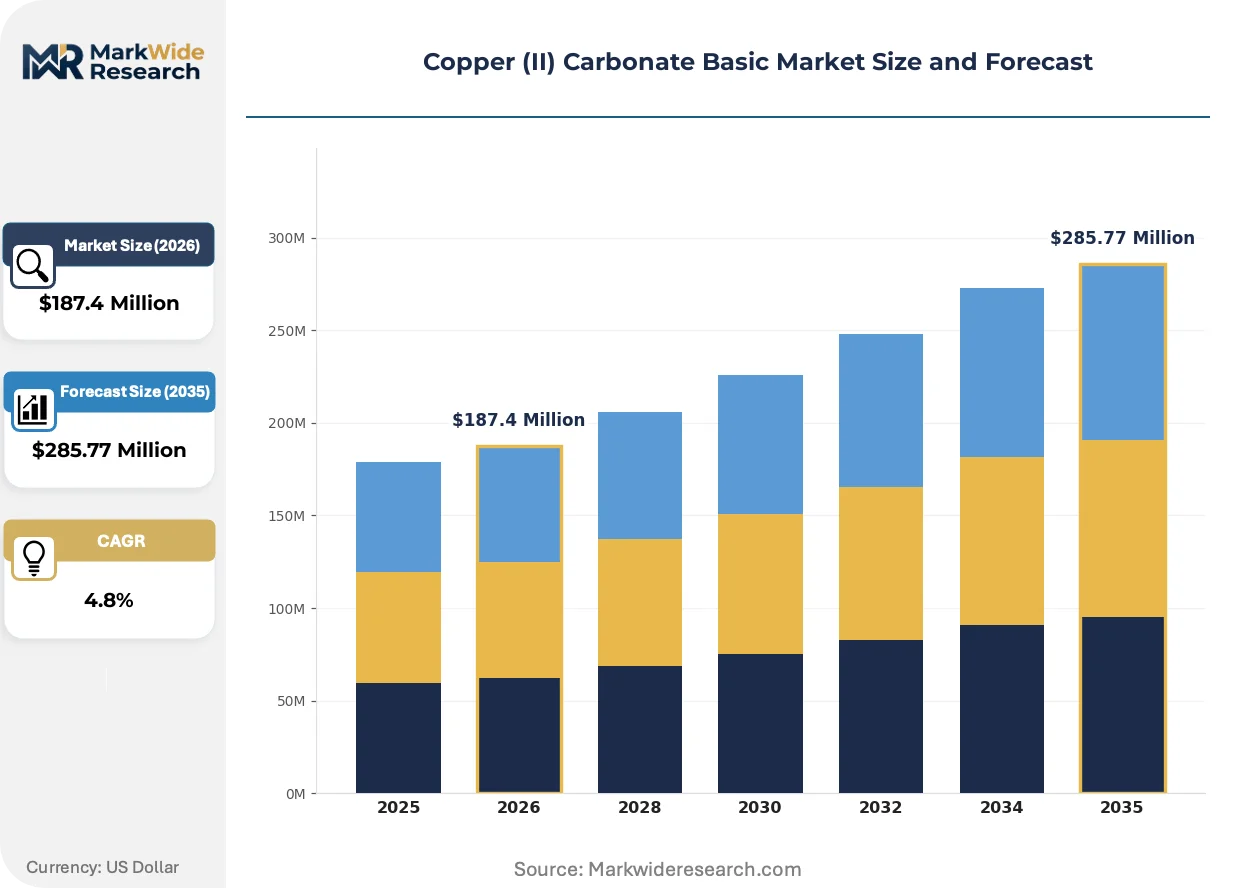
Market Dynamics
REACH registration dossiers and EPA tolerance reassessments are forcing non-compliant manufacturers to exit contract positions, concentrating supply relationships with certified producers possessing backward integration into copper concentrate sourcing.
Growth Catalysts
- EU Green Deal sustainable chemistry mandates:Copper-based fungicides face fewer regulatory barriers than synthetic alternatives across German and French agricultural markets, accelerating formulation demand from regional agrochemical distributors.
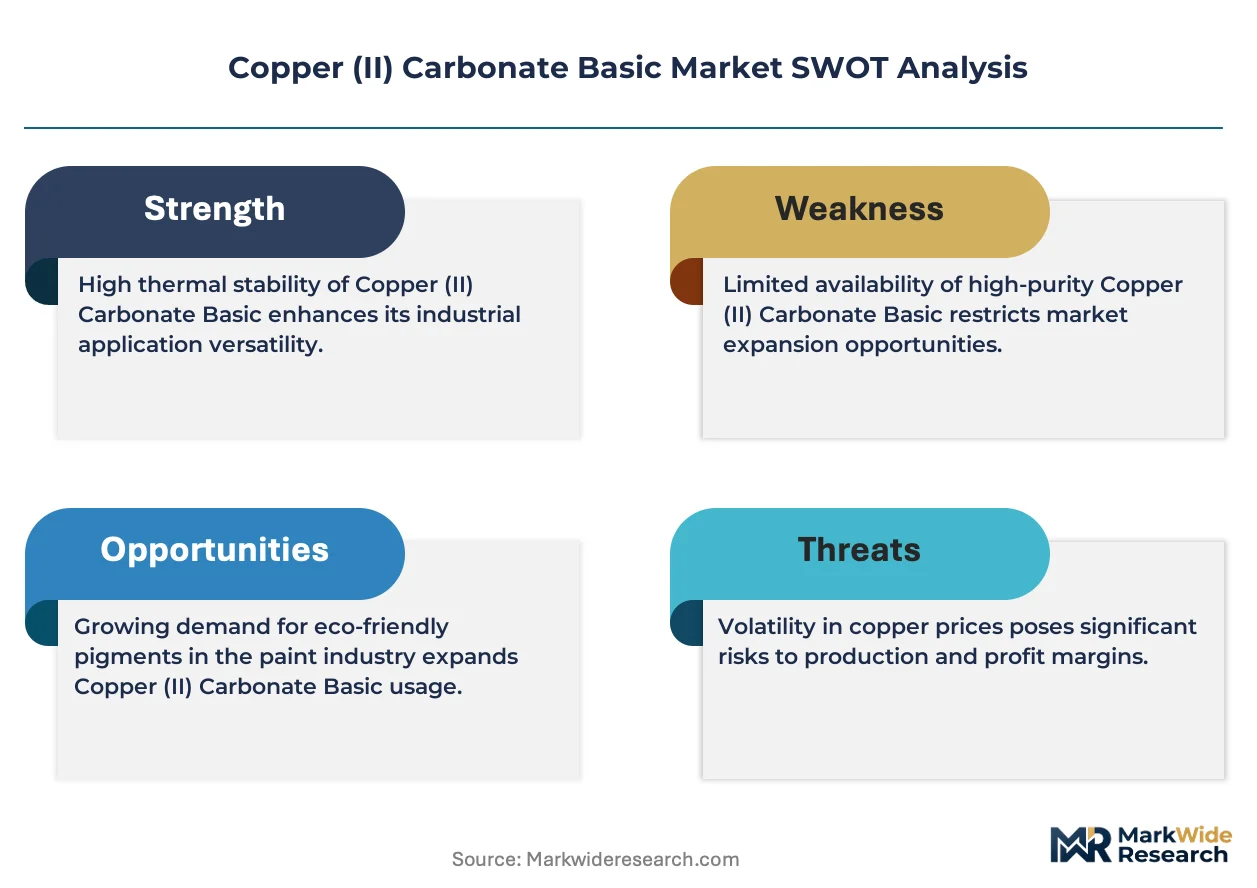
- Precipitation process optimization:Continuous crystallization systems are reducing sodium carbonate consumption per unit output, lowering variable costs for technical-grade producers serving ceramic pigment manufacturers.
- China:Domestic agrochemical manufacturing clusters in Jiangsu and Shandong provinces are absorbing rising volumes of technical-grade material for captive fungicide formulation.
Market Restraints
- Copper concentrate price volatility:London Metal Exchange pricing swings directly compress margins for carbonate producers lacking long-term offtake agreements with mining operations.
- Supply concentration in Chinese technical-grade production:Cost-competitive volumes from Jiangxi-based manufacturers limit pricing power for European and North American producers serving specification-grade segments.
- Substitution by synthetic triazole fungicides:Azoxystrobin and propiconazole formulations continue displacing copper-based products in high-value horticultural applications where residue limits are most stringent.
Strategic Opportunities
- Pharmaceutical-grade compendial supply:USP and EP certification requirements are creating margin pools for producers willing to absorb heavy-metal testing burdens and analytical validation costs.
- India:BIS quality mark adoption and PLI scheme incentives for domestic agrochemical manufacturing are opening import substitution opportunities for carbonate feedstock suppliers.
- Closed-loop wastewater recovery systems:China's Ministry of Ecology and Environment discharge limits are rewarding producers with integrated copper recovery capabilities that reduce environmental compliance capital requirements.
Industry Challenges
- Analytical chemistry talent scarcity:ICP-MS heavy-metal testing expertise and compendial documentation capabilities are concentrated among a narrow pool of qualified laboratory personnel, extending certification timelines for new market entrants.
- ISO 9001 surveillance audit cycles:Smaller manufacturers face recurring costs for quality management system maintenance that strain operational resources without guaranteed contract renewal from specification-grade buyers.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Copper (II) Carbonate Basic Market Trends and Innovations
Continuous processing technologies and compendial-grade certification requirements are fragmenting production methodologies between commodity technical output and specification-grade pharmaceutical supply.
Continuous precipitation reactor design is bifurcating the manufacturing base between batch-processed technical-grade suppliers and continuous-system operators targeting pharmaceutical and electronics applications. Ceramic pigment manufacturers continue absorbing commodity volumes from traditional batch facilities. Specification-grade buyers are consolidating supply relationships with continuous-process operators capable of validated lot-to-lot consistency.
REACH substance dossier completeness requirements are eliminating import pathways for Asian manufacturers lacking European legal entity representation and full toxicological data packages. Non-European producers without established Only Representative arrangements are losing access to formulation houses in Germany and the Netherlands. Certified European manufacturers are capturing displaced volume through controlled-substance distribution networks.
Certification-driven supplier consolidation is compressing approved vendor lists at agrochemical formulators and pharmaceutical compounders. Buyers are reducing qualified supplier counts from five-plus sources to two or three certified relationships. This pattern is most visible in German and Swiss pharmaceutical manufacturing clusters where USP and EP compliance documentation carries contractual weight.
Copper (II) Carbonate Basic Market Segmentation
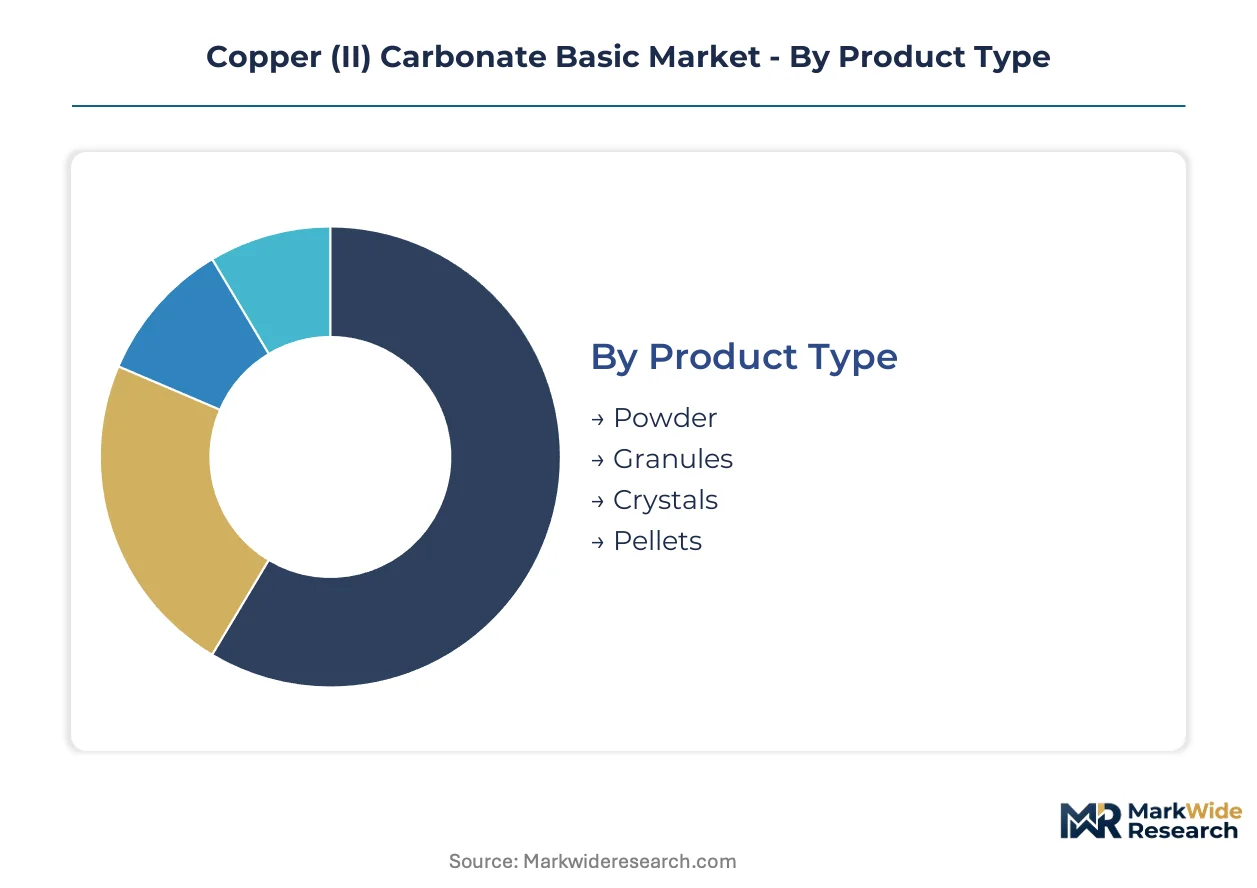
Physical form and purity specifications dictate channel access for Copper (II) Carbonate Basic, with agrochemical distributors handling bulk powder while pharmaceutical compounders require certified crystalline grades. Grade certification determines regulatory clearance, splitting the market between REACH-registered technical supply and compendial-grade pharmaceutical pathways.
Product Type:
Powder and granule volumes flow through agrochemical distribution networks serving fungicide formulators, while crystals and pellets command direct procurement relationships with pharmaceutical and electronics manufacturers.
- Powder:Fine particulate form with 55-57% copper content enables rapid dispersion in wettable powder fungicide formulations. Demand concentrates in Chinese agrochemical manufacturing clusters in Jiangsu and Shandong provinces, driven by domestic crop protection production absorbing technical-grade volumes.
- Crystals:Compendial-grade material meeting USP and EP specifications requires validated crystallization systems and ICP-MS heavy-metal documentation. Pharmaceutical compounders in German and Swiss manufacturing clusters pay premium unit margins for lot-to-lot consistency in copper salt precursors.
- Granules:Intermediate particle size reduces dusting during handling for ceramic pigment manufacturers. Technical-grade granule supply channels through mineral processing distributors serving Spanish and Italian tile producers.
- Pellets:Compressed form facilitates controlled dissolution rates in catalyst manufacturing. Chemical process operators in the Netherlands and Belgium specify pellet geometry for fixed-bed reactor applications.
Powder dominates installed base. Crystals are where expansion concentrates.
Grade:
Cost tiers separate commodity technical supply from certified pharmaceutical grades, with analytical validation burdens concentrating margin pools at the specification end.
- Technical:Standard purity material with baseline heavy-metal specifications serves ceramic pigment and catalyst manufacturing. Jiangxi-based producers compete on volume pricing into Asian agrochemical formulators lacking REACH registration requirements.
- Pharmaceutical:USP and EP compliance demands comprehensive substance dossiers and controlled-substance distribution networks. European manufacturers capture margin premiums through analytical chemistry capabilities scarce among commodity producers.
- Chemical:Intermediate purity grade for laboratory reagent and electroplating precursor applications. Distribution runs through specialty chemical distributors in France and Germany serving research institutions.
- Food:FSSAI and FDA-compliant material for nutritional supplement copper fortification. Heavy-metal limits approaching pharmaceutical stringency restrict qualified supplier pools.
Technical grade anchors volume throughput. Pharmaceutical grade captures value expansion.
Application:
End-use concentration varies by regulatory tolerance, with agricultural residues facing EPA reassessment while pigment applications encounter fewer formulation barriers.
- Fungicides:Active ingredient in copper-based crop protection with established residue tolerance frameworks under FIFRA. Formulation demand from French and German distributors accelerates as EU Green Deal chemistry mandates favor copper over synthetic triazoles.
- Pigments:Ceramic colorant feedstock requiring consistent particle size distribution for glaze applications. Italian and Spanish tile manufacturers absorb commodity volumes through mineral processing supply chains.
- Catalysts:Precursor for copper oxide catalysts in petrochemical and fine chemical synthesis. Belgian and Dutch chemical manufacturing clusters specify pellet geometry for fixed-bed reactor performance.
- Animal Feed:Nutritional copper supplementation subject to FDA and EFSA maximum inclusion rates. Feed compounders in Iowa and Illinois procure food-grade material for livestock mineral premixes.
Fungicides command the largest application footprint. Pigment feedstock is climbing the fastest.
End User Industry:
Customer type determines procurement sophistication, with multinational agrochemicals demanding certification documentation that excludes uncertified producers.
- Agriculture:Crop protection formulators and distributors drive bulk powder demand through seasonal procurement cycles. Chinese domestic manufacturing clusters in Jiangsu province absorb rising technical-grade volumes for captive fungicide production.
- Paints & Coatings:Marine antifouling and protective coating manufacturers specify copper carbonate for controlled-release biocide applications. Korean and Japanese shipyard coating suppliers source through regional chemical distributors.
- Chemical Manufacturing:Catalyst producers and copper salt derivative manufacturers require consistent specification-grade supply. German chemical clusters prioritize REACH-registered producers with backward integration into copper concentrate sourcing.
- Nutraceuticals:Dietary supplement manufacturers demand food and pharmaceutical grades with comprehensive heavy-metal documentation. California and New Jersey compounding facilities contract directly with certified producers.
Agriculture dominates installed demand. Nutraceuticals are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Agrochemical formulators and pharmaceutical compounders concentrate procurement relationships in jurisdictions with established copper salt manufacturing infrastructure and transparent regulatory pathways. REACH-registered European supply and EPA-tolerance-aligned North American demand anchor premium-grade offtake, while Chinese technical-grade production absorbs volume-driven fungicide formulation.
China
Jiangsu and Shandong province manufacturing clusters drive technical-grade carbonate consumption for captive fungicide production serving domestic crop protection markets. MEE discharge limits on copper-containing wastewater force capital investment into closed-loop recovery systems at carbonate precipitation facilities. Jiangxi-based producers dominate cost-competitive powder supply to regional agrochemical formulators lacking export certification requirements.
Germany
REACH substance dossier completeness filters import access for pharmaceutical-grade crystals demanded by compounding facilities in Baden-Württemberg and North Rhine-Westphalia. EU Green Deal sustainable chemistry mandates accelerate copper-based fungicide formulation at agrochemical distributors serving French and German agricultural markets. Bavarian chemical clusters prioritize backward-integrated suppliers with validated lot-to-lot consistency documentation.
United States
EPA tolerance reassessments under FIFRA reshape allowable copper residues in agricultural commodities, directly influencing formulation concentrations at Iowa and Illinois feed compounders. FDA heavy-metal specifications for nutritional supplements restrict qualified supplier pools for California and New Jersey nutraceutical manufacturers. American Elements leverages vertically integrated rare materials platforms to sustain specification-grade output for pharmaceutical and electronics clients.
India
BIS quality mark adoption and PLI scheme incentives for domestic agrochemical manufacturing open import substitution opportunities for carbonate feedstock suppliers serving Maharashtra and Gujarat formulation clusters. FSSAI-compliant material for copper fortification faces tightening heavy-metal limits that concentrate procurement with certified producers. CDSCO pharmaceutical-grade requirements extend certification timelines for new market entrants lacking ICP-MS analytical capabilities.
Belgium
Antwerp-Rotterdam chemical corridor demand for pellet-form carbonate in fixed-bed catalyst applications rewards producers with continuous precipitation reactor capabilities. ECHA REACH enforcement eliminates import pathways for Asian manufacturers lacking European legal entity representation and full toxicological data packages. Dutch and Belgian chemical process operators consolidate supply relationships with certified continuous-system operators.
Copper (II) Carbonate Basic Market Competitive Landscape
Player mix skews toward vertically integrated specialty chemical houses and cost-optimized regional precipitators. The vendor base separates into REACH-registered European suppliers, ISO 9001-certified North American specification-grade producers, and volume-driven Chinese technical-grade manufacturers. Three strategic archetypes dominate: compendial-grade pharmaceutical suppliers, commodity agrochemical feedstock producers, and rare/advanced materials platform operators. Competitive moves concentrate on backward integration into copper concentrate sourcing and continuous crystallization technology licensing.
Among specification-grade suppliers, American Elements and Merck KGaA exemplify the vertically integrated archetype serving pharmaceutical and electronics applications with stringent analytical standards. Jiangxi Jiangnan New Materials Technology occupies the cost-competitive technical-grade position, competing primarily on volume pricing into Asian agrochemical formulators. Dr. Paul Lohmann represents the European compendial specialist tier, anchoring supply relationships through controlled-substance distribution networks and heavy-metal documentation capabilities scarce among commodity producers.
| Leading Market Players |
|---|
| American Elements |
| Merck KGaA |
| Dr. Paul Lohmann |
| Alfa Aesar |
| Haihang Industry |
| Hangzhou Dayangchem |
| Xiamen Hisunny Chemical |
| Pan-Continental Chemical |
| Jiangxi Jiangnan New Materials Technology |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements with copper concentrate suppliers lock in feedstock access and price visibility for carbonate producers serving REACH-registered European formulators, insulating certified manufacturers from London Metal Exchange volatility while compressing spot-market players into margin-negative positions. These contract structures concentrate procurement power with backward-integrated specialists capable of spanning precipitator chemistry and mining economics.
Pricing Analysis
Cost-plus contracts indexed to LME copper cathode pricing dominate technical-grade transactions, with sodium carbonate and energy pass-through clauses protecting Jiangxi-based producers from input volatility. Three-tier pricing structure across pharmaceutical, technical, and food-grade levels separates USP-certified crystals commanding analytical validation premiums from commodity powder volumes. Cost compression in technical-grade supply is intensifying because Chinese precipitation capacity additions outpace fungicide formulation demand growth. Agrochemical distributors in Jiangsu province exhibit highest price sensitivity, while German pharmaceutical compounders prioritize lot-to-lot consistency over unit economics.
Supply Chain Analysis
China produces seventy percent of global technical-grade carbonate powder, with Jiangxi province precipitation facilities feeding Jiangsu and Shandong agrochemical clusters. Copper sulfate feedstock draws from domestic smelter output and Chilean concentrate imports, while sodium carbonate rests on Inner Mongolian soda ash production. Single-source vulnerability concentrates in Jiangxi-based technical-grade supply, where environmental compliance investments are fragmenting producer viability. Distribution runs through mineral processing distributors for ceramic pigment offtake and controlled-substance networks for pharmaceutical-grade crystals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Copper (II) carbonate basic supply is approaching a platform-economics inflection as REACH dossier interoperability and certification data exchange reshape supplier eligibility, with ECHA's substance database becoming the coordination layer that determines market access.
For Market Incumbents: Consolidate compendial-grade certification capabilities through ICP-MS laboratory investment and USP documentation systems, defending against continuous-process technology licensors from Belgian chemical corridors. Prioritize captive copper concentrate offtake agreements with Chilean or Peruvian mining operations to secure feedstock cost position against spot-market volatility. For New Entrants and Emerging Players: CDSCO pharmaceutical-grade fast-track certification opens white-space positioning in Indian nutraceutical supply, where FSSAI-compliant copper fortification demand outpaces domestic analytical chemistry capacity. Target Maharashtra and Gujarat formulation clusters with BIS quality mark adoption as the procurement gatekeeper, leveraging PLI scheme incentives for domestic agrochemical manufacturing scale. For Investors and Strategic Acquirers: Continuous-crystallization technology specialists with validated pharmaceutical-grade output represent the acquisition target archetype, given specification-grade margin pools and scarcity of ICP-MS analytical talent. Watch for ECHA enforcement actions against non-compliant Asian importers as the inflection signal indicating volume redistribution toward certified European producers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Copper Concentrate | Long-term offtake agreements with Chilean mining operations secure feedstock cost visibility against LME volatility. |
| Continuous Crystallization Technology Licensing | Belgian and Dutch chemical process operators reward validated lot-to-lot consistency with specification-grade contracts. |
| REACH Only Representative Establishment | European legal entity representation eliminates import pathway barriers for Asian manufacturers seeking German formulation access. |
| ICP-MS Analytical Capability Buildout | Heavy-metal testing expertise scarcity concentrates USP and EP certification timelines with qualified laboratory operators. |
| Closed-Loop Wastewater Recovery Systems | China MEE discharge compliance rewards integrated copper recovery with reduced environmental capital requirements. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across the copper carbonate value chain, including agrochemical formulation managers at Jiangsu and Shandong manufacturing clusters, ceramic pigment procurement leads at Italian and Spanish tile producers, pharmaceutical compounders in Baden-Württemberg, and copper salt distribution specialists in the Antwerp-Rotterdam corridor. Secondary validation drew from ECHA REACH registration databases, EPA FIFRA tolerance reassessment dockets, China MEE discharge compliance filings, and customs trade data for carbonate powder movements. Bottom-up precipitation capacity estimates and top-down fungicide formulation demand triangulated volume figures across the analysis window.
Across the projection horizon, the analytical framework modeled segmentation dimensions including grade tier (pharmaceutical, technical, food, chemical), physical form (powder, crystals, granules, pellets), end-use industry (agriculture, paints and coatings, chemical manufacturing, nutraceuticals), and regional production hub (China, Germany, United States, India, Belgium). CAGRs were derived from weighted average growth rates across these segments, with copper concentrate price volatility, REACH registration compliance rates, and continuous-process technology adoption curves serving as key forecast inputs.
Underlying assumptions cover sustained EPA tolerance frameworks for copper residues, REACH dossier completeness enforcement continuity, and China MEE discharge limit stringency, with deviation risk concentrated in synthetic triazole substitution acceleration or ECHA import pathway restrictions tightening faster than compliance investment cycles. Recalibration cycles align with material shifts in regulatory enforcement patterns, copper concentrate contract renegotiation windows, and pharmaceutical-grade certification renewal timelines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.