
 Congenital Adrenal Hyperplasia Treatment Market | 2026-2036
Congenital Adrenal Hyperplasia Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Congenital Adrenal Hyperplasia Treatment Market Outlook
Hospital procurement channels for CAH therapies is reconfiguring as specialty pharmacy networks gain leverage over traditional wholesale distribution. Neurocrine Biosciences leverages its endocrinology infrastructure to sustain direct-to-institution contracting. Spruce Biosciences anchors its position through focused rare-disease commercial execution. Crinetics Pharmaceuticals competes via differentiated peptide engineering for sustained-release glucocorticoid delivery.
Congenital adrenal hyperplasia treatment encompasses hormone replacement regimens that restore cortisol and aldosterone deficiencies caused by enzymatic defects in steroidogenesis, primarily targeting 21-hydroxylase deficiency through oral hydrocortisone, fludrocortisone, and novel modified-release formulations designed to mimic physiological circadian rhythms. Glucocorticoids occupy the dominant revenue position due to lifelong daily administration requirements, while oral delivery modes retain the largest patient share despite adherence challenges that transdermal patches aim to address. Pediatric applications lead absolute prescription volumes because newborn screening programs identify cases within days of birth, though adult maintenance segments present underdeveloped margin pools as patients transition from pediatric care.
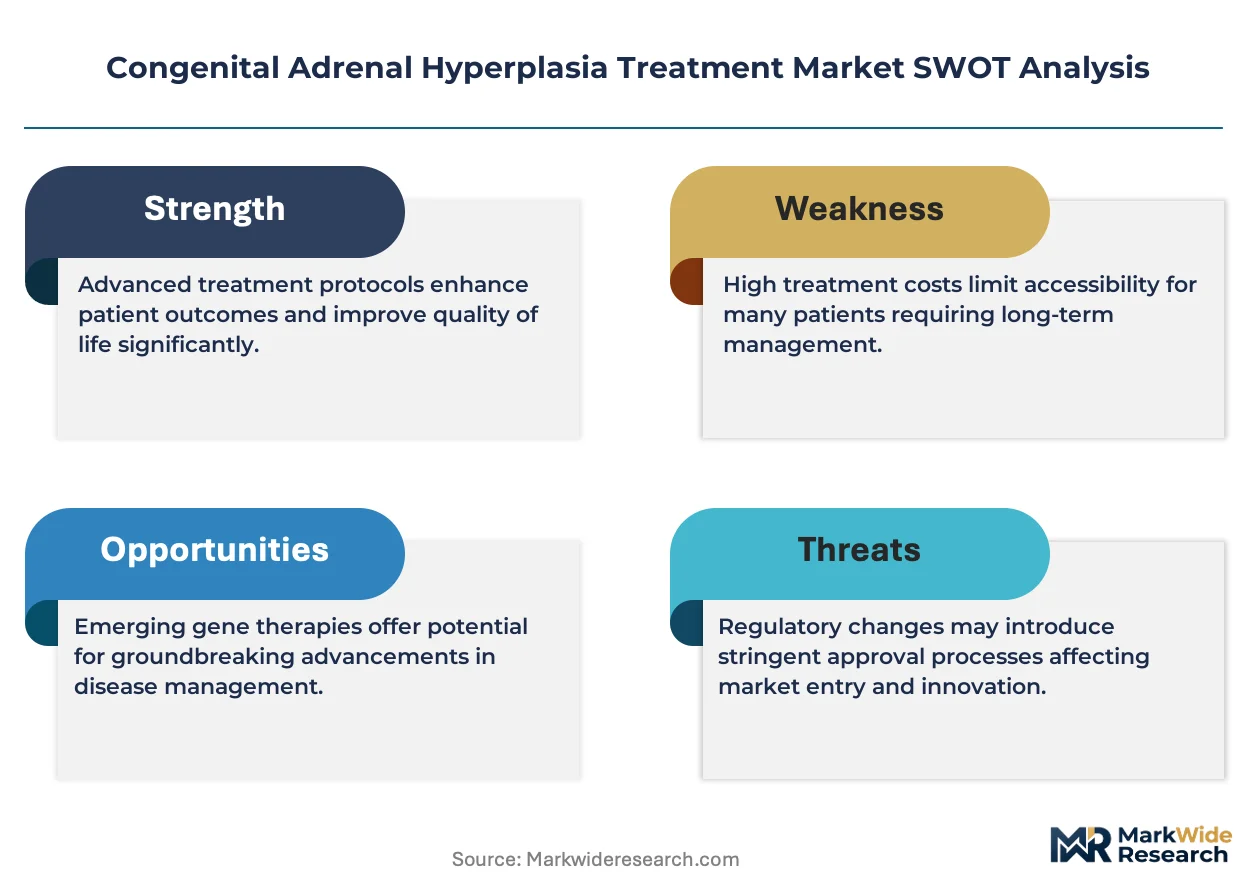
FDA orphan drug incentives and EMA's paediatric investigation plans shape clinical trial investment and pediatric labeling requirements for new CAH entrants. The EU's F-Gas Regulation constrains manufacturing inputs for certain inhalation and transdermal propellant systems, redirecting formulation development toward aqueous-based alternatives. Stakeholders must monitor regulatory divergence between FDA's flexible rare-disease pathways and EMA's stricter long-term safety surveillance mandates when prioritizing geographic launch sequencing.
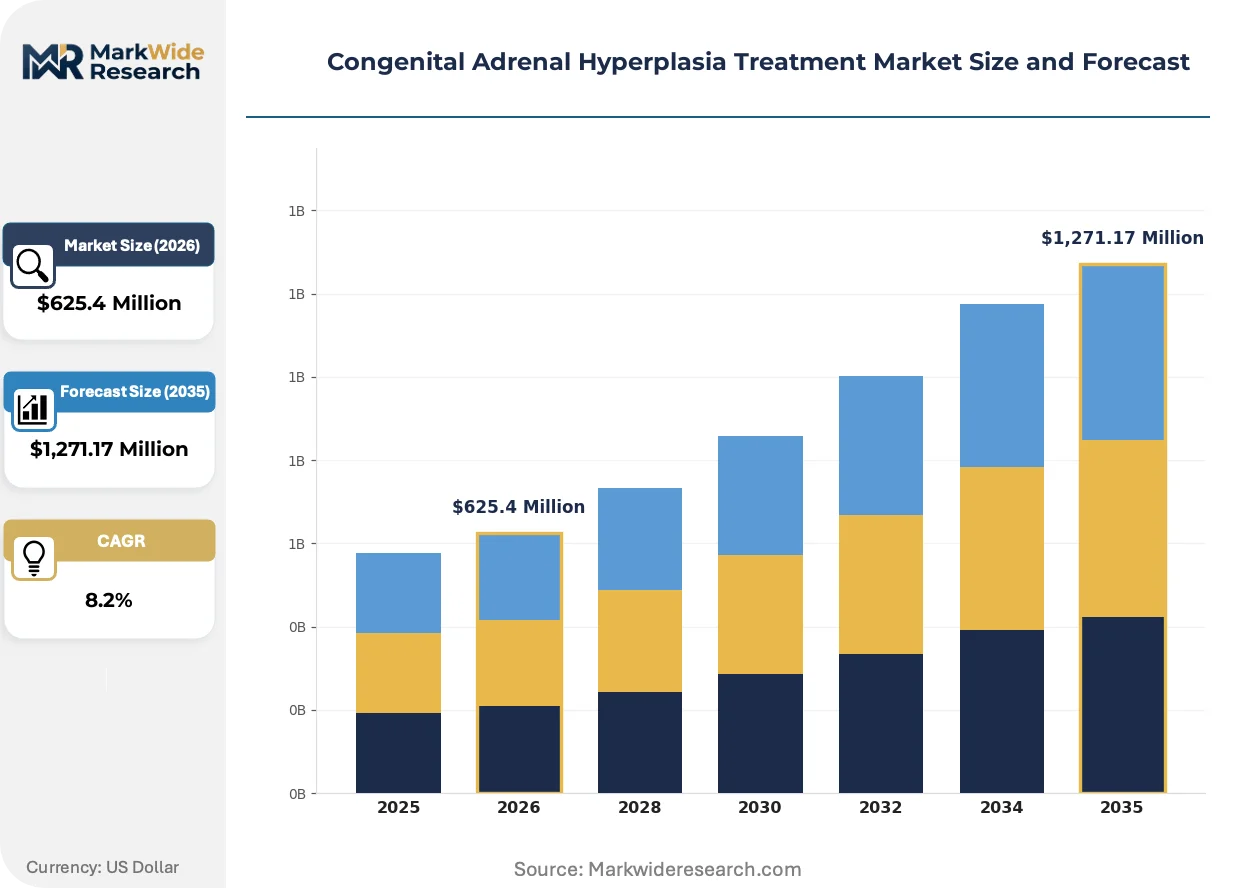
Market Dynamics
Newborn screening mandates in the United States have created a structural pull toward early diagnosis and lifelong patient retention, while the EU's F-Gas Regulation redirects formulation chemistry away from fluorinated propellants toward aqueous-based delivery systems.
Growth Catalysts
- Orphan drug incentives:The FDA's rare-disease pathway accelerates clinical trial timelines and extends market exclusivity for novel cortisol replacement therapies.
- Peptide engineering advances:Sustained-release glucocorticoid formulations now mimic circadian cortisol rhythms, improving adherence in pediatric populations.
- Specialty pharmacy networks:Direct-to-institution contracting channels bypass traditional wholesale distribution, capturing margin from hospital procurement.
Market Restraints
- Fluorinated gas constraints:The EU's F-Gas Regulation limits manufacturing inputs for transdermal propellant systems, forcing reformulation investment.
- Input cost volatility:Synthetic steroid precursor supply concentrates in Chinese API manufacturing clusters, exposing formulators to tariff and logistics risk.
- Regulatory divergence friction:EMA's stricter long-term safety surveillance mandates complicate launch sequencing against FDA's flexible rare-disease pathways.
Strategic Opportunities
- Adult transition care:Patients aging out of pediatric endocrinology clinics represent an underdeveloped maintenance segment with limited specialized service infrastructure.
- Transdermal patch delivery:Adherence challenges in oral hydrocortisone regimens create white space for modified-release skin applications.
- EMA paediatric investigation plans:Pediatric labeling requirements for new entrants create first-mover advantage in structured juvenile clinical development.
Industry Challenges
- Pediatric endocrinology workforce scarcity:Fellowship-trained specialists cluster in academic medical centers, limiting community-based CAH program expansion.
- Legacy system integration:Electronic health record interoperability between newborn screening laboratories and specialty clinics delays care coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Congenital Adrenal Hyperplasia Treatment Market |
| Market Size in 2026 | $625.4 Million |
| Market Size in 2035 | $1,271.17 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Glucocorticoids, Mineralocorticoids, Androgens, Other Hormones Delivery Mode: Oral, Injectable, Transdermal, Other Forms End User: Hospitals, Clinics, Specialty Centers, Home Care Application: Pediatric, Adult, Adolescent, Others |
| Companies Covered | Neurocrine Biosciences, Spruce Biosciences, Crinetics Pharmaceuticals, Diurnal Limited, BridgeBio Pharma, Pfizer, Sanofi, Novartis AG, Adrenas Therapeutics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Congenital Adrenal Hyperplasia Treatment Market Strategic Shifts
Modified-release glucocorticoid engineering is collapsing the distinction between replacement therapy and physiological rhythm restoration, compressing development timelines for circadian-mimetic formulations.
Peptide-based sustained-release platforms are collapsing traditional dosing frequency requirements. Pediatric endocrinology clinics in the United States are adopting these formulations at accelerating rates. This compression enables once-daily administration that previously demanded three to four daily doses.
The EU's F-Gas Regulation is constraining inhalation and transdermal propellant chemistry. Formulation development is pivoting toward aqueous-based alternatives. Transdermal patch segments face the steepest reformulation cost exposure.
Hospital procurement teams are consolidating vendor relationships through specialty pharmacy networks. Traditional wholesale distribution channels face margin compression. This consolidation is most visible in United States academic medical center contracting.
Congenital Adrenal Hyperplasia Treatment Market Segmentation
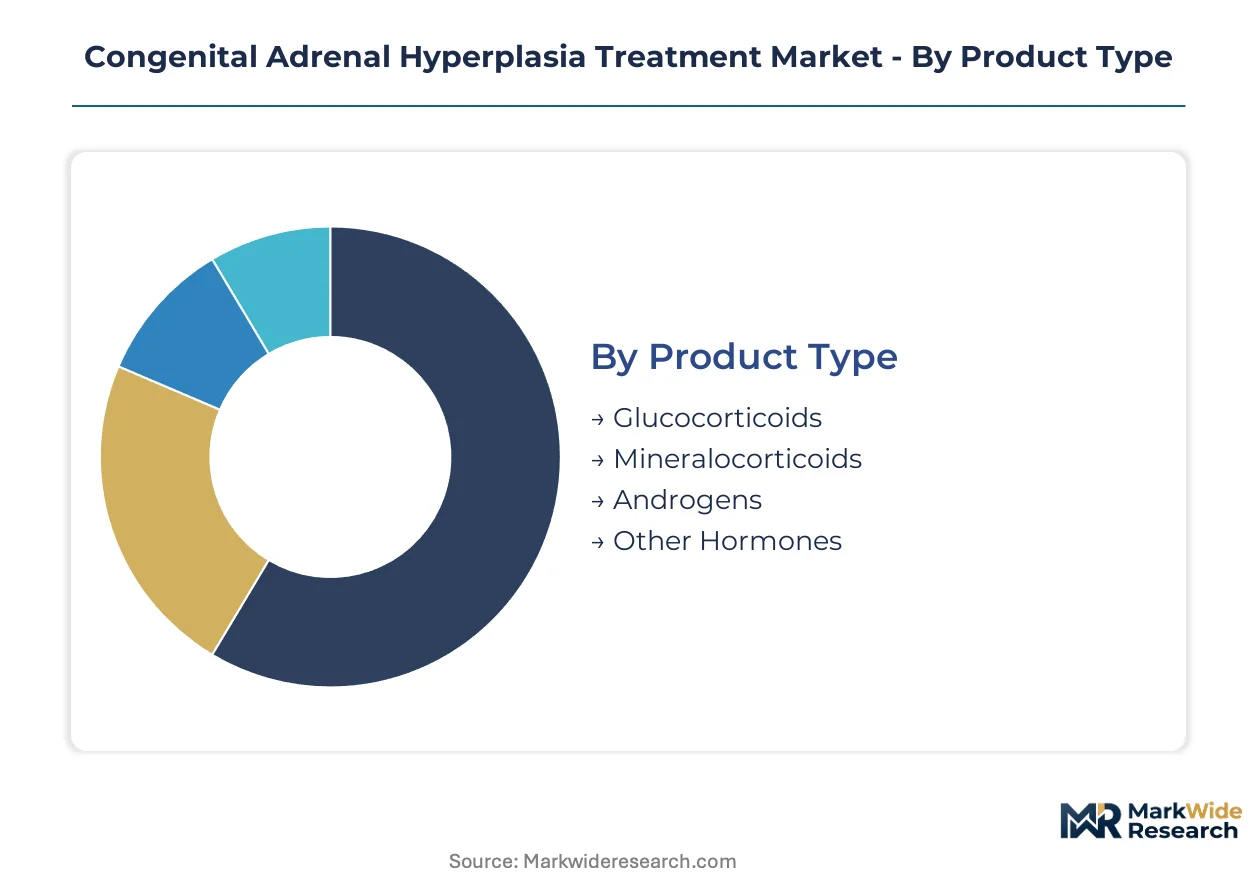
CAH treatment segmentation reflects distinct service intensity requirements across hormone replacement categories. Each segment demands specialized clinical monitoring, creating differentiated aftermarket revenue streams for manufacturers and care providers.
Product Type:
After-sales service intensity varies sharply across hormone replacement categories, with glucocorticoids demanding the most intensive therapeutic drug monitoring and dose titration support.
- Glucocorticoids:Oral hydrocortisone and modified-release cortisol formulations require lifelong daily administration with circadian-mimetic dosing protocols. Pediatric endocrinology clinics in the United States concentrate prescription volumes due to newborn screening mandates driving early diagnosis and sustained adherence programs.
- Mineralocorticoids:Fludrocortisone acetate restores aldosterone deficiency in salt-wasting CAH variants. Demand clusters in academic medical centers with dedicated adrenal insufficiency programs, where electrolyte monitoring infrastructure supports chronic therapy management.
- Androgens:Anti-androgen therapies address virilization complications in 21-hydroxylase deficiency.
- Other Hormones:Adjunctive therapies including growth hormone and thyroid replacement complete multi-hormone regimens.
Glucocorticoids hold the largest share; momentum sits with mineralocorticoids as combination therapies expand.
Delivery Mode:
Cost tier stratification separates premium modified-release platforms from commodity immediate-release generics, with reimbursement intensity driving channel selection.
- Oral:Immediate-release tablets dominate prescription volumes through established pharmacy distribution. Generic hydrocortisone concentrates in retail channels, while modified-release formulations command specialty pharmacy premiums through direct-to-institution contracting.
- Transdermal:Adhesive patch systems address pediatric adherence failures through sustained-release skin delivery. Reformulation investment is accelerating as the EU's F-Gas Regulation constrains fluorinated propellant chemistry, redirecting development toward aqueous-based alternatives.
- Injectable:Intramuscular depot formulations serve acute adrenal crisis protocols and perioperative stress dosing.
- Other Forms:Subcutaneous pumps and buccal films occupy niche development pipelines.
Oral administration retains dominant volume; transdermal platforms are expanding most quickly as adherence engineering matures.
End User:
Customer type fragmentation splits between institutional procurement teams and direct patient acquisition, with specialty pharmacy networks capturing margin from hospital systems.
- Hospitals:Academic medical centers anchor CAH care through integrated newborn screening-to-treatment pathways. Procurement consolidation favors vendors with endocrinology infrastructure and direct contracting capabilities.
- Specialty Centers:Dedicated pediatric endocrinology clinics concentrate fellowship-trained expertise and structured transition programs for adolescent patients aging into adult care.
- Clinics:Community-based endocrinology practices serve stable maintenance patients with streamlined monitoring protocols.
- Home Care:Home infusion and remote monitoring services extend care coordination beyond facility walls.
Hospitals capture the largest revenue share; specialty centers are gaining share fastest through rare-disease program expansion.
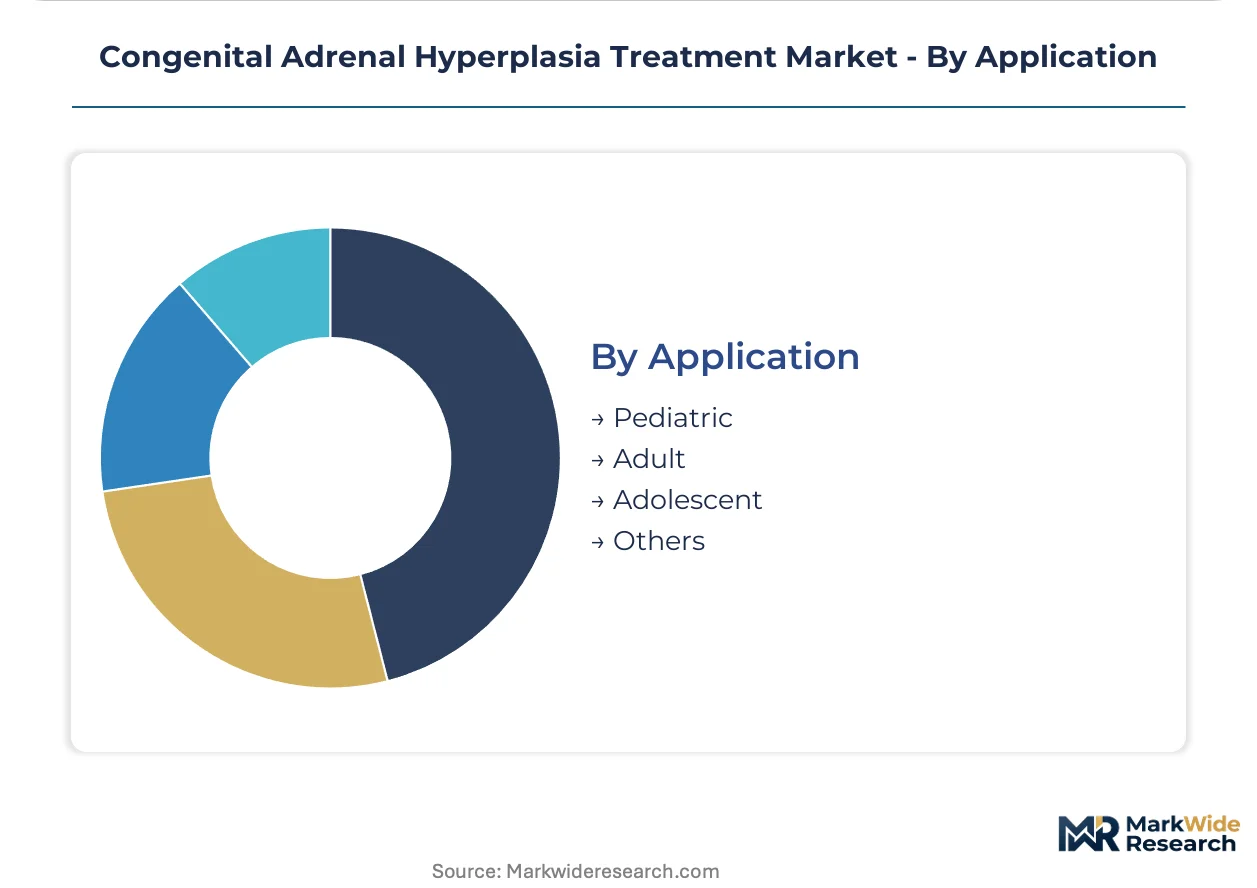
Application:
Age-based application segments reflect distinct clinical maturity levels, with pediatric infrastructure far outpacing adult service development.
- Pediatric:Newborn screening programs identify 21-hydroxylase deficiency within days of birth, creating immediate lifelong therapy requirements. United States state mandates drive diagnostic volume concentration, while EMA paediatric investigation plans shape labeling requirements for new entrants.
- Adult:Patients transitioning from pediatric care encounter fragmented endocrinology services and limited specialized infrastructure. This underdeveloped segment presents white-space opportunity for maintenance-focused delivery models and remote monitoring platforms.
- Adolescent:Pubertal management requires coordinated growth, bone health, and psychosocial support protocols.
- Others:Prenatal diagnosis and fertility preservation services occupy emerging clinical niches.
Pediatric applications dominate absolute volumes; adult segments show the steepest expansion trajectory as transition care infrastructure develops.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States Interstate 95 pharmaceutical corridor underwrites North American distribution density for CAH therapies, connecting Boston's biotech cluster through Philadelphia to Baltimore's regulatory hub.
United States
Newborn screening mandates in all 50 states create structural diagnostic pull, with state health departments funding automated steroid profiling within 48 hours of birth. FDA orphan drug incentives accelerate clinical trial timelines for novel cortisol replacement therapies. Pediatric endocrinology infrastructure concentrates in Boston's Longwood Medical Area and Houston's Texas Medical Center, where academic medical centers anchor integrated care pathways.
Germany
Reference laboratory networks in Munich and Heidelberg process neonatal steroid panels for Central European patient flows. EMA paediatric investigation plans shape labeling requirements for new market entrants seeking EU-wide approval. The Rhine-Main biotechnology corridor hosts formulation development for aqueous-based delivery systems redirecting away from fluorinated propellants.
United Kingdom
NHS England's specialist commissioning framework concentrates CAH care in 15 designated pediatric endocrinology centers. The Medicines and Healthcare products Regulatory Agency aligns post-Brexit pediatric labeling with EMA standards while maintaining separate orphan drug incentive structures. London's Great Ormond Street Hospital anchors transition care research for adolescent patients aging into adult services.
Switzerland
Swissmedic's accelerated access pathway attracts rare-disease developers seeking European market entry ahead of EMA centralized procedures. Basel's pharmaceutical cluster hosts peptide engineering operations for sustained-release glucocorticoid platforms. The country's bilateral recognition agreements with the EU and FDA enable parallel regulatory submissions.
Japan
PMDA's Sakigake designation system fast-tracks novel CAH therapies through priority review, compressing approval timelines for circadian-mimetic formulations. Tokyo's National Center for Child Health and Development maintains the country's largest pediatric adrenal insufficiency registry. Kansai's Osaka University Hospital leads Asia-Pacific clinical trial coordination for modified-release hydrocortisone programs.
Congenital Adrenal Hyperplasia Treatment Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream. The CAH treatment market structures around three tiers: large pharmaceutical conglomerates with endocrinology portfolios, mid-cap rare-disease specialists with focused commercial infrastructure, and emerging biotechs with peptide engineering capabilities. Strategic archetypes include orphan drug pathway navigators, circadian-mimetic formulation developers, and pediatric-to-adult transition care architects. Dominant competitive moves center on direct-to-institution contracting and sustained-release platform differentiation.
Within the rare-disease specialist tier, Neurocrine Biosciences and Spruce Biosciences exemplify focused commercial execution models, while Crinetics Pharmaceuticals occupies a position in peptide-based sustained-release engineering. These three entities anchor distinct strategic vectors: endocrinology infrastructure leverage, rare-disease program concentration, and differentiated delivery technology respectively.
| Leading Market Players |
|---|
| Neurocrine Biosciences |
| Spruce Biosciences |
| Crinetics Pharmaceuticals |
| Diurnal Limited |
| BridgeBio Pharma |
| Pfizer |
| Sanofi |
| Novartis AG |
| Adrenas Therapeutics |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in synthetic steroid precursor manufacturing across Chinese API clusters is compressing supplier margins and amplifying pricing power for integrated formulators with captive supply arrangements. This utilization squeeze propagates through contract manufacturing organizations serving European and North American markets, forcing volume-commitment structures that reshape procurement negotiations.
Pricing Analysis
Volume-discount tiering structures separate modified-release glucocorticoid platforms from commodity immediate-release hydrocortisone, with specialty pharmacy networks capturing premium spreads through direct-to-institution contracting. Price differentiation rests on circadian-mimetic formulation certification and pediatric labeling status under FDA orphan drug pathways. Cost compression in generic oral tablets is intensifying because of wholesale distribution margin compression. Academic medical centers demonstrate lowest price sensitivity due to bundled reimbursement frameworks, while community clinics face acute budget constraints.
Supply Chain Analysis
Export-control regimes limiting fluorinated propellant chemistry under the EU's F-Gas Regulation are redirecting transdermal formulation sourcing toward aqueous-based alternatives developed in Germany and Switzerland. Synthetic steroid precursors draw from manufacturing clusters in China and India, with fludrocortisone acetate APIs resting on specialized fermentation capabilities concentrated in these jurisdictions. Single-source vulnerability in 21-hydroxylase inhibitor supply creates exposure to tariff and logistics disruption. Distribution runs through specialty pharmacy networks that bypass traditional wholesale channels for hospital procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The CAH treatment market functions as a service-attach opportunity where therapeutic drug monitoring and dose titration support expand faster than pharmaceutical product revenue, creating recurring revenue layers that outpace hardware margins.
For Market Incumbents: Pre-empt peptide engineering specialists from capturing circadian-mimetic formulation share by accelerating sustained-release platform development and securing pediatric exclusivity through EMA paediatric investigation plan completion. Backward integration into synthetic steroid precursor manufacturing mitigates Chinese API supply concentration risk. Channel control through direct-to-institution contracting with academic medical centers defends against specialty pharmacy network disintermediation. For New Entrants and Emerging Players: Geographic underpenetration in adult transition care infrastructure across community endocrinology practices offers white-space expansion with limited incumbent service density. Target remote monitoring platform deployment for patients aging out of pediatric clinics, where specialized maintenance protocols remain undeveloped. Partner with hospital systems lacking dedicated adrenal insufficiency programs to embed transition care protocols. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across aqueous-based formulation development as fluorinated propellant reformulation costs dissipate, improving returns on modified-release platform investments. Acquisition candidates with peptide engineering capabilities and orphan drug pathway navigation expertise present strongest positioning. Watch FDA pediatric labeling decisions for novel cortisol replacement therapies as inflection indicators for competitive positioning shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Orphan Drug Pathway Navigation | FDA rare-disease designation accelerates clinical timelines and extends market exclusivity for novel entrants. |
| Peptide Engineering Scale-Up | Sustained-release platform manufacturing in Basel and Boston clusters enables circadian-mimetic dosing differentiation. |
| Specialty Pharmacy Network Partnership | Direct-to-institution contracting bypasses wholesale distribution and captures hospital procurement margin. |
| Aqueous-Based Formulation Transition | F-Gas Regulation compliance redirects transdermal development away from fluorinated propellant chemistry. |
| Adult Transition Care Infrastructure | Remote monitoring and maintenance protocol deployment addresses underdeveloped patient aging pathways. |
Study Parameters
Operator-level perspectives from pediatric endocrinologists, specialty pharmacy procurement directors, regulatory affairs leads at rare-disease developers, and hospital formulary managers anchored the qualitative base. Secondary validation drew from FDA orphan drug designations, EMA paediatric investigation plans, ClinicalTrials.gov entries, and newborn screening program documentation across state health departments. Bottom-up prescription volume modeling triangulated against top-down manufacturer revenue disclosures.
Scenario-bracketing framed demand projections across the analysis window, with segmentation modeling across hormone replacement category, delivery mode, patient age cohort, and regional regulatory cluster. CAGRs derived from iterative reconciliation of epidemiological incidence data, treatment adherence assumptions, and pricing trajectory estimates. Forecast inputs incorporated newborn screening mandate expansion patterns and pediatric-to-adult transition care infrastructure development rates.
The forecast holds incumbent behavior within observed patterns; aggressive moves by mid-cap rare-disease specialists with peptide engineering capabilities would shift outcomes. Material shifts in FDA pediatric labeling requirements or EMA long-term safety surveillance mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Appendicitis Market
Specialty Medicine
Idiopathic Short Stature Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) Market
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Complex Regional Pain Syndrome (CRPS) Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Oral Cancer Treatment Market
Specialty Medicine
GCC Idiopathic Pulmonary Fibrosis Treatment Market
Specialty Medicine
Global Restless Legs Syndrome Market
Specialty Medicine
Global Cryptococcosis Treatment Market
Specialty Medicine
Global Amyotrophic Lateral Sclerosis (ALS) Treatment Market
Specialty Medicine
Vitiligo Treatment Market
Specialty Medicine
Ovarian Cysts Market
Specialty Medicine
Non-Alcoholic Steatohepatitis Treatment Market
Specialty Medicine
Sports Medicine Market