
 Carcinoid Syndrome Management Market | 2026-2036
Carcinoid Syndrome Management Market Size, Share, and Industry Trends Forecast 2026-2036
Carcinoid Syndrome Management Market Analysis
Outpatient facilities is repositioning their role in carcinoid syndrome care, shifting from hospital-dependent infusion centers to community-based administration sites. Novartis AG anchors its presence through sustained investment in peptide receptor radionuclide therapy infrastructure. Ipsen Biopharmaceuticals specializes in long-acting somatostatin analog formulations that dominate maintenance therapy protocols. Bristol Myers Squibb competes through targeted therapy development focused on refractory patient populations.
Carcinoid syndrome management encompasses pharmacological interventions that modulate serotonin and vasoactive peptide overproduction in neuroendocrine tumors, primarily using synthetic somatostatin analogs with half-lives exceeding 28 days to suppress hormone secretion and control flushing and diarrhea symptoms. The industrial purpose centers on reducing morbidity from carcinoid heart disease and improving quality-of-life metrics in metastatic disease. Somatostatin analogs occupy the mature core of the product portfolio, while targeted therapies represent the fastest-expanding margin pool as resistance patterns drive combination protocols. Injectable delivery mode sustains the highest volume share due to depot formulation requirements, though oral alternatives are gaining traction in maintenance settings.
FDA orphan drug incentives and EMA's PRIME designation scheme both accelerate clinical development timelines for rare neuroendocrine indications, directly shaping R&D investment allocation across manufacturers. The FDA's Breakthrough Therapy pathway and EMA's adaptive licensing frameworks further compress time-to-market for novel agents addressing uncontrolled hormone secretion. Stakeholders must monitor how somatostatin analog biosimilar entry reshapes pricing dynamics and whether radioligand therapy reimbursement thresholds expand beyond tertiary academic centers.
Market Dynamics
Peptide receptor radionuclide therapy infrastructure expansion is redistributing patient volumes from tertiary academic centers toward community-based specialty clinics, compressing traditional referral hierarchies and forcing reimbursement recalibration across outpatient networks.
Growth Catalysts
- FDA Orphan Drug Incentives:Tax credits and market exclusivity provisions accelerate clinical trial enrollment for somatostatin analog candidates. Manufacturers prioritize rare neuroendocrine indications over crowded oncology segments.
- Specialty Clinic Capacity Expansion:Outpatient facilities in the United States deploy dedicated neuroendocrine tumor infusion suites. These sites capture maintenance therapy volumes previously retained by hospital-based centers.
- Long-Acting Depot Formulations:Synthetic somatostatin analogs with 28-day dosing intervals reduce patient burden. Extended half-life chemistry improves adherence metrics in metastatic populations.
Market Restraints
- Radioligand Supply Concentration:Lutetium-177 production clusters at limited cyclotron facilities in Germany and the Netherlands. Geopolitical disruption threatens therapy continuity for refractory patients.
- Specialized Endocrinology Workforce Scarcity:Fellowship-trained neuroendocrine tumor specialists concentrate at academic medical centers. Community hospitals lack diagnostic and therapeutic expertise for complex hormone secretion management.
- Biosimilar Pricing Compression:Somatostatin analog reference products face imminent patent expiration. Originators anticipate margin erosion as follow-on biologics enter maintenance therapy protocols.
Strategic Opportunities
- Underpenetrated Asia-Pacific Markets:Japan and South Korea demonstrate rising neuroendocrine tumor incidence without proportional specialist infrastructure. Localized diagnostic protocols and referral networks remain undeveloped relative to Western benchmarks.
- Oral Somatostatin Analog Development:Non-injectable formulations address patient preference for home-based administration. Oral bioavailability breakthroughs would displace depot injection requirements in stable disease maintenance.
- EMA PRIME Designation Pathway:Priority medicines status accelerates assessment timelines for novel targeted therapies. European market access advantages incentivize early regulatory engagement for refractory population agents.
Industry Challenges
- Nuclear Medicine Technologist Pipeline Collapse:Radioligand therapy expansion outpaces trained personnel supply. Cyclotron operation and radiopharmaceutical compounding require certification timelines incompatible with demand growth.
- Biomarker Standardization Delays:Chromogranin A and serotonin metabolite assays lack harmonized reference ranges. Inconsistent diagnostic thresholds complicate treatment response assessment across clinical trial sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Carcinoid Syndrome Management Market |
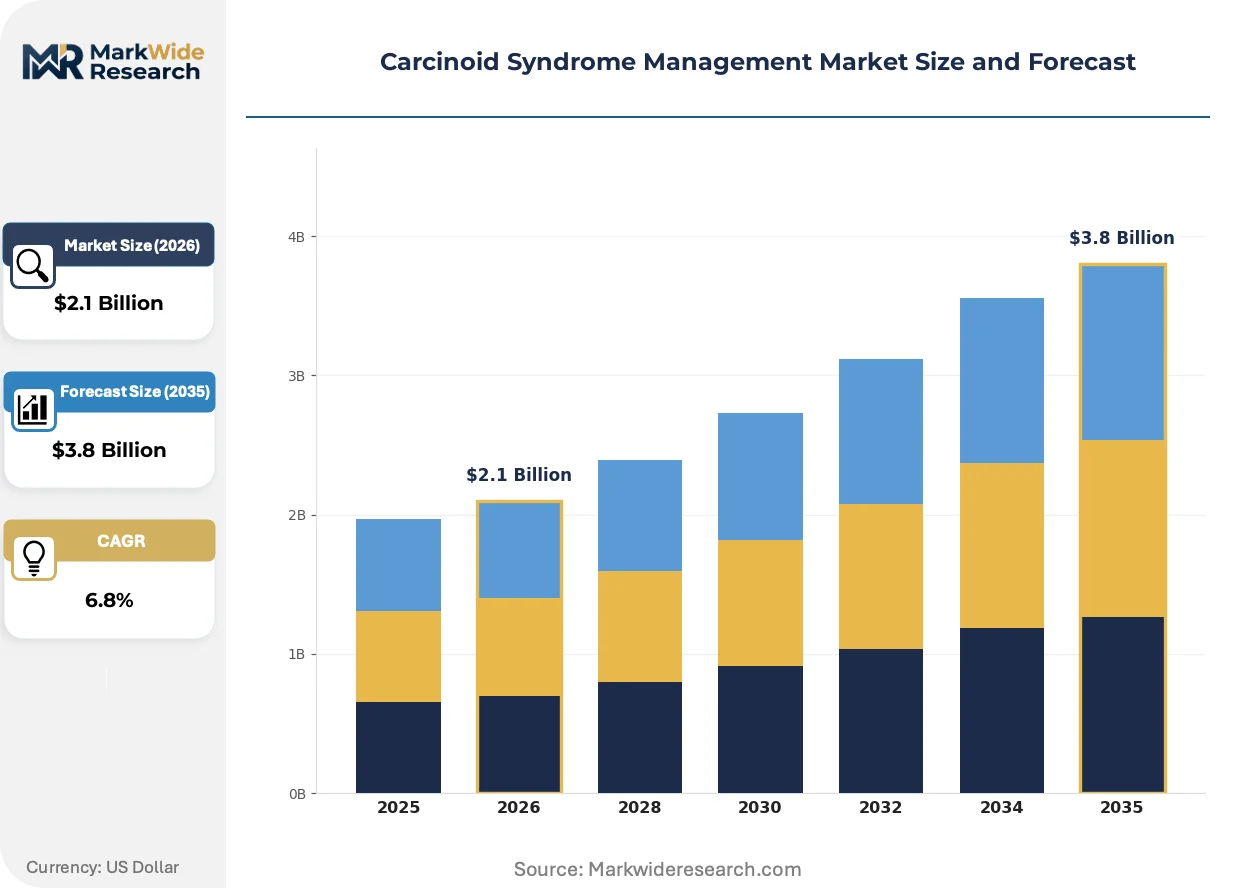
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Somatostatin Analogs, Targeted Therapies, Chemotherapy Agents, Symptomatic Treatments Delivery Mode: Injectable, Oral, Infusion, Transdermal End User: Hospitals, Specialty Clinics, Outpatient Facilities, Home Healthcare Therapy Area: Oncology, Gastroenterology, Endocrinology, Palliative Care |
| Companies Covered | Bristol Myers Squibb, Boehringer Ingelheim, Novartis AG, Advanced Accelerator Applications, Exelixis, Ipsen Biopharmaceuticals, Teva Pharmaceutical Industries, Eli Lilly and Company, Pfizer, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Carcinoid Syndrome Management Market Emerging Trajectories
Radioligand therapy logistics and oral formulation chemistry are compressing traditional administration models. These forces reshape manufacturing scale, site-of-care economics, and patient pathway design simultaneously.
Peptide receptor radionuclide therapy is electrifying the treatment landscape for somatostatin receptor-positive disease. Tertiary centers in Germany and the United States deploy dedicated theranostic units combining gallium-68 imaging with lutetium-177 delivery. This convergence is electrifying infrastructure investment cycles and displacing conventional chemotherapy protocols in refractory patient stratification.
EMA's adaptive licensing framework permits conditional approval based on intermediate clinical endpoints. Manufacturers submit progression-free survival data rather than waiting for overall survival maturation. Neuroendocrine tumor indications with unmet need qualify for accelerated assessment, compressing time-to-reimbursement negotiations with national health technology assessment bodies.
Home administration programs for long-acting somatostatin analogs are displacing clinic-dependent infusion scheduling. Patient training protocols and remote monitoring infrastructure enable self-injection in stable metastatic populations. This shift concentrates in the United States and Nordic countries where reimbursement supports nursing substitution and telehealth follow-up.
Carcinoid Syndrome Management Market Segmentation
Segmentation in carcinoid syndrome management reveals how treatment protocols stratify across site-of-care economics, formulation chemistry, and specialist workforce availability. These divisions directly shape procurement decisions, reimbursement negotiations, and manufacturer R&D allocation across the therapeutic landscape.
Product Type:
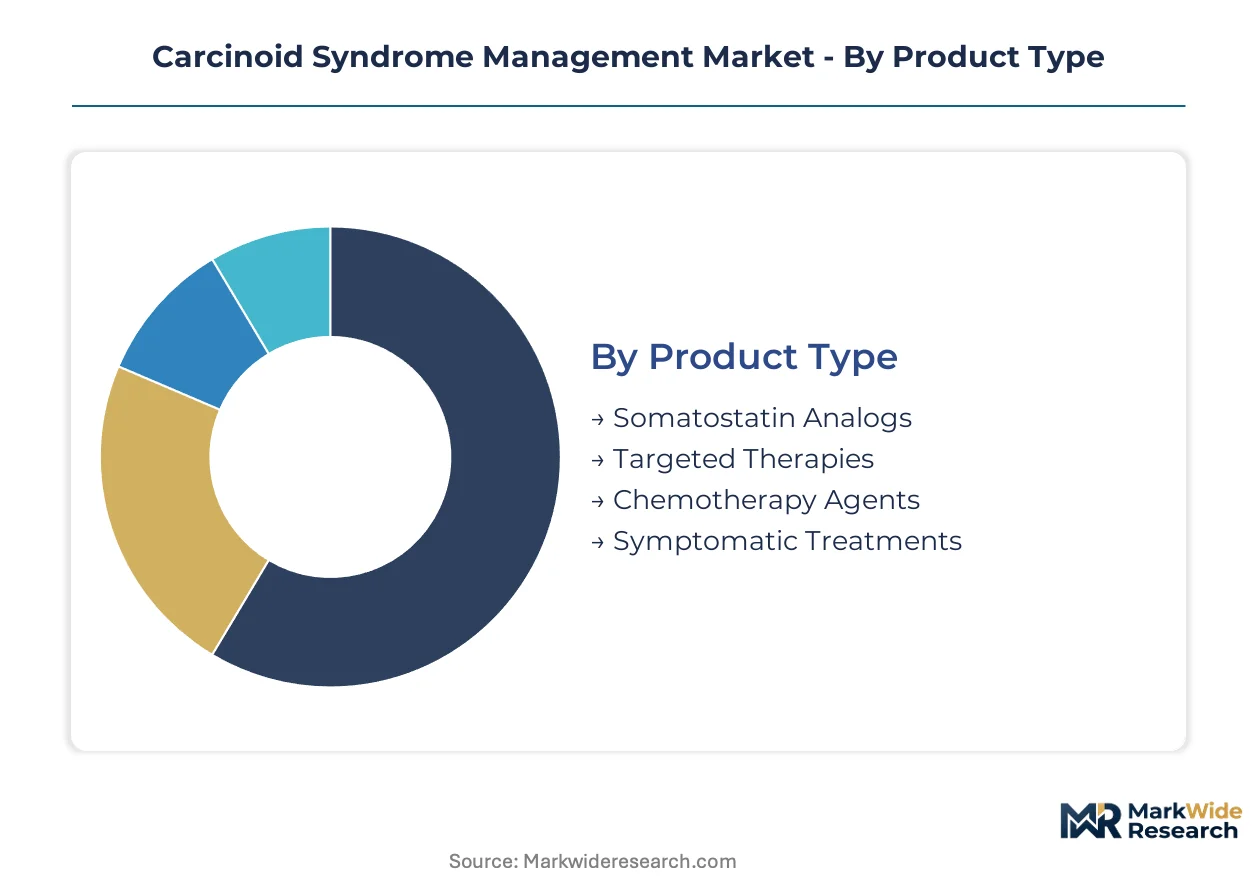
Prescribers select product categories based on disease stage, hormone secretion burden, and prior therapy resistance patterns.
- Somatostatin Analogs:Synthetic peptide formulations with extended half-lives suppress serotonin and vasoactive peptide overproduction. Demand concentrates in United States maintenance therapy protocols where 28-day depot injections reduce clinic visit frequency for metastatic populations.
- Targeted Therapies:Small-molecule inhibitors address refractory hormone secretion through mTOR and tyrosine kinase pathways. United States academic medical centers drive adoption as resistance to first-line somatostatin analogs escalates combination protocol development.
- Chemotherapy Agents:Cytotoxic regimens retain niche application in high-grade neuroendocrine neoplasms with rapid proliferation indices.
- Symptomatic Treatments:Serotonin receptor antagonists and antidiarrheal agents provide adjunctive control for breakthrough flushing and diarrhea episodes.
Somatostatin analogs lead on scale; targeted therapies lead on momentum.
Delivery Mode:
Route of administration determines site-of-care requirements, nursing resource allocation, and patient adherence economics.
- Injectable:Depot formulations requiring intramuscular or subcutaneous delivery sustain the dominant volume share. Specialty clinics in the United States capture these volumes through dedicated neuroendocrine tumor infusion suites.
- Oral:Emerging formulations target patient preference for home-based administration. Japan's aging patient population drives interest in non-injectable alternatives for stable disease maintenance.
- Infusion:Peptide receptor radionuclide therapy requires controlled radiopharmaceutical administration at licensed nuclear medicine facilities.
- Transdermal:Patch-based delivery remains experimental for somatostatin analog absorption with limited commercial penetration.
Injectable delivery commands current volume; oral formulations are climbing the fastest.
End User:
Care setting selection reflects therapy complexity, reimbursement structure, and proximity to specialized diagnostic capabilities.
- Hospitals:Tertiary academic centers manage complex cases requiring multidisciplinary tumor boards and cyclotron-adjacent radioligand facilities. Germany's university hospitals anchor peptide receptor radionuclide therapy capacity.
- Specialty Clinics:Dedicated neuroendocrine tumor centers capture maintenance therapy volumes through streamlined infusion protocols. United States outpatient networks expand capacity to intercept hospital-dependent referrals.
- Outpatient Facilities:Community-based sites deploy long-acting somatostatin analog administration with remote specialist oversight.
- Home Healthcare:Self-injection programs with nursing substitution concentrate in Nordic countries and United States markets with telehealth reimbursement support.
Specialty clinics lead on scale; home healthcare leads on momentum.
Therapy Area:
Specialist discipline involvement varies with tumor origin site, hormone secretion profile, and comorbidity complexity.
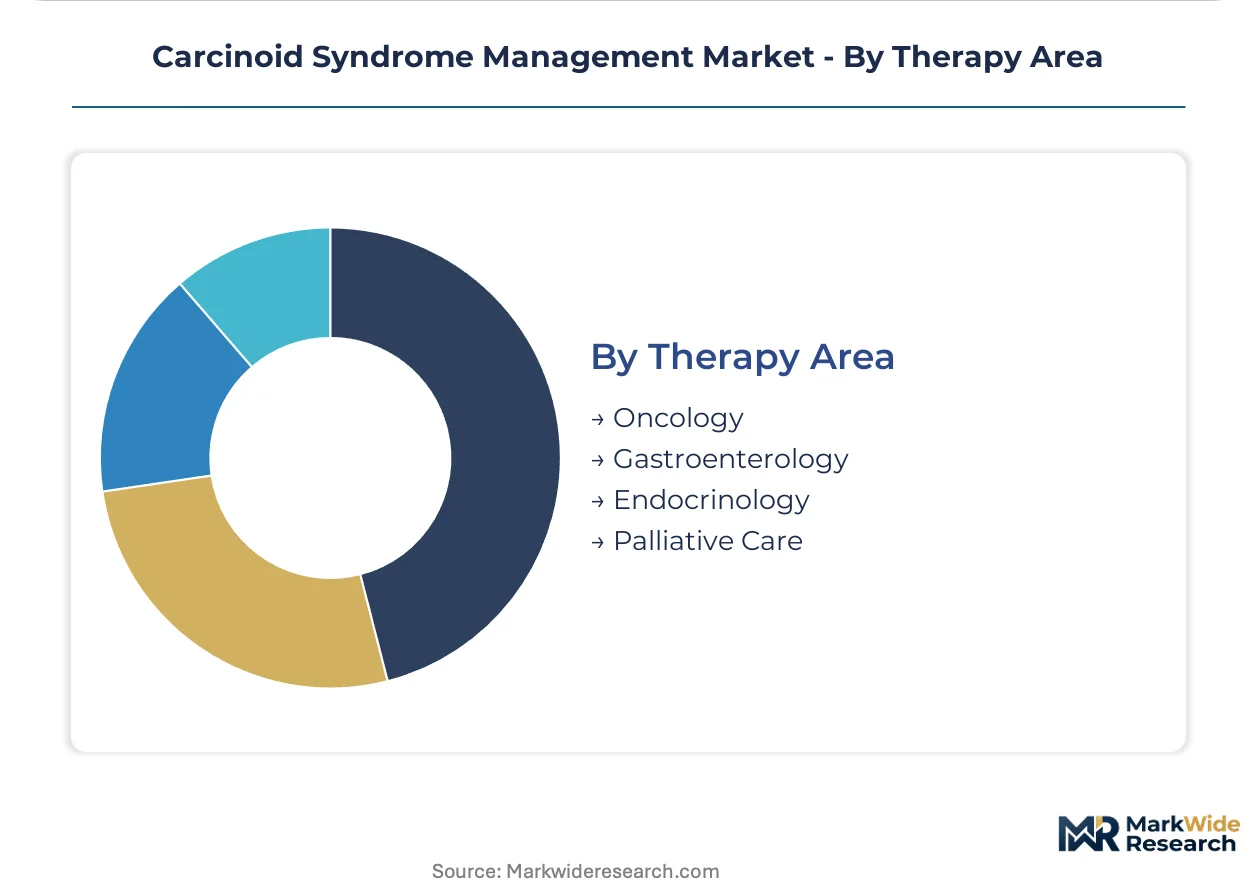
- Oncology:Medical oncologists coordinate systemic therapy selection and clinical trial enrollment. United States comprehensive cancer centers integrate somatostatin analogs with targeted therapy sequencing.
- Gastroenterology:GI specialists manage midgut primary tumors and carcinoid diarrhea complications. European referral networks emphasize gastroenterologist-led diagnostic pathways.
- Endocrinology:Hormone secretion management requires fellowship-trained neuroendocrine tumor expertise concentrated at academic centers.
- Palliative Care:Symptom burden reduction in advanced disease integrates with quality-of-life metrics and hospice transition planning.
Oncology leads on scale; palliative care leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is concentrating somatostatin analog manufacturing in jurisdictions with streamlined FDA and EMA pathways, while radioligand therapy capacity clusters near cyclotron facilities in Germany and the Netherlands to minimize isotope decay logistics.
United States
Academic medical centers in Boston and Houston anchor peptide receptor radionuclide therapy demand through dedicated theranostic units. FDA orphan drug tax credits accelerate clinical trial enrollment for novel somatostatin analog candidates. Specialty clinics in Texas and Florida expand neuroendocrine tumor infusion capacity to intercept hospital-dependent referrals.
Germany
University hospitals in Munich and Heidelberg deploy concentrated lutetium-177 production infrastructure alongside gallium-68 imaging capabilities. EMA's PRIME designation scheme compresses assessment timelines for refractory population agents. The Baden-Württemberg cluster integrates cyclotron operation with radiopharmaceutical compounding for cross-border supply.
Japan
Aging demographics drive interest in oral somatostatin analog alternatives for stable disease maintenance. PMDA's Sakigake designation accelerates priority review for novel targeted therapies addressing uncontrolled hormone secretion. Tokyo and Osaka medical centers concentrate fellowship-trained neuroendocrine tumor expertise.
United Kingdom
NHS England's specialized commissioning framework centralizes complex case management at London and Manchester tertiary centers. MHRA post-Brexit regulatory autonomy permits tailored approval pathways for radioligand therapy reimbursement. The Oxford-Cambridge corridor anchors diagnostic biomarker standardization research.
Switzerland
Swissmedic's expedited access pathway attracts headquarters operations for manufacturers seeking concurrent EMA and FDA alignment. Basel and Zurich host concentrated pharmaceutical R&D infrastructure for long-acting depot formulation chemistry. The country's bilateral agreements facilitate cross-border patient access to German radioligand facilities.
Carcinoid Syndrome Management Market Vendor Landscape
Strategic partnerships dominate the current landscape as manufacturers seek radioligand supply security and biosimilar defense positioning. The market structure concentrates around three tiers: originators with established depot formulations, radiopharmaceutical specialists with cyclotron-adjacent infrastructure, and targeted therapy developers addressing refractory segments. Two archetypes define competitive positioning: vertically integrated theranostic platforms and focused somatostatin analog formulators. Partnership concentration and portfolio diversification represent the dominant competitive moves, with manufacturers securing isotope supply chains and expanding into adjacent neuroendocrine tumor indications.
Among originator-tier pharmaceutical companies, Novartis AG and Ipsen Biopharmaceuticals exemplify divergent strategic positioning within somatostatin receptor modulation. Bristol Myers Squibb occupies a position in the targeted therapy segment for resistant patient populations. These three anchors represent distinct competitive vectors: radioligand infrastructure investment, long-acting formulation specialization, and small-molecule resistance-pattern targeting.
| Leading Market Players |
|---|
| Bristol Myers Squibb |
| Boehringer Ingelheim |
| Novartis AG |
| Advanced Accelerator Applications |
| Exelixis |
| Ipsen Biopharmaceuticals |
| Teva Pharmaceutical Industries |
| Eli Lilly and Company |
| Pfizer |
| Others |
Supply Flow & Price Mechanics
Lutetium-177 isotope production costs cascade through peptide receptor radionuclide therapy pricing tiers, with cyclotron-concentrated supply in Germany and the Netherlands feeding premium reimbursement bands at academic centers while community clinics absorb logistics markups for cross-border isotope transport.
Pricing Analysis
Specialty clinic markup layers differentiate somatostatin analog administration costs across United States outpatient networks, with three-tier pricing structure across premium, standard, and economy levels reflecting site certification status and nursing substitution availability. Brand premium for originator depot formulations persists against impending biosimilar entry, though price erosion runs through maintenance therapy protocols as follow-on biologics gain formulary placement. Academic medical centers demonstrate lowest price sensitivity due to bundled reimbursement for complex cases, while community-based infusion suites face acute cost compression from payor site-of-care differentials.
Supply Chain Analysis
Radiopharmaceutical compounding rests on concentrated cyclotron infrastructure in Germany, the Netherlands, and Belgium, with lutetium-177 supply drawing from limited nuclear reactor facilities and gallium-68 generator production clustering at university hospital radiopharmacies. Cold-chain logistics for short-half-life isotopes create single-source vulnerability where cross-border regulatory misalignment delays therapy scheduling. Distribution runs through licensed nuclear medicine facilities with DEA-controlled substance protocols, while somatostatin analog depot formulations flow through specialty pharmacy channels with temperature-controlled last-mile requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carcinoid syndrome management represents a late-cycle quality story as patient stratification shifts toward theranostic-enabled precision dosing and radioligand therapy moves from salvage to earlier-line positioning.
For Market Incumbents: Deploy backward integration into isotope production capacity to secure lutetium-177 supply continuity against geopolitical disruption threats. Originator somatostatin analog manufacturers must accelerate oral formulation development to defend maintenance therapy positioning against biosimilar pricing compression in United States outpatient networks. For New Entrants and Emerging Players: Begin with oral somatostatin analog development targeting Japan's aging patient population and home administration preference in Nordic reimbursement environments. Localized diagnostic protocol development offers entry angle into underpenetrated Asia-Pacific markets lacking neuroendocrine tumor specialist infrastructure. For Investors and Strategic Acquirers: Consolidation pressure builds where radioligand therapy capacity concentrates near cyclotron facilities and specialist workforce scarcity constrains site expansion. Long-term viability favors theranostic platform operators with integrated imaging-to-therapy workflows. Watch FDA orphan drug exclusivity expiration timelines as inflection signal for somatostatin analog competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Cyclotron Capacity Expansion | Captive isotope production insulates against cross-border supply disruption for German and Dutch facilities. |
| Oral Formulation Development | Non-injectable alternatives address patient preference and expand addressable maintenance therapy populations. |
| Theranostic Platform Integration | Combined gallium-68 imaging with lutetium-177 delivery streamlines patient selection and therapy sequencing. |
| Specialty Clinic Network Buildout | Community-based infusion capacity intercepts hospital-dependent referrals and captures site-of-care economics. |
| Biosimilar Defense Positioning | Next-generation depot chemistry and combination protocols differentiate against follow-on biologic entry. |
Methodological Framework
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with drug development executives, regulatory affairs leads, hospital procurement managers, and payer access specialists with secondary validation against FDA filings, EMA submissions, ClinicalTrials.gov records, and formulary databases. Bottom-up patient volume modeling and top-down manufacturer revenue triangulation anchored segment-weighted forecasts.
Segment-weighting across product type, delivery mode, end user, and therapy area dimensions drove analytical framework construction over the projection horizon. CAGRs derived from epidemiology-adjusted patient flow modeling, pricing trajectory assumptions, and reimbursement pathway maturation timelines. Forecast inputs incorporated somatostatin analog biosimilar entry curves and radioligand therapy capacity expansion schedules.
Several conditions sit outside the modeled scope, including pipeline asset clinical trial failures, isotope production facility regulatory shutdowns, and wholesale reimbursement policy reversals. Forecasts reflect assumptions about specialist workforce training pipeline recovery and biomarker assay standardization progress. A small set of named triggers warrants ongoing watch: FDA Breakthrough Therapy designation awards, EMA PRIME status grants, and cyclotron facility licensing decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Reactive Arthritis Treatment Market
Specialty Medicine
Asia-Pacific Kidney Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Global Brain Tumor Therapeutics Market
Specialty Medicine
Diamond-Blackfan Anemia Syndrome Therapeutics Market
Specialty Medicine
Anaplastic Astrocytoma Market
Specialty Medicine
Checkpoint Inhibitor Refractory Cancer Market
Specialty Medicine
Retroperitoneal Fibrosis Treatment Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Eosinophilic Esophagitis Market
Specialty Medicine
Medical Foods for Orphan Diseases Market
Specialty Medicine
Chronic Myeloid Leukemia Treatment Market
Specialty Medicine
Osteopontin Market
Specialty Medicine
Vasomotor Symptoms Market
Specialty Medicine
Asbestosis Treatment Market
Specialty Medicine
Geographic Atrophy Market
Specialty Medicine
Botulism Treatment Market