
 Golf Club Market | 2026-2036
Golf Club Market Size, Share, and Industry Trends Forecast 2026-2036
Golf Club Market Intelligence
The R&A and USGA's increasing focus on equipment lifecycle sustainability is restructuring material sourcing and manufacturing processes for golf clubs. Topgolf Callaway Brands Corp. leverages its extensive R&D to develop clubs with recyclable components. TaylorMade Golf Co. Inc. differentiates through its use of advanced, lightweight alloys and carbon composites. Acushnet Holdings Corp. sustains its market position through strong brand loyalty and control over professional tour endorsements.
A golf club is a piece of equipment used to strike a golf ball in the game of golf. It consists of a shaft with a grip and a clubhead, which is designed with specific loft and lie angles and often constructed from materials like titanium for drivers or forged steel for irons. Drivers, often made from titanium and carbon composites, represent a key segment for technological innovation and premium pricing. The Irons segment, primarily using steel, constitutes the largest volume category for most manufacturers.
The equipment rules set by the USGA and The R&A strictly govern club design, including head volume, shaft length, and groove specifications. In Europe, material compliance under regulations like REACH influences the selection of alloys and polymers used in club manufacturing. Manufacturers must continuously balance performance innovation against these stringent regulatory constraints to maintain a competitive edge.
Market Dynamics
The golf club market's evolution is defined by the tension between aggressive performance engineering and stringent regulatory oversight. This dynamic forces manufacturers to innovate within the tight constraints set by governing bodies like the USGA and The R&A.
Growth Catalysts
- Advanced Materials:The adoption of lightweight carbon composites and specialized titanium alloys in clubhead and shaft design enables manufacturers to create more forgiving and powerful clubs, appealing to the large and expanding amateur golfer segment.
- Leisure and Tourism Growth:Rising participation in golf as a leisure sport and the development of high-end golf resorts, particularly in markets like the United Arab Emirates and South Korea, stimulate demand for new equipment sets.
- Regulatory Focus on Sustainability:Initiatives by The R&A and other bodies promoting equipment lifecycle sustainability are creating a market for clubs designed with recyclable components and manufactured through greener processes, attracting environmentally conscious consumers.
Market Restraints
- Strict Equipment Rules:Governing bodies like the USGA and The R&A impose strict limits on club design, including head volume, groove geometry, and shaft length, which constrains the scope of performance-enhancing innovations.
- Raw Material Price Volatility:The market is exposed to price fluctuations for key materials such as aerospace-grade titanium and carbon fiber, which can compress manufacturer margins or increase end-user costs for premium clubs.
- Rise of Golf Entertainment:The popularity of golf entertainment venues offers a casual alternative to traditional golf, potentially reducing the necessity for personal club ownership among infrequent players and diverting recreational spending.
Strategic Opportunities
- Direct-to-Consumer (DTC) Channels:Building out DTC platforms with integrated online fitting tools allows brands to capture higher margins, control the customer experience, and gather valuable data on player preferences and performance needs.
- Mass Customization:Leveraging advanced manufacturing like 3D printing for club components allows for on-demand production of personalized clubs tailored to an individual golfer's swing biometrics, creating a new premium service tier.
- Emerging Market Penetration:Targeting growth in Southeast Asian nations, where a rising middle class is showing increased interest in golf, presents significant white space for brand development and market share capture outside traditional strongholds.
Industry Challenges
- Global Compliance Complexity:Manufacturers face the operational challenge of ensuring that the alloys, polymers, and coatings used in clubs comply with disparate chemical regulations, such as REACH in Europe, across a global supply chain.
- Intellectual Property Protection:Defending proprietary designs for clubheads, shaft flex profiles, and weighting systems from counterfeiting and patent infringement remains a persistent and costly challenge, particularly in certain Asian markets.
- Sustainable Sourcing:Reconfiguring supply chains to incorporate certified recycled metals and composites presents logistical and quality control hurdles, complicating efforts to meet corporate sustainability and circular economy goals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Golf Club Market |
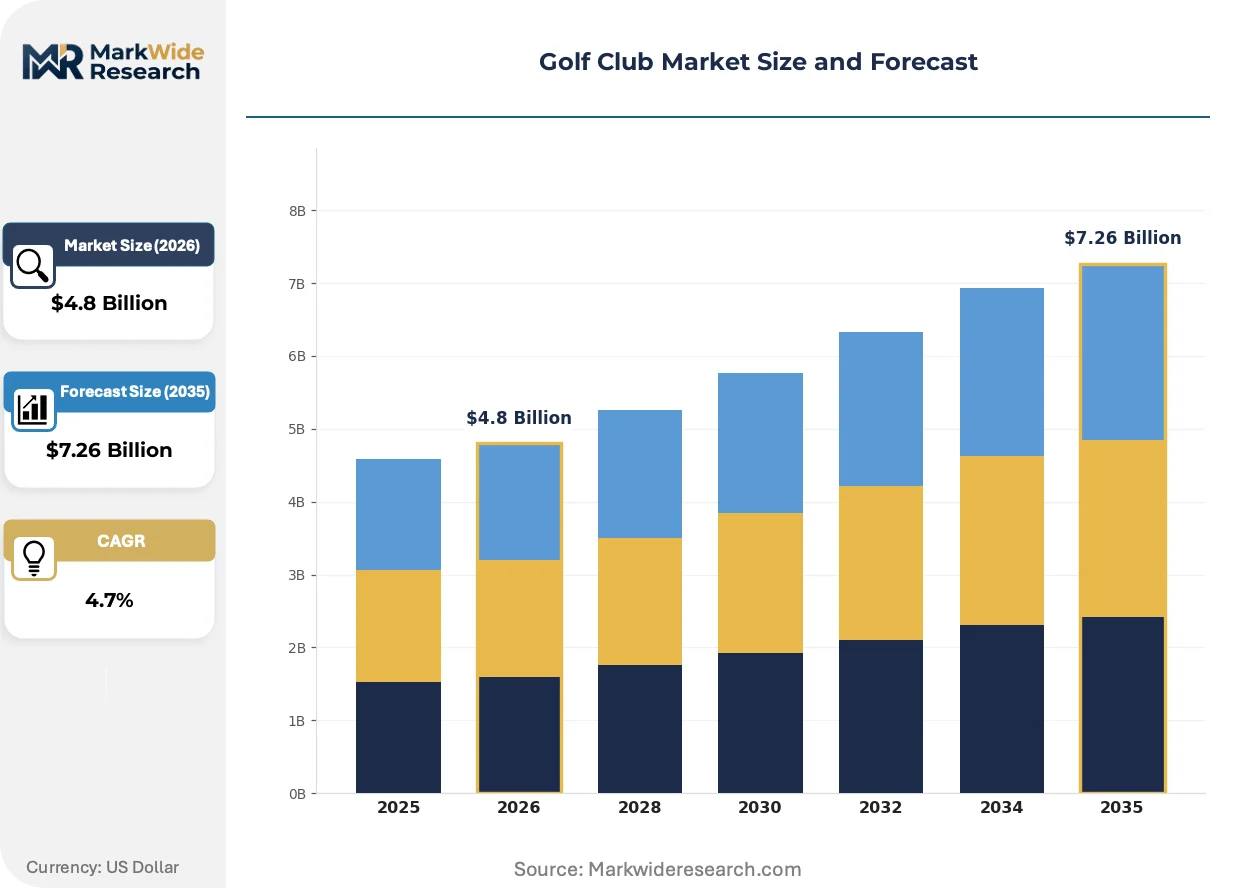
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.26 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
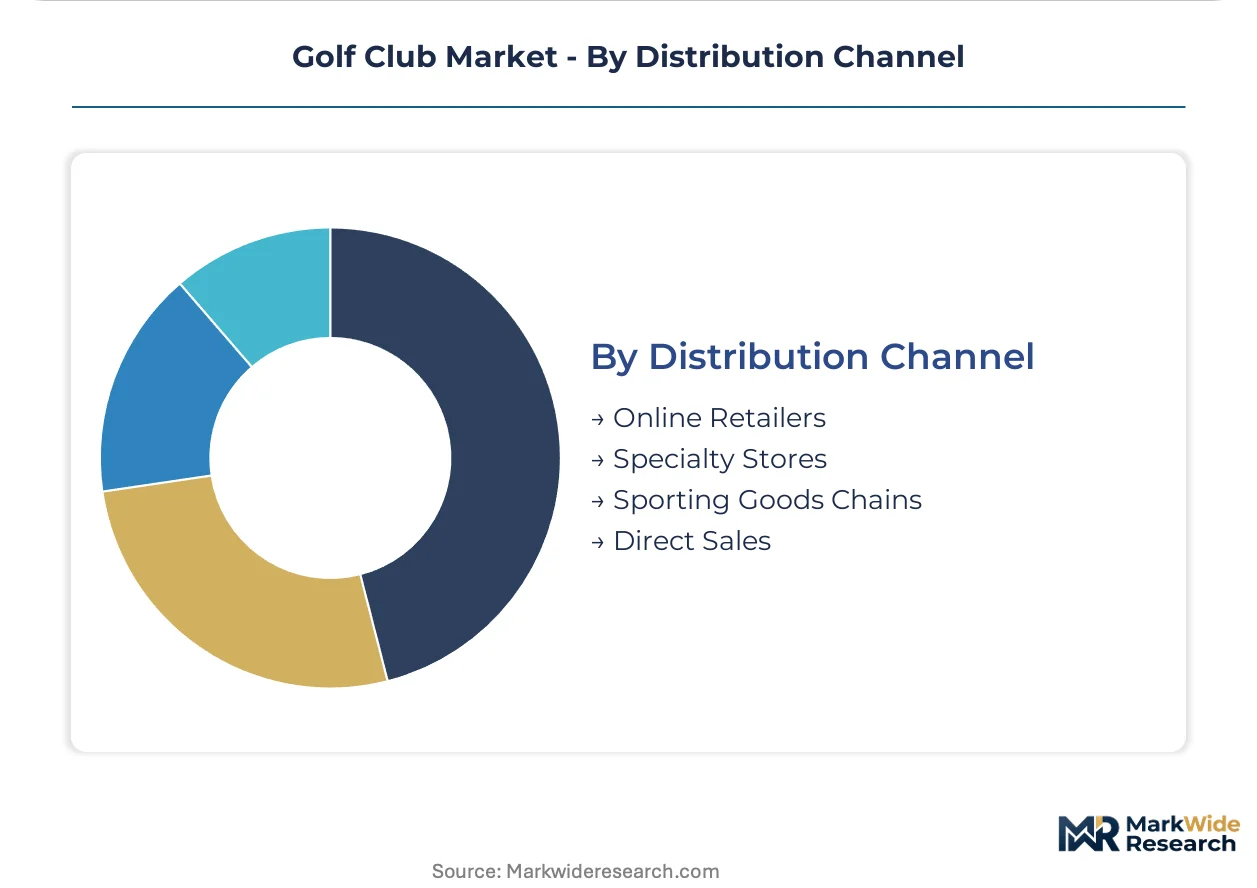
| Segmentation | Product Type: Drivers, Irons, Putters, Woods End User: Amateur Golfers, Professional Players, Coaches, Collectors Material: Graphite, Steel, Titanium, Aluminum Distribution Channel: Online Retailers, Specialty Stores, Sporting Goods Chains, Direct Sales |
| Companies Covered | Acushnet Holdings Corp., Topgolf Callaway Brands Corp., TaylorMade Golf Co. Inc., PING Inc., Mizuno Corp., Amer Sports Corp., Cobra Golf, Bridgestone Golf Inc., Honma Golf Co. Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Golf Club Market Strategic Shifts & Innovations
The competitive landscape is being reshaped by the fusion of data analytics in club design, new material science applications, and a growing emphasis on lifecycle sustainability. These forces are pushing product development beyond simple aesthetics toward quantifiable performance and environmental responsibility.
Advanced computational fluid dynamics (CFD) and AI-driven modeling are core to modern club development, allowing for precise optimization of aerodynamics and mass properties. Professional and dedicated amateur golfers are the primary adopters seeking measurable performance advantages from these technologies. This data-centric design process is converging with material science, enabling the creation of clubs with unique forgiveness and power profiles that remain compliant with governing body rules.
Sustainability mandates are influencing manufacturing processes and material selection across the industry. The European Union's Corporate Sustainability Reporting Directive (CSRD) is increasing pressure on companies to provide transparent lifecycle assessments for their products. This directly impacts the production of high-volume segments like irons, pushing for innovation in chrome plating alternatives and the use of recycled steel to reduce environmental footprints.
Personalization is increasingly displacing the traditional off-the-shelf purchasing model for golf clubs. This trend disrupts established retail channels as consumers gravitate towards brand-agnostic fitting studios and direct-to-consumer websites that offer component-level customization. This shift is most visible in mature golf markets like the United States and Japan, where experienced players seek to optimize their equipment through precisely tailored specifications.
Golf Club Market Segmentation
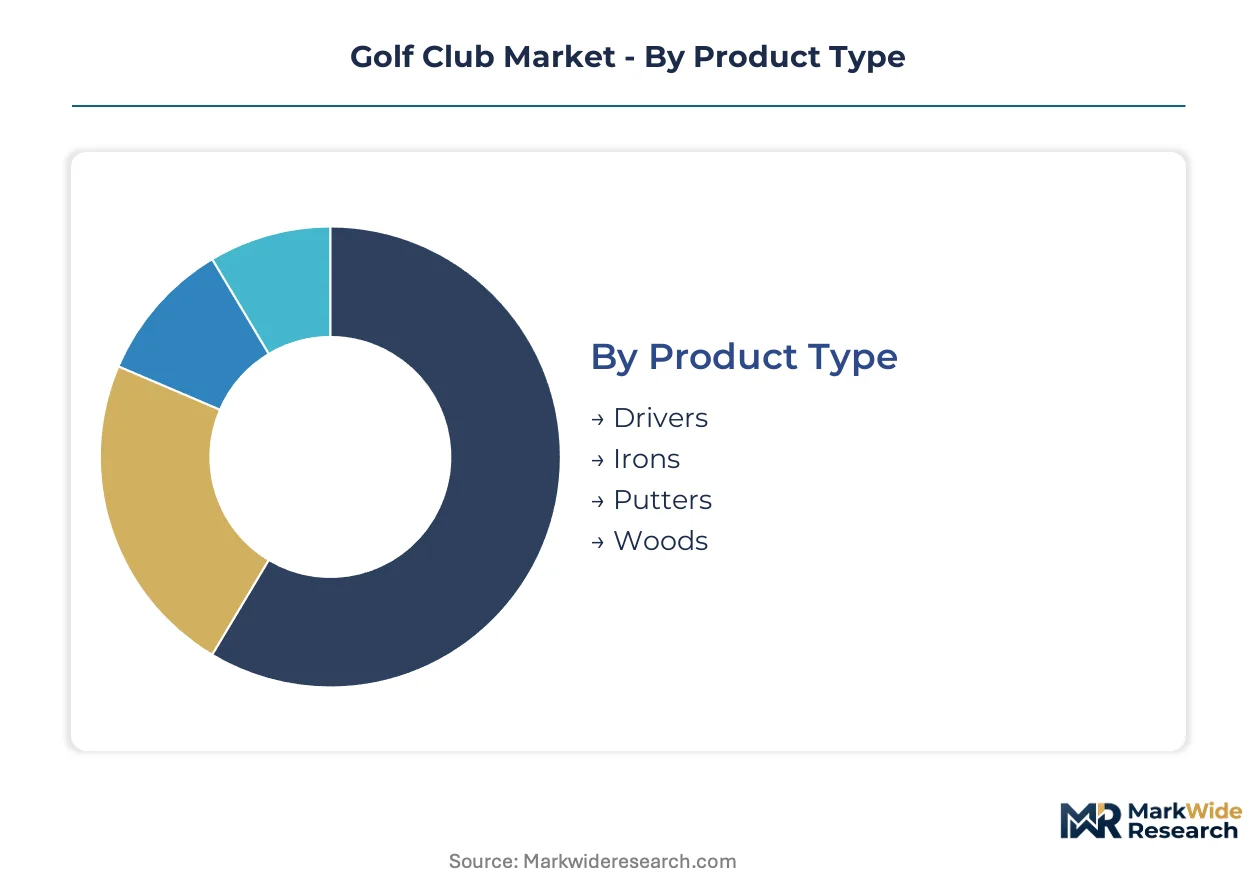
Understanding the golf club market's segmentation reveals the diverse needs of golfers and the strategic priorities of manufacturers. This detailed categorization highlights specific product innovations, material preferences, and evolving distribution strategies. These segments reveal where investment and product development are most impactful.
Product Type:
Golfer performance needs primarily dictate product type selection within the golf club market, influencing club design and material integration.
- Drivers:These clubs feature large heads, often constructed from titanium and carbon composites, designed for maximum distance off the tee. Technological innovation, such as aerodynamic shaping and adjustable weighting, drives demand among performance-focused golfers in markets like the United States.
- Irons:Comprising a set of clubs with varying lofts, irons are typically forged or cast from steel, offering control and accuracy for approach shots. This segment represents the largest volume category for manufacturers, catering to the broad base of amateur golfers globally.
- Putters:Used for striking the ball on the green, putters come in various head shapes and are often made from steel or softer inserts for feel. Their design focuses on alignment and consistency for precise short-game performance.
- Woods:Characterized by their larger clubheads and longer shafts compared to irons, woods are designed for long shots from the fairway or tee. Modern woods incorporate composite materials to optimize weight distribution and ball speed.
Irons lead on volume scale; Drivers lead on innovation momentum.
End User:
Customer type directly influences purchasing patterns and product specifications within the golf club industry.
- Amateur Golfers:This extensive segment encompasses casual players and dedicated enthusiasts who seek clubs offering forgiveness, distance, and affordability. Their participation in leisure sports drives significant demand for complete club sets and accessible technology.
- Professional Players:Elite athletes on global tours demand highly customized, precision-engineered clubs that offer specific performance characteristics for competitive play. Their equipment choices often influence broader market trends and brand perception.
- Coaches:Golf instructors frequently purchase clubs for teaching purposes, including training aids and demo models to fit students. Equipment needs focus on durability and versatility for various skill levels.
- Collectors:This niche segment acquires vintage or limited-edition clubs, often for their historical significance or unique craftsmanship. Collectors prioritize rarity and aesthetic value over on-course performance.
Amateur golfers constitute the largest segment by participation, while professional players drive premium product development.
Material:
Material selection is fundamentally driven by the specific application requirements of each club component, impacting performance and cost.
- Graphite:Utilized primarily for club shafts, graphite offers a lightweight and flexible alternative to steel, increasing swing speed and reducing vibration. Its performance benefits appeal to golfers seeking greater distance and comfort, particularly in drivers and woods.
- Titanium:Predominantly used in driver clubheads, titanium provides an excellent strength-to-weight ratio, allowing for larger head volumes and enhanced forgiveness. This premium material contributes to higher clubhead speeds and improved ball flight.
- Steel:A traditional and durable material, steel is widely employed in iron and putter heads, as well as shafts for its consistent feel and control. Its cost-effectiveness and workability make it a staple across various club types.
- Aluminum:Less common in high-performance clubs, aluminum can be found in some entry-level or specialized club components due to its lighter weight compared to steel. It offers an economical option for certain designs.
Steel dominates the market by sheer volume, whereas titanium commands premium pricing in specific club types.
Distribution Channel:
Supply concentration within distribution channels shapes market accessibility and brand reach for golf club manufacturers.
- Online Retailers:E-commerce platforms provide extensive product catalogs and direct-to-consumer options, often integrating online fitting tools for personalized purchases. This channel facilitates market penetration into new geographies like Southeast Asian nations.
- Specialty Stores:These dedicated golf retail outlets offer expert fitting services, a wide selection of premium brands, and personalized customer advice. They remain crucial for experienced players seeking tailored equipment and professional guidance.
- Sporting Goods Chains:Large multi-sport retailers provide a convenient, accessible option for casual golfers to purchase entry-level and mid-range club sets. These chains focus on volume sales and broader market appeal.
- Direct Sales:Manufacturers engage in direct sales through their own websites or exclusive events, fostering brand loyalty and offering unique customization options. This channel allows higher margins and direct customer feedback.
Specialty stores offer crucial fitting services, while online retailers expand direct-to-consumer engagement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The specialized engineering workforce in the United States anchors demand for golf club innovation, driving advanced product development. This concentration influences market dynamics across key global regions. Each region presents unique growth drivers and regulatory environments shaping the golf club industry.
United States
The expanding amateur golfer segment and a strong preference for performance-focused equipment drive significant demand in the United States. The USGA's stringent equipment rules guide club design, influencing material choices and technological integration. California serves as a hub for golf technology startups and R&D centers, fostering continuous product advancement.
South Korea
Rising interest in golf as a leisure activity and the development of high-end golf resorts stimulate equipment sales in South Korea. The country's national consumer product safety standards ensure compliance for imported and domestically manufactured clubs. Seoul's urban centers feature numerous golf entertainment venues and premium retail outlets, catering to a growing enthusiast base.
United Arab Emirates
High-end golf resort development and a growing tourism sector contribute to golf club demand in the United Arab Emirates. Investment policies supporting sports infrastructure development encourage market expansion. Dubai has emerged as a significant luxury retail and golf course development hub, attracting international players.
Japan
Experienced players seeking precise customization and a mature golf market characterize demand in Japan. The Ministry of Economy, Trade and Industry (METI) oversees industrial standards and consumer product safety for golf equipment. Tokyo's specialized fitting studios and premium golf retail outlets cater to discerning golfers optimizing their equipment.
Germany
Environmentally conscious consumers and sustainability mandates influence product development and material selection in Germany. European regulations like REACH and the Corporate Sustainability Reporting Directive (CSRD) impact manufacturing processes. Bavaria hosts advanced manufacturing facilities and materials science research, contributing to sustainable club design.
Golf Club Market Key Industry Players
Capital-heavy producers compete with asset-light designers, creating a tiered market structure within the golf club industry. This landscape features integrated manufacturers alongside specialized component suppliers and direct-to-consumer brands. Integrated manufacturers leverage extensive R&D capabilities, while DTC brands focus on personalized customer experiences. Key competitive moves include strategic investments in advanced materials and the development of direct-to-consumer channels.
Within the integrated manufacturer tier, Topgolf Callaway Brands Corp. exemplifies a company leveraging extensive research and development for product innovation. Acushnet Holdings Corp. occupies a strong position through brand loyalty and control over professional tour endorsements. TaylorMade Golf Co. Inc. sits within the segment that differentiates through advanced, lightweight alloys and carbon composites, appealing to performance-driven golfers.
| Leading Market Players |
|---|
| Acushnet Holdings Corp. |
| Topgolf Callaway Brands Corp. |
| TaylorMade Golf Co. Inc. |
| PING Inc. |
| Mizuno Corp. |
| Amer Sports Corp. |
| Cobra Golf |
| Bridgestone Golf Inc. |
| Honma Golf Co. Ltd. |
| Others |
Cost & Logistics Intelligence
Publicly traded integrated manufacturers like Topgolf Callaway Brands Corp. dictate supply concentrations and pricing strategies. Their extensive R&D investments influence premium club segment costs and downstream distribution.
Pricing Analysis
Bundled club sets versus unbundled component sales define the pricing structure in golf equipment. Pricing stratifies across premium, standard, and economy tiers, driven by customization levels and brand premium from manufacturers like Acushnet Holdings Corp. Price erosion runs through the entry-level segment due to competition from sporting goods chains. Amateur golfers seeking complete sets are highly price-sensitive, while professional players prioritize performance over cost.
Supply Chain Analysis
Material compliance under regulations like Europe's REACH influences the selection of alloys and polymers, gating supplier entry. The supply chain draws from specialized R&D hubs in the United States, alongside volume manufacturing centers in China and advanced component production in Japan. Key dependencies include aerospace-grade titanium, carbon fiber, and various steel alloys. Raw material price volatility poses a structural risk across the industry, while distribution runs through online retailers, specialty stores, and sporting goods chains.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The golf club market presents a geographic-arbitrage opportunity, as manufacturing costs in Southeast Asian nations offer a significant differential compared to established production in the United States. This cost advantage allows for competitive pricing in high-volume segments.
For Market Incumbents:Extend intellectual property protection for proprietary designs against counterfeiting in Asian markets. Deepen R&D investments in lightweight composite materials to maintain performance leadership against new entrants. Strengthen brand loyalty through exclusive professional tour endorsements, mitigating the threat from golf entertainment venues. Enhance direct-to-consumer channels to control customer experience and data.
For New Entrants and Emerging Players:Enter via mass customization services, leveraging 3D printing for club components tailored to individual swing biometrics. Target the underpenetrated Southeast Asian nations, where a rising middle class shows interest in golf. Focus on the amateur golfer segment seeking personalized equipment solutions. Utilize direct-to-consumer websites with integrated online fitting tools as a primary go-to-market angle.
For Investors and Strategic Acquirers:Integrated sporting goods conglomerates are the most active acquirers in this space, seeking to expand their golf equipment portfolios. Long-term viability rests on sustained demand from leisure sports and continuous innovation in lightweight materials. Target specialized component manufacturers or successful direct-to-consumer brands with strong customer data. The signal to watch is the adoption rates of sustainable manufacturing processes and recyclable components across the industry.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Material R&D | Enables creation of more forgiving and powerful clubs for amateur golfers. |
| Expand Direct-to-Consumer Channels | Captures higher margins and gathers valuable data on player preferences and performance needs. |
| Develop Sustainable Manufacturing Processes | Addresses European Union's CSRD mandates and attracts environmentally conscious consumers. |
| Target Emerging Market Penetration | Unlocks significant white space for brand development in Southeast Asian nations. |
| Leverage Mass Customization Technologies | Creates a new premium service tier tailored to individual golfer's swing biometrics. |
Research Approach
Bottom-up amateur golfer segment modeling reconciled against top-down golf club manufacturer tracking forms the analytical core of this study. Primary interviews with R&D directors, club fitters, and retail managers provided critical insights, validated through secondary research. This included analysis of USGA equipment rules, R&A reports, industry association data, and manufacturer financial filings. The approach ensured comprehensive data triangulation.
Historical trendline analysis, coupled with forward-looking projections, defined the forecast framework across the analysis window. Segmentation dimensions modeled included product type, end user, material, distribution channel, and regional regulatory compliance. Compound Annual Growth Rates were derived from a weighted average of historical performance and anticipated market shifts. Industry-specific inputs like golf participation rates and advanced material costs informed the projections.
Inputs from major manufacturer reports and regulatory body publications were available through the study window; gaps in real-time consumer spending data introduce uncertainty bands. Forecasts reflect assumptions regarding equipment rule stability and material science advancements. A model refresh is warranted upon material change in global trade policies impacting raw material supply.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Playground Sets and Equipment Market
Sports Equipment
Global Bicycle Market
Sports Equipment
Global Weighted Hula Hoop Market
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Field Hockey Equipment Market
Sports Equipment
France Artificial Turf Market
Sports Equipment
Surfboard Market
Sports Equipment
GCC Running Gear Market
Sports Equipment
Football Equipment Market
Sports Equipment
BMX Bikes Market
Sports Equipment
US Sports Flooring Market
Sports Equipment
Riding Gear Market
Sports Equipment
Global Kinesio Tape Market
Sports Equipment
Golf Gloves Market
Sports Equipment
Air Cushion Basketball Shoes Market
Sports Equipment
Surfing Equipment Market