
 Football Equipment Market | 2026-2036
Football Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Football Equipment Market Analysis
Specialized polymer engineering talent is redrawing competitive boundaries in football equipment manufacturing. Nike Inc. leverages vertically integrated material science labs to control cushioning system development from compound formulation to finished cleat. Adidas AG anchors its position through captive knitting facilities that produce Primeknit uppers for football boots at scale. Riddell Sports Group specializes in helmet shell geometry and liner density configurations that exceed baseline impact attenuation thresholds.
Football equipment comprises purpose-built apparel, protective systems, and training implements engineered to withstand repeated high-velocity collisions, rotational forces, and all-weather pitch exposure. Helmets integrate multi-layered polycarbonate shells bonded to vinyl nitrile foam or thermoplastic urethane cushioning matrices designed to manage linear and angular acceleration during player contact. Protective gear and footwear together command the dominant share of product-type revenue pools, with training equipment representing the fastest-expanding application segment as professional clubs and academies invest in sensor-integrated practice tools. Recreational play applications remain volume-heavy but margin-thin due to price-sensitive amateur purchasers and shorter replacement cycles.
NOCSAE standards govern football helmet performance testing in the United States, while the EU Green Deal and REACH protocols constrain chemical inputs in synthetic leather and adhesive formulations sold across Europe. These frameworks compel manufacturers to reformulate material bases and maintain dual certification tracks for cross-border distribution. Stakeholders must monitor emerging state-level concussion litigation trends and corresponding liability exposure that could reshape product design priorities and insurance costs independent of baseline regulatory floors.
Market Dynamics
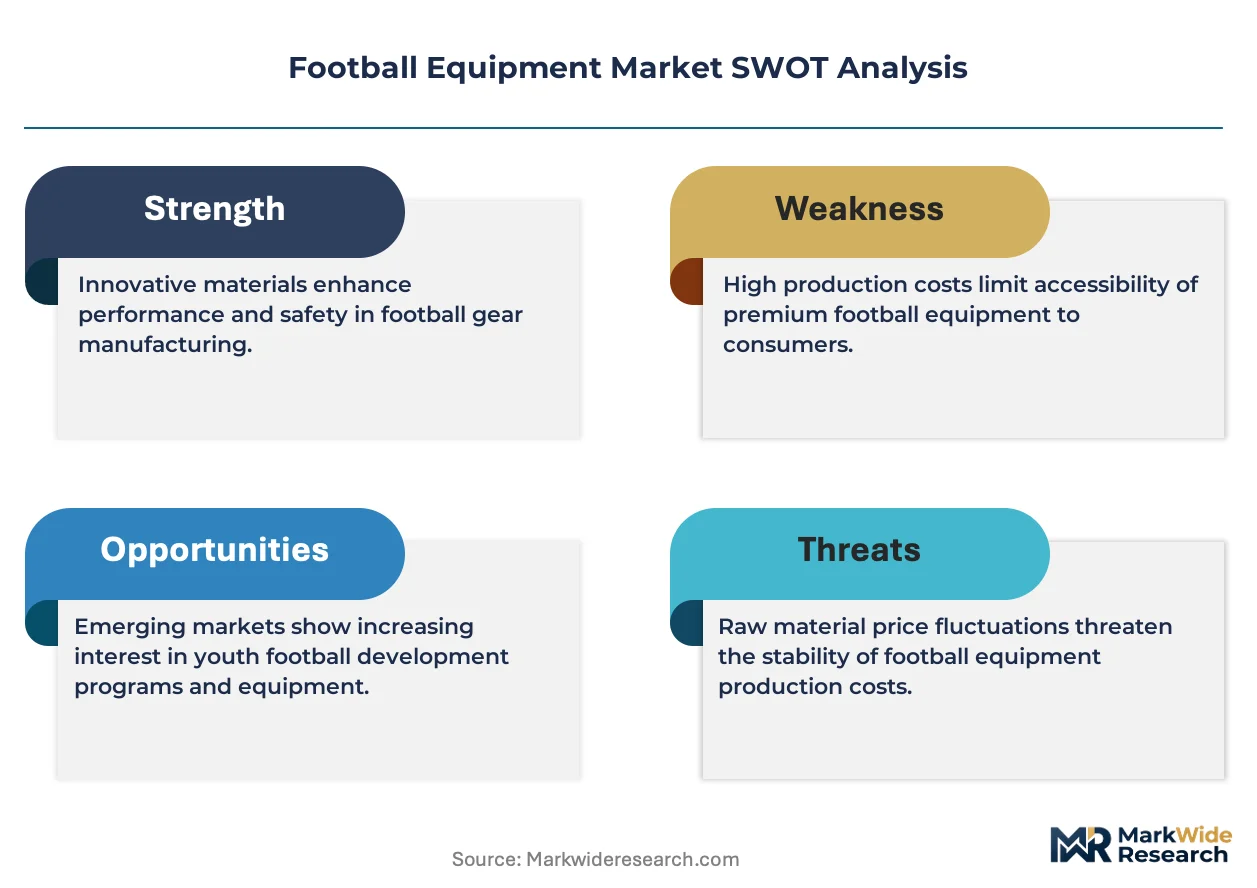
NOCSAE certification mandates and EU REACH chemical protocols are forcing manufacturers to reformulate material bases across entire product lines, compressing development timelines while elevating compliance costs as non-negotiable cost-of-entry requirements.
Growth Catalysts
- Youth League Expansion:Municipal investment in Brazil and club-level infrastructure across the United States is accelerating equipment procurement cycles for grassroots programs.
- Sensor-Integrated Training Tools:Professional academies in Germany and Spain are deploying motion-capture practice systems that require specialized ball-tracking hardware and wearable impact monitors.
- EU Green Deal Alignment:REACH-compliant synthetic leather formulations are opening distribution channels across France, Italy, and the Netherlands for manufacturers with certified material supply chains.
Market Restraints
- Petrochemical Volatility:Thermoplastic urethane and polycarbonate resin prices fluctuate with crude oil indices, compressing margin predictability for helmet shell producers.
- Asian Manufacturing Concentration:Overreliance on Guangdong and Zhejiang province facilities for molded foam components creates single-source vulnerability during shipping disruptions.
- Biodegradability Trade-offs:Plant-based cushioning alternatives currently fail NOCSAE impact attenuation thresholds, limiting material substitution options for US-bound product lines.
Strategic Opportunities
- Indian Subcontinent Penetration:BIS certification pathways and state-level sports infrastructure programs in Maharashtra and Karnataka present first-mover positioning for compliant suppliers.
- Direct-to-Academy Distribution:Bypassing traditional retail through club partnership portals reduces channel margin capture and enables customized bulk configurations.
- Carbon-Neutral Product Lines:EU CSRD disclosure requirements are creating premium positioning for manufacturers with verified lifecycle emissions data and recycled polymer content.
Industry Challenges
- Polymer Engineering Talent Scarcity:Formulation chemists with vinyl nitrile foam and multi-layer bonding expertise command premium compensation, constraining R&D scaling.
- Dual Certification Complexity:Maintaining parallel NOCSAE and CE marking test tracks extends product launch timelines by 8-14 months for cross-Atlantic distribution.
- Legacy Equipment Integration:Sensor-embedded smart helmets face interoperability barriers with existing team data management platforms, requiring costly middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Football Equipment Market |
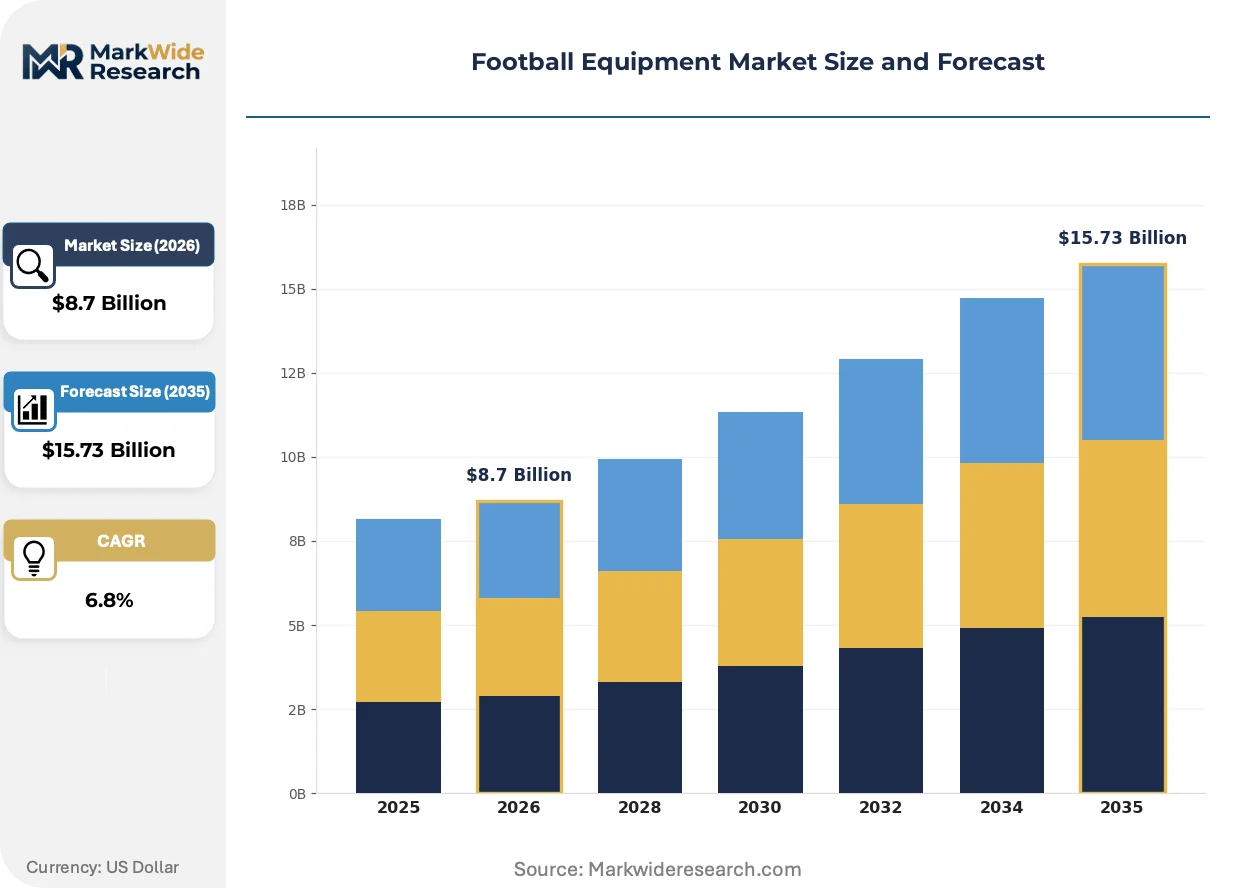
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Footwear, Protective Gear, Balls, Training Equipment Application: Professional Training, Recreational Play, School Competitions, Coaching End User: Athletes, Coaches, Schools, Organizations Distribution Channel: Online Retail, Specialty Stores, Sporting Goods Chains, Direct Sales |
| Companies Covered | Nike Inc., Adidas AG, Puma SE, Under Armour Inc., New Balance Inc., ASICS Corporation, Mizuno Corporation, Riddell Sports Group, Wilson Sporting Goods Co., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Football Equipment Market Emerging Trajectories
Digital fabrication methods and biomaterial science are converging to redefine performance benchmarks across protective gear categories, compressing traditional manufacturing lead times while introducing novel sustainability verification requirements.
3D-printed lattice cushioning structures are supplanting molded foam liners in high-end helmet configurations. NFL and NCAA equipment managers are piloting these systems for customized fit mapping. This shift is compressing minimum order quantities and enabling mass-customization economics previously restricted to bespoke medical orthotics.
REACH Annex XVII restrictions on phthalate plasticizers are compelling European manufacturers to migrate toward bio-based polyurethane alternatives. The reformulation burden falls heaviest on synthetic leather suppliers serving the football boot segment. German and Italian producers are accelerating water-based adhesive substitution programs to maintain CE marking compliance.
Club procurement officers now demand lifecycle cost documentation extending beyond purchase price to replacement frequency and injury-risk reduction metrics. This behavior is displacing pure unit-cost bidding in municipal tender processes. The shift is most pronounced in Dutch and Danish municipal league systems where public accountability frameworks mandate transparent total-cost-of-ownership analysis.
Football Equipment Market Segmentation
Equipment procurement patterns diverge sharply across use cases, with certification requirements and replacement cycles creating distinct margin profiles. Segment-specific demand drivers determine which manufacturers capture volume versus premium positioning.
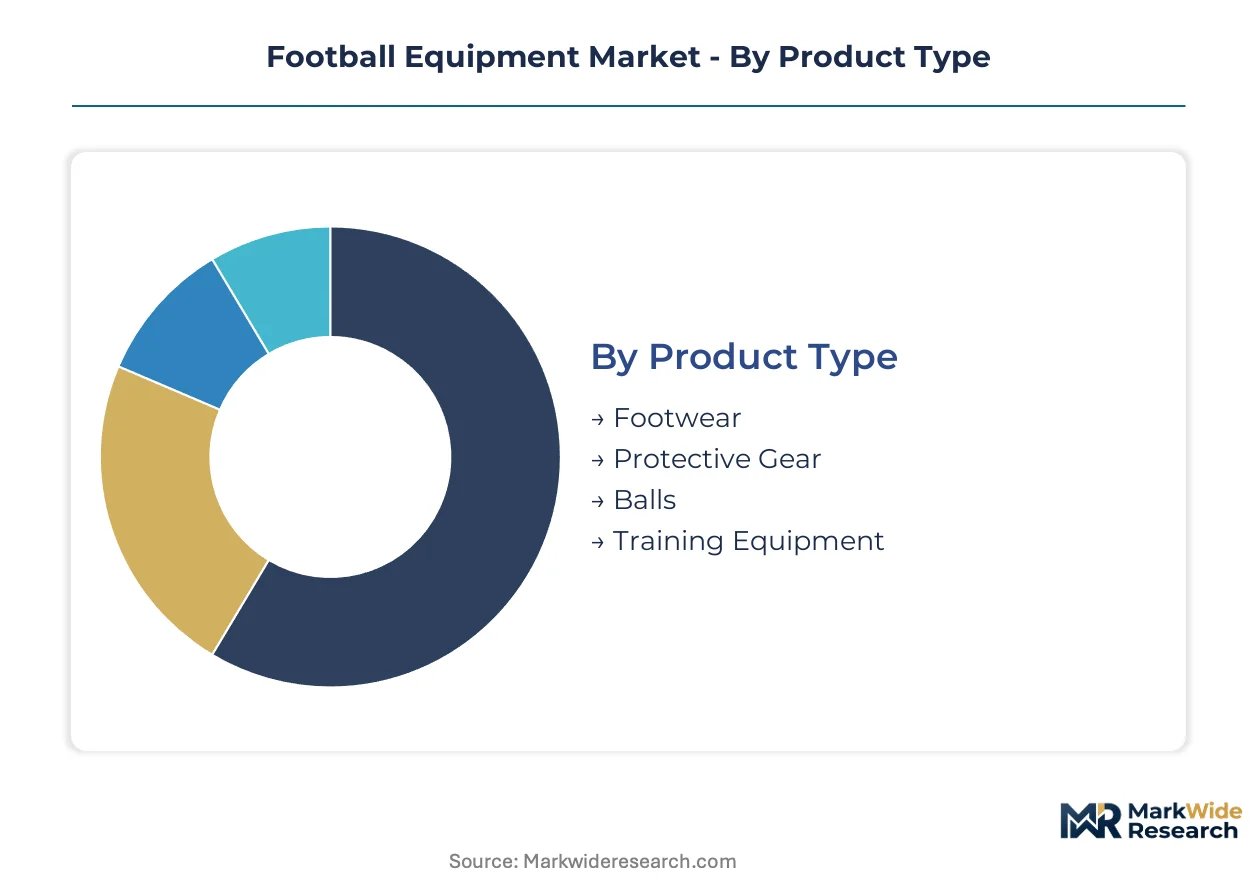
Product Type:
Protective gear faces the most acute substitution pressure from 3D-printed lattice alternatives and smart-embedded systems that displace traditional foam configurations.
- Footwear:Engineered cleat systems integrate thermoplastic urethane studs and Primeknit uppers for multi-surface traction. Demand concentrates in German and Spanish professional academies where surface-specific stud configurations reduce ankle injury incidence.
- Protective Gear:Multi-layered polycarbonate shells bonded to vinyl nitrile foam manage linear and angular acceleration during contact. NOCSAE certification mandates in the United States compress development timelines while elevating compliance costs as baseline requirements.
- Balls:Thermally bonded polyurethane panels with latex bladders maintain shape retention across temperature ranges. FIFA Quality Pro certification governs professional match specifications.
- Training Equipment:Sensor-integrated ball-tracking hardware and wearable impact monitors enable motion-capture practice systems. Professional clubs in Germany and Spain are deploying these tools at scale.
Protective gear anchors the volume base while training equipment gains share at the steepest rate.
Application:
Cost tier stratification separates specification-heavy professional deployments from price-sensitive recreational procurement.
- Professional Training:Custom-fit helmet liners and position-specific shoulder pad configurations require individualized measurement protocols. NFL and NCAA equipment managers pilot 3D-printed cushioning for customized fit mapping.
- Recreational Play:Standardized sizing and shorter replacement cycles dominate amateur purchaser behavior. Municipal leagues in Brazil drive volume through infrastructure investment at club levels.
- School Competitions:NOCSAE-compliant inventory requirements govern US high school athletics procurement. District-level bulk purchasing consolidates vendor relationships.
- Coaching:Tactical board systems, whistle-integrated communication devices, and video analysis software support sideline operations. Dutch and Danish municipal systems mandate transparent total-cost-of-ownership documentation.
Recreational play commands the widest volume base while professional training delivers the steepest margin expansion.
End User:
Customer type determines whether procurement flows through institutional tender processes or individual retail channels.
- Athletes:Individual fit preference and position-specific protection requirements drive premium equipment selection. Custom orthotic integration is expanding in collegiate programs.
- Coaches:Training tool procurement focuses on squad-level analytics and practice efficiency metrics. Spanish La Liga academies prioritize sensor-integrated ball-tracking systems.
- Schools:Budget-constrained inventory cycles emphasize durability and multi-sport compatibility. US public school districts face liability exposure from concussion litigation trends.
- Organizations:Club-level infrastructure investment in Brazil accelerates equipment procurement for grassroots development programs. Municipal partnerships reduce per-unit acquisition costs.
Schools anchor institutional volume while organizations are expanding most quickly through municipal partnership structures.
Distribution Channel:
Supply concentration in Asian manufacturing clusters shapes channel economics and inventory risk profiles.
- Online Retail:Direct-to-consumer platforms enable mass-customization economics for individualized fit systems. Return logistics complexity limits penetration for protective gear categories.
- Specialty Stores:Staff expertise supports proper fitting protocols for helmet and shoulder pad configurations. German and Italian markets emphasize CE marking verification at point of sale.
- Sporting Goods Chains:Volume purchasing agreements with Guangdong and Zhejiang province facilities create margin leverage. Inventory concentration risk escalates during shipping disruptions.
- Direct Sales:Club partnership portals bypass traditional retail margin capture and enable customized bulk configurations. Dutch municipal leagues mandate lifecycle cost documentation in tender processes.
Sporting goods chains dominate volume throughput while direct sales channels are climbing the fastest among professional and institutional buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
NOCSAE certification mandates in the United States establish the regulatory baseline that other jurisdictions reference or diverge from. Municipal procurement cycles and club infrastructure investments are reshaping equipment demand patterns across distinct national markets.
United States
High school athletics programs drive institutional volume through district-level bulk purchasing agreements. NOCSAE standards govern helmet performance testing and compliance documentation. Equipment manufacturing clusters in Ohio and Texas specialize in polycarbonate shell fabrication and vinyl nitrile foam liner assembly.
Germany
Professional academies in Bavaria and North Rhine-Westphalia deploy sensor-integrated training systems at scale. REACH Annex XVII restrictions on phthalate plasticizers compel synthetic leather reformulation for football boot production. Stuttgart-based material science labs develop bio-based polyurethane alternatives for CE marking compliance.
Brazil
Municipal infrastructure investment in São Paulo and Rio de Janeiro accelerates grassroots program equipment procurement. ANVISA oversees product safety registration for imported protective gear. Domestic manufacturing capacity concentrates in Minas Gerais for molded foam components serving club-level demand.
India
State-level sports infrastructure programs in Maharashtra and Karnataka create first-mover positioning for compliant suppliers. BIS certification pathways govern quality standards for protective equipment distribution. Manufacturing activity clusters in Tamil Nadu for thermoplastic urethane stud systems and knitted upper production.
United Kingdom
Professional club academies in Greater London and the Midlands prioritize customized fit systems for developmental squads. HSE guidelines influence protective gear specification in amateur league contexts. Manchester-based distribution hubs coordinate direct-to-academy supply chains bypassing traditional retail channels.
Football Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure. Vertically integrated material science operations occupy premium positioning, while scale-driven manufacturers capture volume through Asian production networks. Two strategic archetypes dominate: integrated innovators controlling compound-to-finished-product pipelines, and modular assemblers leveraging distributed supplier ecosystems. Competitive moves center on captive R&D facility expansion and direct-to-institutional distribution partnerships that disintermediate traditional sporting goods retail.
Within the integrated innovator tier, Nike Inc. and Adidas AG exemplify archetypes that anchor material science development through in-house laboratory networks. Riddell Sports Group occupies a specialized position in protective systems engineering. These three entities represent distinct competitive postures: apparel-centric diversification, footwear-dominant scale, and safety-equipment-focused technical depth.
| Leading Market Players |
|---|
| Nike Inc. |
| Adidas AG |
| Puma SE |
| Under Armour Inc. |
| New Balance Inc. |
| ASICS Corporation |
| Mizuno Corporation |
| Riddell Sports Group |
| Wilson Sporting Goods Co. |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between municipal league systems and polycarbonate shell manufacturers lock in supply access while stabilizing price visibility across multi-season procurement cycles. These contracts insulate Brazilian club programs and US high school districts from petrochemical volatility that otherwise disrupts helmet production economics.
Pricing Analysis
Price spreads between US and European markets widen during REACH compliance reformulation cycles for synthetic leather components. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated smart helmets from baseline NOCSAE-compliant inventory and recreational-grade alternatives. Cost compression in the economy tier intensifies because Asian manufacturing concentration enables volume leverage. Recreational purchasers exhibit highest price sensitivity, while professional academies prioritize fit customization over unit cost.
Supply Chain Analysis
Strategic stockpiling of vinyl nitrile foam liners characterizes professional club procurement, contrasting with just-in-time inventory practices among retail sporting goods chains. Manufacturing gravity centers on Guangdong and Zhejiang provinces for molded foam components, Ohio and Texas for polycarbonate shell fabrication, and Tamil Nadu for thermoplastic urethane stud systems. Raw material flows draw from Saudi petrochemical feedstocks, German specialty chemical additives, and Malaysian natural rubber latex. Single-source vulnerability during shipping disruptions poses structural risk. Distribution runs through direct-to-academy portals for institutional buyers and specialty retail for individual athletes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Equipment lifecycle management services represent a service-attach opportunity expanding faster than hardware sales, as Dutch and Danish municipal leagues mandate total-cost-of-ownership documentation that bundles replacement scheduling with injury-risk analytics.
For Market Incumbents: Secure captive supply of vinyl nitrile foam formulation chemists through dedicated R&D facility expansion in Stuttgart or Ohio manufacturing clusters. Deepen backward integration into Primeknit upper production to defend margin position against modular assemblers leveraging distributed Asian supplier ecosystems. Certification investment in dual NOCSAE-CE marking tracks protects against regulatory fragmentation risk. For New Entrants and Emerging Players: Custom-fit 3D-printed helmet liner services represent a service-layer gap where incumbents under-serve individual athletes outside professional systems. Target Maharashtra and Karnataka state infrastructure programs as the most penetrable geography, where BIS certification pathways favor first-mover positioning. Deploy direct-to-academy distribution partnerships to bypass entrenched retail channel capture. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among sensor-integrated training tool developers with club-level subscription contracts. Long-term viability across the projection horizon favors acquisition targets with verified lifecycle emissions data and recycled polymer content positioning for EU CSRD alignment. Watch concussion litigation settlement trends as the signal indicating inflection in liability-driven product design priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Academy Distribution Launch | Bypasses traditional retail margin capture while enabling customized bulk configurations for institutional buyers. |
| Dual Certification Investment | Parallel NOCSAE and CE marking tracks accelerate cross-Atlantic market access despite extended development timelines. |
| Carbon-Neutral Product Line Development | Verified lifecycle emissions data opens premium positioning under EU CSRD disclosure requirements. |
| Sensor Platform Integration Partnership | Middleware development resolves interoperability barriers between smart helmets and existing team data systems. |
| 3D-Printed Customization Capability Buildout | Mass-customization economics for individualized fit systems compress minimum order quantities previously restricted to medical orthotics. |
Methodological Framework
Initial hypotheses were tested against primary input from equipment managers at NFL and NCAA programs, municipal league procurement officers, polycarbonate shell manufacturing plant managers, and synthetic leather R&D directors, then refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of NOCSAE certification databases, REACH Annex XVII regulatory filings, FIFA Quality Pro specifications, and customs records tracking thermoplastic urethane resin trade flows. Bottom-up segment sizing and top-down market triangulation cross-validated volume estimates.
Variance decomposition across product type, application tier, end-user category, and distribution channel shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate calibration against macroeconomic indicators and industry-specific inputs including youth league participation trajectories and municipal infrastructure investment pipelines. Modeled dimensions encompassed protective gear, footwear, training equipment, and ball categories crossed with professional, recreational, school, and coaching applications.
Underlying assumptions cover sustained petrochemical feedstock availability, stable NOCSAE certification timelines, and continued municipal infrastructure investment in Brazil and India, with deviation risk concentrated in REACH chemical restriction expansion and concussion litigation liability exposure. Revision becomes warranted when dual certification complexity extends product launch timelines beyond current baseline thresholds or when plant-based cushioning alternatives achieve NOCSAE impact attenuation compliance.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Gym Shoes Market
Sports Equipment
Global Darts Market
Sports Equipment
Smart Swim Goggles Market
Sports Equipment
Shuffleboard Equipment Market
Sports Equipment
Premium Bicycle Market
Sports Equipment
PE Sports Turf Market
Sports Equipment
Sports Mouthguard Market
Sports Equipment
Ankle Roll Guard Market
Sports Equipment
Football Market
Sports Equipment
Boxing Gear Market
Sports Equipment
Pickleball Pitching Machine Market
Sports Equipment
Golf Bags Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Running Gear Market
Sports Equipment
Mountain Bicycle Cassette Market