
 US Sports Flooring Market | 2026-2036
US Sports Flooring Market Size, Share, and Industry Trends Forecast 2026-2036
US Sports Flooring Market Outlook
Aftermarket service revenue from resurfacing and recoating is narrowing the margin gap between initial installation and lifecycle maintenance. Tarkett leverages its nationwide distribution network to capture recurring maintenance contracts. Connor Sports anchors the premium maple hardwood segment through exclusive partnerships with NCAA basketball programs. Robbins Sports Surfaces differentiates via patented subfloor systems that reduce athlete injury risk.
US sports flooring comprises engineered surface systems designed for athletic performance, shock absorption, and dimensional stability under dynamic loads, typically incorporating polyurethane coatings, recycled rubber bases, or kiln-dried maple veneer layers. These installations serve competitive athletics, recreational fitness, and physical education by managing impact forces and controlling ball rebound. Wooden flooring dominates elite basketball and volleyball venues where FIBA and NCAA standards mandate specific shock absorption and vertical deformation parameters. Vinyl and rubber surfaces are gaining share in multipurpose community centers and school gyms where budget constraints and maintenance simplicity override premium performance requirements. Modular installation systems now lead new construction as facility managers prioritize future reconfiguration flexibility.
The EPA regulates volatile organic compound emissions in polyurethane adhesives and finishes, pushing manufacturers toward water-based formulations that comply with national air quality standards. OSHA workplace safety requirements influence installer certification programs and jobsite exposure limits during adhesive application. ASTM International maintains F2569 and F2772 standards that specify force reduction, ball rebound, and surface finish criteria for indoor sports floors. Facility operators must monitor evolving state-level procurement mandates that increasingly require recycled content disclosure and extended producer responsibility provisions.
Market Dynamics
School gymnasium renovation cycles across the Midwest and Southeast are compressing replacement timelines, while California's Title 24 energy standards redirect specification toward low-VOC synthetic surfaces that meet air quality mandates without sacrificing performance ratings.
Growth Catalysts
- EPA VOC Regulations:Federal emissions standards for polyurethane adhesives and finishes push manufacturers toward water-based formulations. Facility operators in Texas and Florida school districts now prioritize compliant synthetic systems for basketball and multipurpose installations.
- Modular Installation Systems:Prefabricated subfloor assemblies reduce on-site labor hours and enable future reconfiguration. Community centers and recreational fitness facilities in the Southeast specify these systems for operational flexibility.
- NCAA Performance Standards:FIBA and NCAA shock absorption mandates for elite basketball venues sustain demand for engineered maple systems. University athletic departments drive specification toward surfaces meeting F2569 and F2772 criteria.
Market Restraints
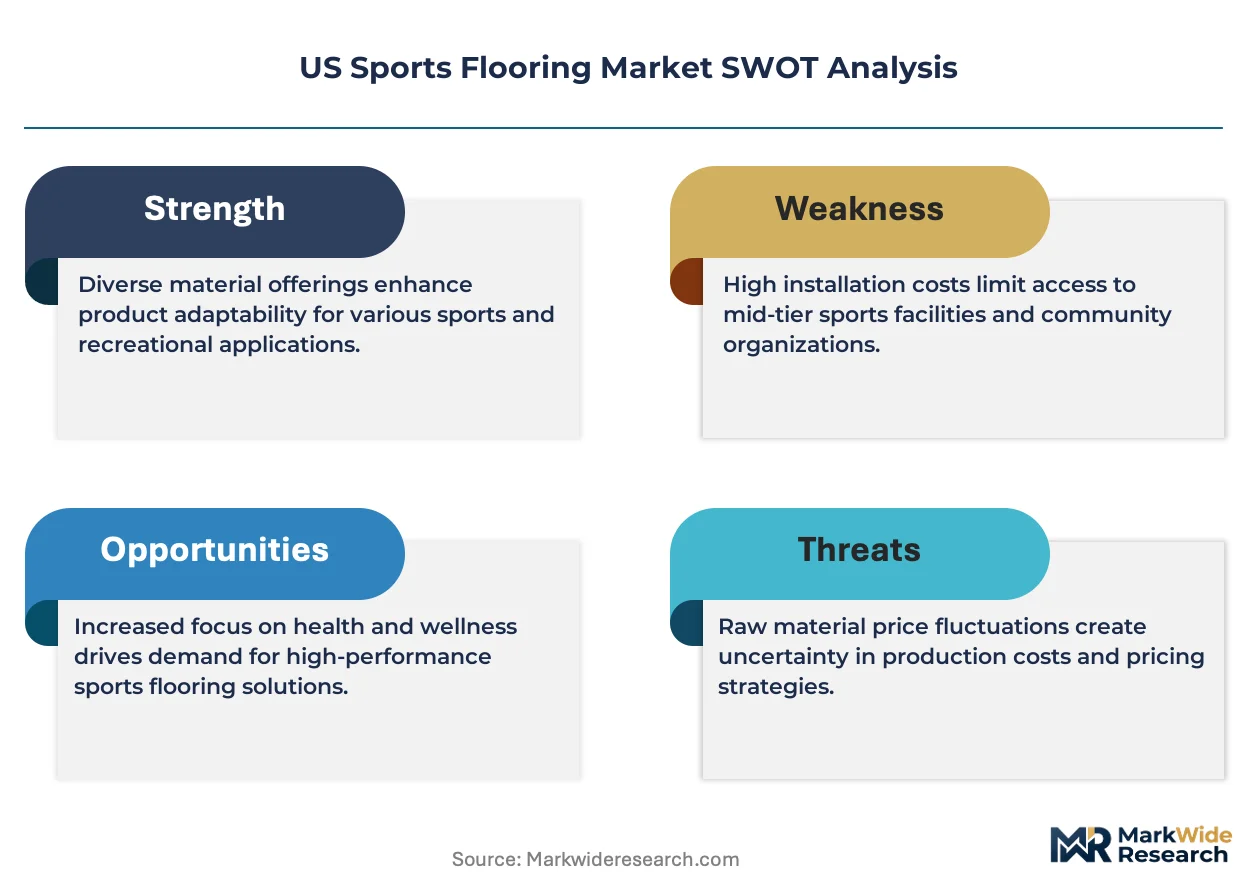
- Kiln-Dried Maple Supply Concentration:Premium hardwood veneer production clusters in specific Great Lakes regions, exposing buyers to weather-related harvest disruptions and freight cost volatility.
- OSHA Installer Certification Requirements:Workplace safety exposure limits during adhesive application extend project timelines and elevate contractor qualification costs for polyurethane-based installations.
- Rubber Flooring Substitution:Budget-constrained K-12 districts in the Southwest increasingly specify recycled rubber surfaces that sacrifice vertical deformation performance for capital expenditure reduction.
Strategic Opportunities
- Aftermarket Service Contracts:Resurfacing and recoating revenue streams narrow the margin gap between initial installation and lifecycle maintenance. Tarkett's nationwide distribution network captures recurring maintenance agreements.
- State-Level Extended Producer Responsibility:Procurement mandates requiring recycled content disclosure create competitive differentiation for manufacturers with verified supply chain documentation.
- Biomechanical Subfloor Integration:Convergence of force-sensing technology with engineered subfloor systems enables real-time athlete load monitoring. Robbins Sports Surfaces patents position for injury prevention specification.
Industry Challenges
- Certified Installer Pipeline Constraints:ASTM F2569 and F2772 compliance requires specialized training that outpaces vocational program output in the Mountain West and Pacific Northwest.
- Legacy Facility Retrofit Complexity:Existing post-tensioned concrete slabs in 1970s-era gymnasiums demand custom leveling systems that extend project duration and compress contractor margins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Sports Flooring Market |
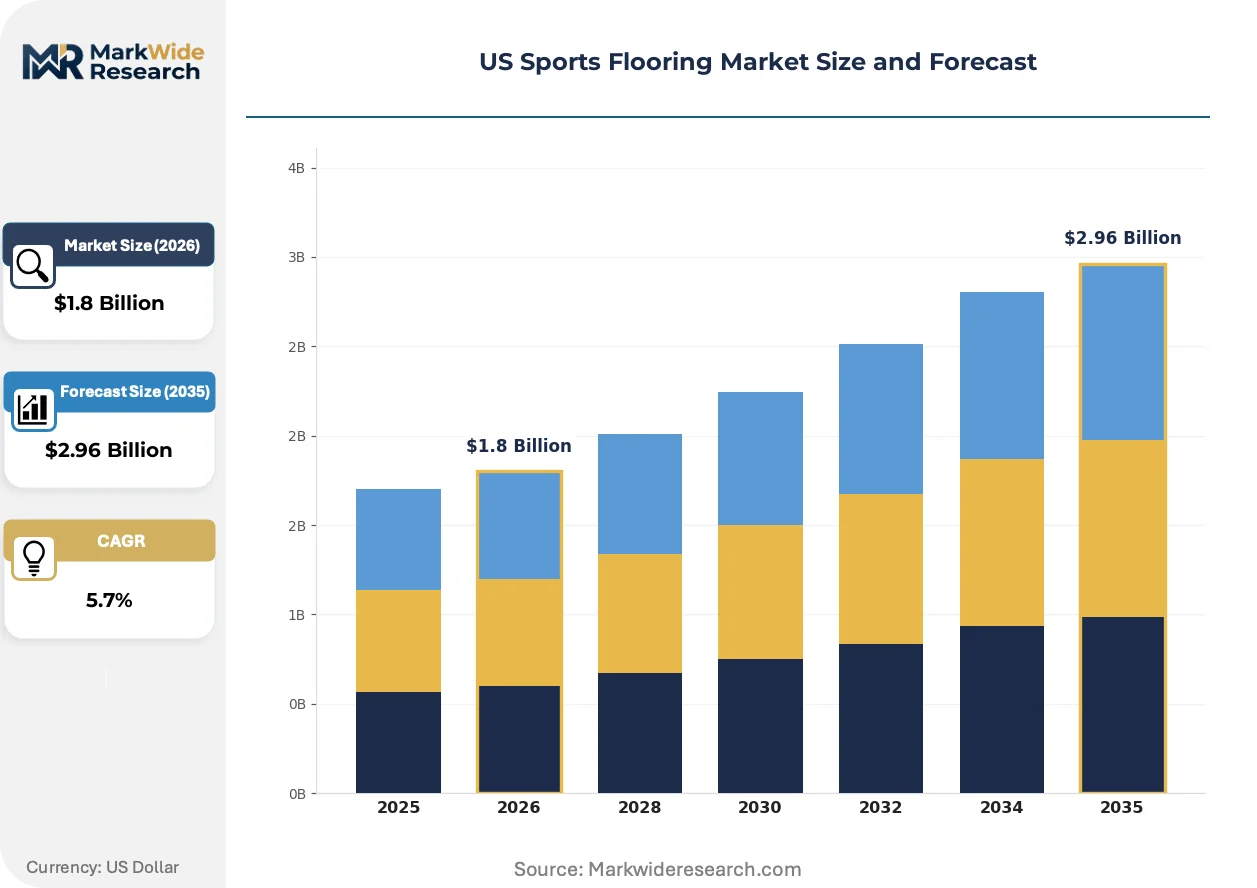
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carpet, Rubber, Wooden, Vinyl Installation Type: Indoor, Outdoor, Modular, Fixed End User: Schools, Gyms, Community Centers, Stadiums Application: Basketball, Volleyball, Multipurpose, Fitness |
| Companies Covered | Tarkett, Connor Sports, Robbins Sports Surfaces, Gerflor USA, Action Floor Systems, Kiefer USA, SnapSports Athletic Surfaces, Forbo Flooring Systems, LG Hausys, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Sports Flooring Market Strategic Shifts
Material science advances are collapsing the performance gap between traditional maple hardwood and engineered synthetics, while procurement centralization among large school districts rewrites competitive dynamics for regional installers and national manufacturers alike.
Polyurethane-coated recycled rubber composite flooring is hybridizing performance characteristics previously segmented by price tier. Texas and Florida school districts now specify these surfaces for basketball installations that must double as multipurpose community venues. The technology is compressing the historical trade-off between shock absorption ratings and surface durability, enabling mid-budget projects to access elite-tier performance metrics.
California's Title 24 energy efficiency standards are mandating low-VOC formulations across all publicly funded construction. Manufacturers serving the West Coast market have reformulated adhesive portfolios to meet these thresholds ahead of potential federal adoption. The policy is accelerating water-based polyurethane displacement of solvent systems in school gymnasium specifications nationwide.
Facility managers in the Midwest and Southeast are consolidating procurement decisions at the district level rather than individual school authority. This concentration shifts vendor selection criteria toward lifecycle cost modeling and standardized maintenance protocols. Ohio and Georgia school systems now require ten-year total cost of ownership projections that include resurfacing schedules and warranty transferability.
US Sports Flooring Market Segmentation
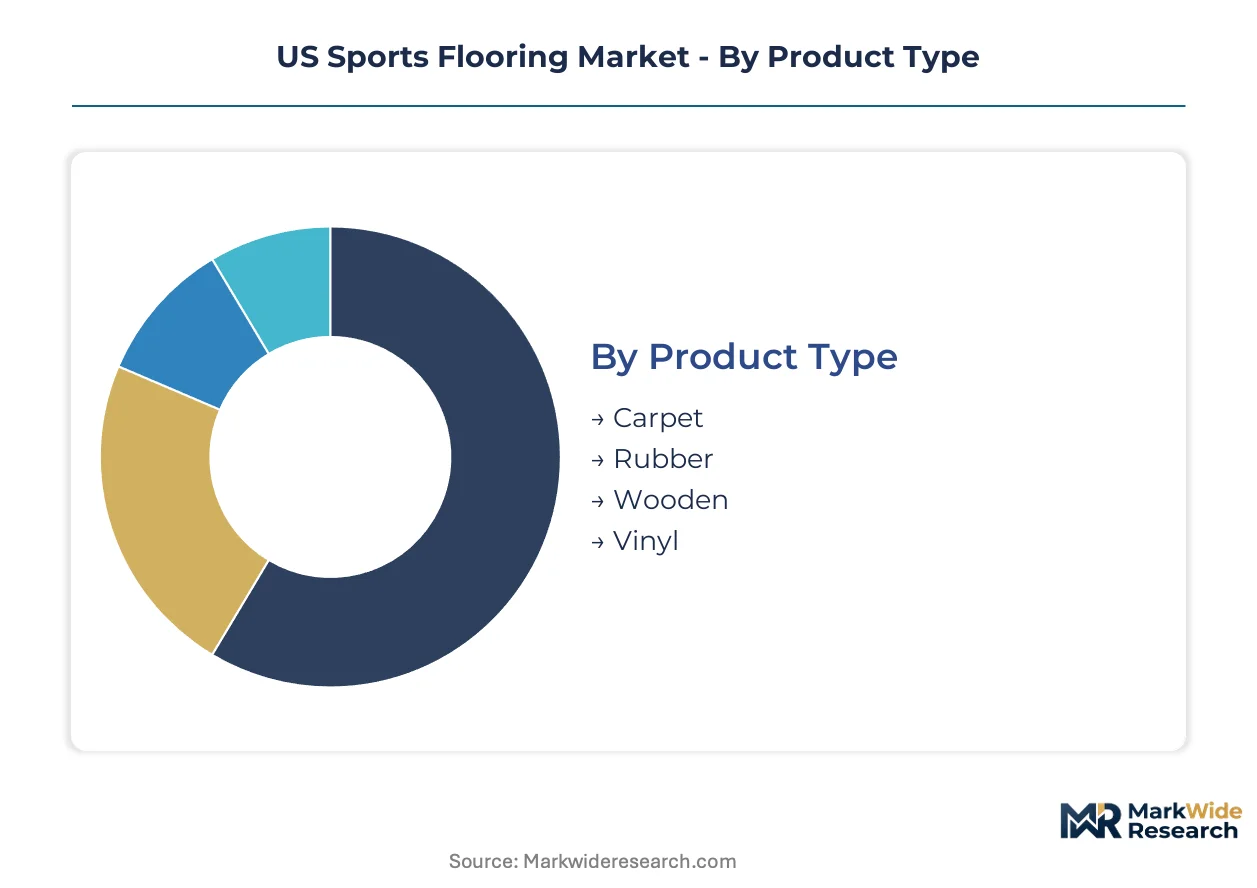
Sports flooring segmentation reveals how performance requirements, budget constraints, and facility lifecycle demands fragment procurement patterns across distinct customer archetypes. Specification divergence between NCAA-caliber venues and K-12 gymnasiums creates parallel demand tracks that manufacturers must serve simultaneously.
Product Type:
Surface composition determines shock absorption ratings, maintenance protocols, and compliance with athletic federation standards across the use-case spectrum.
- Wooden:Kiln-dried maple veneer systems deliver the force reduction and vertical deformation parameters mandated by FIBA and NCAA regulations. University athletic departments in the Midwest and Southeast specify engineered maple for competitive basketball venues where ball rebound consistency is non-negotiable.
- Rubber:Polyurethane-coated recycled rubber composites hybridize durability with mid-tier shock absorption. Texas and Florida school districts specify these surfaces for multipurpose installations where capital constraints override premium performance requirements.
- Vinyl:Homogeneous sheet flooring offers chemical resistance and rapid installation for fitness centers and physical education spaces.
- Carpet:Needle-punch synthetic turf serves low-impact training zones and warm-up areas adjacent to hardwood courts.
Established volume favors wooden systems; emerging adoption favors rubber composites.
Installation Type:
Construction methodology shapes project timelines, labor cost structures, and future facility reconfiguration flexibility.
- Modular:Prefabricated subfloor assemblies with clip-together mechanical fastening enable rapid deployment and future relocation. Community centers in the Southeast prioritize these systems for operational flexibility as programming needs evolve.
- Fixed:Permanent adhesive-bonded installations anchor premium maple systems in elite competitive venues. NCAA basketball programs require fixed installation to meet ASTM F2569 ball rebound consistency standards.
- Indoor:Climate-controlled environments dominate specification for competitive athletics and year-round recreational use.
- Outdoor:UV-stabilized surfaces with drainage substructures serve seasonal training facilities and temporary competition venues.
Fixed installation retains margin concentration; modular systems are climbing the fastest as facility managers prioritize adaptability.
End User:
Customer type dictates procurement authority, budget cycles, and performance specification thresholds.
- Schools:K-12 districts concentrate purchasing decisions at the central administration level, shifting vendor selection toward lifecycle cost modeling. Ohio and Georgia systems now require ten-year total cost of ownership projections including resurfacing schedules.
- Gyms:Commercial fitness operators prioritize surface durability under high-traffic conditions and chemical resistance to cleaning protocols.
- Community Centers:Municipal recreation departments balance multipurpose programming demands against constrained capital budgets.
- Stadiums:Professional and collegiate arena operators specify surfaces meeting broadcast lighting reflectance and athlete biomechanical performance standards.
District-level procurement favors school installations; private capital deployment favors gym operators.
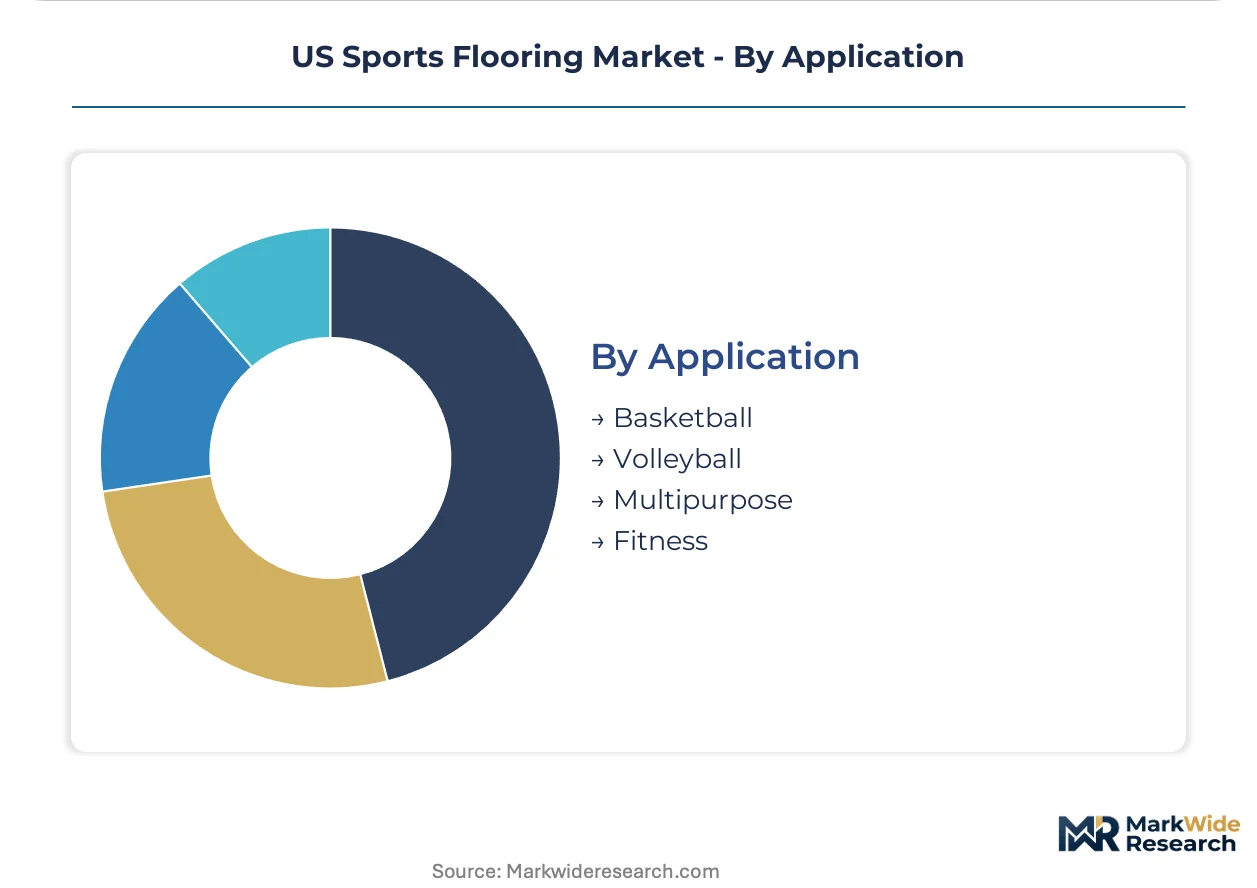
Application:
Activity-specific biomechanical demands drive surface specification divergence across athletic disciplines.
- Basketball:NCAA and FIBA standards mandate precise shock absorption, vertical deformation, and ball rebound coefficients. Engineered maple systems with proprietary subfloor technology dominate elite venue specification.
- Multipurpose:Variable-use spaces require surfaces accommodating basketball, volleyball, and non-athletic events without performance degradation. Synthetic systems with adjustable floor covering systems serve this flexibility requirement.
- Volleyball:Lower force reduction thresholds than basketball permit specification of slightly less rigid surface systems at moderate cost reduction.
- Fitness:Free-weight zones and group exercise studios prioritize impact sound attenuation and equipment load distribution over ball rebound characteristics.
Single-sport optimization favors basketball specification; programming diversity favors multipurpose surfaces.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns across US sub-regions diverge sharply: the Midwest and Southeast prioritize school gymnasium renovations with maple systems, while California and the Southwest specify low-VOC synthetics under energy mandates. Texas and Florida concentrate district-level procurement for multipurpose installations.
Midwest
School districts across Ohio and Michigan compress replacement timelines for aging gymnasium infrastructure. State procurement offices require ten-year lifecycle cost projections from vendors. The Great Lakes region anchors premium maple veneer supply chains, though harvest disruptions periodically constrain availability.
Southeast
Georgia and Florida school systems centralize purchasing decisions at district administration levels. Community centers in the region specify modular installation systems for programming flexibility. The Carolinas cluster recreational fitness facility construction, driving demand for rapid-deployment subfloor assemblies.
California
Title 24 energy efficiency standards mandate low-VOC synthetic surfaces in publicly funded construction. Facility operators specify water-based polyurethane formulations to meet air quality thresholds. The Los Angeles and Bay Area metro areas concentrate municipal recreation department capital projects.
Southwest
Budget-constrained K-12 districts in Arizona and New Mexico specify recycled rubber surfaces for capital expenditure reduction. The region sacrifices vertical deformation performance for installation cost containment. Texas anchors district-level basketball and multipurpose procurement concentration.
Northeast
Legacy facility retrofit complexity elevates contractor qualification requirements in New York and Massachusetts. Post-tensioned concrete slabs from 1970s-era gymnasiums demand custom leveling systems. The region trails national averages in modular system adoption due to existing fixed-installation infrastructure.
US Sports Flooring Market Competitive Environment
Capability concentration sits with specialized hardwood manufacturers; scale advantage sits with diversified flooring conglomerates. The market structures around three tiers: premium maple specialists, synthetic system generalists, and regional installation contractors. Two strategic archetypes dominate competitive positioning: technology licensors with patented subfloor IP, and maintenance service bundlers capturing lifecycle revenue. M&A activity concentrates among synthetic manufacturers acquiring regional distributors; strategic partnerships link hardwood producers to university athletic departments.
Within the premium hardwood tier, Connor Sports and Robbins Sports Surfaces occupy positions defined by NCAA program relationships and proprietary subfloor technology. Tarkett represents the diversified conglomerate archetype with nationwide distribution infrastructure. These three companies exemplify the capability-scale bifurcation: specialized engineering versus operational scale.
| Leading Market Players |
|---|
| Tarkett |
| Connor Sports |
| Robbins Sports Surfaces |
| Gerflor USA |
| Action Floor Systems |
| Kiefer USA |
| SnapSports Athletic Surfaces |
| Forbo Flooring Systems |
| LG Hausys |
| Others |
Value Chain & Pricing Dynamics
Great Lakes kiln-dried maple supply concentration determines both premium tier spreads and supply chain shape. Buyers face freight cost volatility and weather-related harvest disruptions that compress margins on engineered hardwood systems.
Pricing Analysis
Project-based contracting dominates school district procurement, with ten-year total cost of ownership models now standard in Ohio and Georgia. Price differentiation hinges on ASTM F2569/F2772 certification tier and volume scale across district-level consolidated awards. Cost compression in mid-tier rubber composites intensifies as Texas and Florida districts prioritize capital expenditure containment over vertical deformation performance. K-12 administrators exhibit highest price sensitivity; NCAA athletic departments tolerate premium positioning for biomechanical compliance.
Supply Chain Analysis
Extended payment terms from national distributors like Tarkett strain regional installer cash flows, particularly on large district contracts. Raw material sourcing draws from Great Lakes maple veneer producers, domestic polyurethane resin manufacturers, and recycled rubber processors in the Southeast. Single-source vulnerability concentrates in premium hardwood substrate supply during harvest disruption periods. Distribution runs through manufacturer-direct specification teams for elite athletic venues and regional distributor networks for school and community center installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified installer pipeline gaps constrain market expansion, with vocational program output lagging demand across the Mountain West and Pacific Northwest. This capability scarcity rewards players who control training certification and field deployment capacity.
For Market Incumbents: Harden proprietary subfloor technology positions through patent enforcement and exclusive NCAA program relationships. Expand captive installer training capacity to capture district-level maintenance contract bundling. Rubber flooring substitution from Southwest K-12 districts threatens maple volume; respond with lifecycle cost modeling tools that quantify total ownership economics. For New Entrants and Emerging Players: Build out modular installation system offerings targeting Southeast community centers seeking programming flexibility. The Southwest recycled rubber segment offers lowest entry barriers for capital-constrained challengers. Lead with rapid-deployment subfloor assemblies that reduce on-site labor hours and enable future facility reconfiguration. For Investors and Strategic Acquirers: EPA VOC regulation phase-in reshapes the acquisition landscape toward water-based formulation capabilities and verified supply chain documentation. Five-to-ten year viability favors manufacturers with district-level procurement relationships and aftermarket service infrastructure. Monitor California Title 24 adoption velocity as signal for federal standards convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Biomechanical Subfloor Patent Portfolio | Robbins Sports Surfaces IP positions capture injury prevention specification from NCAA programs. |
| District-Level Maintenance Contract Bundling | Tarkett's nationwide distribution network captures recurring resurfacing revenue streams. |
| Water-Based Polyurethane Formulation Transition | California Title 24 compliance creates competitive differentiation in publicly funded construction. |
| Modular Installation System Scale-Up | Southeast community centers prioritize rapid-deployment subfloors for operational flexibility. |
| Certified Installer Training Program Expansion | ASTM F2569/F2772 compliance requirements outpace vocational output in undersupplied regions. |
Study Parameters
Cross-validation between facility manager interviews and manufacturer specification data anchors the qualitative findings. Primary fieldwork engaged athletic directors, district procurement officers, and installation contractor operations leads. Secondary sources included EPA emissions filings, ASTM standard documentation, and state procurement database records. Bottom-up project pipeline analysis and top-down construction spending triangulation validated volume estimates across the analysis window.
Calibration against historical replacement cycle data and district budget authorization patterns informed the projection framework. Segmentation modeling covered surface composition, installation methodology, end-user type, and application-specific performance requirements. CAGRs derived from fitted trend extrapolation with elasticity adjustments for regulatory compliance cost impacts. Forecast inputs incorporated Title 24 adoption curves and school facility age distribution data.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified flooring conglomerates would shift outcomes. Macroeconomic deviation in construction spending, regulatory acceleration beyond California's Title 24 framework, or breakthrough synthetic performance parity would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Alpine Ski Equipment Market
Sports Equipment
Global Sports Bicycle Market
Sports Equipment
Surfing Equipment Market
Sports Equipment
Global Sporting Goods Market
Sports Equipment
Backboard Market
Sports Equipment
Tennis Pole Market
Sports Equipment
Global Golf Accessories Market
Sports Equipment
Pitching Machine Market
Sports Equipment
Ice Hockey Equipment Market
Sports Equipment
Europe Artificial Grass Market
Sports Equipment
Archery Equipment Market
Sports Equipment
Ladderball Market
Sports Equipment
Shooting Ranges Market
Sports Equipment
Crampon Market
Sports Equipment
Global Badminton Equipment Market
Sports Equipment
Global Mountain Bicycles Market