
 Field Hockey Equipment Market | 2026-2036
Field Hockey Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Field Hockey Equipment Market Analysis
Elite carbon-fiber composite construction is redrawing competitive dynamics in field hockey equipment. Grays of Cambridge leverages proprietary layup techniques to sustain premium positioning in professional-tier sticks. Adidas AG anchors volume through its global team sponsorship network and retail scale. Kookaburra Sport Pty Ltd differentiates via specialized goalkeeper protective gear where technical certification requirements create barriers.
Field hockey equipment comprises sticks, balls, protective gear, and footwear engineered to FIH dimensional and safety specifications, with carbon-fiber composite sticks typically constructed from woven graphite and aramid layers bonded under heat pressure to achieve targeted flex ratings and power transfer coefficients. This equipment serves competitive match play, training, and grassroots development across amateur through professional tiers. Composite material sticks command the dominant margin pool due to raw material costs and performance differentiation, while protective gear represents the fastest-expanding category as goalkeeper safety standards tighten. The amateur player segment drives absolute volume, though professional athlete channels yield higher per-unit pricing and brand association value.
FIH equipment standards, REACH chemical compliance for European distribution, and ISO 9001 manufacturing certifications collectively shape product legality, material permissibility, and market access across major sales corridors. The EPA oversees composite resin emissions in US-based production facilities, adding environmental compliance layers to domestic manufacturing decisions. Stakeholders must monitor evolving carbon-fiber supply constraints and regulatory harmonization between FIH playing rules and national consumer safety frameworks.
Market Dynamics
Carbon-fiber supply concentration in East Asian manufacturing clusters is compressing margin structures across composite stick producers, forcing procurement diversification and layup technology differentiation as primary competitive levers.
Growth Catalysts
- FIH stick curvature revisions:Mandated dimensional updates are accelerating composite material upgrades across manufacturing bases, creating replacement cycles in professional and amateur tiers simultaneously.
- Australia school athletic procurement:Expanded equipment budgets in secondary education programs are driving volume demand for entry-level stick and protective gear bundles.
- Netherlands club participation density:Elevated grassroots registration rates in Dutch hockey associations are sustaining premium equipment turnover through institutional channel partnerships.
Market Restraints
- Aramid fiber cost volatility:Raw material price swings in synthetic fiber feedstocks are compressing gross margins for mid-tier composite manufacturers without long-term supply contracts.
- East Asian supply concentration:Carbon-fiber precursor production clusters in China and Taiwan create geographic vulnerability for European and North American stick assemblers.
- REACH chemical compliance:ECHA substance restrictions on resin formulations are extending product development timelines and testing expenditures for EU market entry.
Strategic Opportunities
- Goalkeeper protective gear specialization:Technical certification requirements for chest protectors and leg guards are creating defensible niche positions with higher margin profiles than commodity sticks.
- India grassroots infrastructure:Hockey India federation development programs and state-level academy construction are opening equipment procurement channels outside traditional Western markets.
- Direct-to-club digital distribution:Bypassing traditional retail intermediaries through team-specific customization portals is capturing margin and shortening order-to-delivery cycles.
Industry Challenges
- Composite layup technician scarcity:Skilled labor capable of precision fiber orientation and heat-pressure calibration is concentrated among legacy manufacturers, constraining capacity expansion.
- ISO 9001 certification timelines:Extended audit and documentation requirements are delaying new facility qualification for FIH-approved production.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Field Hockey Equipment Market |
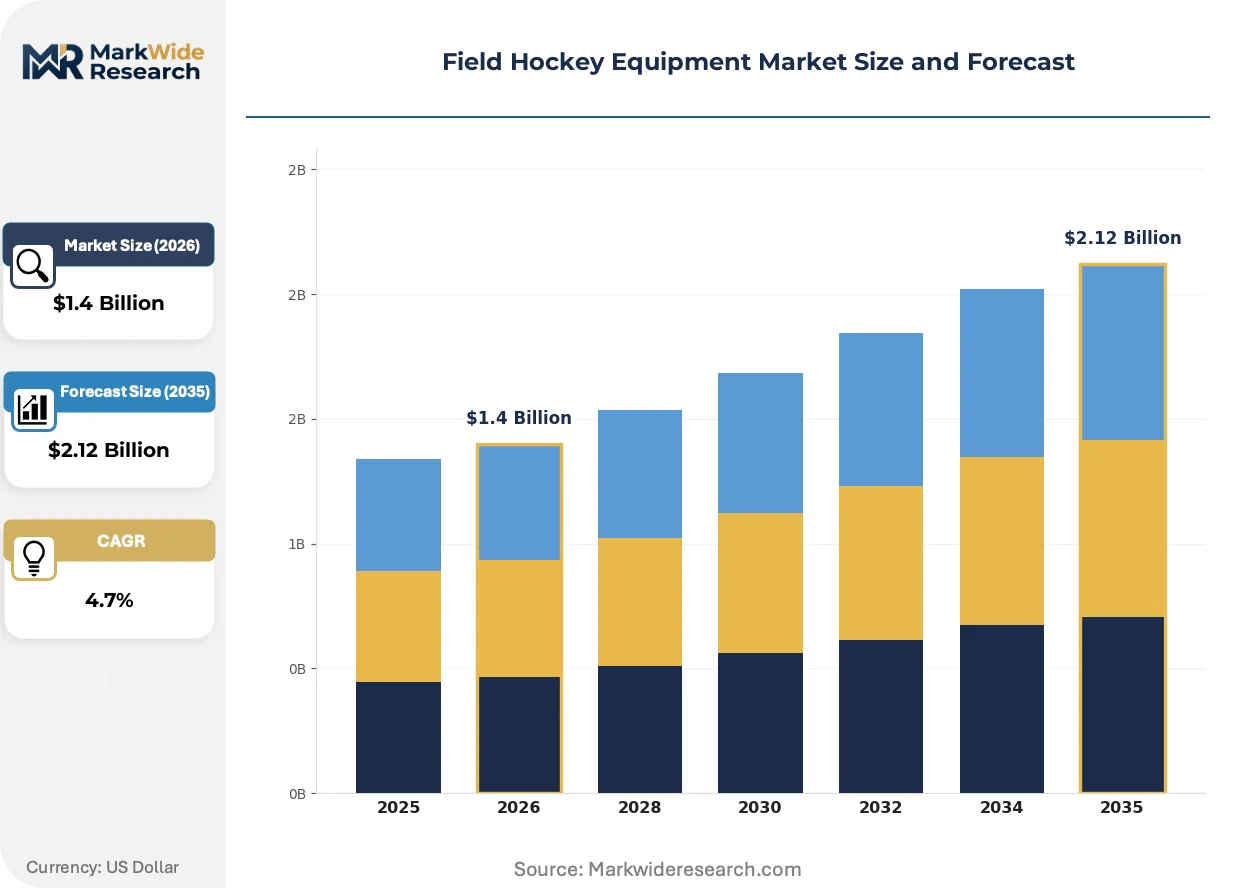
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.12 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sticks, Balls, Protective Gear, Footwear End User: Amateur Players, Professional Athletes, Schools, Clubs Material: Composite, Wood, Aluminum, Plastic Distribution Channel: Online Retail, Sporting Goods Stores, Specialty Shops, Events |
| Companies Covered | STX, Bauer Hockey, LLC, Adidas AG, Mazon Hockey, Harrow Sports, Grays of Cambridge, Kookaburra Sport Pty Ltd, OBO Hockey, Gryphon Hockey Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Field Hockey Equipment Market Emerging Trajectories
Material science convergence with digital manufacturing is redefining equipment performance benchmarks. Three developments are compressing traditional production cycles and redrawing competitive boundaries.
Embedded sensor integration in composite stick handles is miniaturizing. Micro-accelerometer packages now capture swing velocity and impact force data for real-time biomechanical feedback. Elite training programs in the Netherlands and Australia are adopting these instrumented sticks for athlete development protocols. The technology is compressing the gap between equipment manufacturers and sports analytics providers.
REACH substance restrictions on epoxy resin formulations are tightening across European distribution corridors. ECHA candidate list updates are forcing reformulation of bonding agents used in multi-layer composite construction. Manufacturers serving EU markets are accelerating bio-based resin testing programs to preempt compliance-driven product obsolescence.
Club-level bulk purchasing is consolidating decision authority away from individual players. Amateur associations in Belgium and Germany are centralizing equipment procurement through multi-year framework agreements with preferred suppliers. This concentration is displacing traditional retail foot traffic and favoring manufacturers with direct institutional sales capabilities.
Field Hockey Equipment Market Segmentation
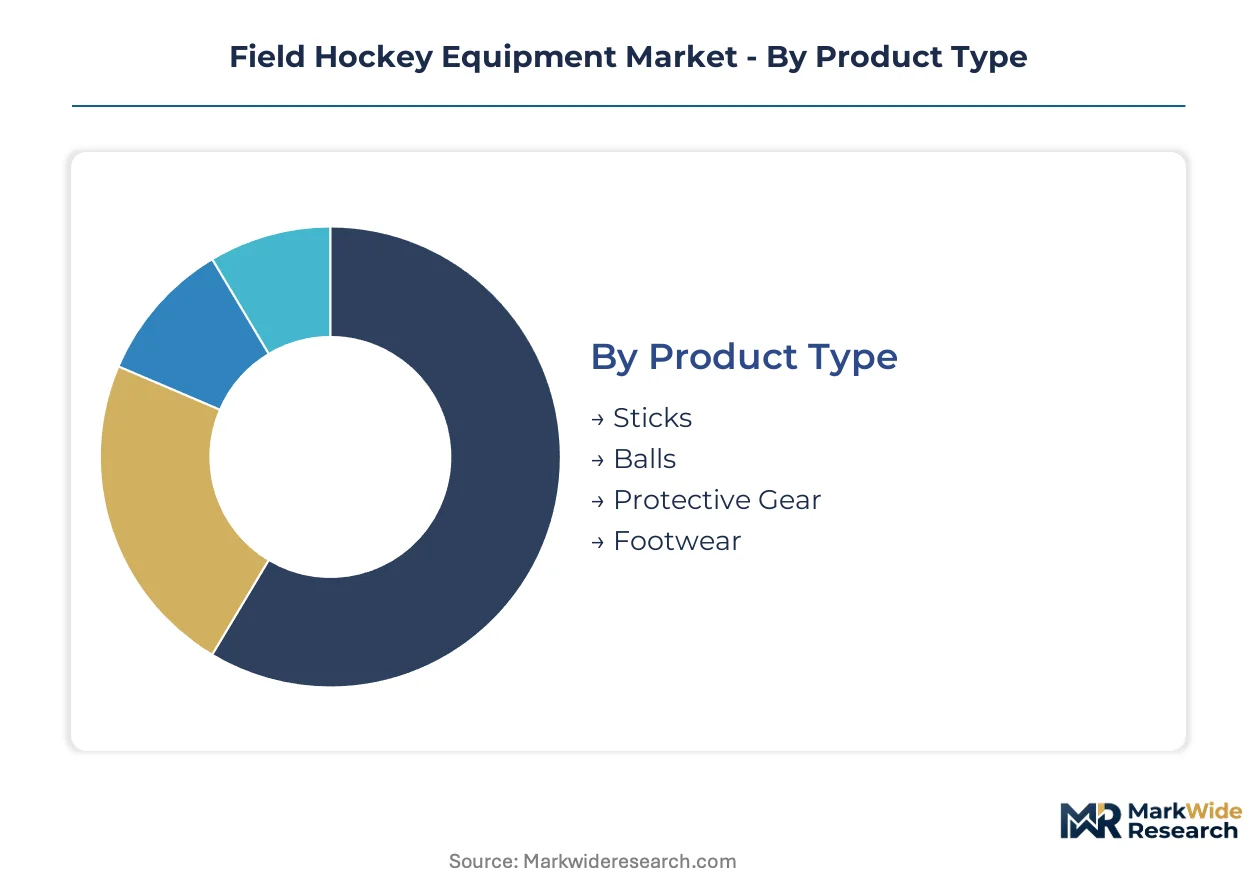
Segmentation in field hockey equipment reveals divergent margin architectures across product construction, user sophistication, and procurement channel. Composite material tiers and institutional purchasing patterns command disproportionate profitability compared to mass-market commodity segments.
Product Type:
Margin pools concentrate in composite stick construction where carbon-fiber layup complexity sustains premium pricing, while protective gear generates expanding returns through tightening FIH goalkeeper safety mandates.
- Sticks:Carbon-fiber composite construction using woven graphite and aramid layers bonded under heat pressure delivers calibrated flex ratings and power transfer coefficients. Demand clusters in the Netherlands where club participation density sustains premium turnover through institutional channel partnerships.
- Protective Gear:Technical chest protectors and leg guards engineered to FIH goalkeeper safety specifications require specialized certification that creates defensible niche positions. Australia school athletic programs are expanding equipment procurement budgets for entry-level protective bundles, driving volume expansion.
- Balls:Molded polymer construction with surface texturing for consistent roll characteristics on synthetic turf surfaces.
- Footwear:Cleated outsole designs optimized for lateral stability and turf traction across varying pitch conditions.
Sticks hold installed capacity. Protective gear is rotating up the share rankings.
End User:
Volume distribution tilts toward amateur participation tiers, though professional athlete channels yield superior per-unit economics and brand association value.
- Amateur Players:Grassroots participants across club and recreational tiers drive absolute unit volume through replacement cycles and entry-level purchases. Belgium and Germany amateur associations are centralizing equipment procurement through multi-year framework agreements, displacing traditional retail foot traffic.
- Professional Athletes:Elite-tier competitors require FIH-certified equipment with precise dimensional compliance and performance specifications. Netherlands training programs are adopting embedded sensor-integrated sticks for biomechanical feedback protocols, compressing equipment-analytics convergence.
- Schools:Secondary education athletic programs in Australia are expanding equipment procurement budgets for developmental tier bundles.
- Clubs:Institutional purchasing authorities are consolidating decision authority away from individual players through direct manufacturer relationships.
Amateur players hold installed capacity. Professional athletes are rotating up the share rankings.
Material:
Supply-side concentration in East Asian precursor manufacturing clusters compresses margin structures for composite assemblers without captive fiber sourcing or differentiated layup capabilities.
- Composite:Multi-layer carbon-fiber and aramid construction achieves targeted stiffness-to-weight ratios through precision fiber orientation and resin bonding. REACH chemical compliance requirements from ECHA are extending product development timelines for EU market entry.
- Wood:Traditional timber laminates retain presence in developmental and educational tiers where cost sensitivity outweighs performance optimization.
- Aluminum:Extruded alloy shafts offer durability for institutional rental and introductory player segments.
- Plastic:Injection-molded polymer components serve training accessories and entry-level protective elements.
Composite holds installed capacity. Wood is rotating up the share rankings as educational procurement expands.
Distribution Channel:
Channel economics are shifting as institutional procurement consolidation and digital direct-to-club platforms capture margin from traditional retail intermediaries.
- Online Retail:Direct-to-consumer platforms enable customization portals that shorten order-to-delivery cycles and capture margin previously allocated to retail intermediaries.
- Sporting Goods Stores:Generalist retail footprints face displacement as club-level bulk purchasing concentrates decision authority with institutional buyers.
- Specialty Shops:Technical consultation and fitting services retain relevance for high-performance stick selection among competitive players.
- Events:Tournament and championship merchandising generates concentrated demand spikes tied to competitive calendars.
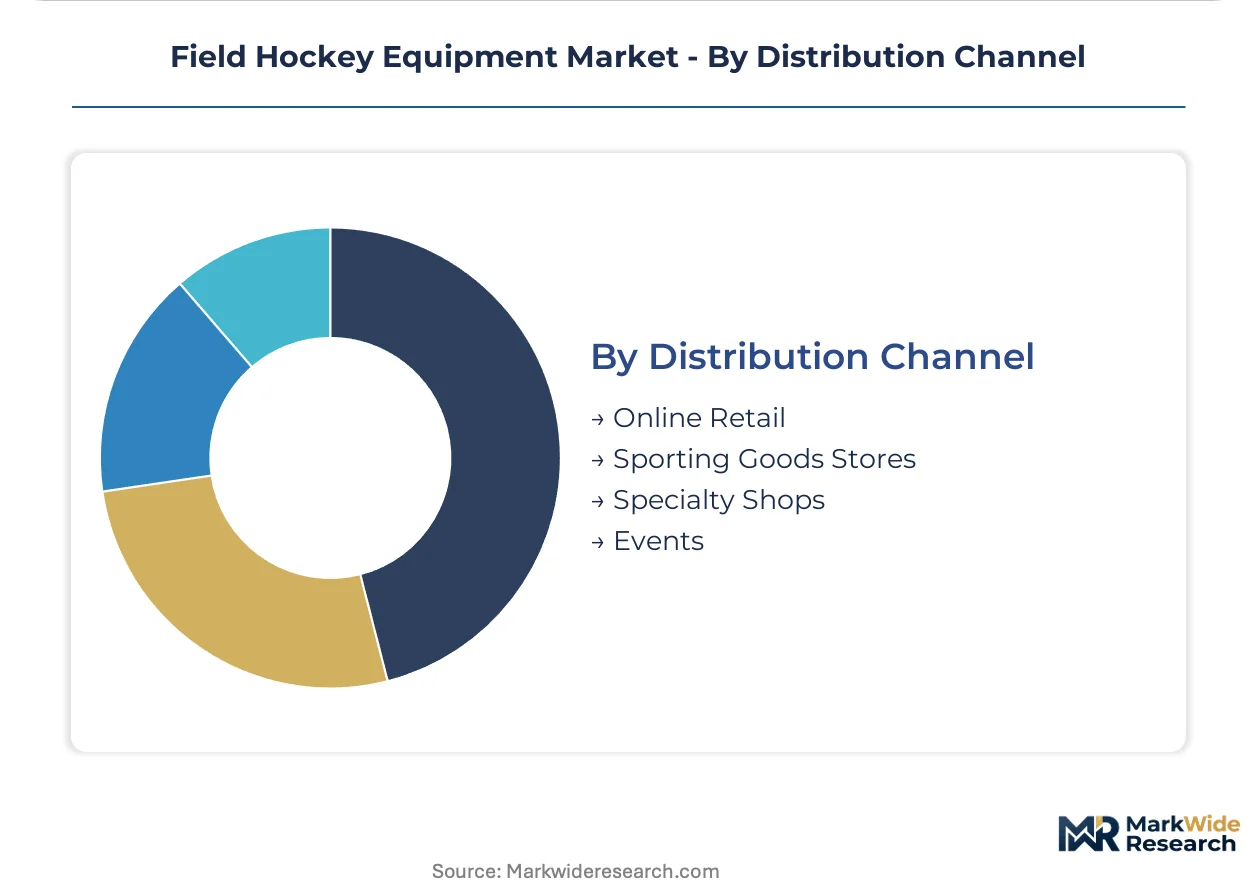
Specialty shops hold installed capacity. Online retail is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity fragments sharply across geographies. Amateur club systems in Western Europe absorb premium-tier pricing with minimal elasticity. School procurement channels in Australia and grassroots programs in India demand cost-optimized bundles with tight budget constraints.
Netherlands
Club participation density sustains premium equipment turnover through institutional channel partnerships. The Dutch hockey federation operates development programs that standardize equipment specifications across member clubs. Eindhoven and Amsterdam host concentration of specialty retailers serving competitive player segments.
Australia
Secondary school athletic programs are expanding equipment procurement budgets for developmental-tier stick and protective gear bundles. TGA product safety standards govern protective equipment certification requirements. Melbourne and Sydney metropolitan areas concentrate club registration growth and retail distribution infrastructure.
India
Hockey India federation development programs and state-level academy construction are opening equipment procurement channels outside traditional Western markets. Ministry of Youth Affairs and Sports funding flows to equipment subsidies for grassroots programs. Punjab and Haryana states maintain historical participation concentration with expanding manufacturing assembly presence.
Germany
Amateur associations are centralizing equipment procurement through multi-year framework agreements with preferred suppliers, displacing traditional retail foot traffic. REACH chemical compliance from ECHA extends product development timelines for composite stick manufacturers. North Rhine-Westphalia and Bavaria host dense club networks with institutional purchasing authority.
United States
NCAA athletic programs and private academy systems drive institutional procurement volume with specification-driven purchasing. EPA oversight of composite resin emissions affects domestic manufacturing facility siting decisions. California and Mid-Atlantic states concentrate participation growth and specialty retail presence.
Field Hockey Equipment Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes. Premium-tier positioning concentrates among heritage manufacturers with proprietary layup capabilities and FIH certification depth. Volume-scale players anchor mass-market segments through team sponsorship networks and retail distribution breadth. Competitive moves center on direct-to-club digital platform development and goalkeeper protective gear specialization to escape commodity stick margin compression.
Among heritage British manufacturers, Grays of Cambridge occupies a position representing premium-tier composite specialization, while Kookaburra Sport Pty Ltd exemplifies protective gear differentiation with technical certification barriers. Adidas AG anchors the scale-driven archetype through global team sponsorship infrastructure and retail footprint density.
| Leading Market Players |
|---|
| STX |
| Bauer Hockey, LLC |
| Adidas AG |
| Mazon Hockey |
| Harrow Sports |
| Grays of Cambridge |
| Kookaburra Sport Pty Ltd |
| OBO Hockey |
| Gryphon Hockey Ltd |
| Others |
Supply Flow & Price Mechanics
Ninety-day carbon-fiber precursor lead times from East Asian manufacturing clusters compress margin structures for European and North American stick assemblers, while institutional buyers in the Netherlands and Australia exploit consolidated procurement to extract volume discounts from premium-tier manufacturers.
Pricing Analysis
After-sales service contracts for stick reconditioning and flex recalibration drive lifetime value in professional athlete channels. Three-tier pricing structure across premium, standard, and economy levels stratifies by carbon-fiber layup complexity and FIH certification grade. Pricing pressure stems from aramid fiber cost volatility and REACH compliance testing expenditures. Amateur school programs in Australia exhibit highest price sensitivity, while Dutch club systems absorb premium-tier pricing with minimal elasticity.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes extend inbound logistics costs for composite precursor materials. Carbon-fiber supply concentrates in China and Taiwan, with aramid fiber production anchored in the United States and Japan. Raw material dependencies include PAN precursor, epoxy resin formulations, and synthetic turf-adapted polymers. Single-source vulnerability in East Asian precursor manufacturing creates geographic concentration risk. Distribution runs through direct-to-club digital platforms and specialty retail channels serving competitive player segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics reshape competitive positioning as embedded sensor integration compresses equipment-analytics convergence, creating interoperability requirements between stick manufacturers and sports technology providers.
For Market Incumbents: Compound proprietary layup capabilities with goalkeeper protective gear specialization to escape commodity stick margin compression. Deepen FIH certification depth as a defensive moat against emerging composite manufacturers. Anchor volume through multi-year framework agreements with Australian school athletic programs and Dutch institutional buyers. For New Entrants and Emerging Players: Lead with direct-to-club digital distribution portals that bypass traditional retail intermediaries and capture margin through team-specific customization. Target India's grassroots infrastructure expansion as the most penetrable geography, where Hockey India federation development programs create procurement channels outside established Western markets. For Investors and Strategic Acquirers: Carve-out targets emerge from heritage British manufacturers with captive composite layup technician pools and FIH-approved production facilities. Long-term viability hinges on backward integration into carbon-fiber precursor sourcing or differentiated resin formulation capabilities. Watch embedded sensor adoption rates in Netherlands and Australian elite training programs as inflection indicators for equipment-analytics convergence.| Strategic Initiative | Industry Significance |
|---|---|
| Goalkeeper Protective Gear Specialization | Technical certification requirements for chest protectors create defensible niche positions with higher margins than commodity sticks. |
| Direct-to-Club Digital Platform Development | Bypassing retail intermediaries through team-specific customization portals captures margin and shortens order-to-delivery cycles. |
| Backward Integration into Carbon-Fiber Sourcing | Captive precursor supply from East Asian manufacturing clusters mitigates geographic vulnerability and cost volatility exposure. |
| Bio-Based Resin Formulation Investment | REACH substance restrictions on epoxy resins force reformulation programs to preempt compliance-driven product obsolescence. |
| India Grassroots Infrastructure Partnership | Hockey India federation development programs open equipment procurement channels outside traditional Western markets. |
Methodological Framework
Cross-validation between primary interviews with composite manufacturing engineers, FIH equipment certification officers, and school athletic procurement directors anchors the qualitative findings against secondary sources including FIH regulatory filings, ECHA substance restriction updates, and Australian TGA product safety standards. Bottom-up demand modeling from club registration databases and institutional purchasing records triangulates with top-down market sizing from customs trade data and specialty retail point-of-sale systems.
Sensitivity analysis across carbon-fiber cost scenarios and REACH compliance timeline variations tests forecast robustness over the projection horizon. Segmentation dimensions include material tier, end-user sophistication, and distribution channel structure, with additional granularity on goalkeeper versus outfield equipment specifications. CAGRs derive from replacement cycle analysis tied to FIH stick curvature regulation revisions and grassroots participation growth trajectories in priority markets.
The analysis sits within stated boundaries; outcomes outside sustained club participation density in Western Europe, continued school procurement expansion in Australia, or carbon-fiber supply chain stability would require recalibration. Forecasts reflect documented assumptions regarding FIH regulatory harmonization and composite material substitution elasticities. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports Equipment
Recreational Rowing Boats Market
Sports Equipment
Power Sports Aftermarket Market
Sports Equipment
Pickleball Paddle Market
Sports Equipment
Global Pickleball Equipment Market
Sports Equipment
Sports Fishing Equipment Market
Sports Equipment
Sports Protective Equipment Market
Sports Equipment
Gymnastic Hoops Market
Sports Equipment
Surface Water Sports Equipment Market
Sports Equipment
Europe Ski Gear and Equipment Market
Sports Equipment
Quad Skate Market
Sports Equipment
Global Golf Rangefinders Market
Sports Equipment
Tennis Equipment Market
Sports Equipment
Rowing Oars Market
Sports Equipment
Gym Rubber Flooring Market
Sports Equipment
Sports Devices Market
Sports Equipment
Global Mountain Bicycles Market