
 USA Sports Team and Club Market | 2026-2036
USA Sports Team and Club Market Size, Share, and Industry Trends Forecast 2026-2036
USA Sports Team and Club Market Insights
Corporate hospitality and experiential entertainment spending is realigning how sports organizations prioritize premium seating and venue amenities. The National Football League leverages its broadcast infrastructure to command sustained media rights valuations. Major League Baseball anchors its revenue base through legacy ballpark real estate and regional sports network partnerships. The National Basketball Association differentiates through international digital streaming reach and jersey patch sponsorship integration.
USA sports teams and clubs constitute organized athletic entities operating across professional, collegiate, and amateur tiers, generating revenue through live event production, media content licensing, and brand commercialization with operational parameters spanning 82-game regular seasons to 16-team playoff brackets. Professional teams within the organization type segment capture disproportionate national media attention and capital investment, while amateur clubs and youth organizations represent fragmented grassroots participation infrastructure. Broadcast rights and sponsorships within the revenue stream segment concentrate margin pools among top-tier leagues with national distribution, whereas merchandise and ticket sales face more localized competitive dynamics.
The Federal Communications Commission shapes media access through broadcast licensing and anti-siphoning rules protecting free-to-air game coverage, while the NCAA governs amateur athlete compensation structures affecting college team commercialization boundaries. State athletic commissions regulate professional competition standards, medical protocols, and wagering integrity requirements. Stakeholders must monitor evolving NIL enforcement patterns, regional sports network bankruptcy restructuring, and municipal stadium financing covenant renegotiations to calibrate capital allocation and partnership strategies.
Market Dynamics
The NCAA's NIL policy framework has restructured amateur athlete compensation, redirecting capital flows from traditional broadcast bundles toward direct athlete-brand relationships and fragmenting established revenue concentration models across collegiate athletics.
Growth Catalysts
- Direct-to-consumer streaming infrastructure:Over-the-top platforms bypass legacy regional sports network intermediaries, capturing subscriber data and enabling dynamic pricing experimentation for live event access.
- Texas metropolitan venue construction:Dallas-Fort Worth and Houston markets anchor stadium financing pipelines, drawing corporate naming rights commitments and mixed-use development capital.
- FCC anti-siphoning rule enforcement:Regulatory protection of free-to-air broadcast access preserves mass-market audience reach, sustaining national advertising rate premiums for marquee events.
Market Restraints
- Regional sports network bankruptcy exposure:Diamond Sports Group restructuring creates carriage fee uncertainty, compressing local team media revenue visibility and covenant compliance headroom.
- California labor classification litigation:AB5 contractor reclassification challenges threaten gameday staffing cost structures and benefits obligations across minor league and seasonal operations.
- Municipal bond market volatility:Rising interest rate environments extend stadium financing timelines and increase debt service coverage requirements for public-private partnerships.
Strategic Opportunities
- Florida youth academy vertical integration:Unconsolidated amateur club networks present acquisition targets for professional franchises seeking developmental pipeline control and early talent identification.
- Wagering platform data partnerships:State-level sports betting legalization creates real-time engagement inventory, enabling micro-betting integration with live broadcast feeds and second-screen applications.
- Jersey patch sponsorship whitespace:NBA precedent expansion into MLB and NHL uniform inventory unlocks endemic and non-endemic brand categories previously excluded from on-field visibility.
Industry Challenges
- Athlete mental health service scaling:Expanded duty-of-care obligations require specialized clinical staffing and liability framework adaptation across high-pressure performance environments.
- Legacy ticketing system migration:Blockchain-based secondary market transparency initiatives force infrastructure replacement timelines and fan data architecture reconfiguration.
- Cross-platform content rights harmonization:Short-form social media clip licensing conflicts between leagues, broadcasters, and athlete representatives complicate unified monetization strategy execution.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | USA Sports Team and Club Market |
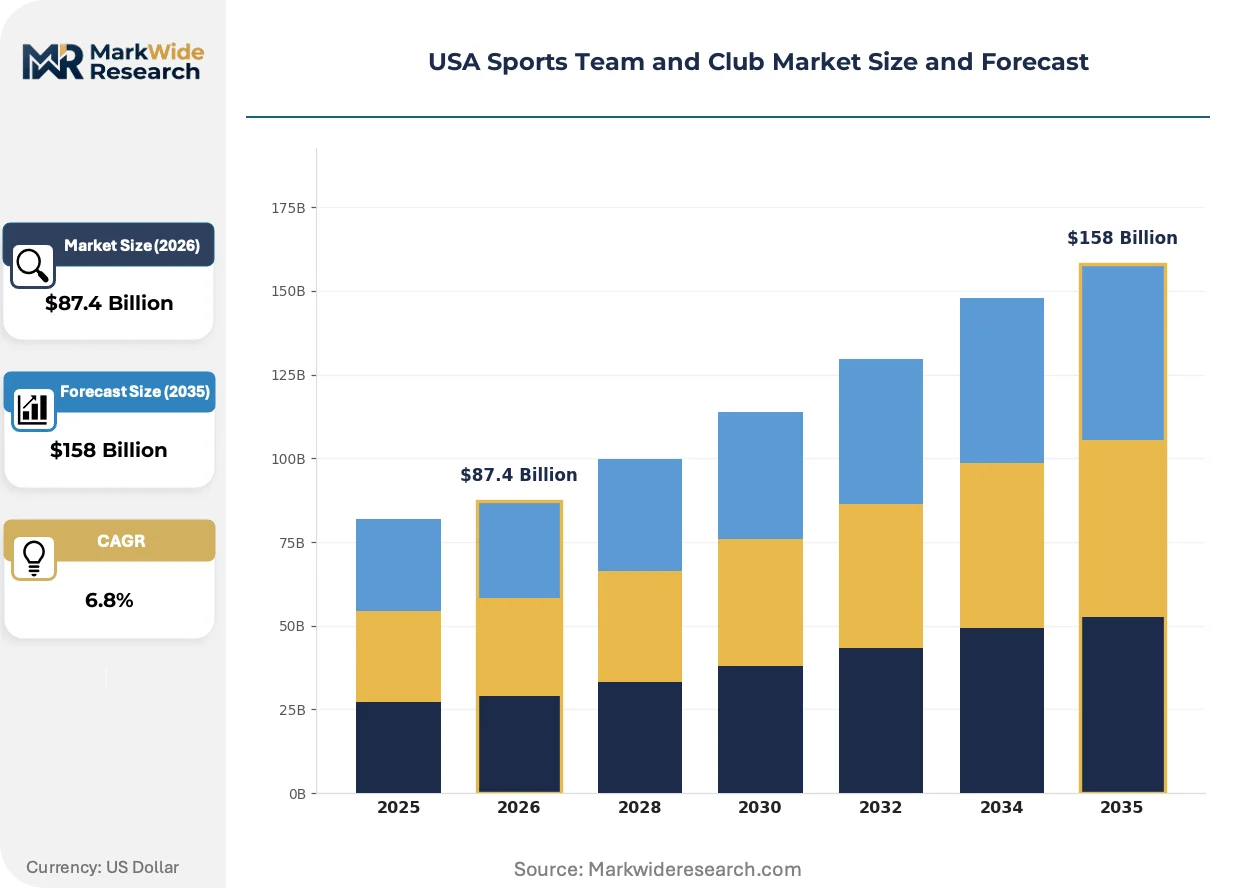
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Organization Type: Professional Teams, Amateur Clubs, College Teams, Youth Organizations Revenue Stream: Ticket Sales, Merchandise, Broadcast Rights, Sponsorships Membership Model: Annual Memberships, Pay-Per-Event, Subscription, Free Memberships Customer Type: Fans, Season Ticket Holders, Corporate Sponsors, Retail Partners |
| Companies Covered | National Hockey League, Los Angeles Lakers, Major League Baseball, Dallas Cowboys, New York Yankees, National Football League, Golden State Warriors, New England Patriots, National Basketball Association, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
USA Sports Team and Club Market Trends and Innovations
Immersive venue technology and predictive analytics are compressing the distance between spectator experience and personalized engagement, redefining how sports organizations architect physical and digital touchpoints.
Computer vision and spatial tracking systems are absorbing spectator attention previously captured by static broadcast angles. NBA franchises deploy court-side camera arrays delivering real-time player biometric overlays to mobile applications. This technology is absorbing traditional replay consumption minutes into interactive second-screen experiences that command premium subscription tiers.
The FCC's spectrum reallocation proceedings and 5G infrastructure mandates are accelerating in-venue connectivity deployment timelines. Stadium operators must upgrade distributed antenna systems to maintain broadcast quality and wagering latency standards. California and Texas facilities face the most compressed compliance windows due to concurrent municipal broadband initiatives.
Corporate hospitality procurement is migrating from annual suite leases to event-specific experiential packages. Professional teams in New York and Los Angeles markets pilot dynamic inventory management platforms that unbundle traditional season ticket structures. This shift is most visible among technology sector buyers seeking flexible entertainment allocation without fixed capital commitment.
USA Sports Team and Club Market Segmentation
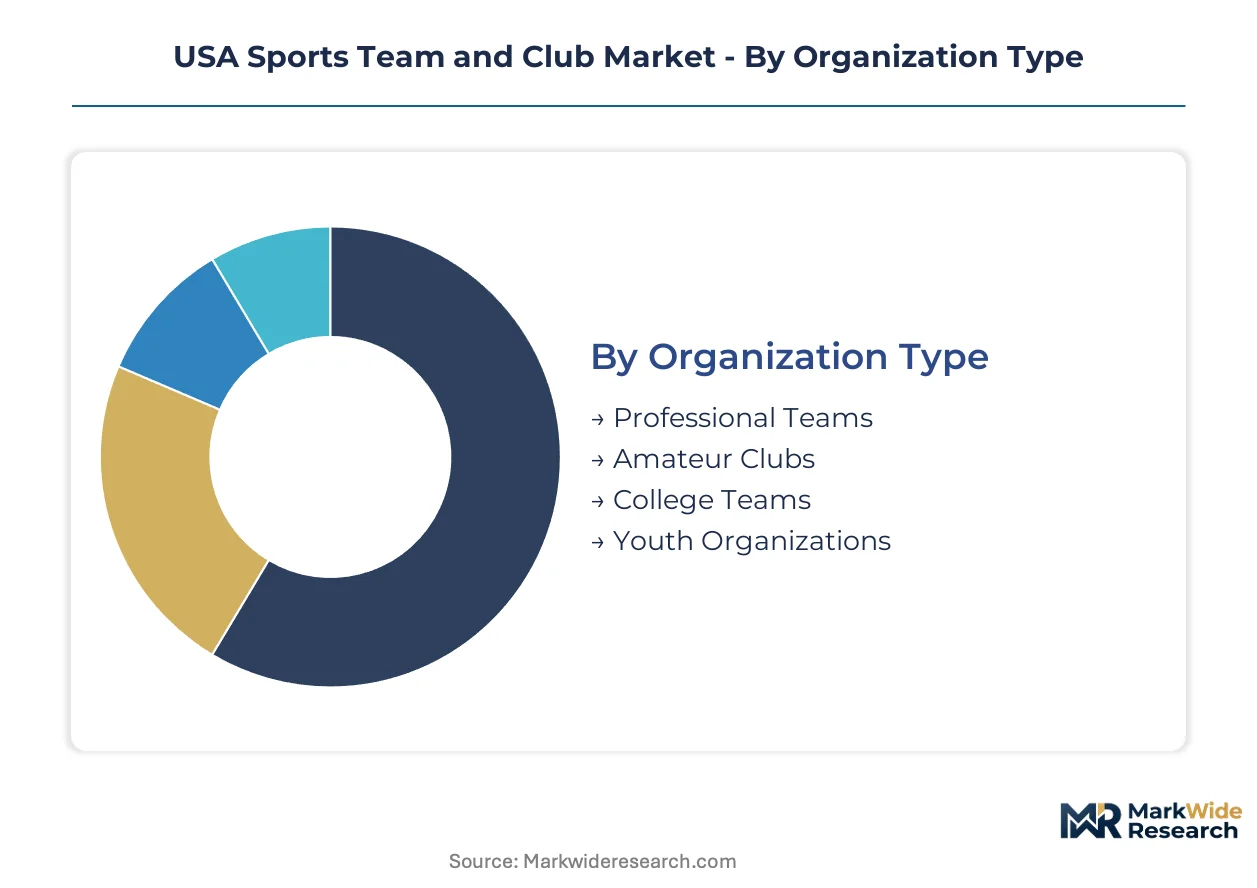
USA sports teams and clubs fragment across organizational tiers, revenue architectures, and engagement models that dictate capital intensity and margin structure. Segmentation reveals where broadcast infrastructure investments concentrate versus where grassroots participation networks remain acquisition targets.
Organization Type:
Professional franchises command national media infrastructure while amateur and youth tiers anchor geographic density and developmental pipelines.
- Professional Teams:These entities operate within league-governed structures featuring salary caps, collective bargaining agreements, and centralized media rights pooling. Revenue concentrates in NFL, NBA, MLB, and NHL franchises located in California and Texas metropolitan markets where stadium financing pipelines and corporate naming rights commitments flow most heavily.
- Amateur Clubs:Semi-professional and recreational leagues function without centralized media distribution, relying instead on local sponsorships and facility rental economics. Florida and Arizona markets host dense amateur club networks that professional franchises increasingly target for vertical integration and early talent identification.
- College Teams:NCAA-governed athletic departments generate revenue through conference media rights, ticket sales, and now direct athlete-brand relationships under NIL frameworks.
- Youth Organizations:Unconsolidated grassroots leagues and academy systems operate below commercial radar, representing fragmented participation infrastructure with minimal standardized governance.
Volume sits with Professional Teams; growth tilts toward Youth Organizations as acquisition pipelines tighten.
Revenue Stream:
Margin capture diverges between nationally distributed media rights and locally contested gate receipts.
- Broadcast Rights:League-level media contracts with ESPN, Fox, and NBCUniversal generate the most predictable revenue streams. NFL Sunday Ticket and NBA League Pass illustrate how exclusive distribution windows command premium carriage fees from cable operators and streaming platforms.
- Sponsorships:Corporate partnerships span jersey patches, venue naming rights, and league-level official designations. NBA jersey patch integration has unlocked endemic and non-endemic brand categories previously excluded from on-field visibility, with MLB and NHL now expanding this inventory.
- Ticket Sales:Gate revenue faces localized competitive dynamics and weather-dependent scheduling risk across outdoor venues.
- Merchandise:Licensed apparel and equipment sales track team performance volatility and regional retail distribution density.
Broadcast Rights anchor current valuation; Sponsorships are climbing the fastest as inventory formats proliferate.
Membership Model:
Engagement economics shift between committed recurring revenue and transactional flexibility.
- Annual Memberships:Traditional season ticket structures lock in predictable base revenue but face corporate procurement migration toward flexible allocation models. New York and Los Angeles franchises pilot dynamic inventory platforms that unbundle fixed commitments into event-specific experiential packages.
- Subscription:Over-the-top streaming services bypass legacy regional sports network intermediaries, capturing subscriber data and enabling dynamic pricing experimentation for live event access.
- Pay-Per-Event:Single-game digital purchases appeal to casual fans without geographic proximity to home markets.
- Free Memberships:Freemium tiers build audience databases for wagering platform data partnerships and targeted sponsorship activation.
Annual Memberships retain volume dominance; Subscription models gain share fastest as cord-cutting accelerates.
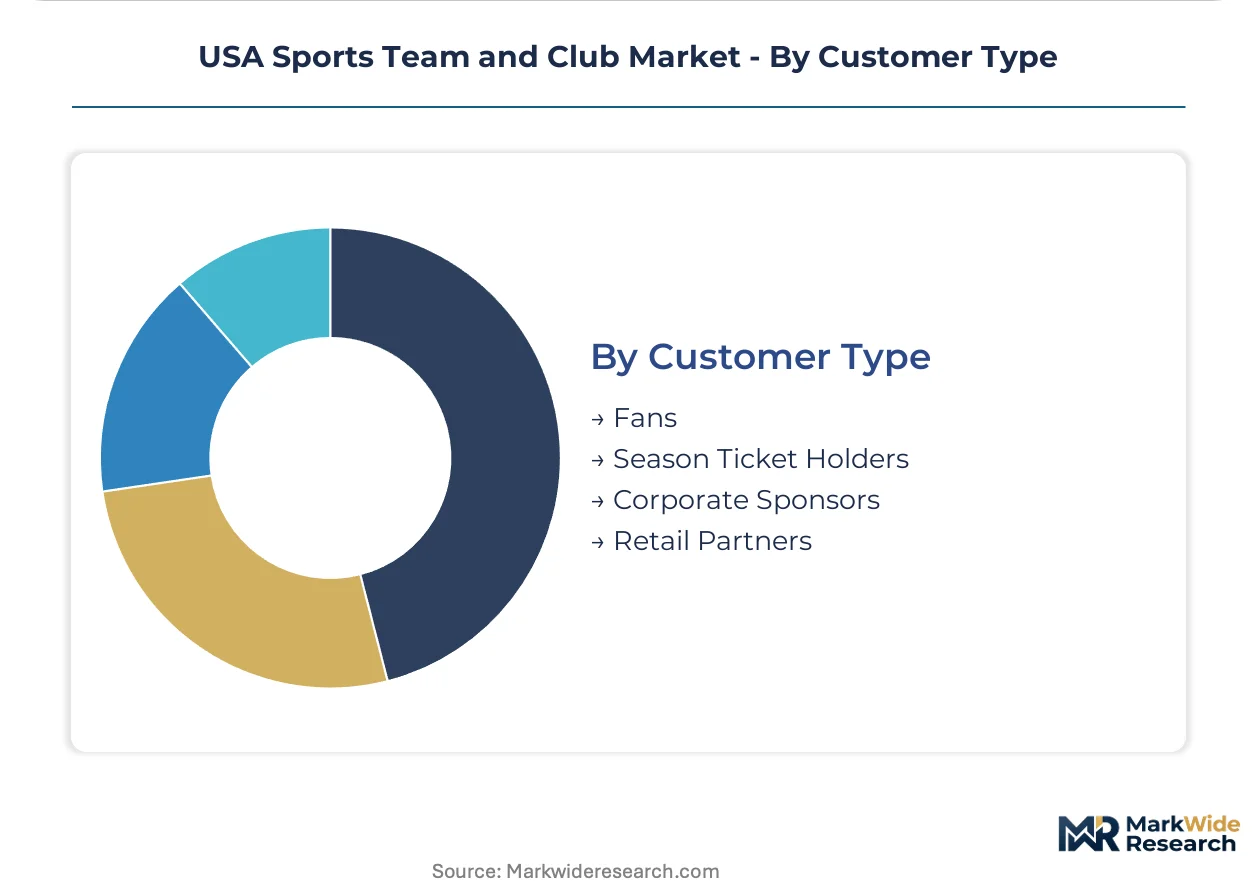
Customer Type:
Procurement authority separates individual consumption from institutional entertainment budgets.
- Corporate Sponsors:Technology sector buyers in San Francisco and Seattle markets drive hospitality procurement away from annual suite leases toward flexible event-specific packages. These entities seek direct fan engagement platforms without fixed capital commitment.
- Season Ticket Holders:Long-tenured individual subscribers represent the most price-inelastic demand segment, though aging demographics threaten renewal rates in legacy baseball markets.
- Fans:Individual ticket buyers and merchandise purchasers respond to team performance and star player availability with high elasticity.
- Retail Partners:Licensed merchandise distribution through Dick's Sporting Goods, Fanatics, and regional sporting goods chains extends brand reach with revenue-sharing complexity.
Season Ticket Holders provide revenue stability; Corporate Sponsors show the steepest expansion trajectory as B2B entertainment budgets realign.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Opportunity Zones and stadium financing districts concentrate capital deployment across Texas and California metropolitan corridors, with municipal bond incentives redirecting sports infrastructure investment toward Sun Belt population growth centers.
California
Los Angeles and San Francisco Bay Area franchises command premium media valuations through legacy broadcast infrastructure and technology sector corporate partnerships. The state's AB5 labor classification litigation reshapes gameday staffing economics across minor league and seasonal operations. SoFi Stadium in Inglewood anchors a mixed-use development pipeline drawing naming rights commitments from financial services and technology brands.
Texas
Dallas-Fort Worth and Houston markets lead national stadium construction financing, with Arlington and Frisco developments capturing corporate hospitality migration from fixed suite leases to flexible experiential packages. The Texas Sports Commission oversees event wagering integrity protocols affecting real-time data partnerships. AT&T Stadium and Globe Life Field exemplify the debt service coverage structures municipal authorities negotiate with professional franchises.
Florida
Miami and Tampa Bay franchises leverage state tax advantages to attract free-agent talent and corporate headquarters relocations. The Florida Department of Business and Professional Regulation governs sports betting operator licensing affecting second-screen wagering integration. Orlando's youth academy density presents vertical integration targets for professional franchises seeking developmental pipeline control.
New York
New York City and Buffalo markets sustain the highest per-capita season ticket pricing through financial services sector entertainment budgets. The New York State Gaming Commission regulates mobile wagering platforms enabling micro-betting inventory for broadcast partners. Madison Square Garden and Yankee Stadium pilot dynamic hospitality inventory platforms unbundling traditional annual commitments.
USA Sports Team and Club Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with league-governed professional franchises capturing national media infrastructure while amateur clubs remain fragmented across unconsolidated local networks. The market structure concentrates revenue among four major league central offices controlling centralized broadcast rights pooling. Two strategic archetypes dominate: vertically integrated franchise operators controlling venue real estate and developmental pipelines, and league-level media rights aggregators managing national distribution windows. Competitive moves center on municipal stadium financing renegotiations and regional sports network bankruptcy restructuring.
Within the league-governed tier, the National Football League, National Basketball Association, and Major League Baseball exemplify media rights aggregation models, while the Dallas Cowboys and New York Yankees represent franchise-level venue and brand commercialization strategies.
| Leading Market Players |
|---|
| National Hockey League |
| Los Angeles Lakers |
| Major League Baseball |
| Dallas Cowboys |
| New York Yankees |
| National Football League |
| Golden State Warriors |
| New England Patriots |
| National Basketball Association |
| Others |
Pricing and Supply Chain Analysis
Specialized broadcast technicians and venue operations staff concentrated in California and Texas metropolitan markets command wage premiums that compress operating margins for premium-tier franchises while amplifying price spreads between legacy ballpark experiences and technology-enabled premium offerings. Labor-cost differentials across these coastal and Sun Belt markets directly shape how teams structure three-tier pricing architectures across premium hospitality, standard seating, and economy inventory.
Pricing Analysis
Short lead-time procurement of experiential packages commands premium positioning above annual suite leases, with Dallas-Fort Worth and Houston franchises extracting 15-40% markups for event-specific corporate hospitality against fixed-commitment baselines. Three-tier pricing structure across premium, standard, and economy levels segments buyer archetypes by procurement flexibility rather than seat quality alone. Pricing pressure stems from corporate procurement migration toward dynamic allocation models without fixed capital commitment. Technology sector buyers in San Francisco and Seattle markets exhibit lowest price sensitivity; individual season ticket holders in legacy baseball markets face renewal elasticity pressures.
Supply Chain Analysis
Workforce availability for specialized stadium construction and broadcast infrastructure installation concentrates in Texas, California, and Florida metropolitan corridors where municipal bond financing pipelines and right-to-work frameworks attract development capital. Raw material dependencies span steel superstructure components, LED display systems, and distributed antenna network equipment sourced from domestic fabrication facilities and East Asian electronics manufacturers. Supply chain risk centers on single-source vulnerability for proprietary scoreboard and replay system technologies. Distribution runs through league-centralized media rights aggregators for national broadcast inventory, with regional sports network intermediaries facing restructuring-driven fragmentation for local team coverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The USA Sports Team and Club Market is executing a technology-transition phase as over-the-top streaming infrastructure displaces legacy regional sports network distribution economics, compressing intermediary margins while reallocating value capture toward direct-to-consumer platforms and data-enabled wagering integrations.
For Market Incumbents: To counter Diamond Sports Group bankruptcy-driven carriage fee uncertainty, NFL and NBA franchises should accelerate in-house streaming platform development and negotiate direct broadband distribution partnerships with municipal fiber operators. Backward integration into venue real estate through mixed-use development structures in Texas and California markets secures naming rights commitment visibility and debt service coverage headroom. For New Entrants and Emerging Players: AI-powered personalization engines for second-screen wagering integration represent the most penetrable white-space target, with Florida youth academy networks offering acquisition pathways for developmental pipeline control. New entrants should prioritize micro-betting data partnerships with state-licensed operators as the primary go-to-market angle, leveraging real-time engagement inventory that legacy broadcast infrastructure cannot replicate. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated franchise operators controlling venue real estate and regional sports network replacement streaming platforms given FCC spectrum reallocation and 5G infrastructure deployment timelines. Long-term viability favors entities with diversified revenue across media rights, corporate hospitality, and wagering data licensing. The signal to watch is municipal stadium financing covenant renegotiation patterns in rising interest rate environments as inflection indicator for capital deployment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Direct-to-Consumer Streaming Launch | Bypasses Diamond Sports Group restructuring uncertainty and captures subscriber data for dynamic pricing. |
| Jersey Patch Sponsorship Expansion | Unlocks non-endemic brand categories following NBA precedent into MLB and NHL uniform inventory. |
| Youth Academy Vertical Integration | Secures developmental pipeline control and early talent identification in Florida's fragmented club networks. |
| Wagering Platform Data Partnership | Enables micro-betting integration with live broadcast feeds under state-level legalization frameworks. |
| Mixed-Use Venue Development | Draws corporate naming rights commitments and diversifies revenue beyond game-day operations in Texas markets. |
Research Methodology
Multi-period observation of NCAA NIL policy enforcement patterns, regional sports network bankruptcy restructuring timelines, and municipal bond issuance volumes anchored the trend analysis, supplemented by interviews with league broadcast executives, stadium operations directors, corporate hospitality procurement managers, and state gaming commission regulators. Secondary validation drew from FCC spectrum allocation proceedings, NCAA financial disclosure databases, municipal authority debt offering documents, and SEC filings from publicly traded venue operators. Bottom-up segmentation modeling triangulated against top-down league revenue aggregation.
Input-output matrices mapped organization type, revenue stream, and membership model dimensions across the projection horizon, with organization type disaggregated into professional franchise, amateur club, college team, and youth organization tiers. CAGRs were derived from recursive substitution of segment-level growth assumptions into aggregate market value trajectories. Forecast inputs incorporated NIL policy adoption velocity, cord-cutting penetration rates, and state-level sports betting legalization progression.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated regional sports network liquidation or federal NIL preemption scenarios. Forecasts reflect documented assumptions regarding stadium financing availability and corporate sponsorship commitment durability. Material deviation in FCC anti-siphoning rule enforcement or municipal bond market access conditions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sports & Fitness Technology
Virtual Reality Fitness Market
Sports & Fitness Technology
Europe Sports Promoter Market
Sports & Fitness Technology
Smart Sports Market
Sports & Fitness Technology
Reflective Sportswear Market
Sports & Fitness Technology
North America Sports Promoter Market
Sports & Fitness Technology
Europe Sports Management Software Market
Sports & Fitness Technology
UK Sports Team and Clubs Market
Sports & Fitness Technology
Football Merchandise Market
Sports & Fitness Technology
UK Sports Promoters Market
Sports & Fitness Technology
France Sports Teams and Clubs Market
Sports & Fitness Technology
Smart Fitness Device Market
Sports & Fitness Technology
Sports Sponsorship Market
Sports & Fitness Technology
3D Motion Capture Market
Sports & Fitness Technology
Sportswear Rental and Rotation Market
Sports & Fitness Technology
Stadium and Arena Management Solution Market
Sports & Fitness Technology
Asia Pacific Sports Team and Clubs Market